CTC Media — Investor Day (June 2012)
30 slides from CTC Media's investor day presentation, Jun 14, 2012
Slide 1: MTG Capital Markets Day
MTG Capital Markets Day June 14, 2012 Boris Podolsky Acting Chief Executive Officer Chief Financial Officer
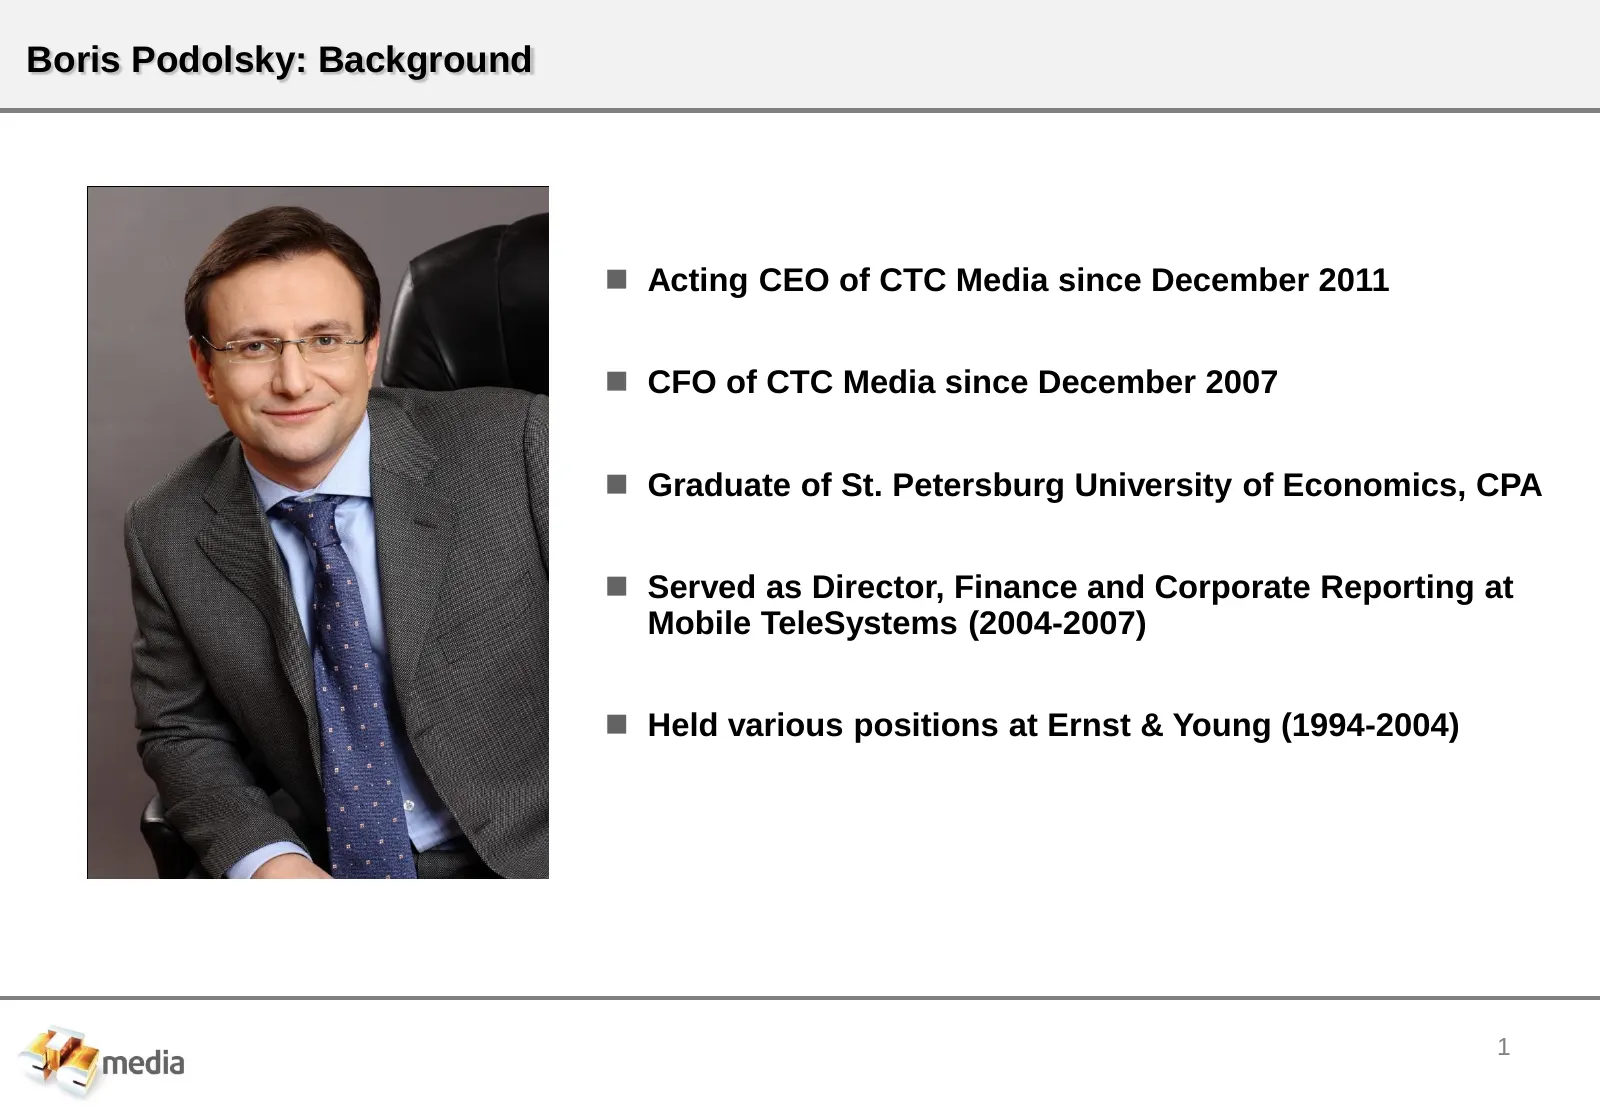
Slide 2: Boris Podolsky: Background
Boris Podolsky: Background Acting CEO of CTC Media since December 2011 CFO of CTC Media since December 2007 Graduate of St. Petersburg University of Economics, CPA Served as Director, Finance and Corporate Reporting at Mobile TeleSystems (2004-2007) Held various positions at Ernst & Young
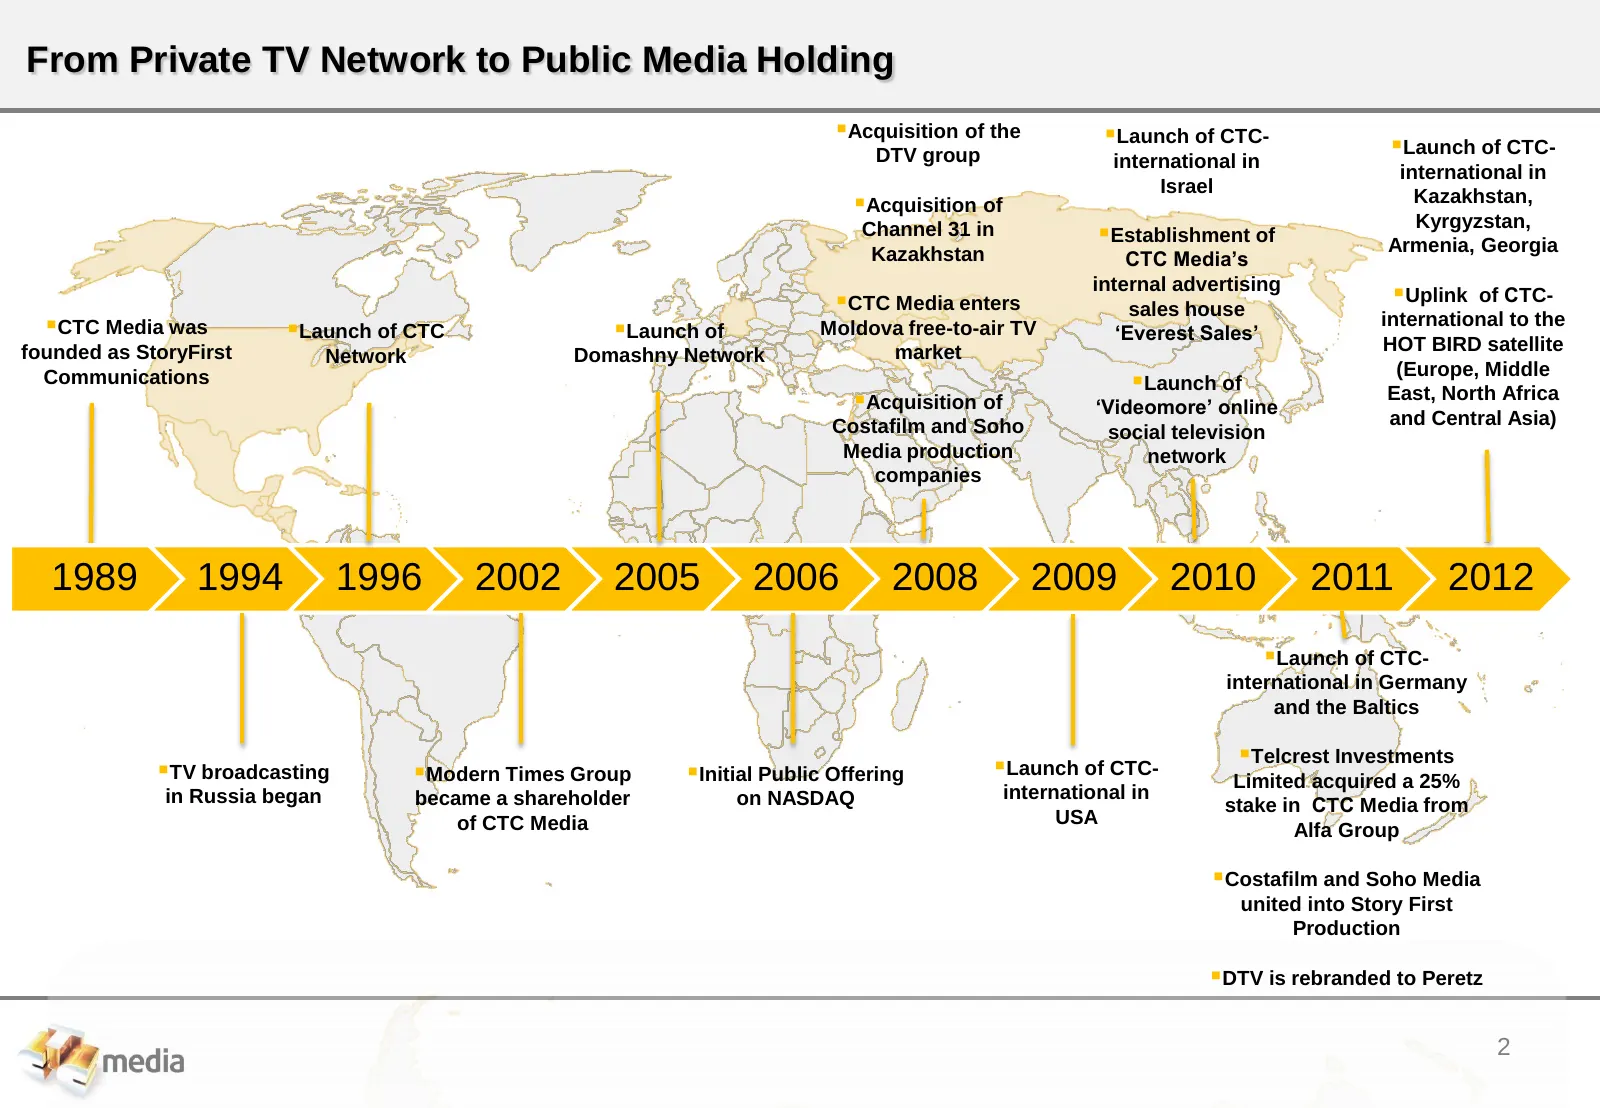
Slide 3: From Private TV Network to Public Media Holding
From Private TV Network to Public Media Holding Acquisition of the Launch of CTC- DTV group Launch of CTC- international in international in Israel Acquisition of Kazakhstan, Kyrgyzstan, Channel 31 in Establishment of Armenia, Georgia Kazakhstan CTC Media’s internal advertising CTC Media enter
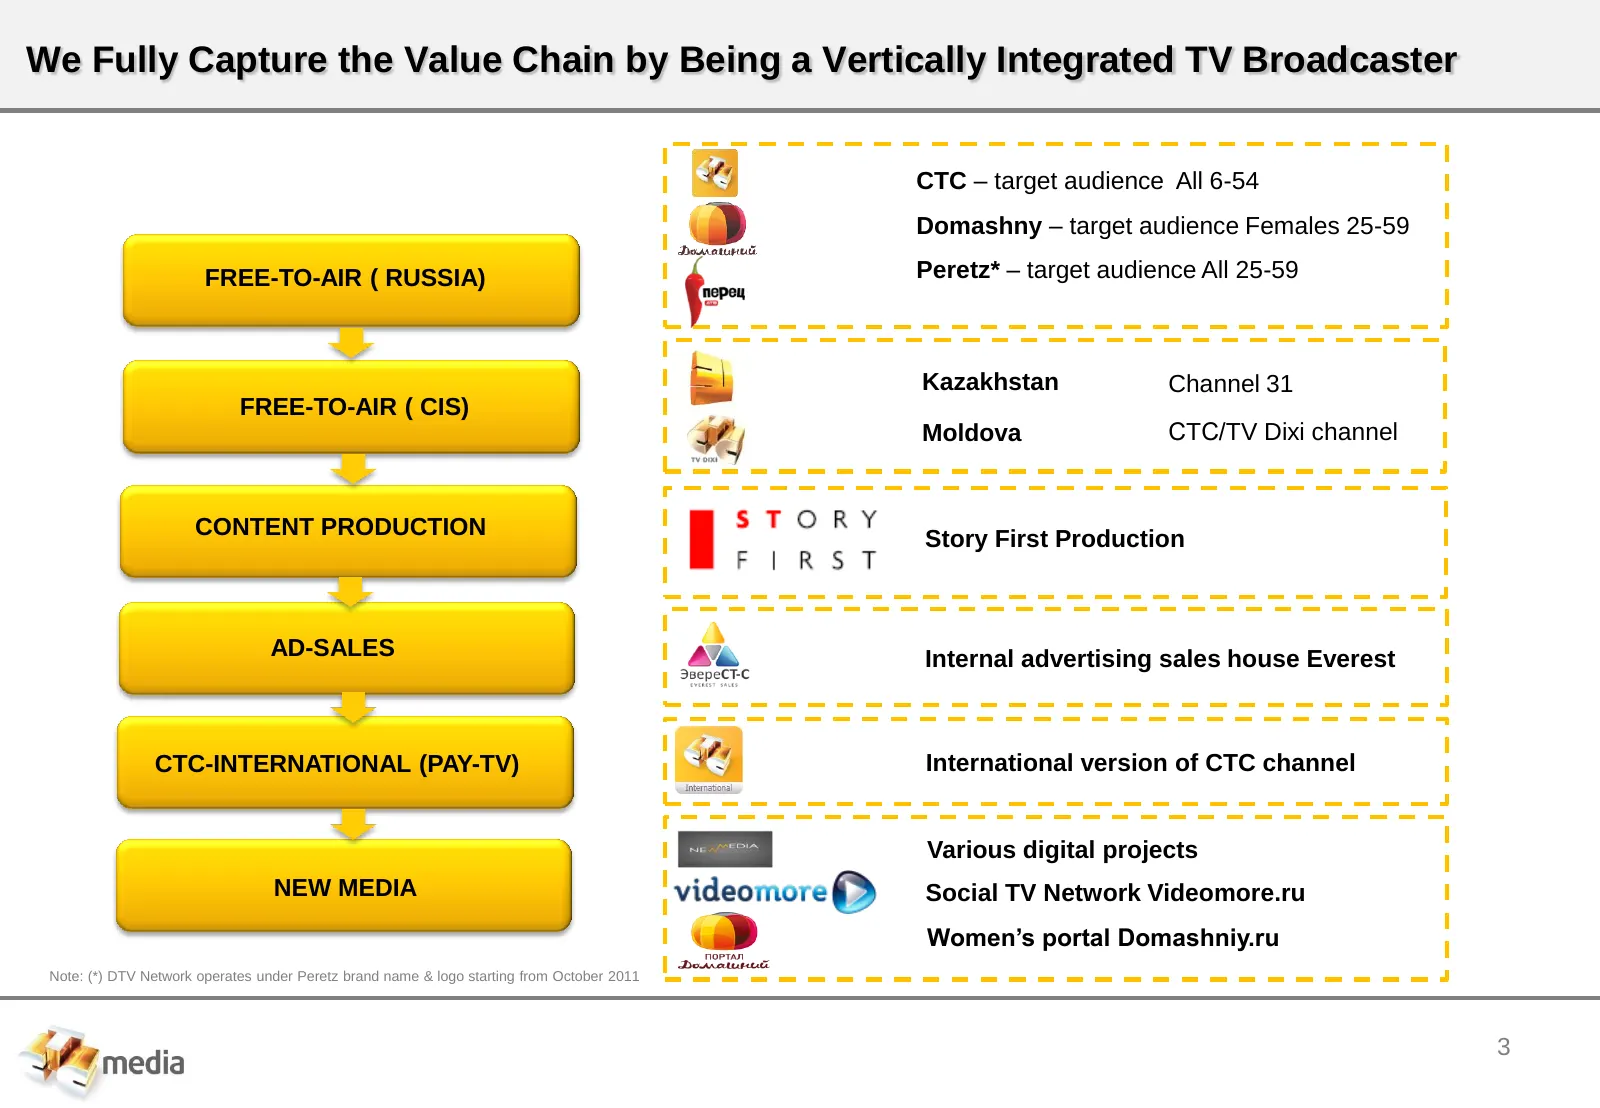
Slide 4: We Fully Capture the Value Chain by Being a Vertically Integrated TV Broadcaster
We Fully Capture the Value Chain by Being a Vertically Integrated TV Broadcaster CTC – target audience All 6-54 Domashny – target audience Females 25-59 FREE-TO-AIR ( RUSSIA) Peretz* – target audience All 25-59 Kazakhstan Channel 31 FREE-TO-AIR ( CIS) Moldova СTС/TV Dixi channel CONTENT PRODUCTION S
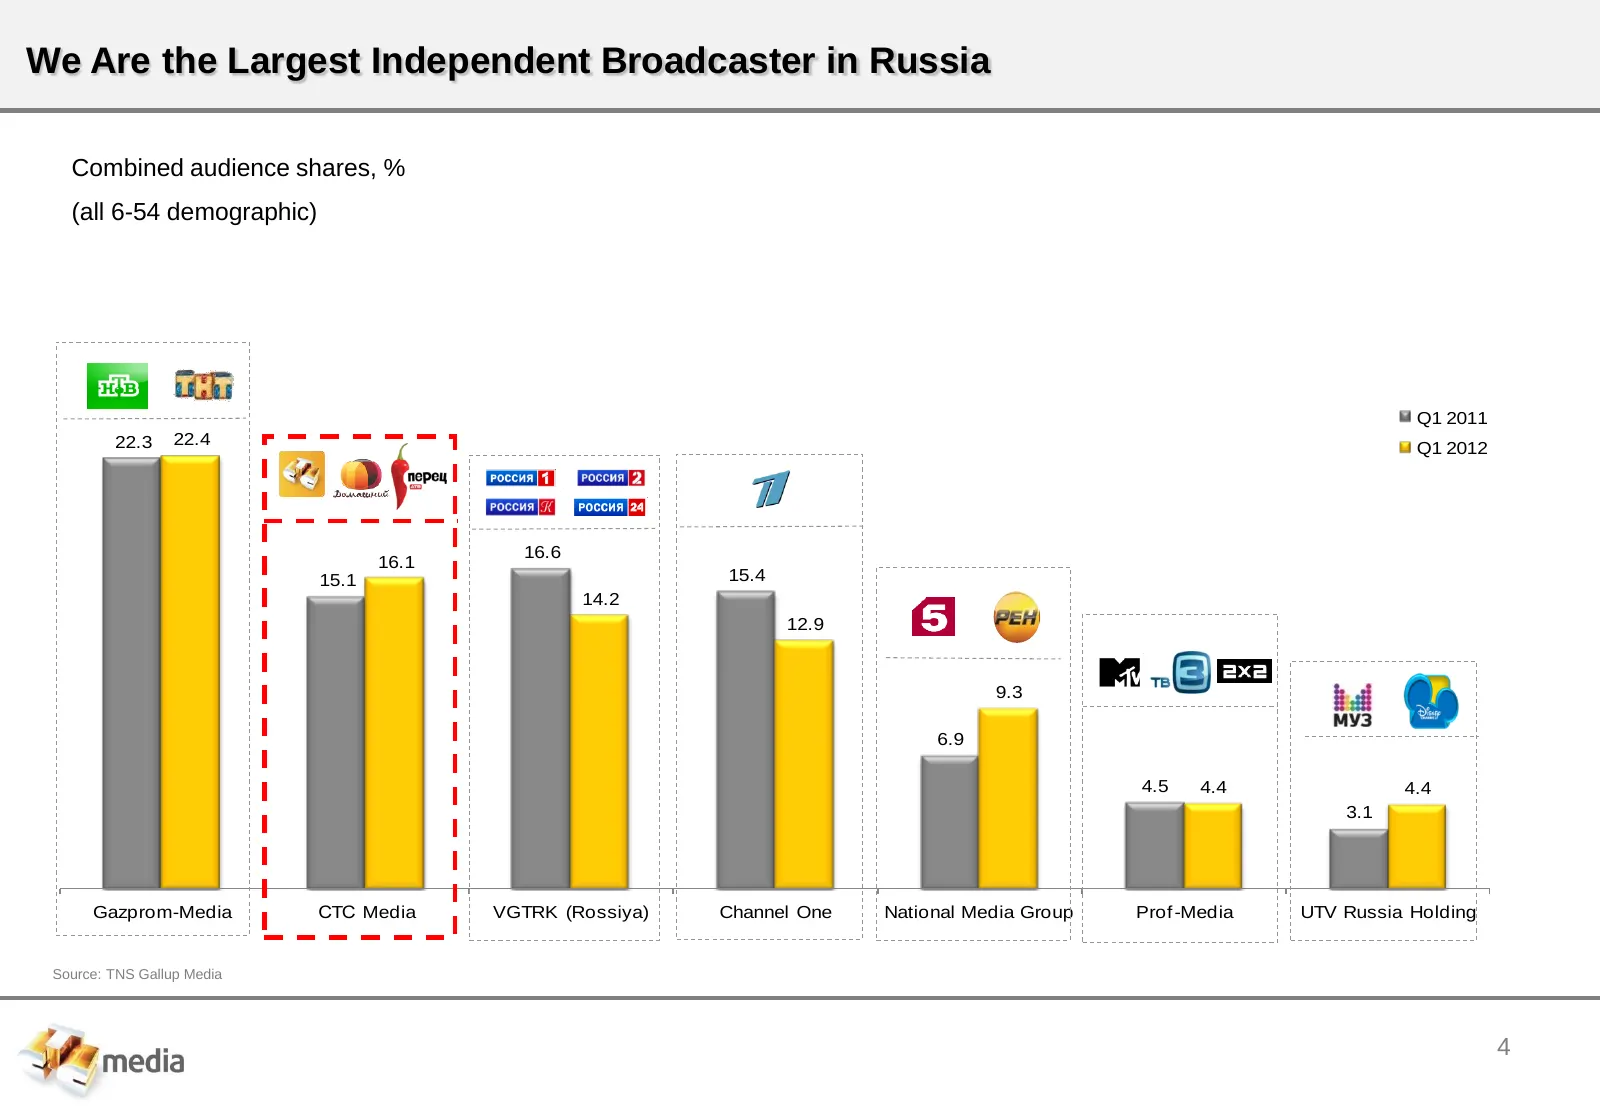
Slide 5: We Are the Largest Independent Broadcaster in Russia
We Are the Largest Independent Broadcaster in Russia Combined audience shares, % (all 6-54 demographic) Q1 2011 22.3 22.4 Q1 2012 16.6 16.1 15.1 15.4 14.2 12.9 9.3 6.9 4.5 4.4 4.4 3.1 Gazprom-Media СTС Media VGTRK (Rossiya) Channel One National Media Group Prof -Media UTV Russia Holding Source: TNS
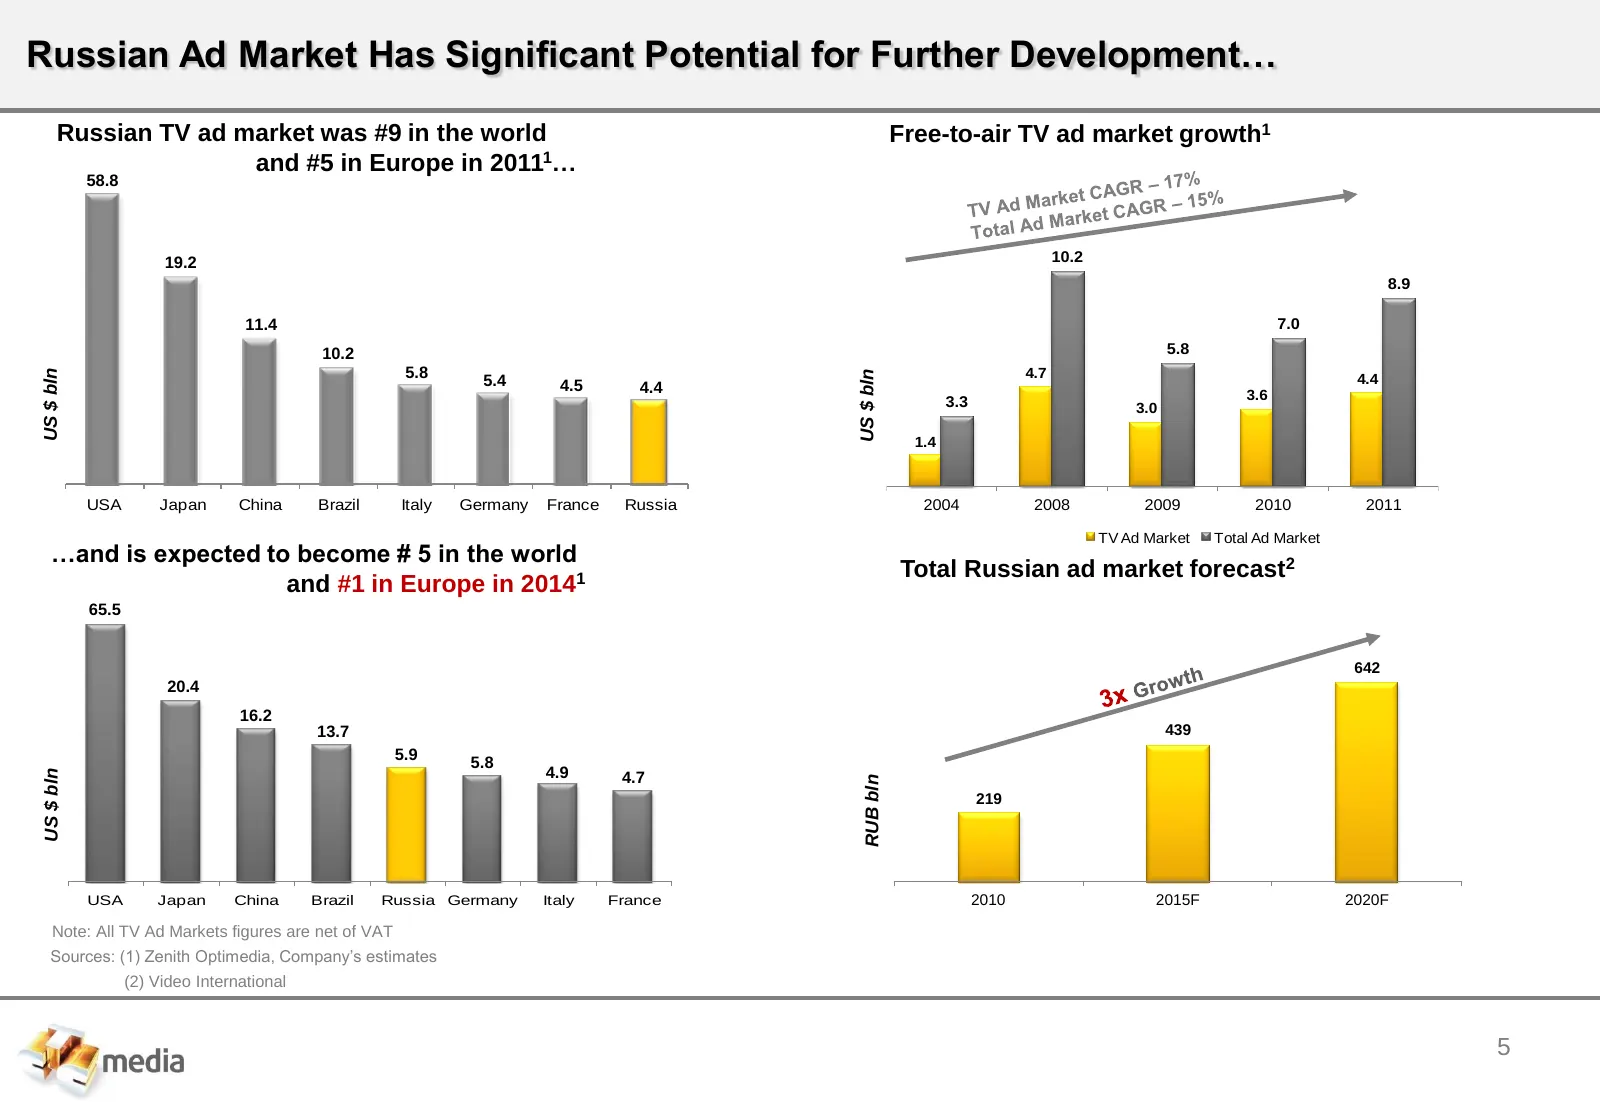
Slide 6: Russian Ad Market Has Significant Potential for Further Development
Russian Ad Market Has Significant Potential for Further Development… Russian TV ad market was #9 in the world Free-to-air TV ad market growth1 and #5 in Europe in 20111… 58.8 19.2 10.2 8.9 11.4 7.0 10.2 5.8 5.8 4.7 US $ bln US $ bln 5.4 4.5 4.4 4.4 3.6 3.3 3.0 1.4 USA Japan China Brazil Italy German
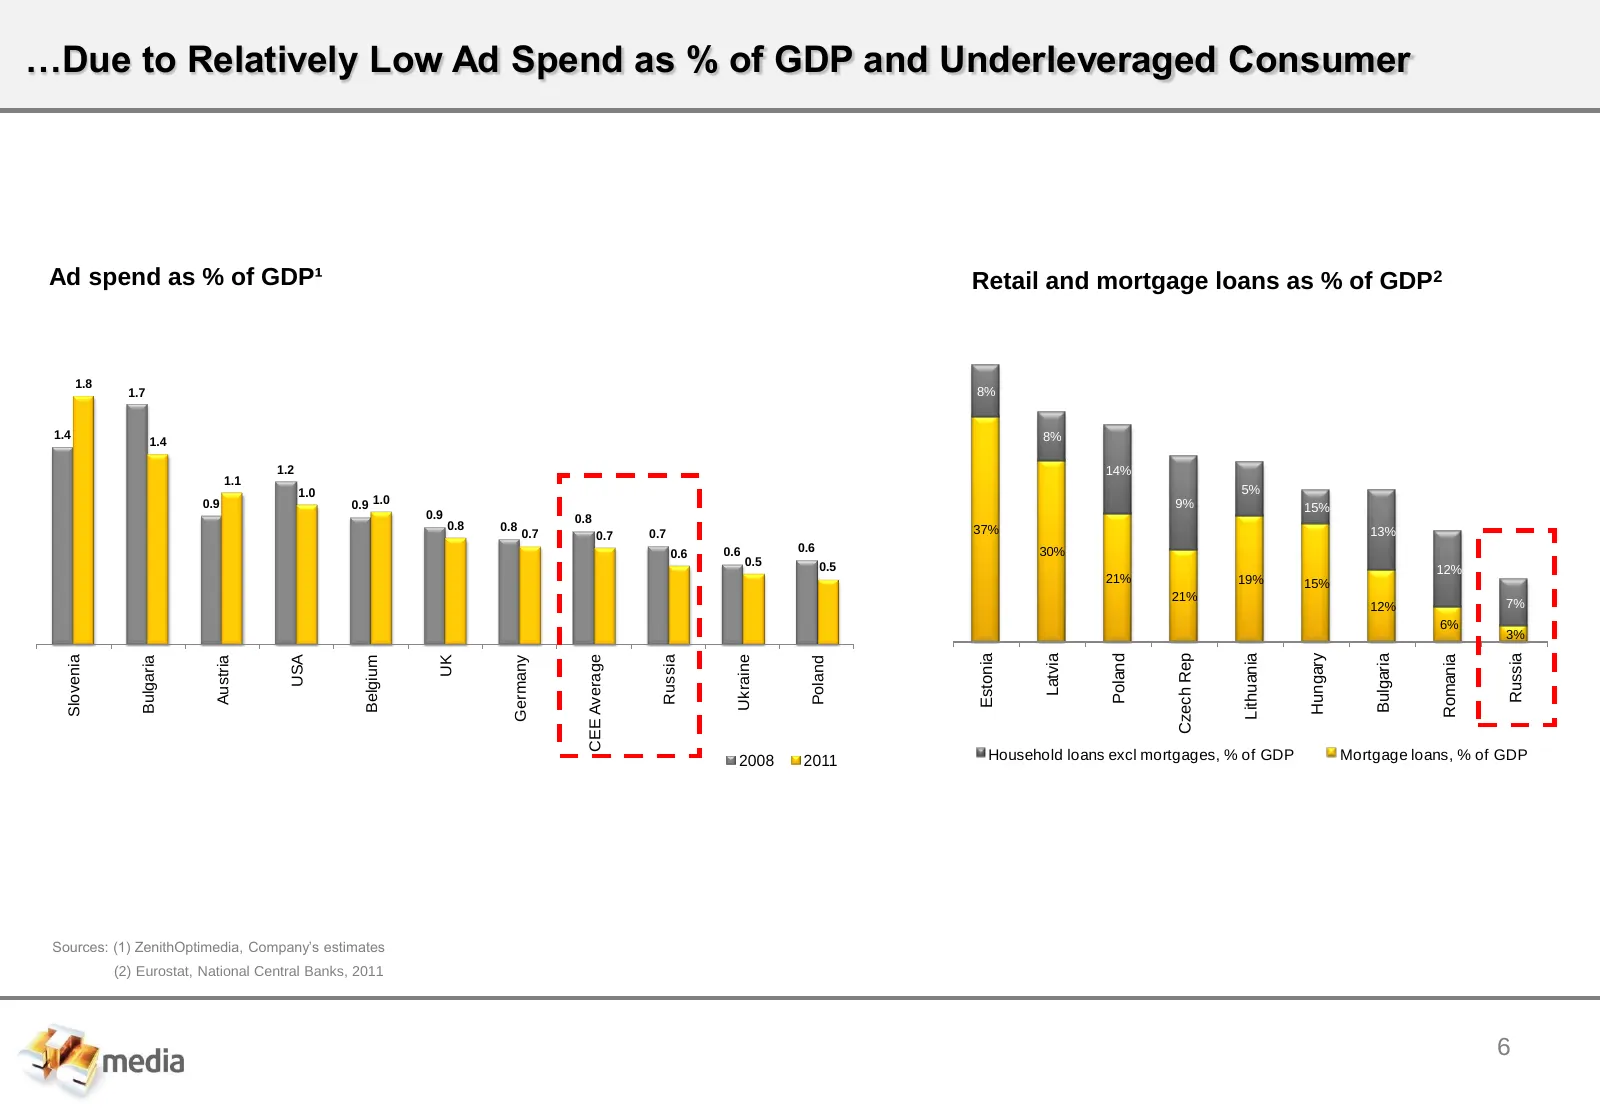
Slide 7: Low Ad Spend as % of GDP and Underleveraged Consumer
…Due to Relatively Low Ad Spend as % of GDP and Underleveraged Consumer Ad spend as % of GDP¹ Retail and mortgage loans as % of GDP2 1.8 1.7 8% 1.4 8% 1.4 1.2 14% 1.1 1.0 5% 0.9 0.9 1.0 9% 15% 0.9 0.8 0.8 0.8 37% 13% 0.7 0.7 0.7 0.6 0.6 0.6 30% 0.5 0.5 12% 21% 19% 15% 21% 12% 7% 14% 9% 6% 3% Estonia
Slide 8: TV Is the Most Attractive Advertising Medium in Russia
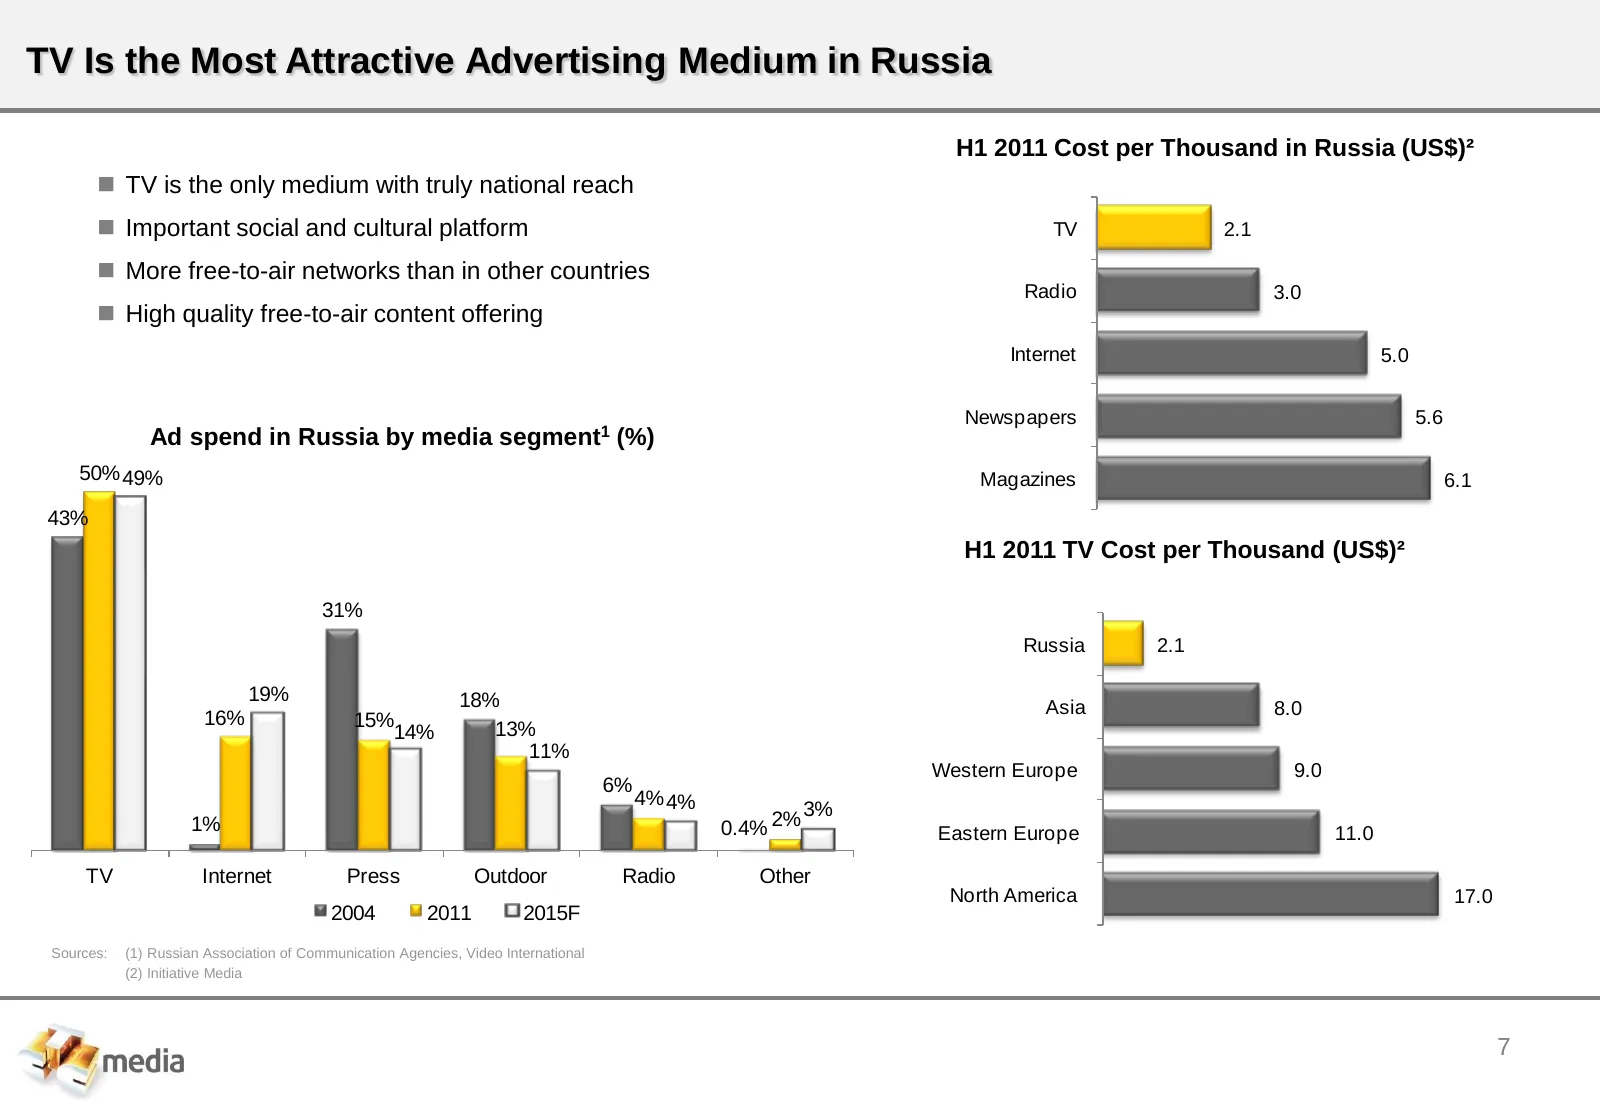
TV Is the Most Attractive Advertising Medium in Russia H1 2011 Cost per Thousand in Russia (US$)² TV is the only medium with truly national reach Important social and cultural platform TV 2.1 More free-to-air networks than in other countries Radio 3.0 High quality free-to-air content offerin
Slide 9: Internet Consumption Is Growing
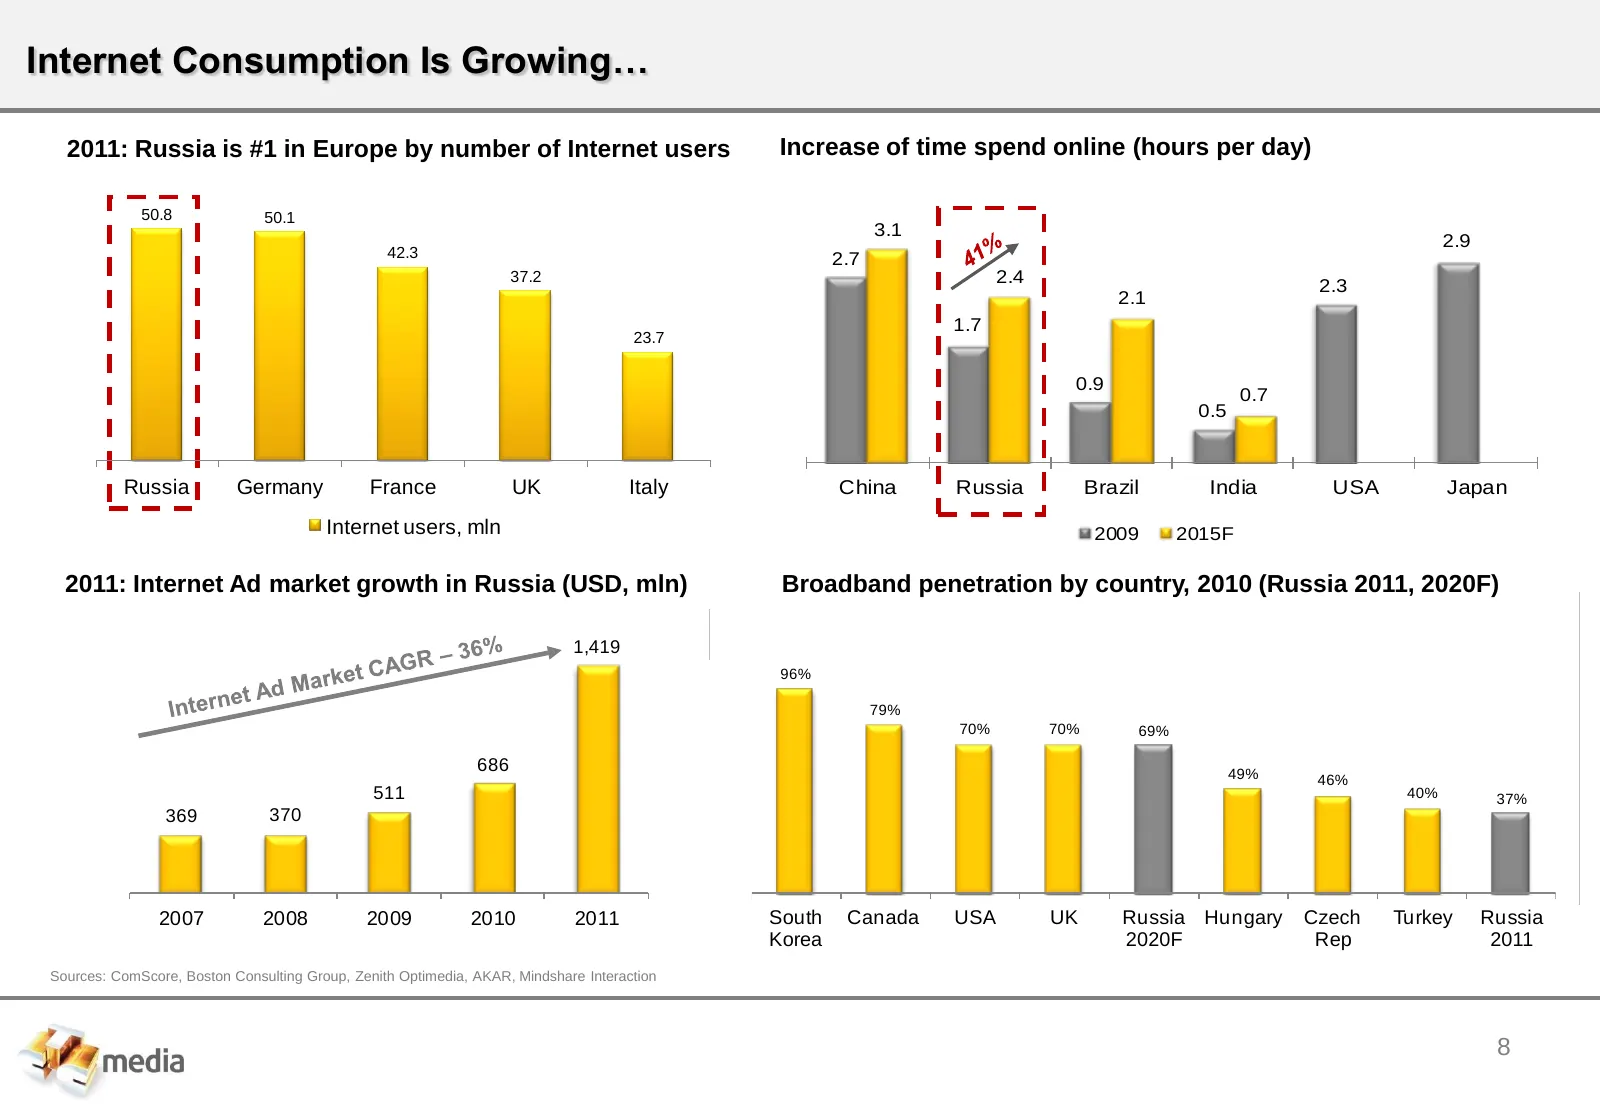
Internet Consumption Is Growing… 2011: Russia is #1 in Europe by number of Internet users Increase of time spend online (hours per day) 50.8 50.1 3.1 2.9 42.3 2.7 37.2 2.4 2.3 2.1 1.7 23.7 0.9 0.7 0.5 Russia Germany France UK Italy China Russia Brazil India USA Japan Internet users, mln 2009 2015F 2
Slide 10: …but Not at the Expense of TV Usage
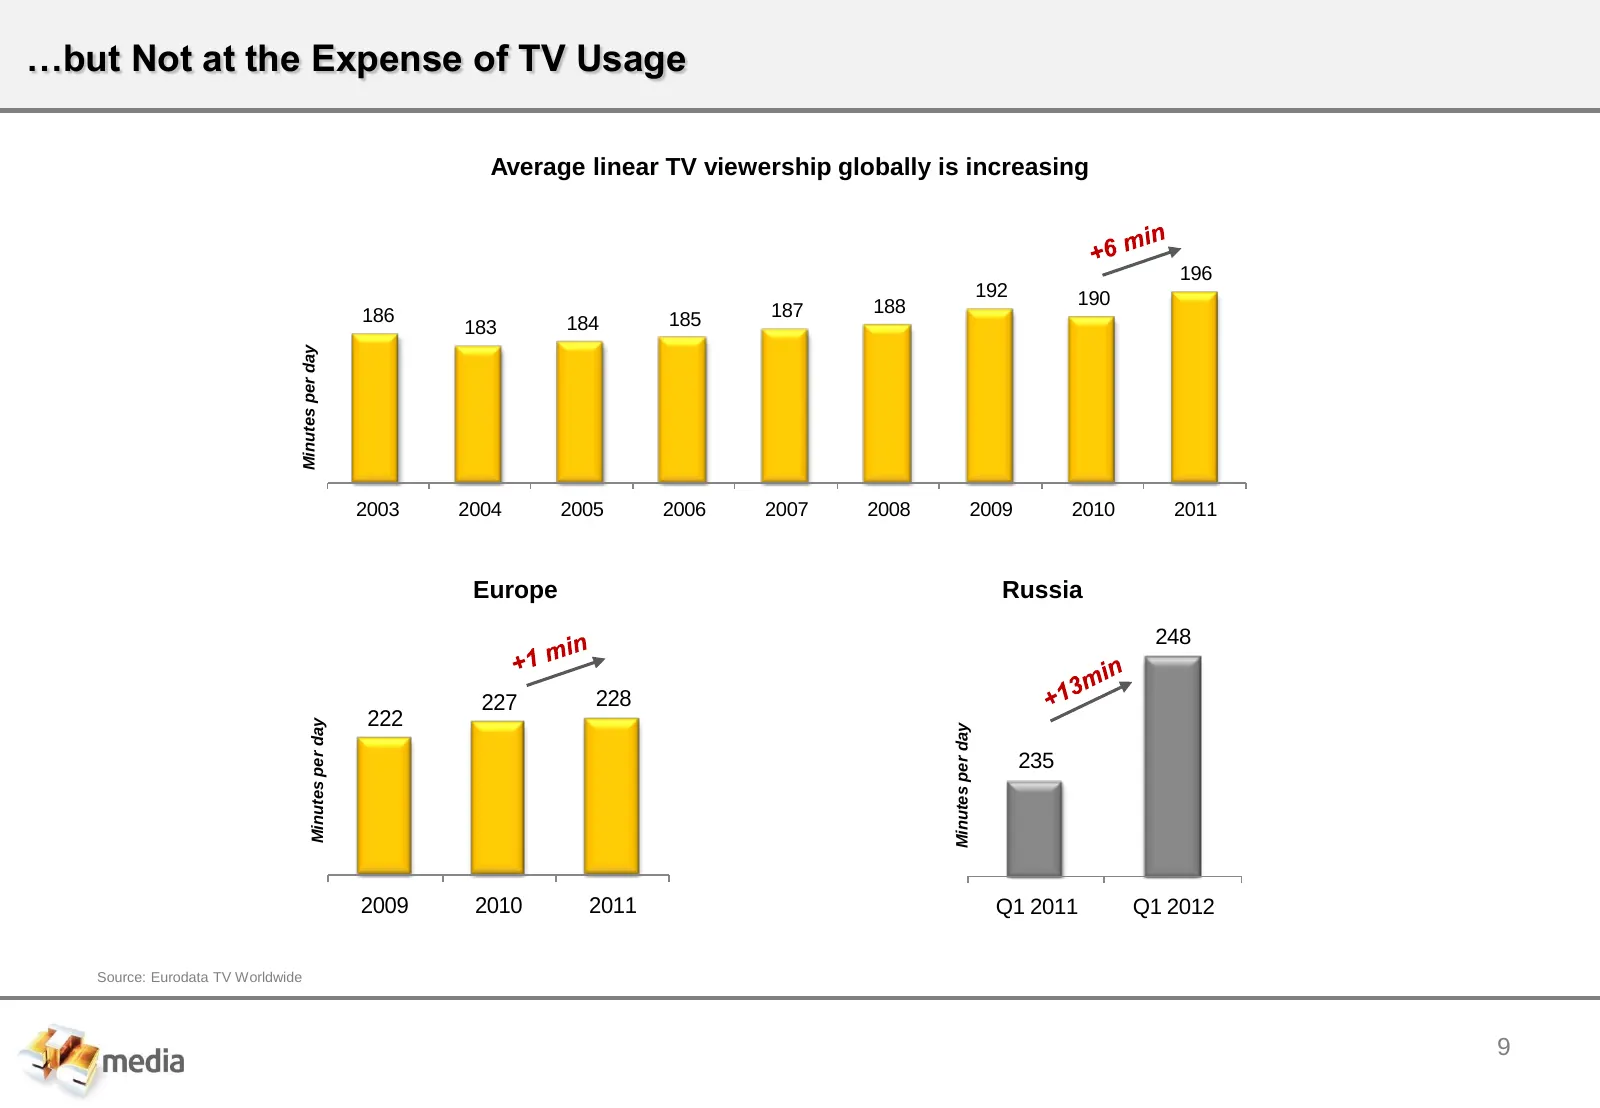
…but Not at the Expense of TV Usage Average linear TV viewership globally is increasing 196 192 190 186 187 188 183 184 185 Minutes per day 2003 2004 2005 2006 2007 2008 2009 2010 2011 Europe Russia 248 227 228 222 Minutes per day Minutes per day 235 2009 2010 2011 Q1 2011 Q1 2012 Source: Eurodata T
Slide 11: We Continue to Deliver Strong Top and Bottom-line Growth
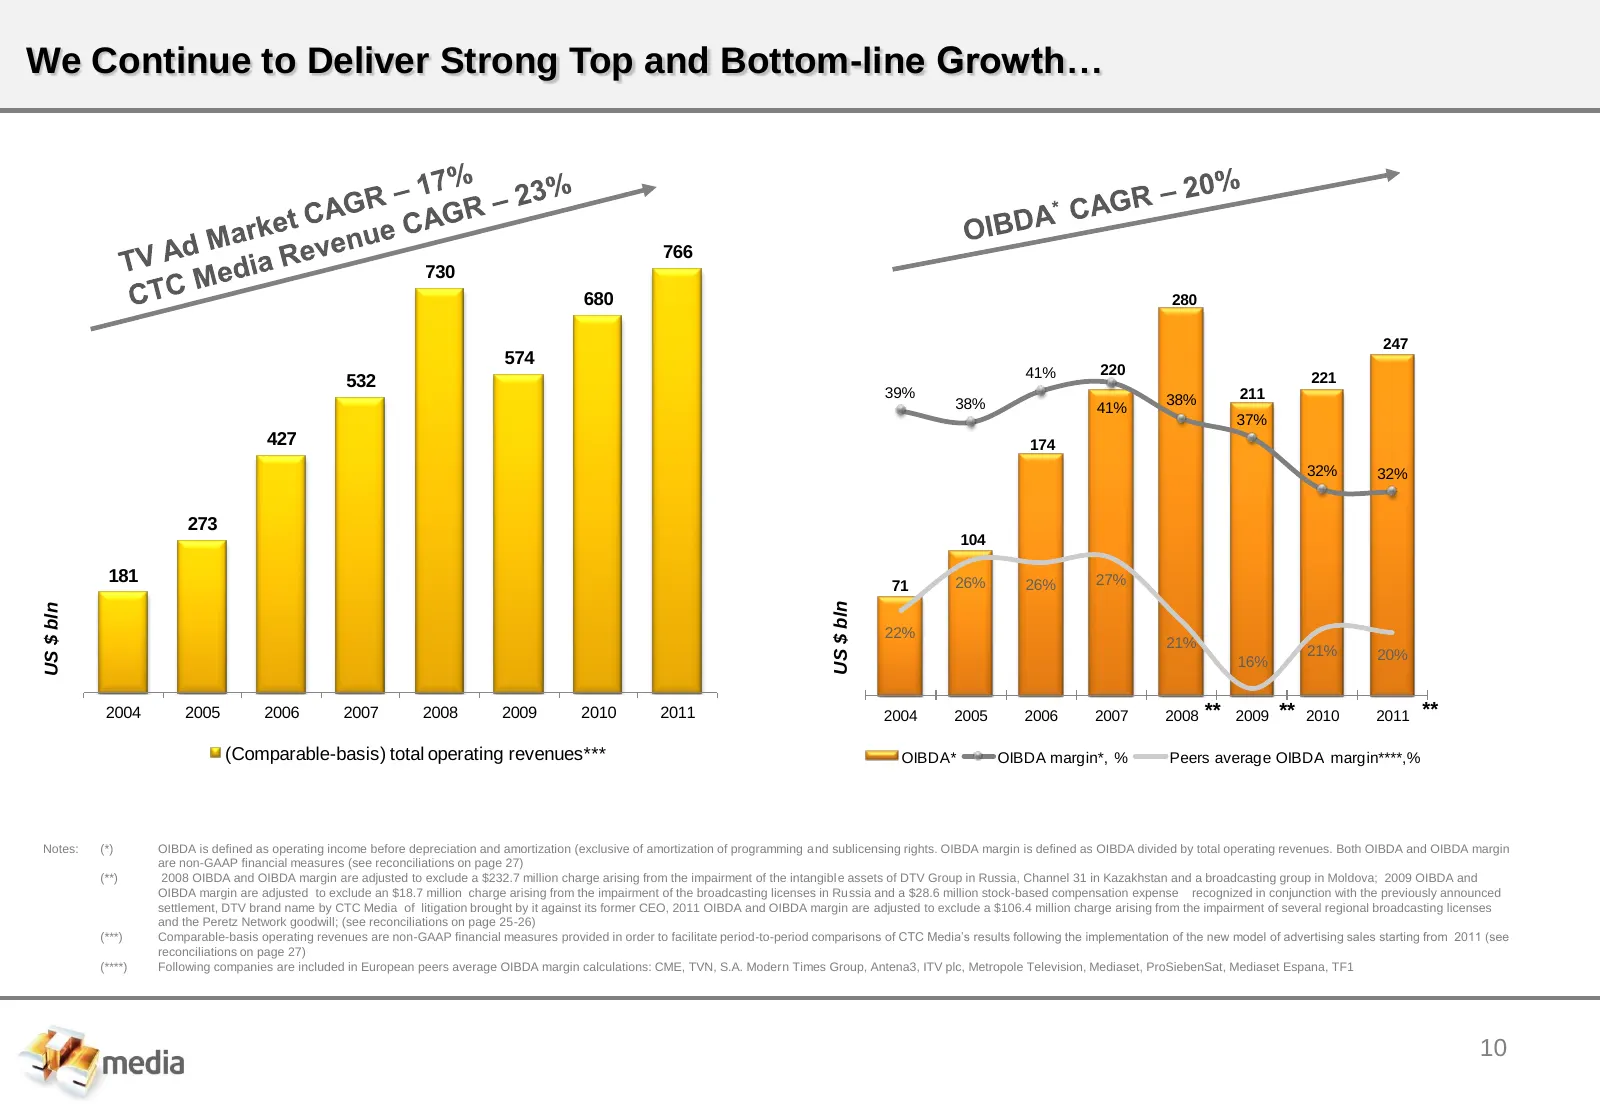
We Continue to Deliver Strong Top and Bottom-line Growth… 766 730 680 280 247 45% 250 574 41% 220 221 532 39% 38% 211 38% 41% 200 37% 427 174 35% 32% 32% 150 273 104 100 181 71 26% 26% 27% 25% US $ bln US $ bln 50 22% 21% 21% 16% 20% 0 15% 2004 2005 2006 2007 2008 2009 2010 2011 2004 2005 2006 2007
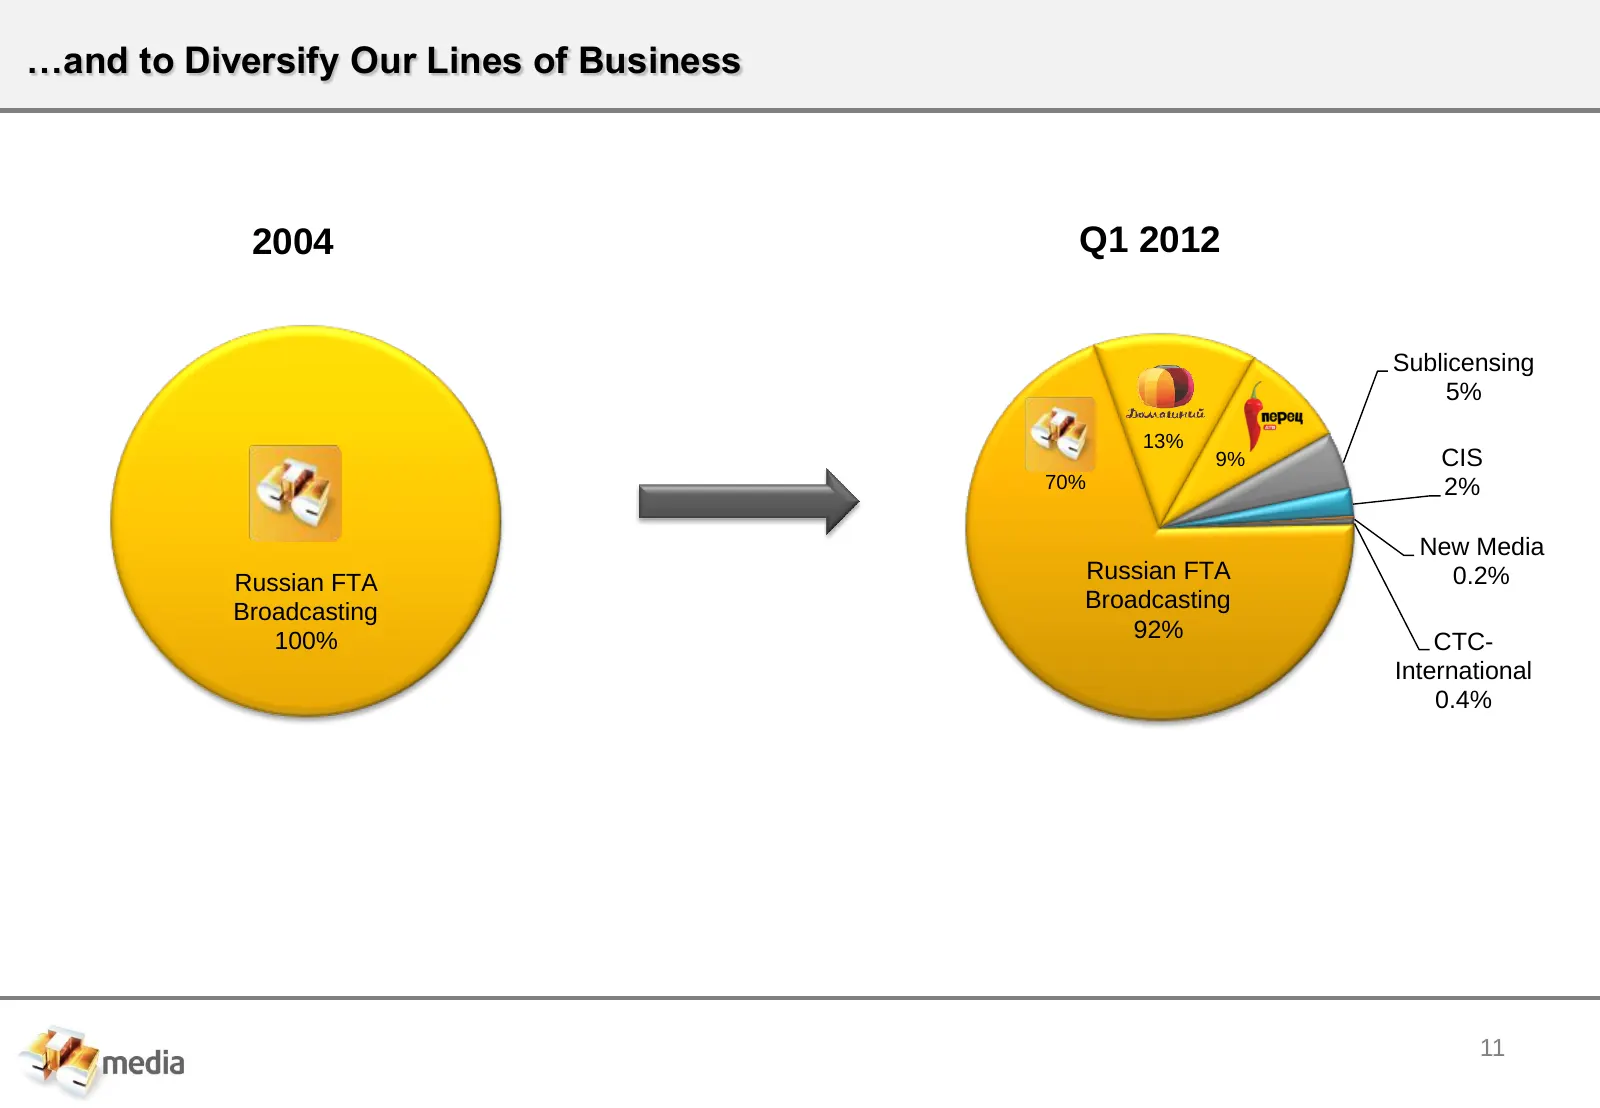
Slide 12: …and to Diversify Our Lines of Business
…and to Diversify Our Lines of Business 2004 Q1 2012 Sublicensing 5% 13% 9% CIS 70% 2% New Media Russian FTA Russian FTA 0.2% Broadcasting Broadcasting 100% 92% CTC- International 0.4% 11
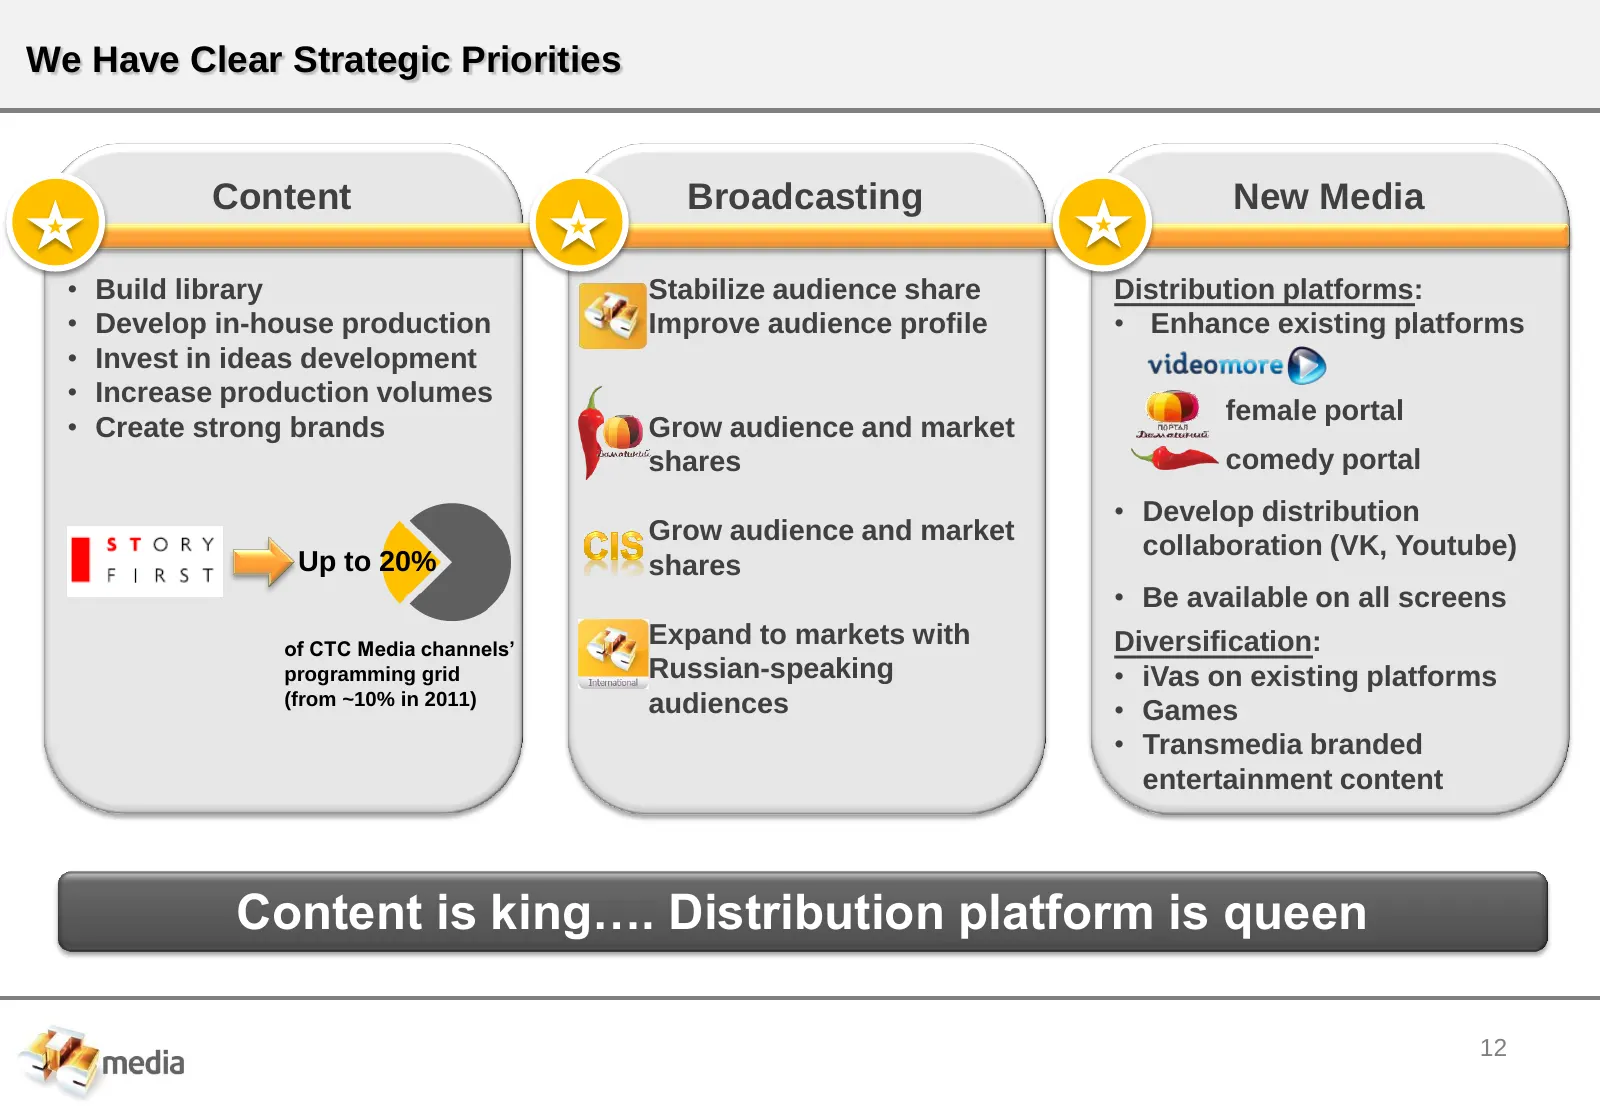
Slide 13: We Have Clear Strategic Priorities
We Have Clear Strategic Priorities Content Broadcasting New Media • Build library Stabilize audience share Distribution platforms: • Develop in-house production Improve audience profile • Enhance existing platforms • Invest in ideas development • Increase production volumes female portal • Create st
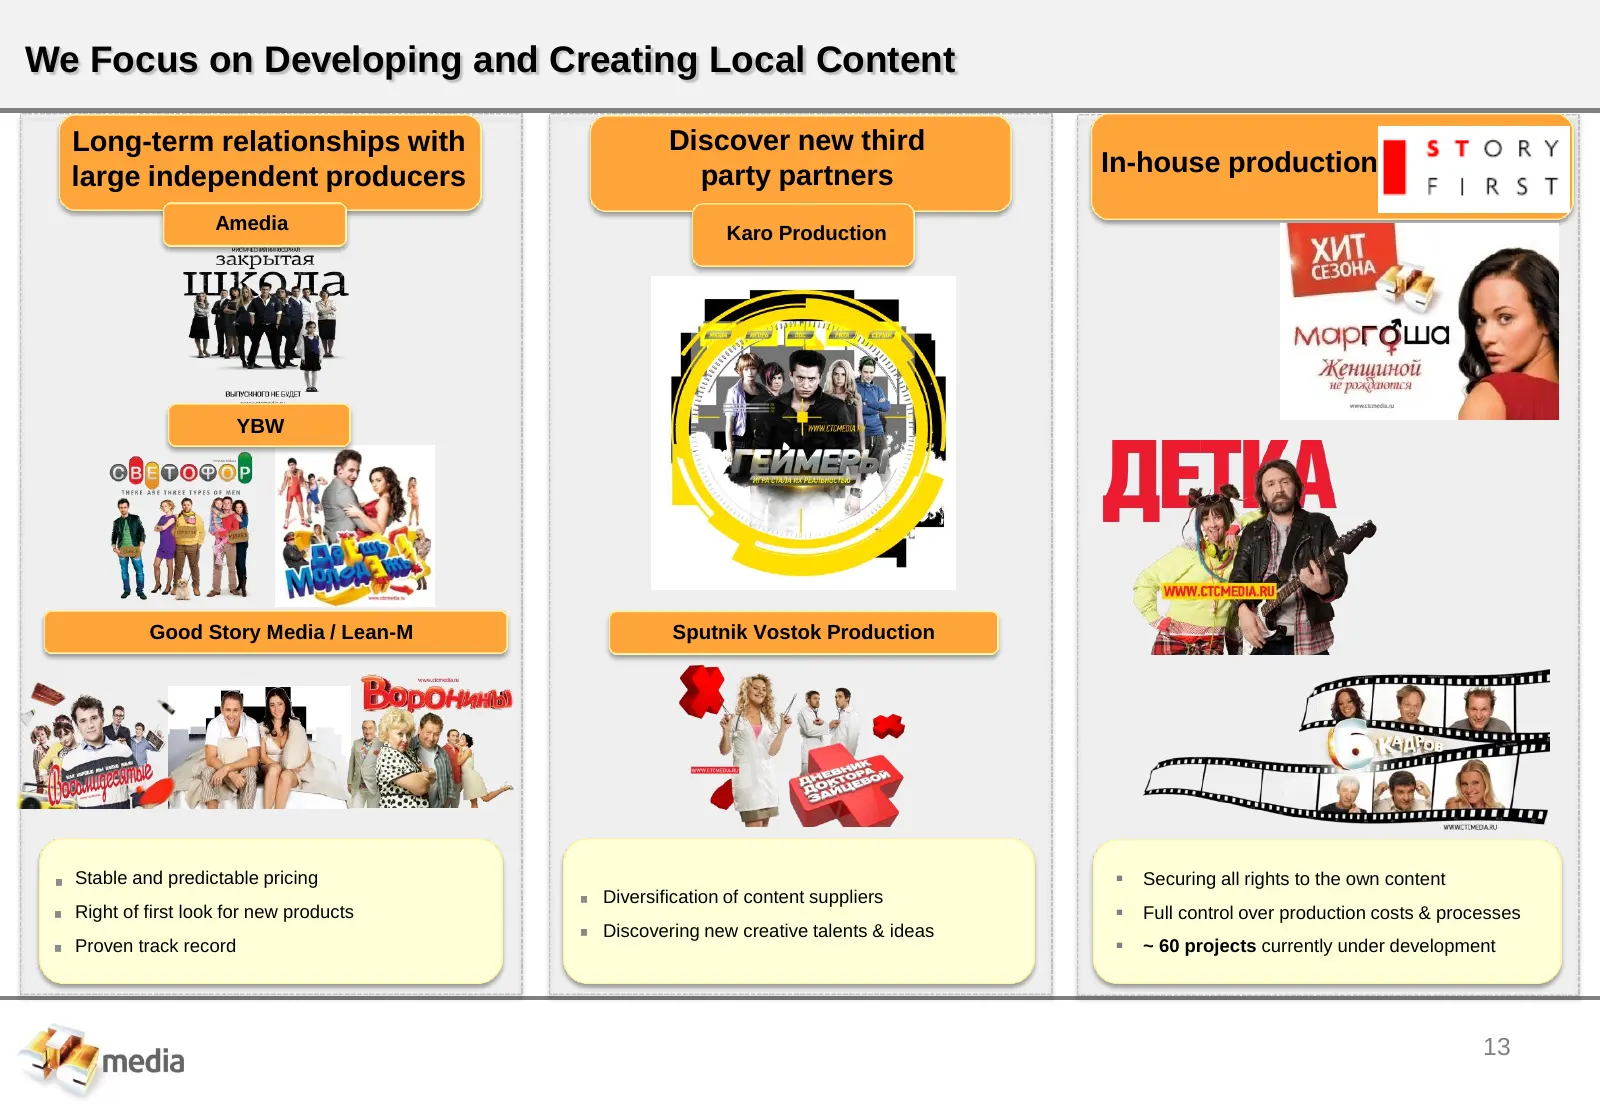
Slide 14: We Focus on Developing and Creating Local Content
We Focus on Developing and Creating Local Content Long-term relationships with Discover new third large independent producers party partners In-house production Amedia Karo Production YBW Good Story Media / Lean-M Sputnik Vostok Production Stable and predictable pricing Securing all rights to the
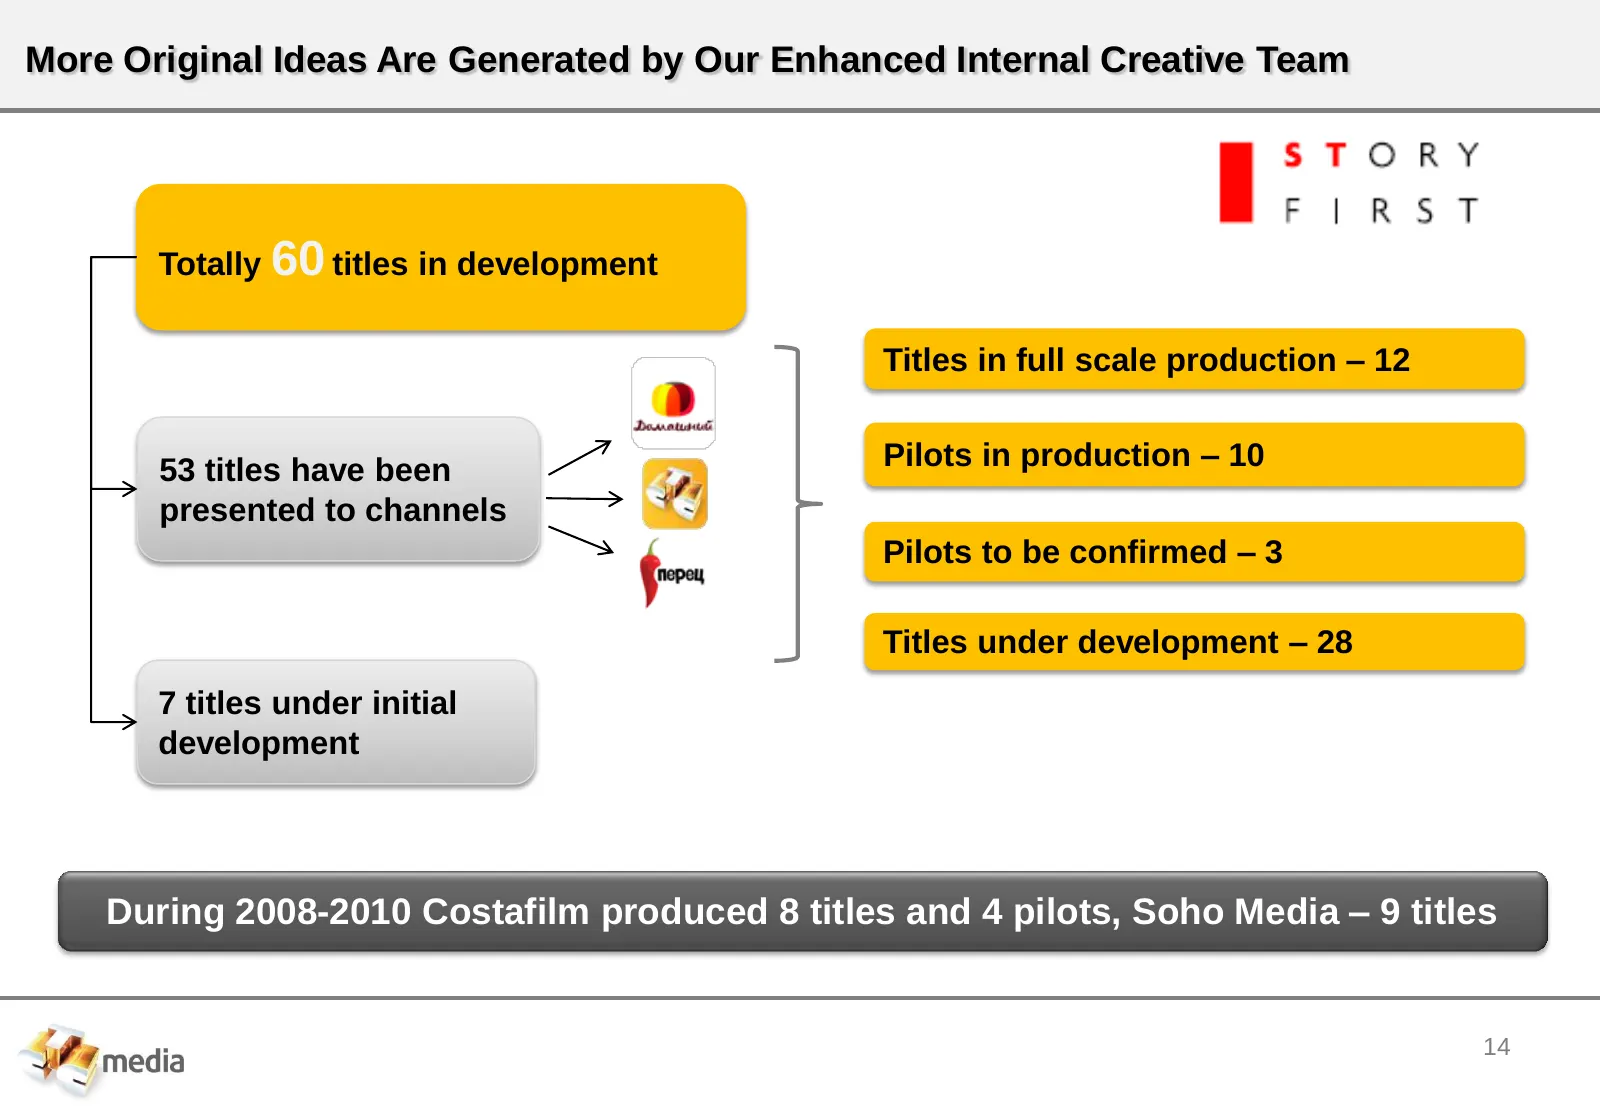
Slide 15: More Original Ideas Are Generated by Our Enhanced Internal Creative Team
More Original Ideas Are Generated by Our Enhanced Internal Creative Team Totally 60 titles in development Titles in full scale production – 12 53 titles have been Pilots in production – 10 presented to channels Pilots to be confirmed – 3 Titles under development – 28 7 titles under initial developme
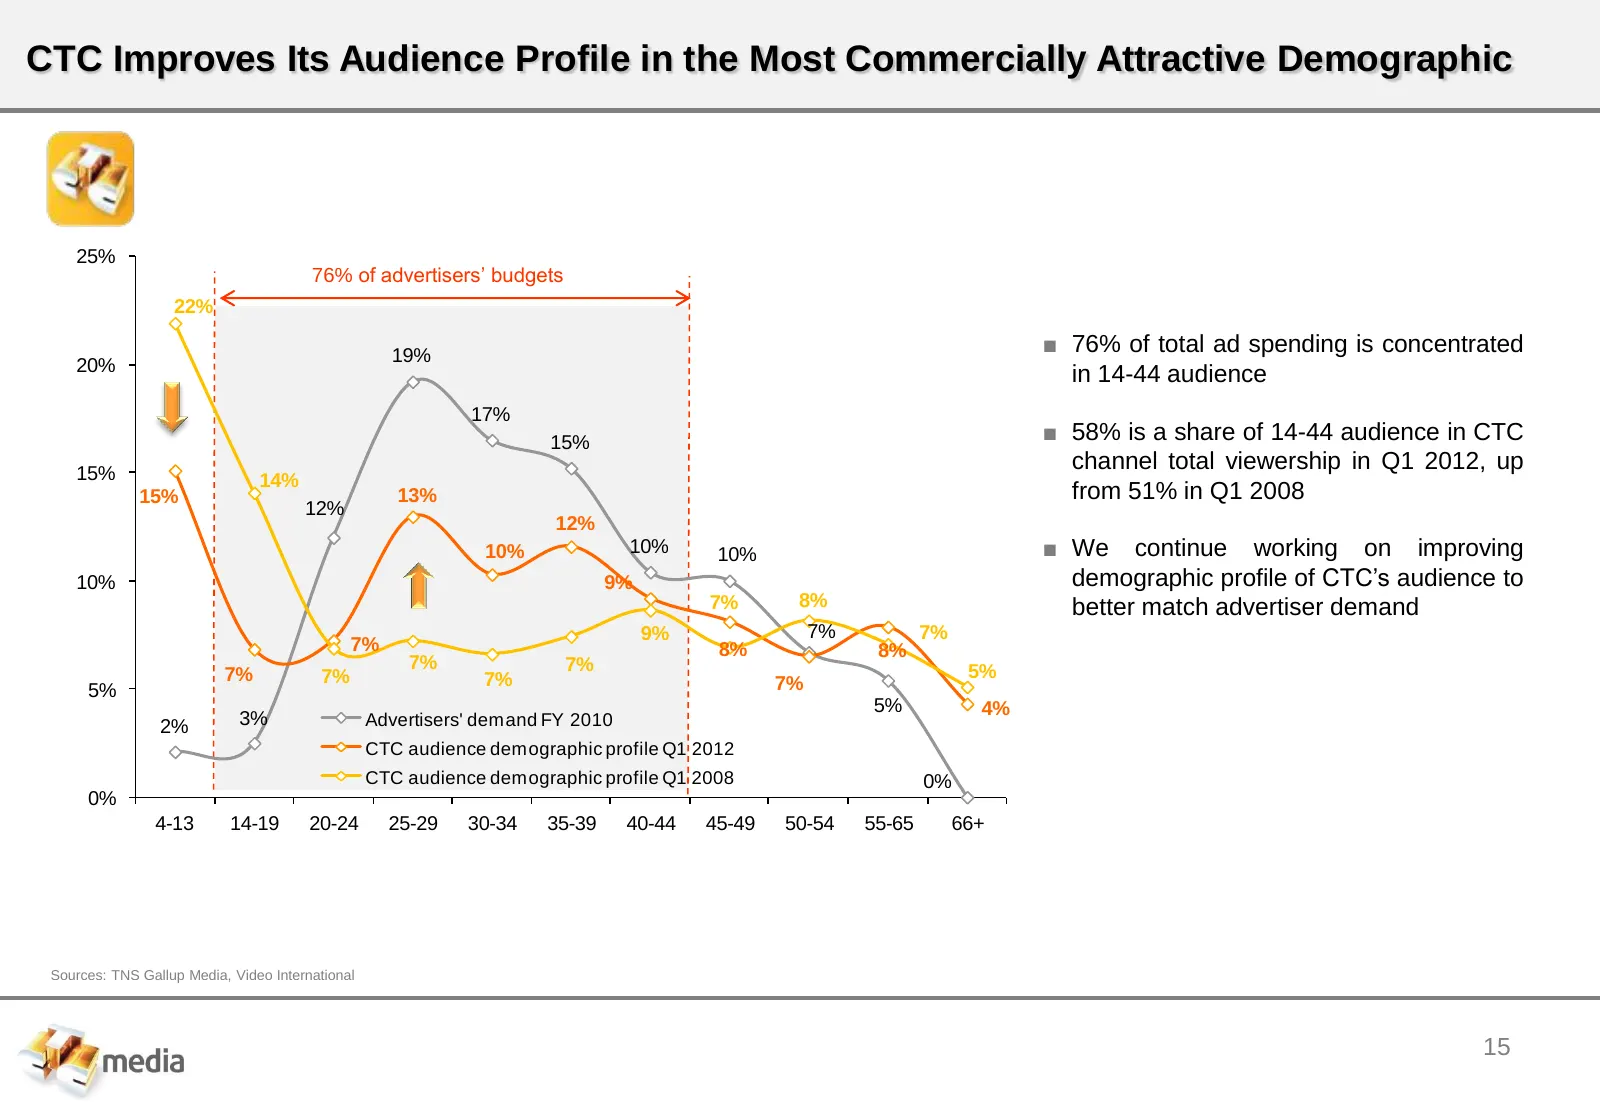
Slide 16: CTC Improves Its Audience Profile in the Most Commercially Attractive Demographic
CTC Improves Its Audience Profile in the Most Commercially Attractive Demographic 25% 76% of advertisers’ budgets 22% 19% ■ 76% of total ad spending is concentrated 20% in 14-44 audience 17% 15% ■ 58% is a share of 14-44 audience in CTC 15% channel total viewership in Q1 2012, up 14% 15% 13% from 51
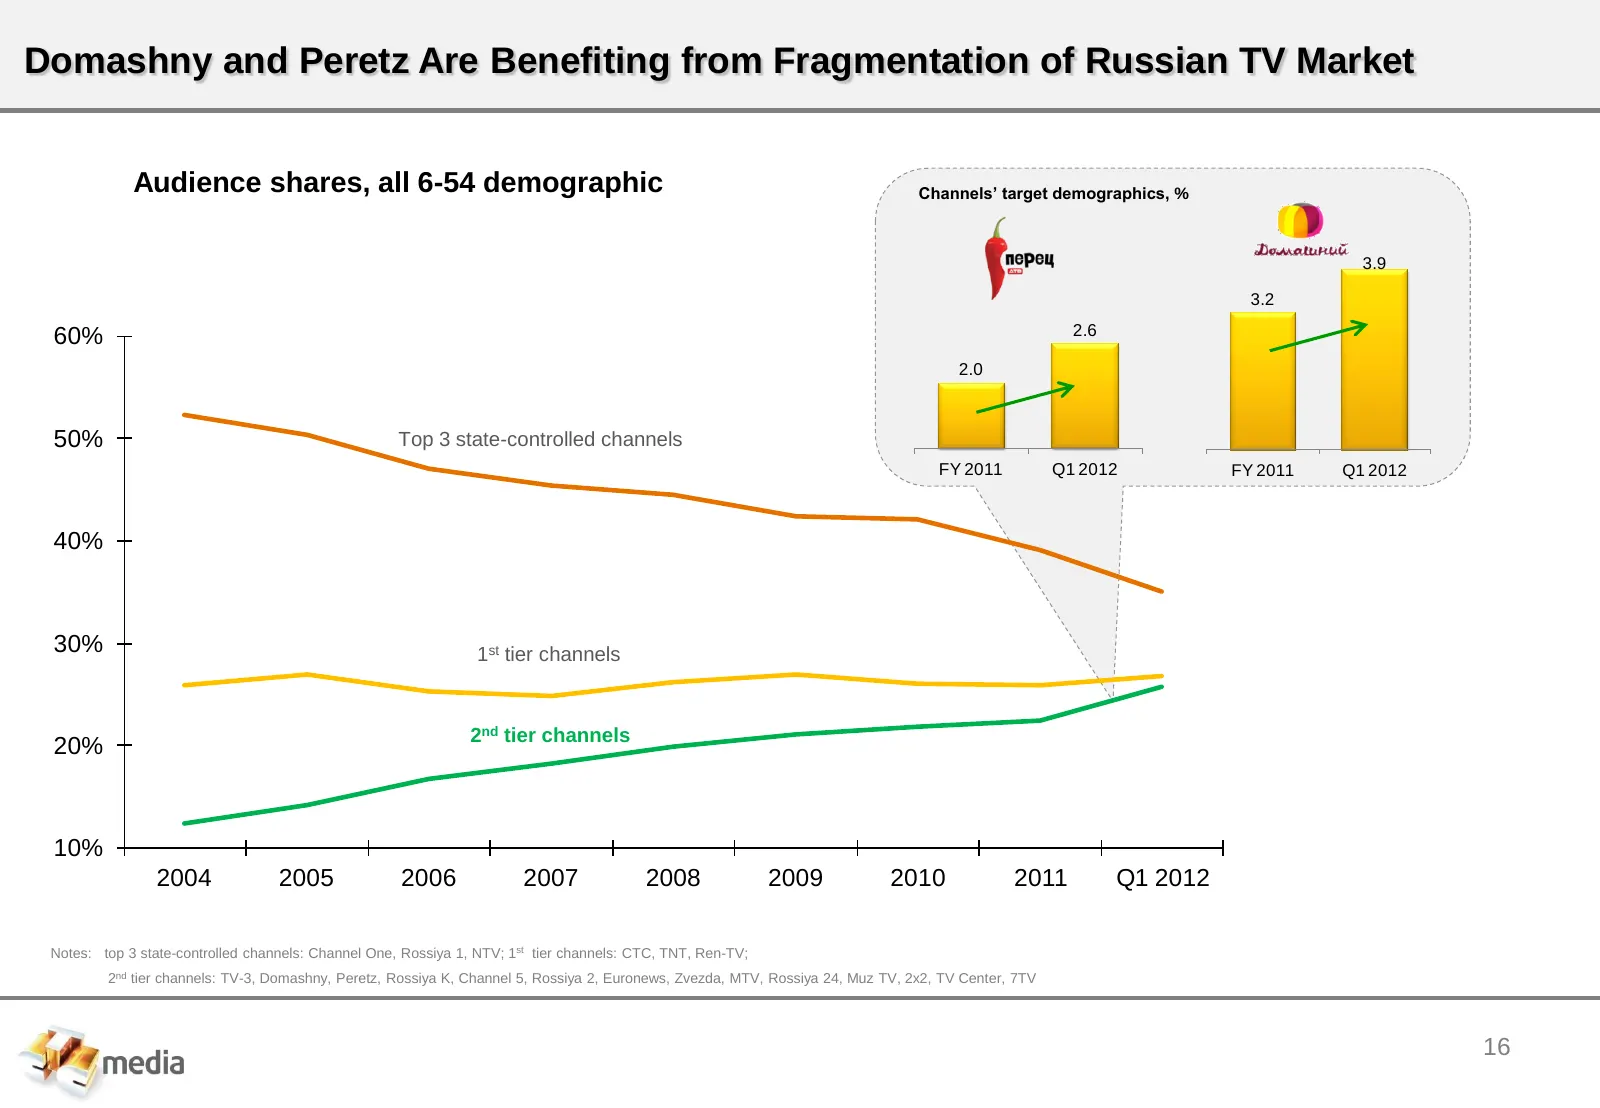
Slide 17: Domashny and Peretz Are Benefiting from Fragmentation of Russian TV Market
Domashny and Peretz Are Benefiting from Fragmentation of Russian TV Market Audience shares, all 6-54 demographic Channels’ target demographics, % 3.9 3.2 60% 2.6 2.0 50% Top 3 state-controlled channels FY 2011 Q1 2012 FY 2011 Q1 2012 40% 30% 1st tier channels 2nd tier channels 20% 10% 2004 2005 2006
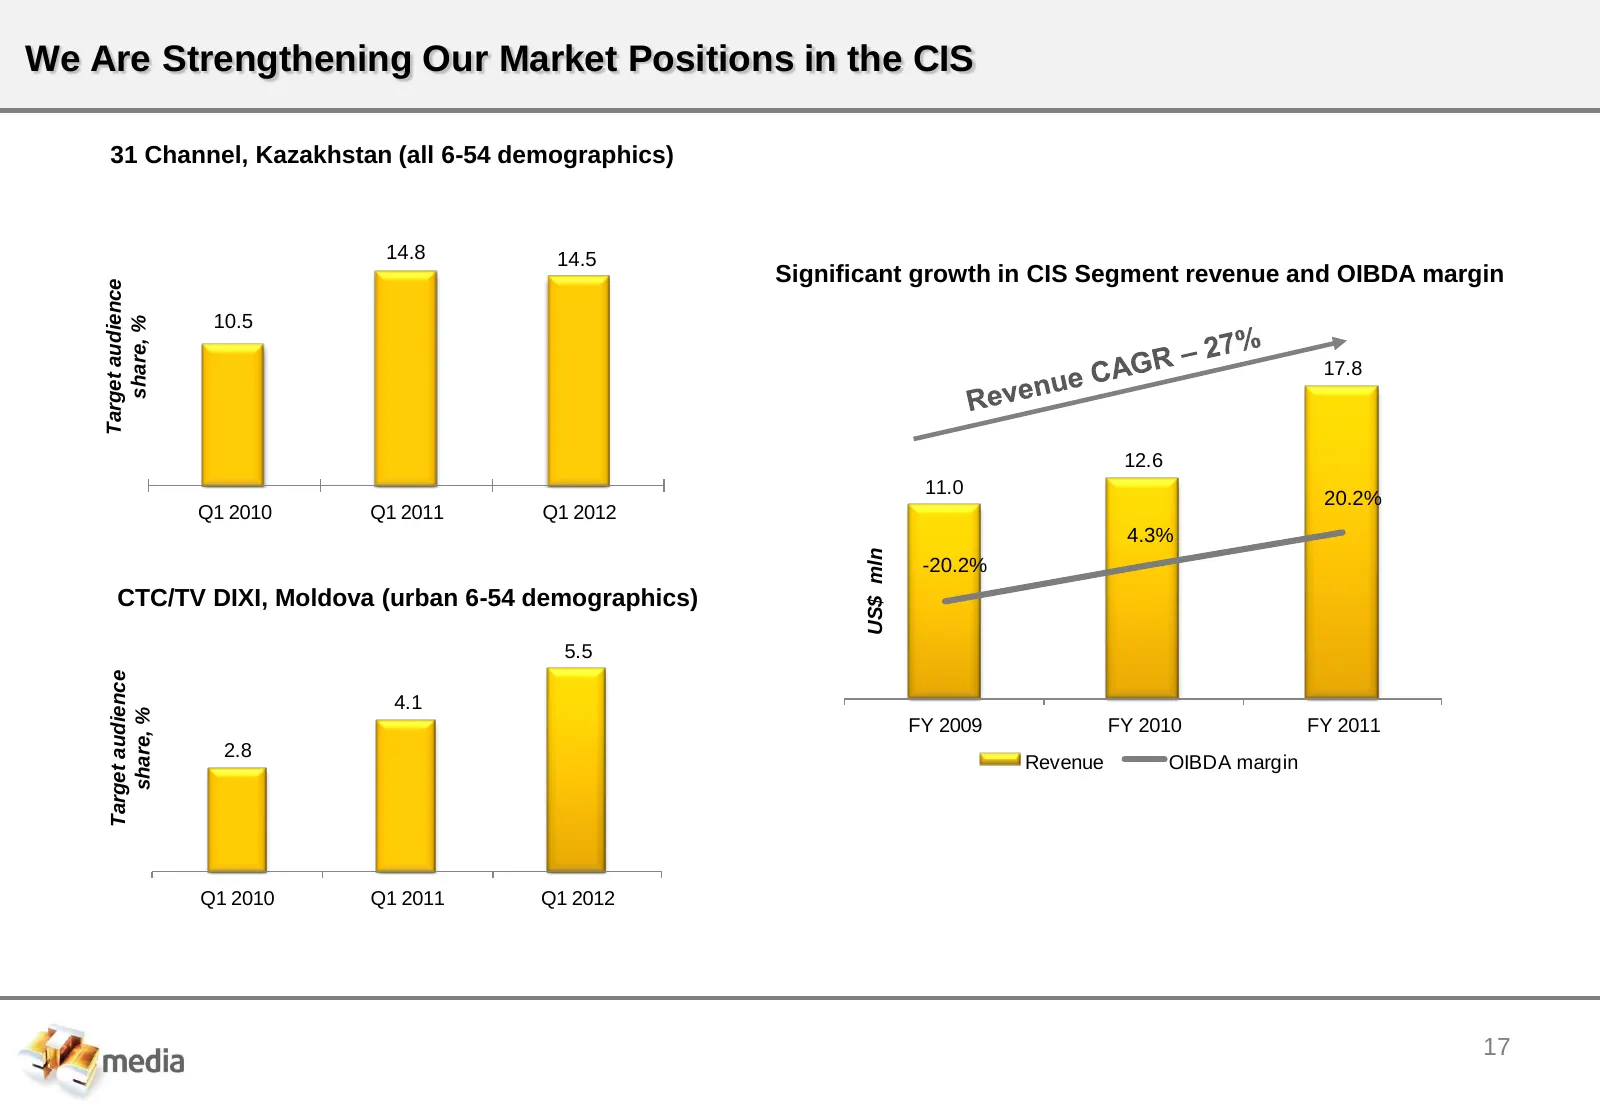
Slide 18: We Are Strengthening Our Market Positions in the CIS
We Are Strengthening Our Market Positions in the CIS 31 Channel, Kazakhstan (all 6-54 demographics) 14.8 14.5 Significant growth in CIS Segment revenue and OIBDA margin Target audience 10.5 share, % 17.8 12.6 11.0 20.2% Q1 2010 Q1 2011 Q1 2012 4.3% US$ mln -20.2% CTC/TV DIXI, Moldova (urban 6-54 dem
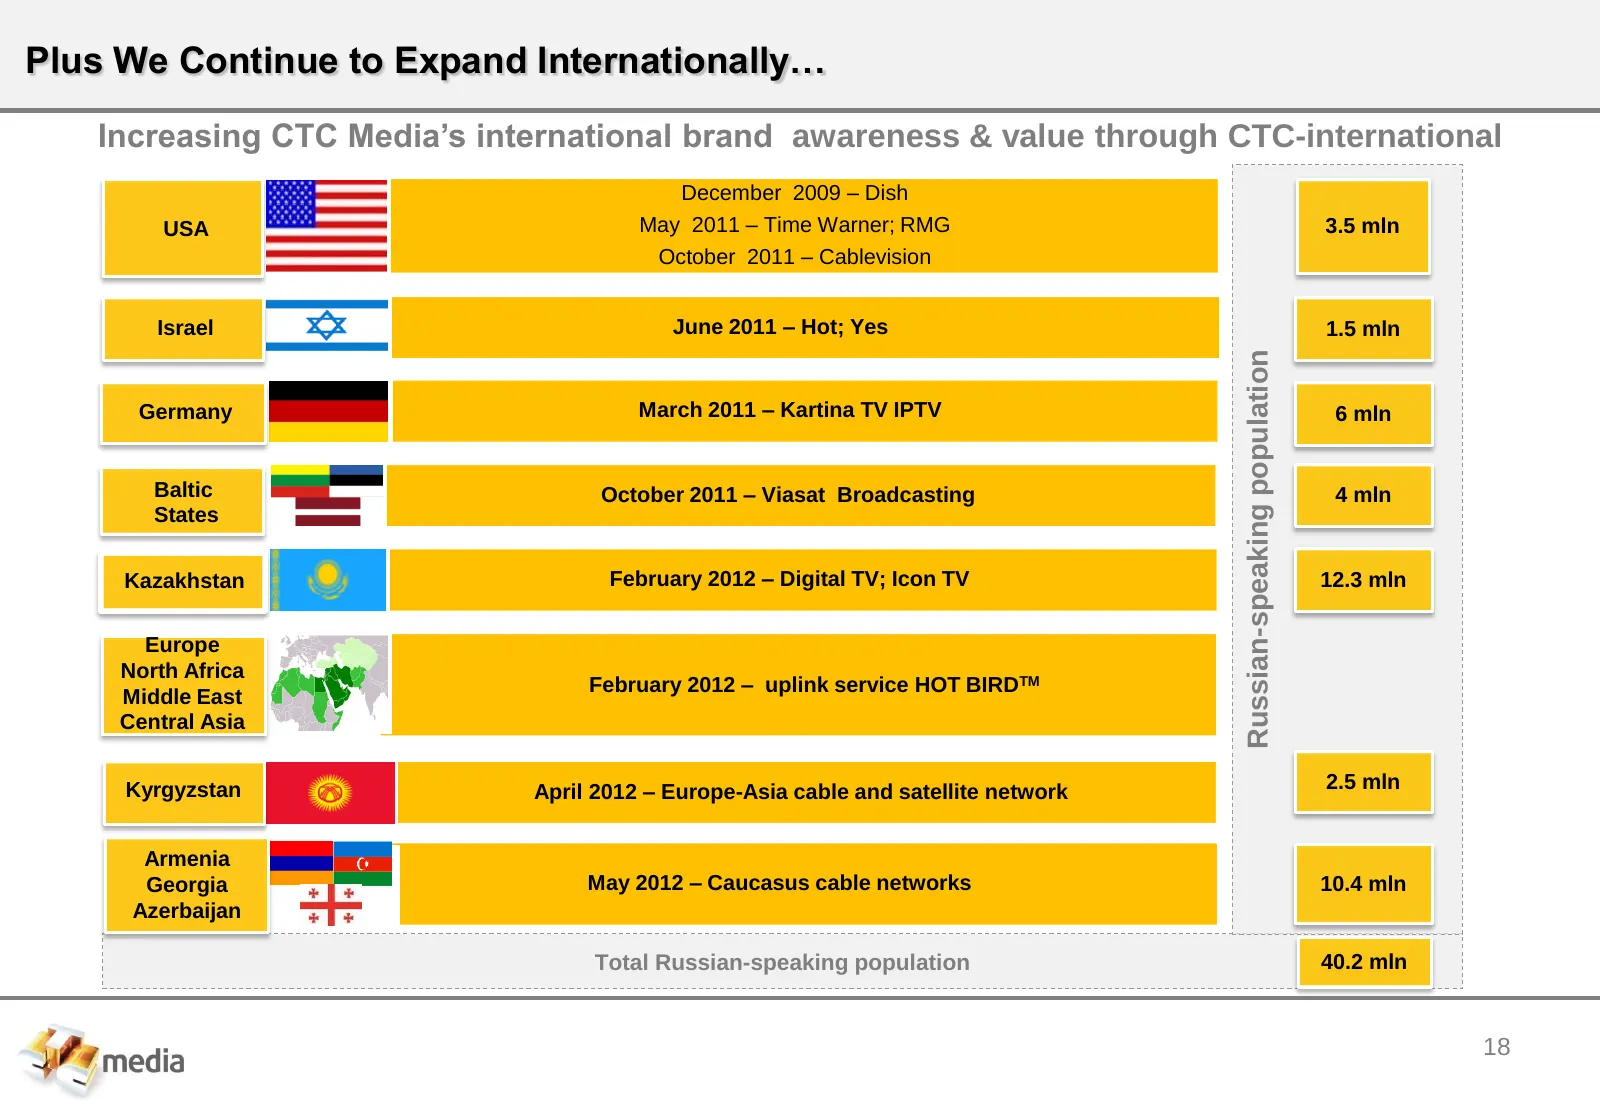
Slide 19: Plus We Continue to Expand Internationally
Plus We Continue to Expand Internationally… Increasing CTC Media’s international brand awareness & value through CTC-international December 2009 – Dish USA May 2011 – Time Warner; RMG 3.5 mln October 2011 – Cablevision Israel June 2011 – Hot; Yes 1.5 mln Russian-speaking population Germany March 201
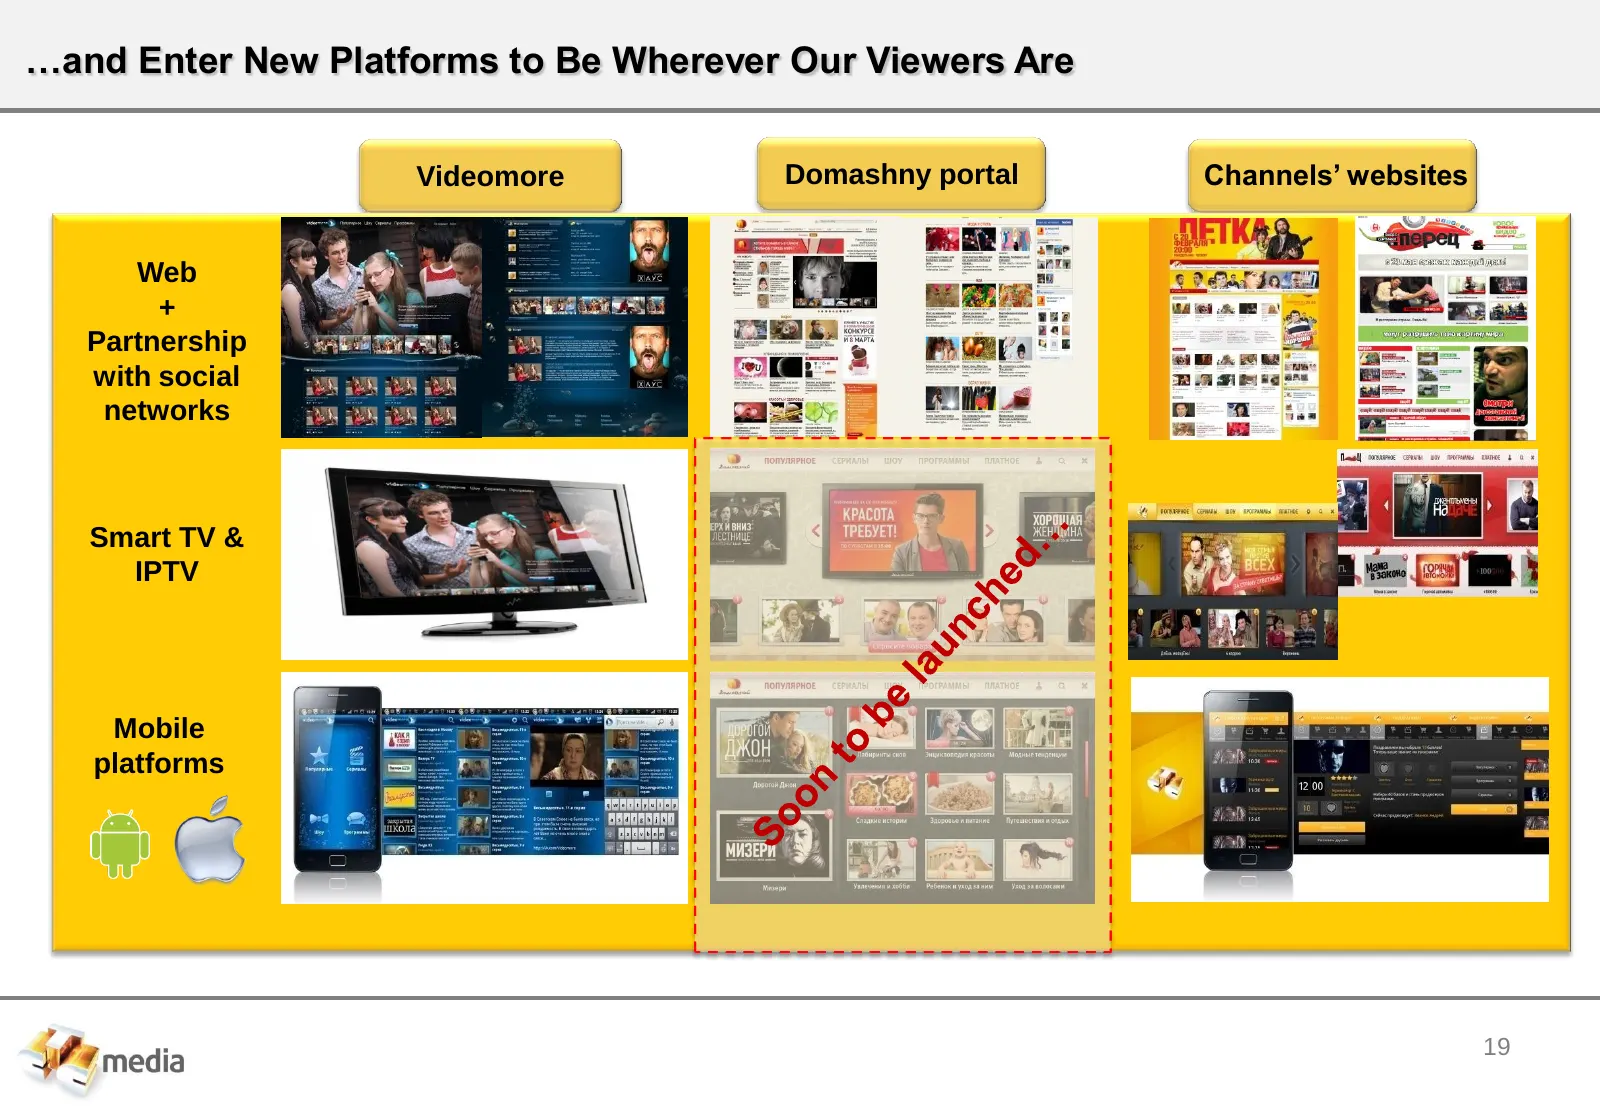
Slide 20: …and Enter New Platforms to Be Wherever Our Viewers Are
…and Enter New Platforms to Be Wherever Our Viewers Are Videomore Domashny portal Channels’ websites Web + Partnership with social networks Smart TV & IPTV Mobile platforms 19
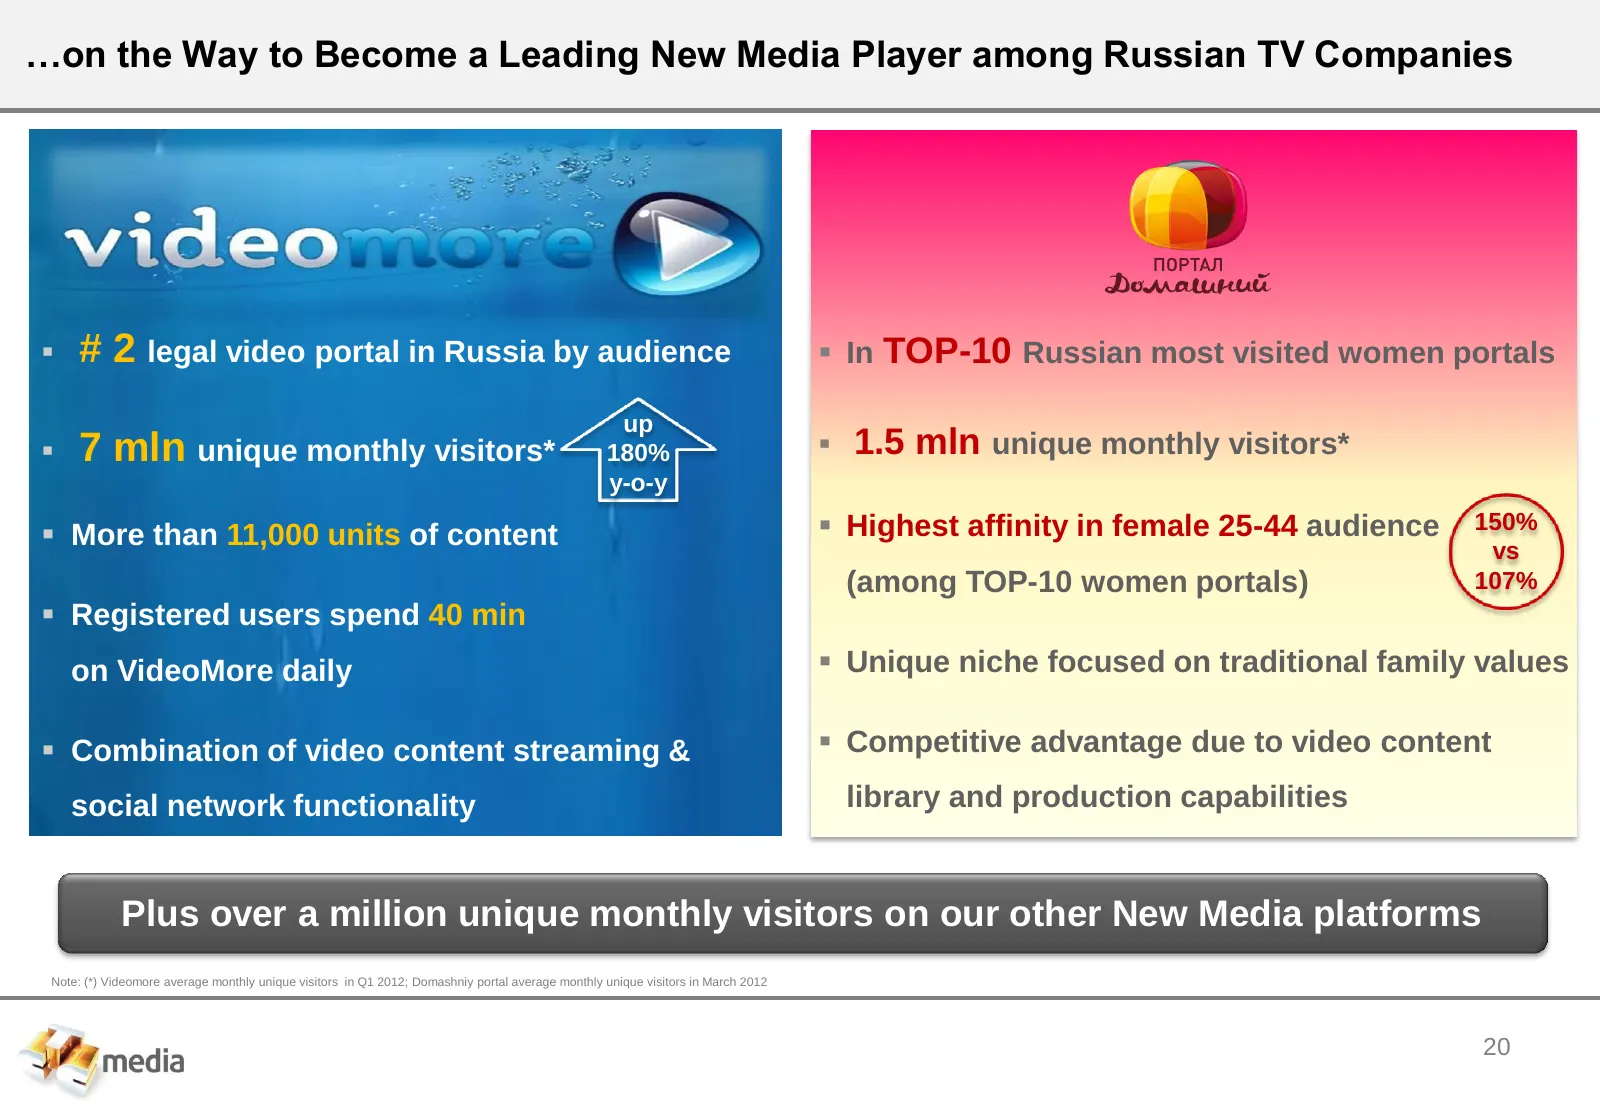
Slide 21: On the Way to Become a Leading New Media Player among Russian TV Companies
…on the Way to Become a Leading New Media Player among Russian TV Companies # 2 legal video portal in Russia by audience In TOP-10 Russian most visited women portals up 7 mln unique monthly visitors* 180% 1.5 mln unique monthly visitors* y-o-y More than 11,000 units of content Highest af
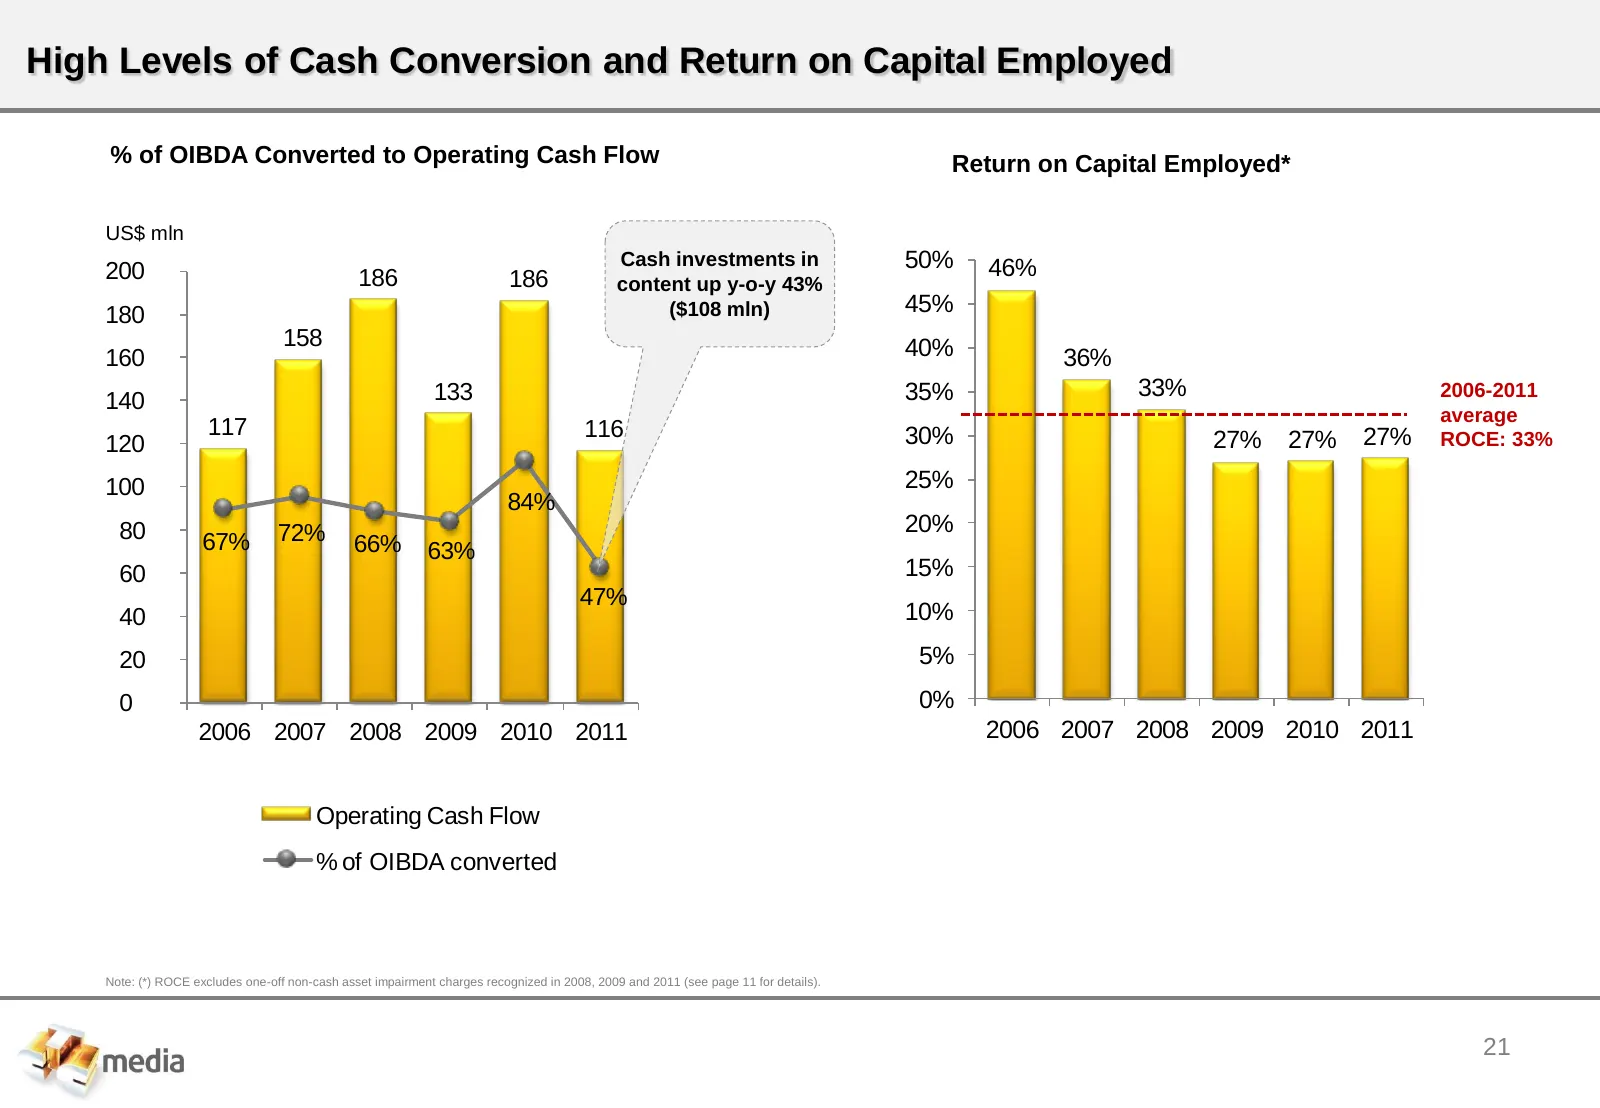
Slide 22: High Levels of Cash Conversion and Return on Capital Employed
High Levels of Cash Conversion and Return on Capital Employed % of OIBDA Converted to Operating Cash Flow Return on Capital Employed* US$ mln 200 Cash investments in 50% 46% 186 186 content up y-o-y 43% 180 ($108 mln) 45% 158 40% 160 36% 133 35% 33% 2006-2011 140 average 117 116 30% 27% 120 27% 27%
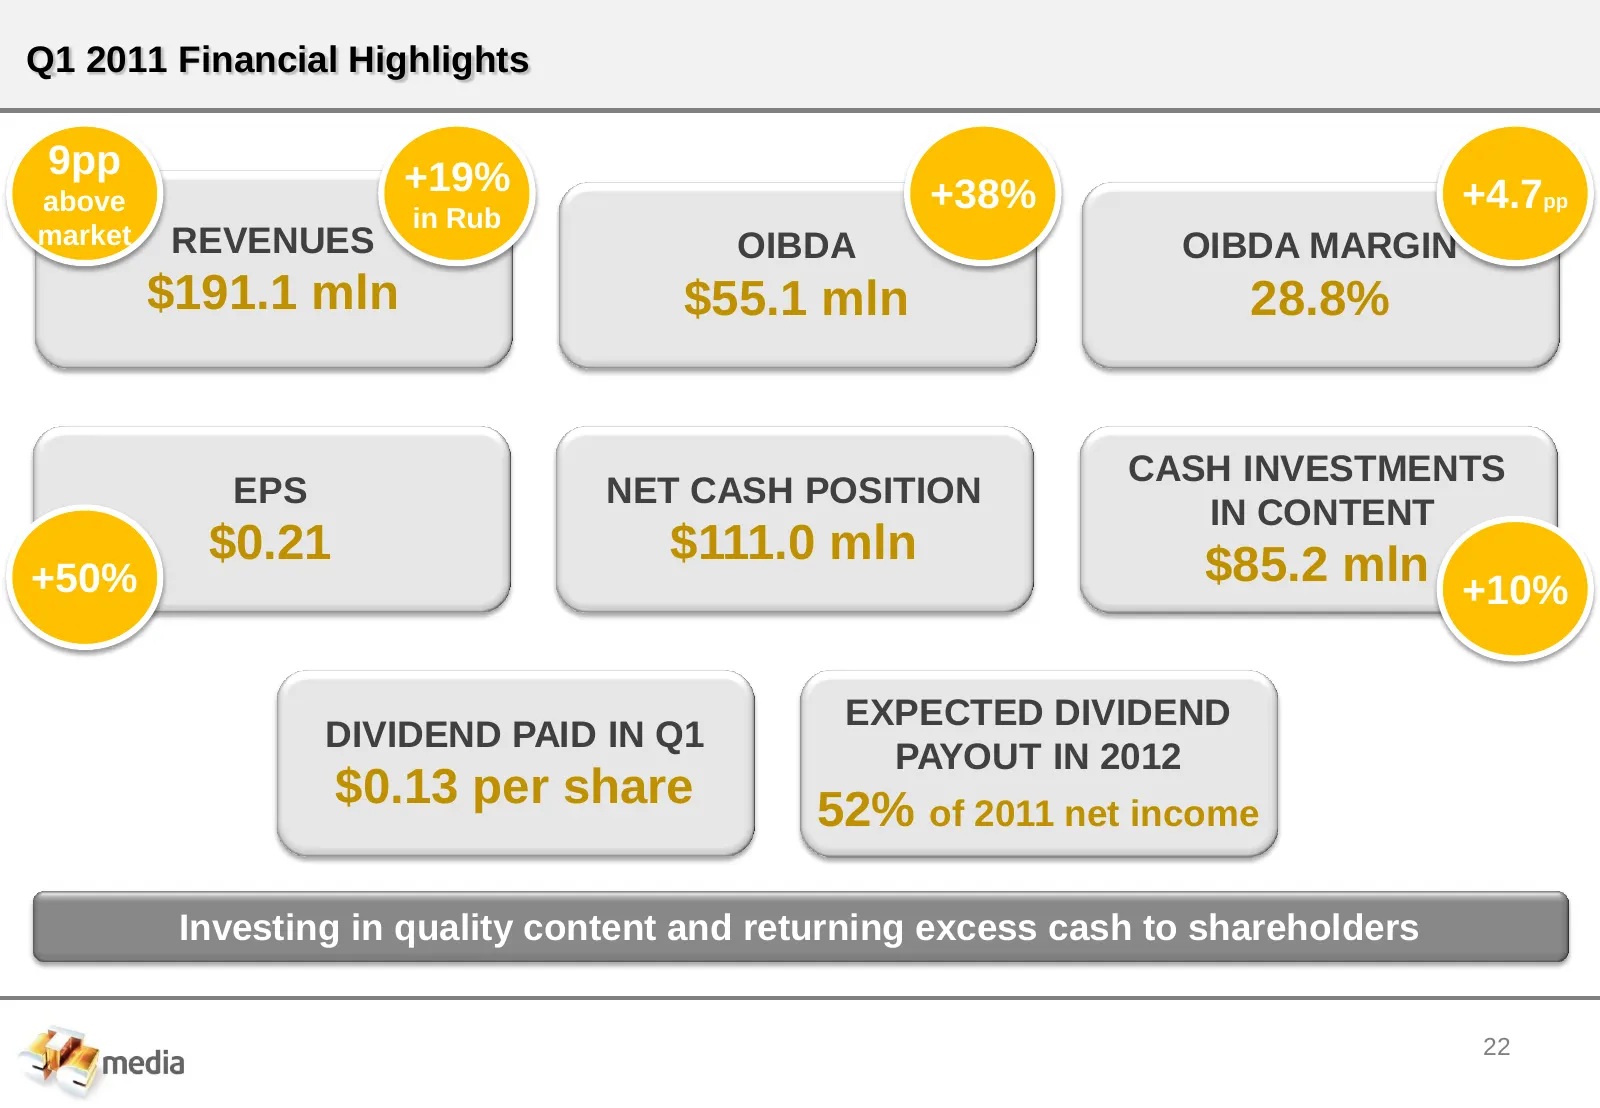
Slide 23: Q1 Financial Highlights
Q1 2011 Financial Highlights 9pp +19% above in Rub +38% +4.7pp market REVENUES OIBDA OIBDA MARGIN $191.1 mln $55.1 mln 28.8% CASH INVESTMENTS EPS NET CASH POSITION IN CONTENT $0.21 $111.0 mln $85.2 mln +10% +50% EXPECTED DIVIDEND DIVIDEND PAID IN Q1 PAYOUT IN 2012 $0.13 per share 52% of 2011 net inc
Slide 24: To Conclude…
To Conclude… The largest independent and the only publicly listed broadcaster in Russia Growth company offering unique play on growing Russian & CIS TV advertising markets Targeting audiences which are most attractive to advertisers Controlling the whole value chain by vertically integrating content
Slide 25: MTG Capital Markets Day
MTG Capital Markets Day June 14, 2012 Boris Podolsky Acting Chief Executive Officer Chief Financial Officer
Slide 26: Appendix
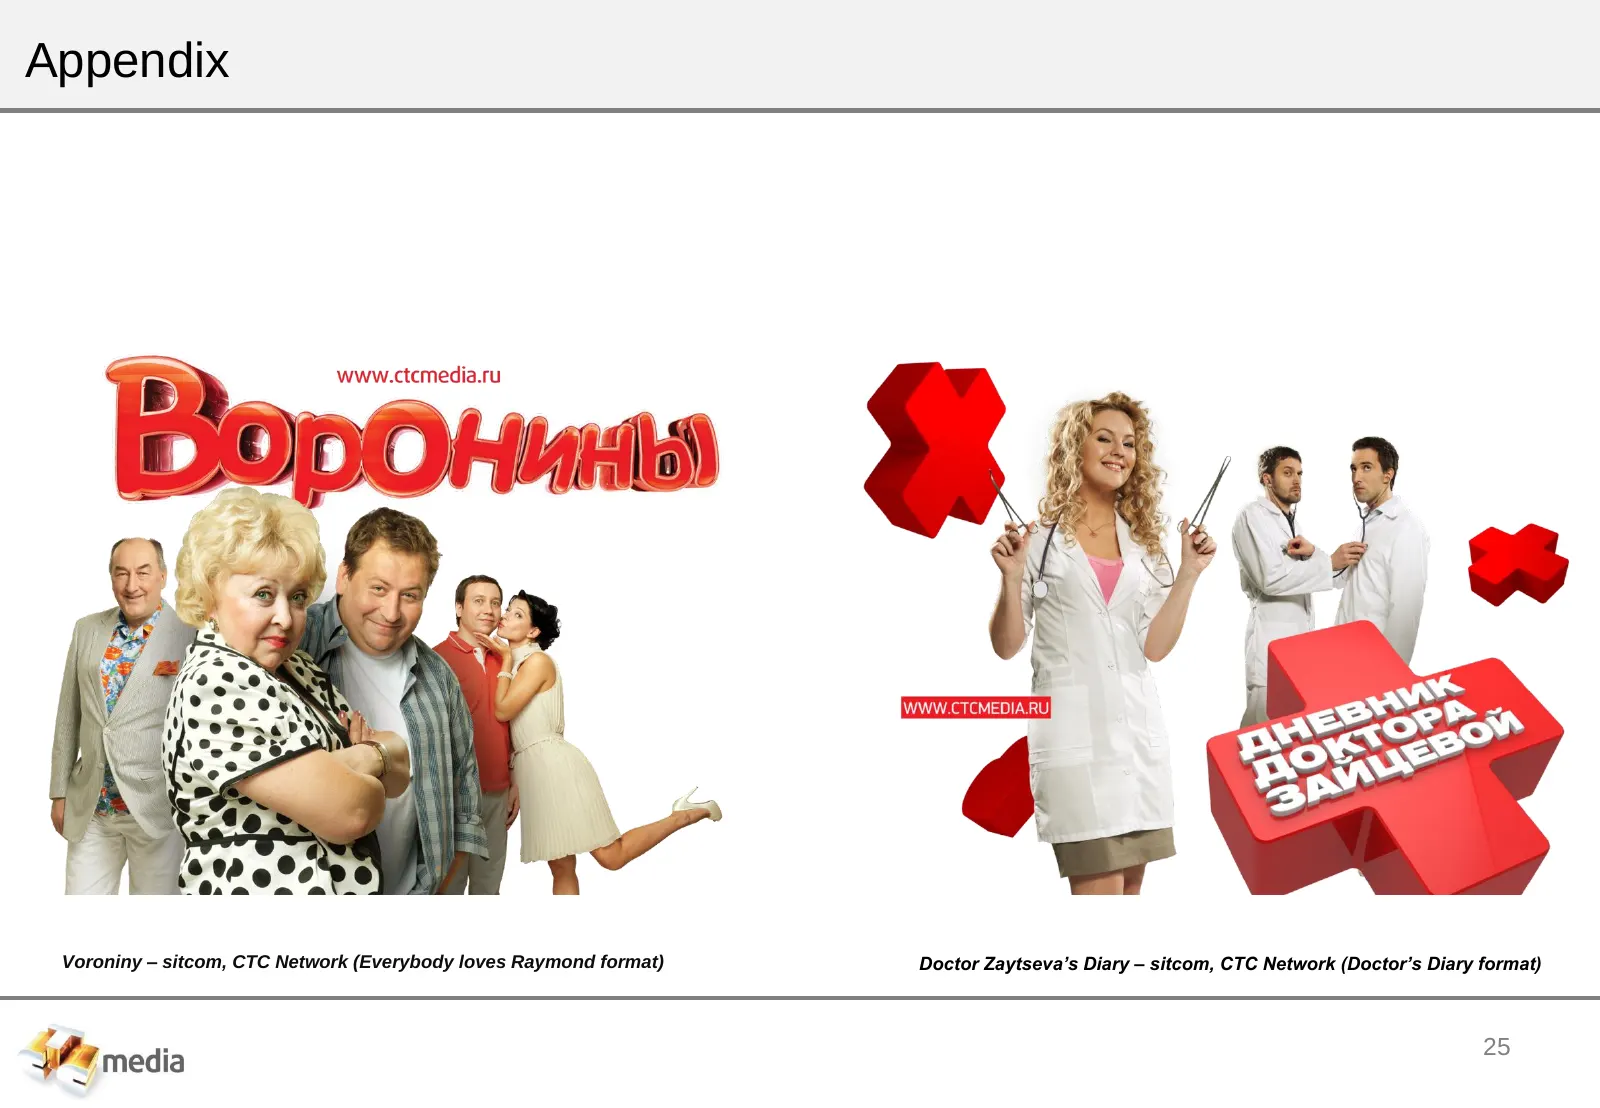
Appendix Voroniny – sitcom, CTC Network (Everybody loves Raymond format) Doctor Zaytseva’s Diary – sitcom, CTC Network (Doctor’s Diary format) 25
Slide 27: Reconciliation of Non-GAAP Measures
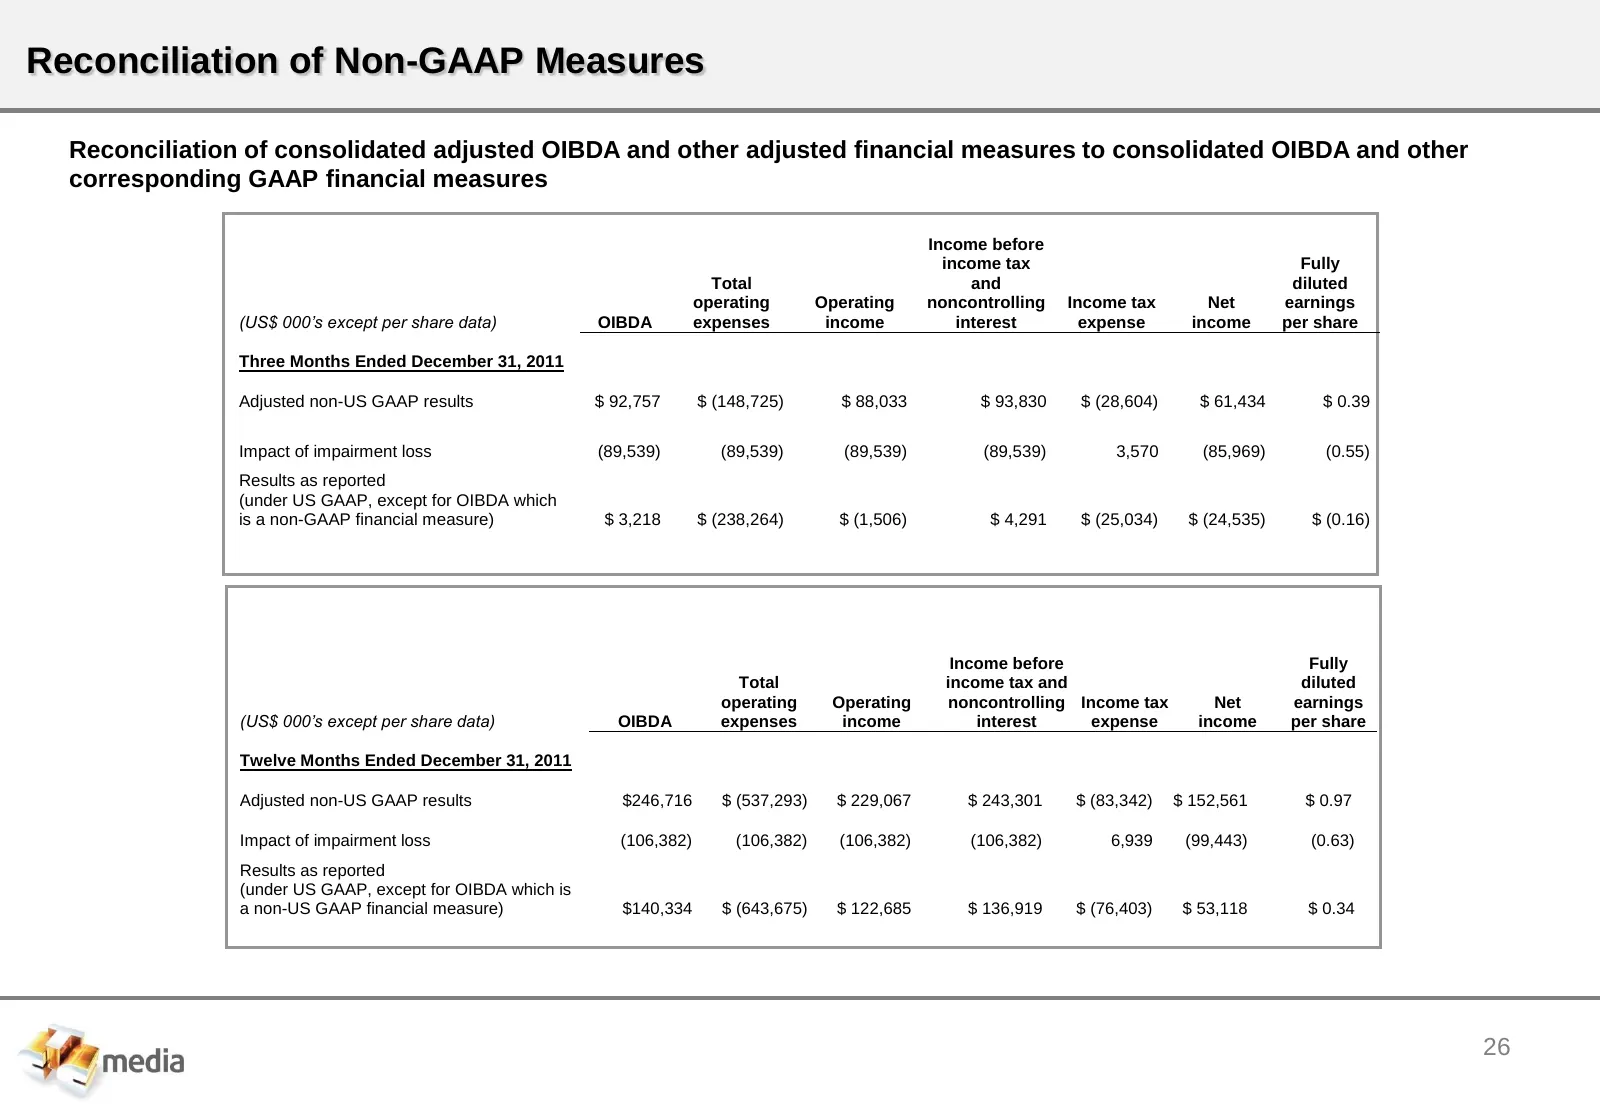
Reconciliation of Non-GAAP Measures Reconciliation of consolidated adjusted OIBDA and other adjusted financial measures to consolidated OIBDA and other corresponding GAAP financial measures Income before income tax Fully Total and diluted operating Operating noncontrolling Income tax Net earnings (U
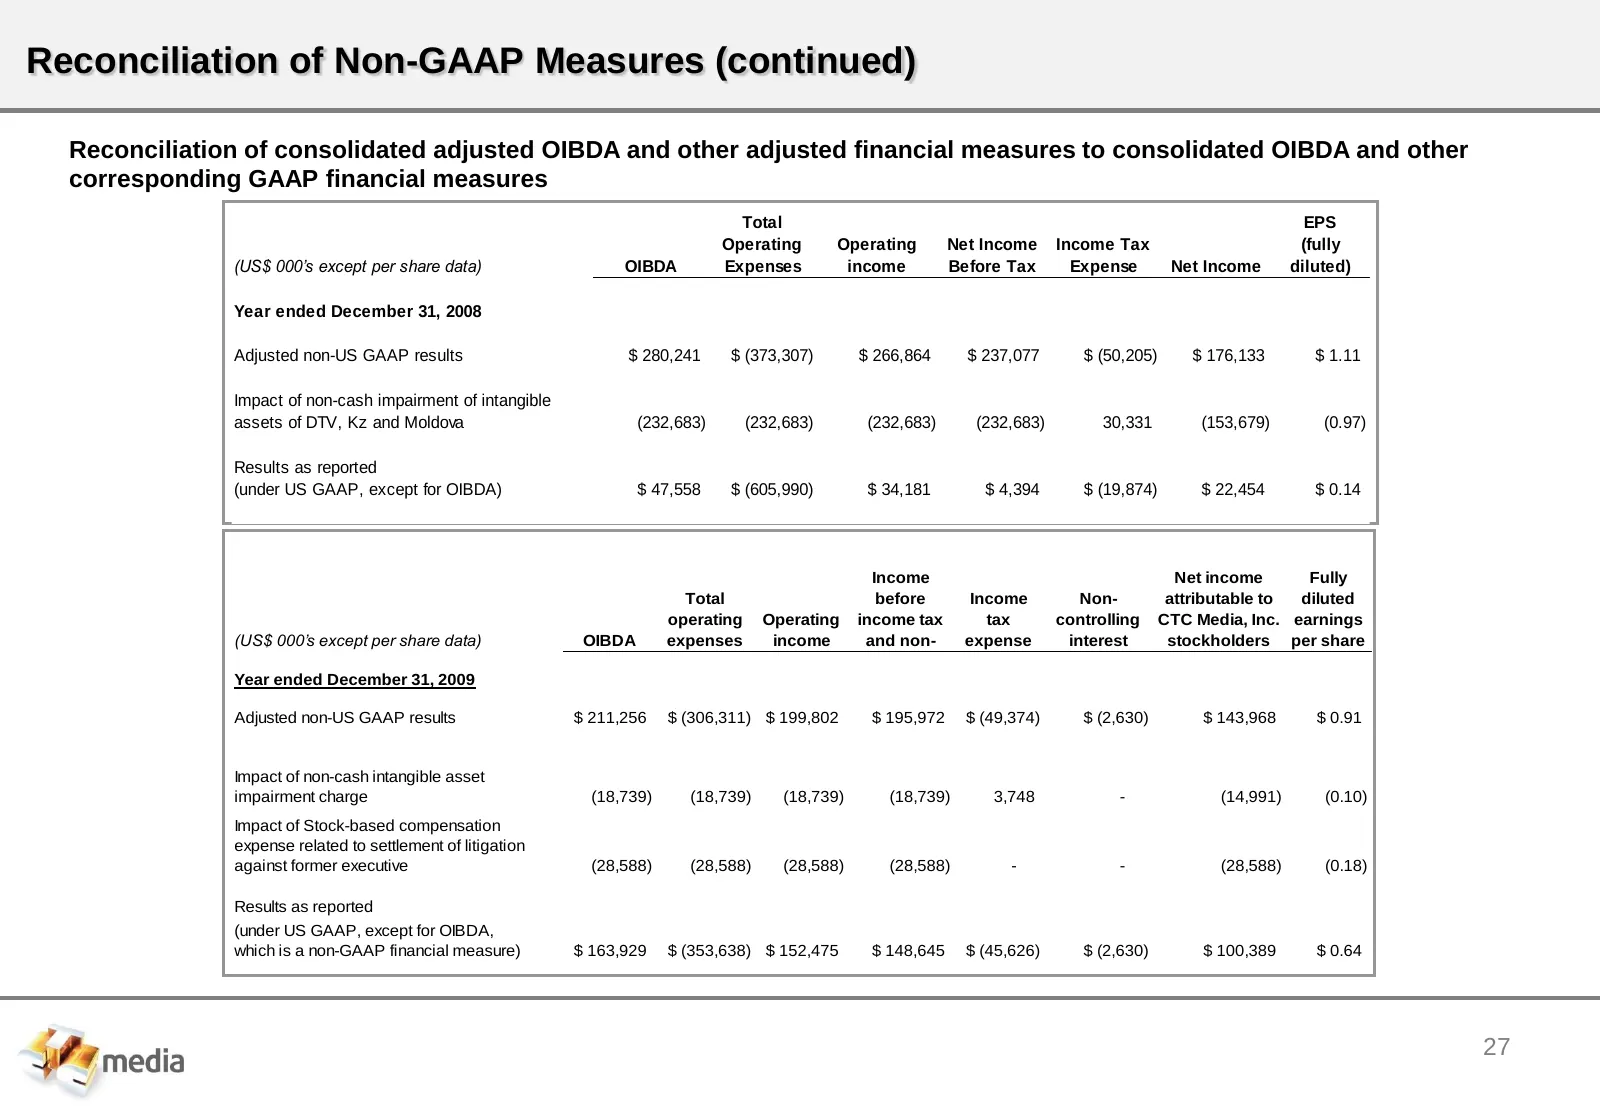
Slide 28: Reconciliation of Non-GAAP Measures (continued)
Reconciliation of Non-GAAP Measures (continued) Reconciliation of consolidated adjusted OIBDA and other adjusted financial measures to consolidated OIBDA and other corresponding GAAP financial measures Total EPS Operating Operating Net Income Income Tax (fully (US$ 000’s except per share data) OIBDA
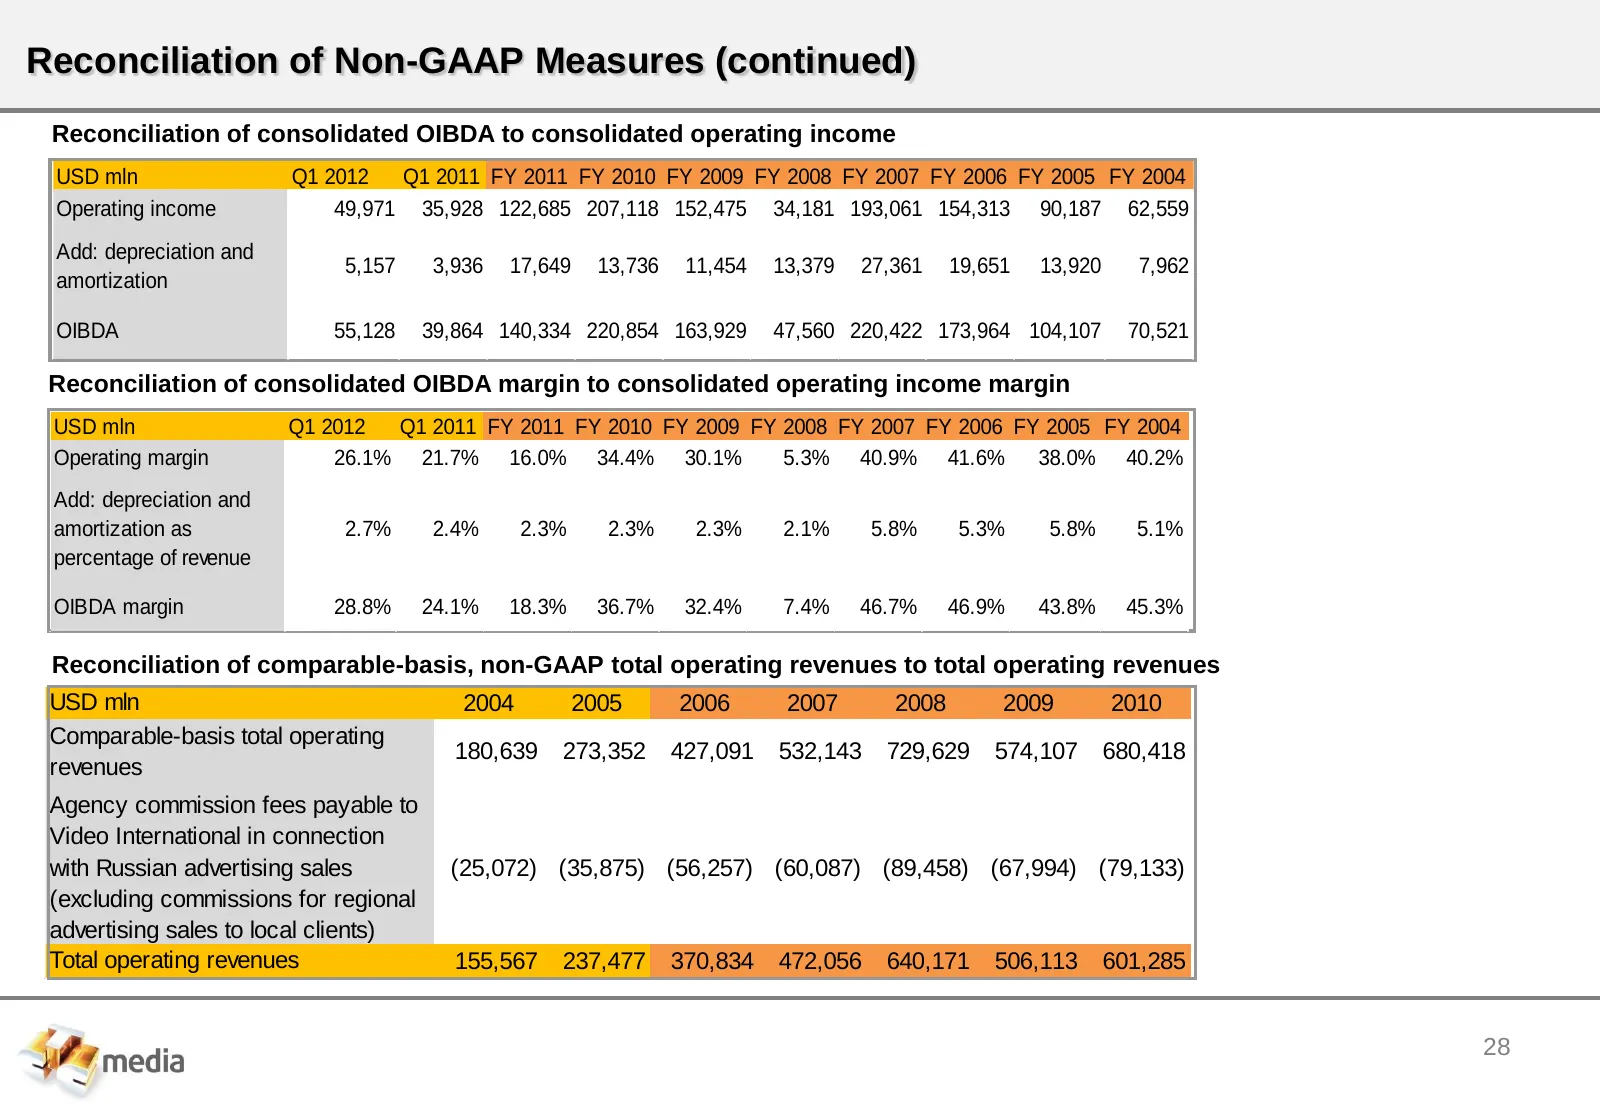
Slide 29: Reconciliation of Non-GAAP Measures (continued)
Reconciliation of Non-GAAP Measures (continued) Reconciliation of consolidated OIBDA to consolidated operating income USD mln Q1 2012 Q1 2011 FY 2011 FY 2010 FY 2009 FY 2008 FY 2007 FY 2006 FY 2005 FY 2004 Operating income 49,971 35,928 122,685 207,118 152,475 34,181 193,061 154,313 90,187 62,559 Ad
Slide 30: Contact Information and Disclaimer
Contact Information and Disclaimer For further information please visit www.ctcmedia.ru or contact: Ekaterina Ostrova Irina Klimova Director, Investor Relations Investor Relations Manager E-mail: ir@ctcmedia.ru Tel: +7 (495) 783 3650 Tel: +7 (495) 981 0740 DISCLAIMER The information contained in t
Source: company website