Airtran — Merger or Acquisition (January 2007)
34 slides from Airtran's merger presentation, Jan 11, 2007
Slide 1: Tender Offer Presentation
Exhibit 99.1 Tender Offer Presentation January 11, 2007 1
Slide 2: Safe Harbor Disclosure
Safe Harbor Disclosure Certain of the statements contained herein should be considered “forward-looking staternents” within the meaning of the Private Securities Litigation Reform Act of 1995. These forward-looking statements may be identified by words such as “may, “ “will, “ “expect, “ “intend,” “
Slide 3: AirTran and Midwest
AirTran and Midwest AirTran Holdings has initiated a tender offer for all outstanding shares of Midwest Air Group Significant benefits exist for all stakeholders — Midwest shareholders receive a significant premium — Employees benefit from improved growth opportunities and additional job security —
Slide 4: Tender Offer Overview
Tender Offer Overview Offer Price: $13.25 per share Per Share Consideration: $6.625 in cash; 0.5884 shares of AAI Stock Premium(1) to 30 Day Avg.: 61% Conditions: Tender of a majority of Midwest shares on fully diluted basis. Satisfy the provisions of the Wisconsin Control Share Act and Wisconsin Bu
Slide 5: Powerful Strategic Rationale
Powerful Strategic Rationale Complementary route networks with limited overlap Combine AirTran’s strong East Coast network with Midwest’s hubs in Network Milwaukee and Kansas City Improved scale in consolidating industry with improved incremental growth opportunities 717 fleet commonality creates si
Slide 6: Stand Alone Strategy Risk
Stand Alone Strategy Risk Clirlran.com
Slide 7: Midwest Business Model is Struggling to Adapt
Midwest Business Model is Struggling to Adapt Originally a business travel service for Kimberly-Clark, Midwest Airlines began commercial services in 1984, and became a publicly-held company in 1995 Evolved slowly over time through its hub at Milwaukee — Unique, largely business product to select mar
Slide 8: Midwest Has Not Been Able to Sustain Profits
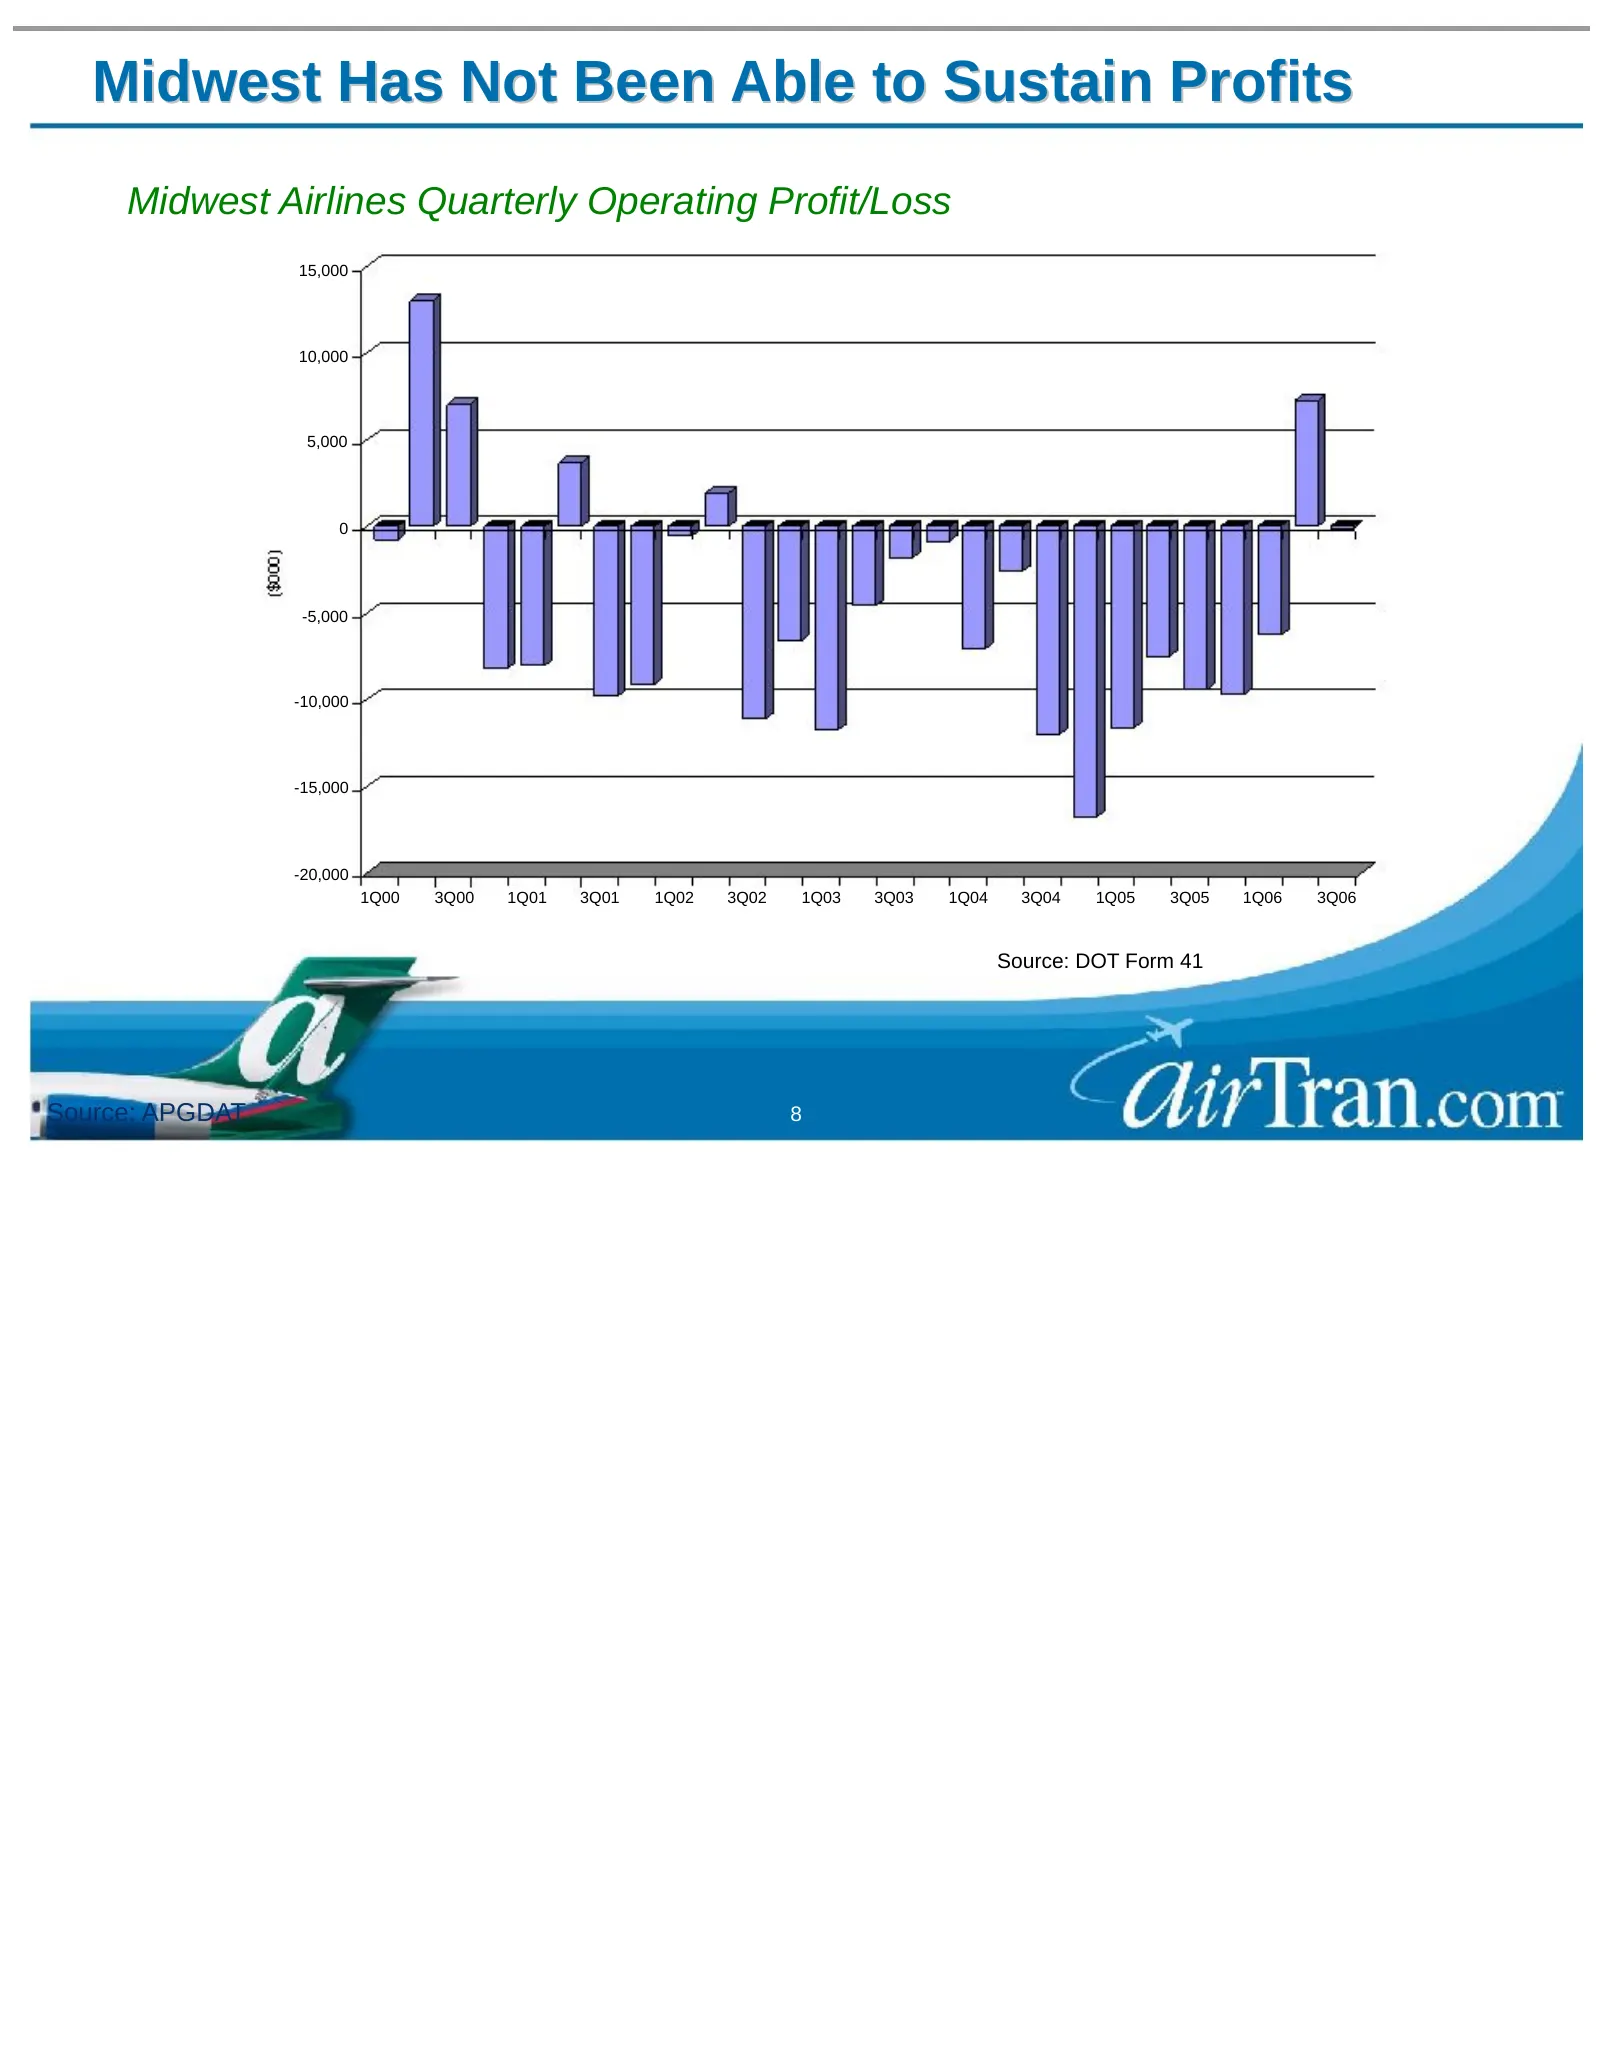
Midwest Has Not Been Able to Sustain Profits Midwest Airlines Quarterly Operating Profit/Loss 15,000 10,000 5,000 0 -5,000 -10,000 -15,000 -20,000 1Q00 3Q00 1Q01 3Q01 1Q02 3Q02 1Q03 3Q03 1Q04 3Q04 1Q05 3Q05 1Q06 3Q06 Source: DOT Form 41 Source: APGDAT 8
Slide 9: Midwest Faces Risks as a Standalone Carrier
Midwest Faces Risks as a Standalone Carrier Fuel prices will likely remain at historic levels Midwest is vulnerable to competitive incursions at Milwaukee A strategy focused on premium pricing is unsustainable Uncertainties related to acquisition of future aircraft 9
Slide 10: Escalated Fuel Cost is a Continuous Threat
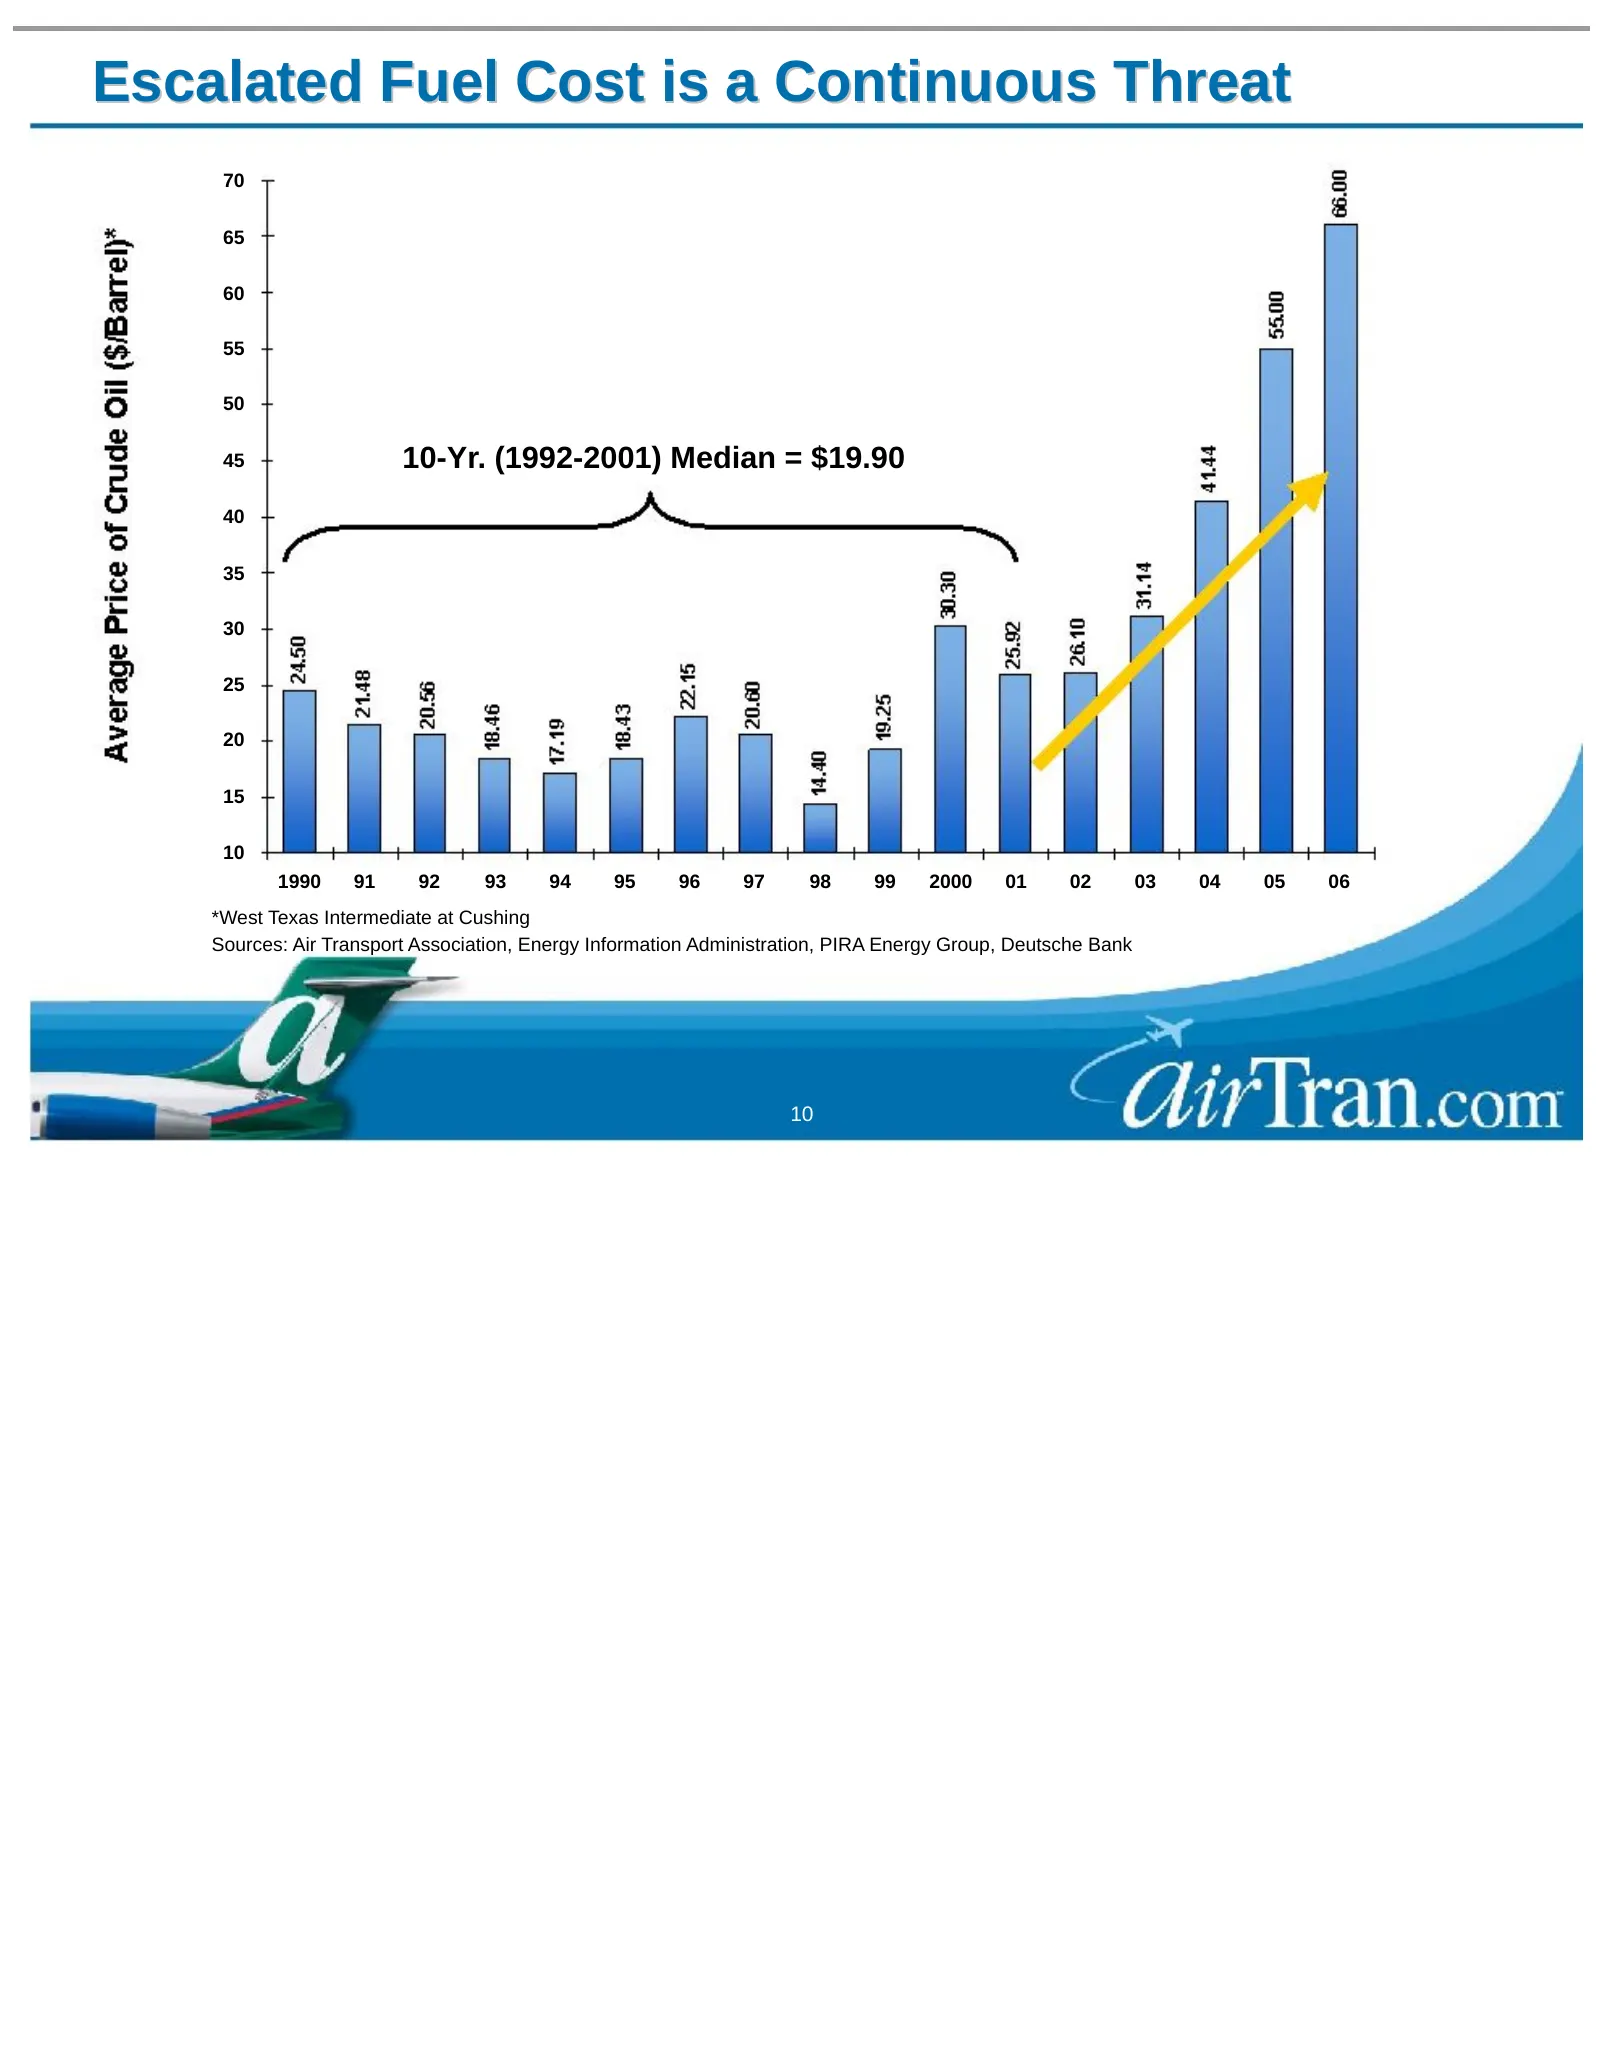
Escalated Fuel Cost is a Continuous Threat 70 65 60 55 50 45 10-Yr. (1992-2001) Median = $19.90 40 35 30 25 20 15 10 1990 91 92 93 94 95 96 97 98 99 2000 01 02 03 04 05 06 *West Texas Intermediate at Cushing Sources: Air Transport Association, Energy Information Administration, PIRA Energy Group, De
Slide 11: Midwest Revenue is Concentrated
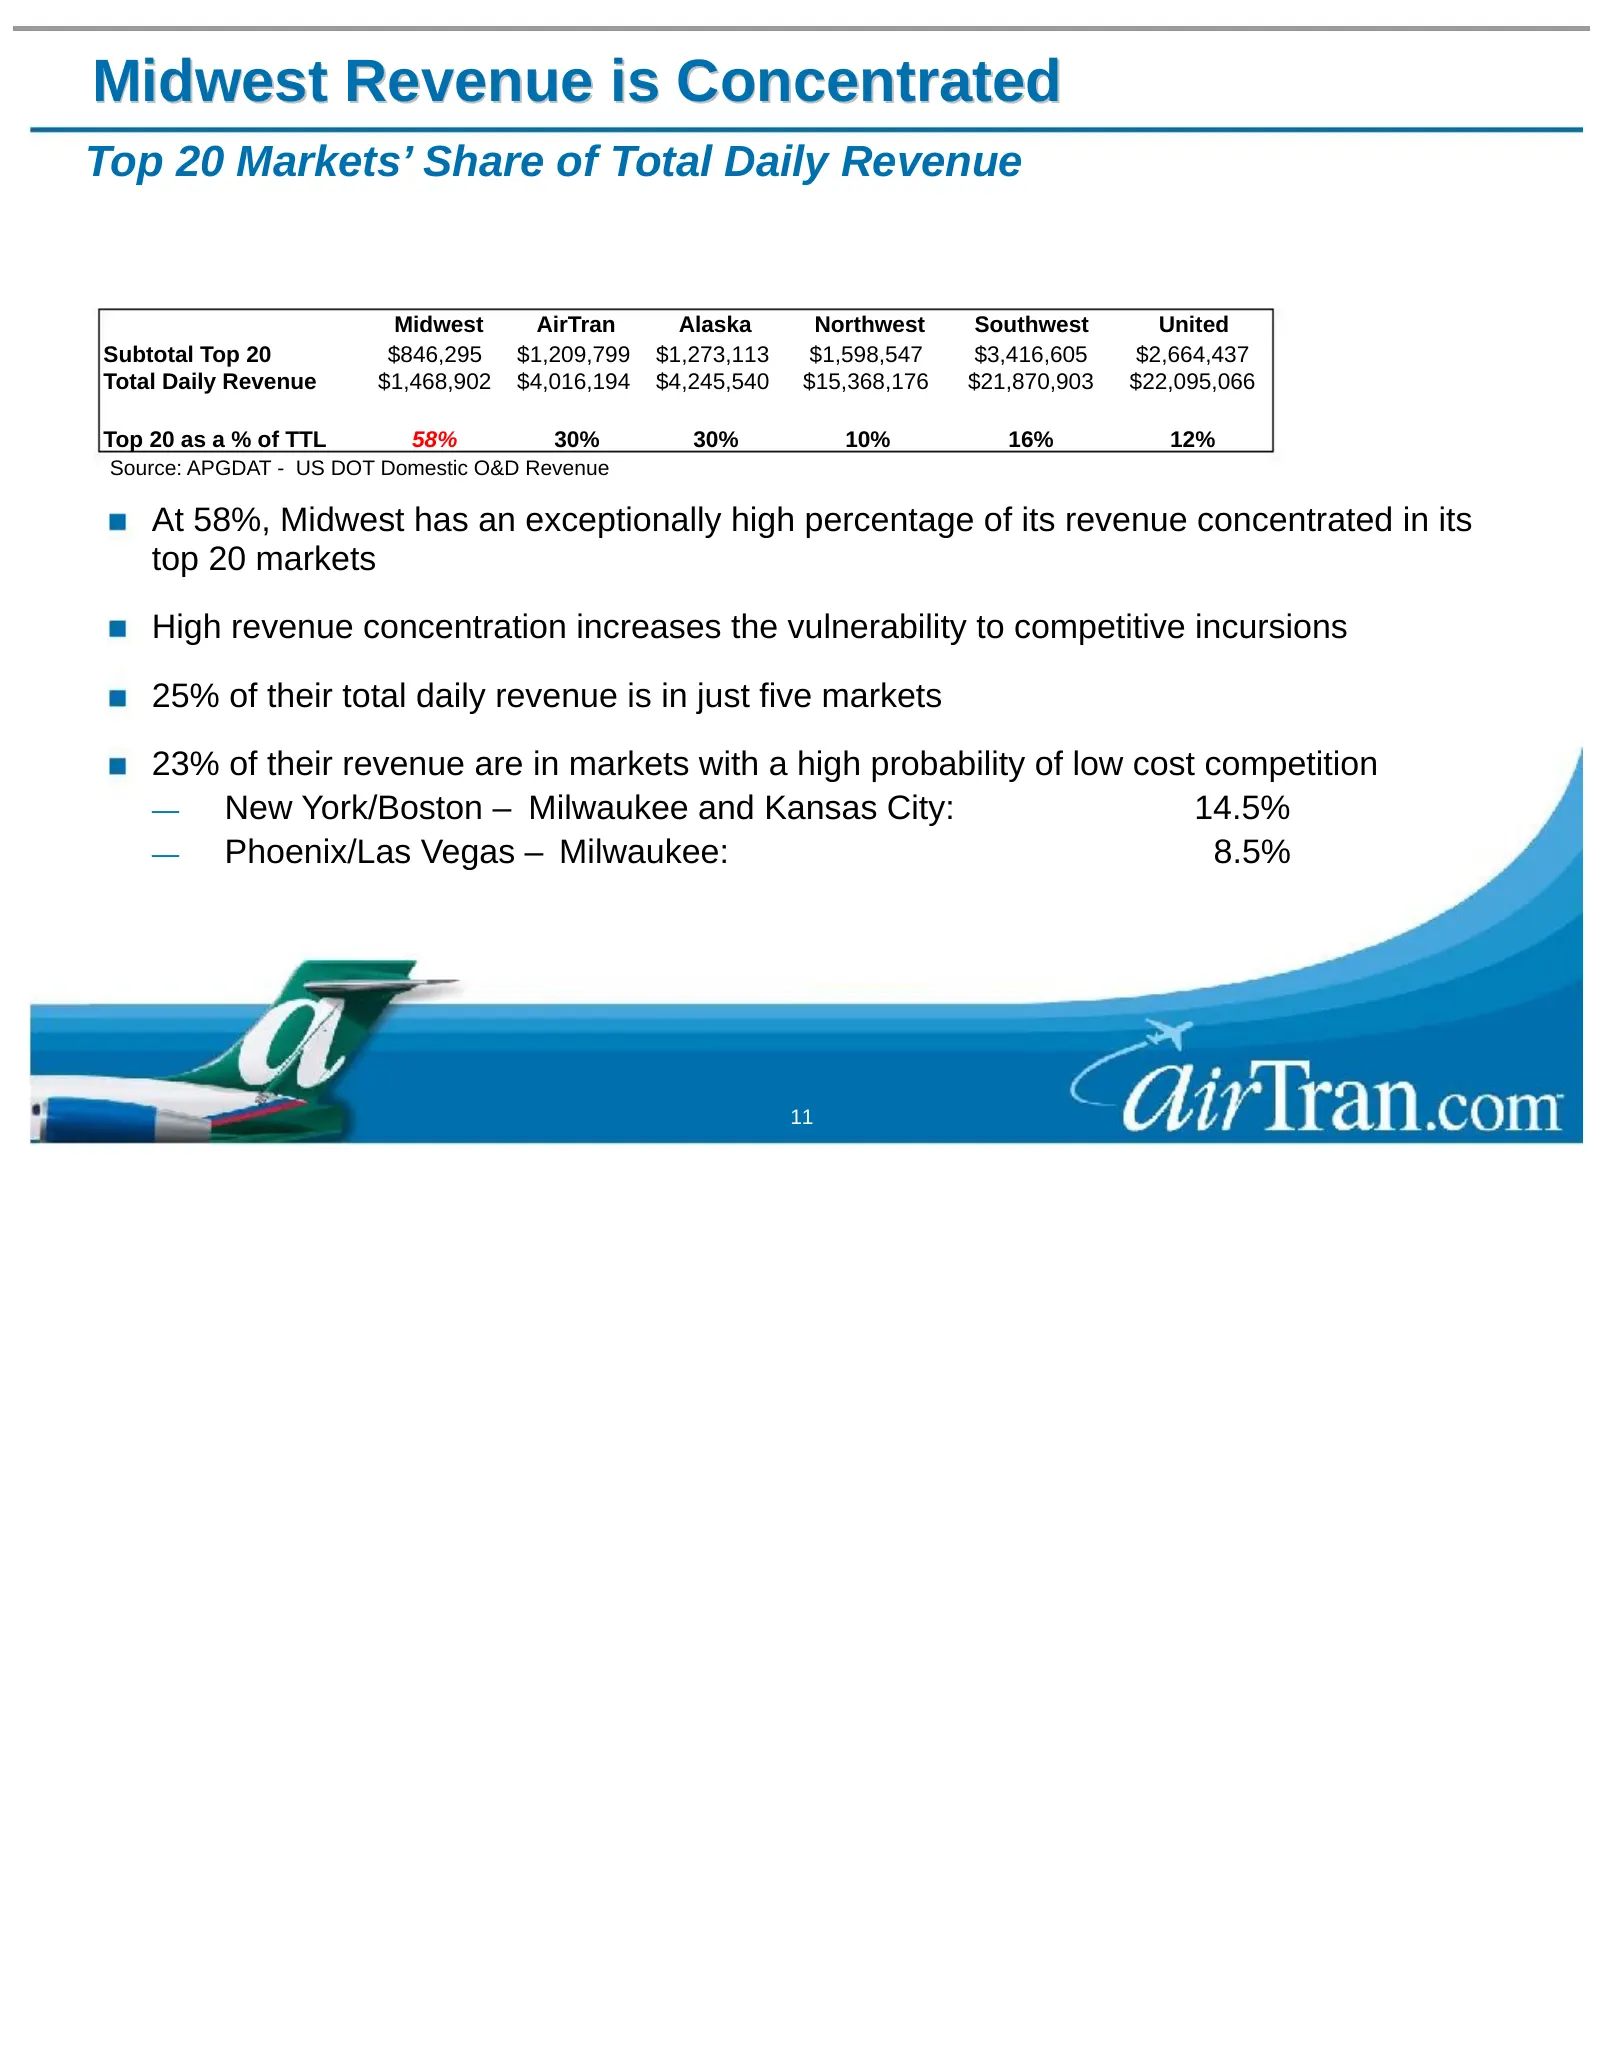
Midwest Revenue is Concentrated Top 20 Markets’ Share of Total Daily Revenue Midwest AirTran Alaska Northwest Southwest United Subtotal Top 20 $846,295 $1,209,799 $1,273,113 $1,598,547 $3,416,605 $2,664,437 Total Daily Revenue $1,468,902 $4,016,194 $4,245,540 $15,368,176 $21,870,903 $22,095,066 Top
Slide 12: Midwest Revenue is Highly Susceptible to Competition
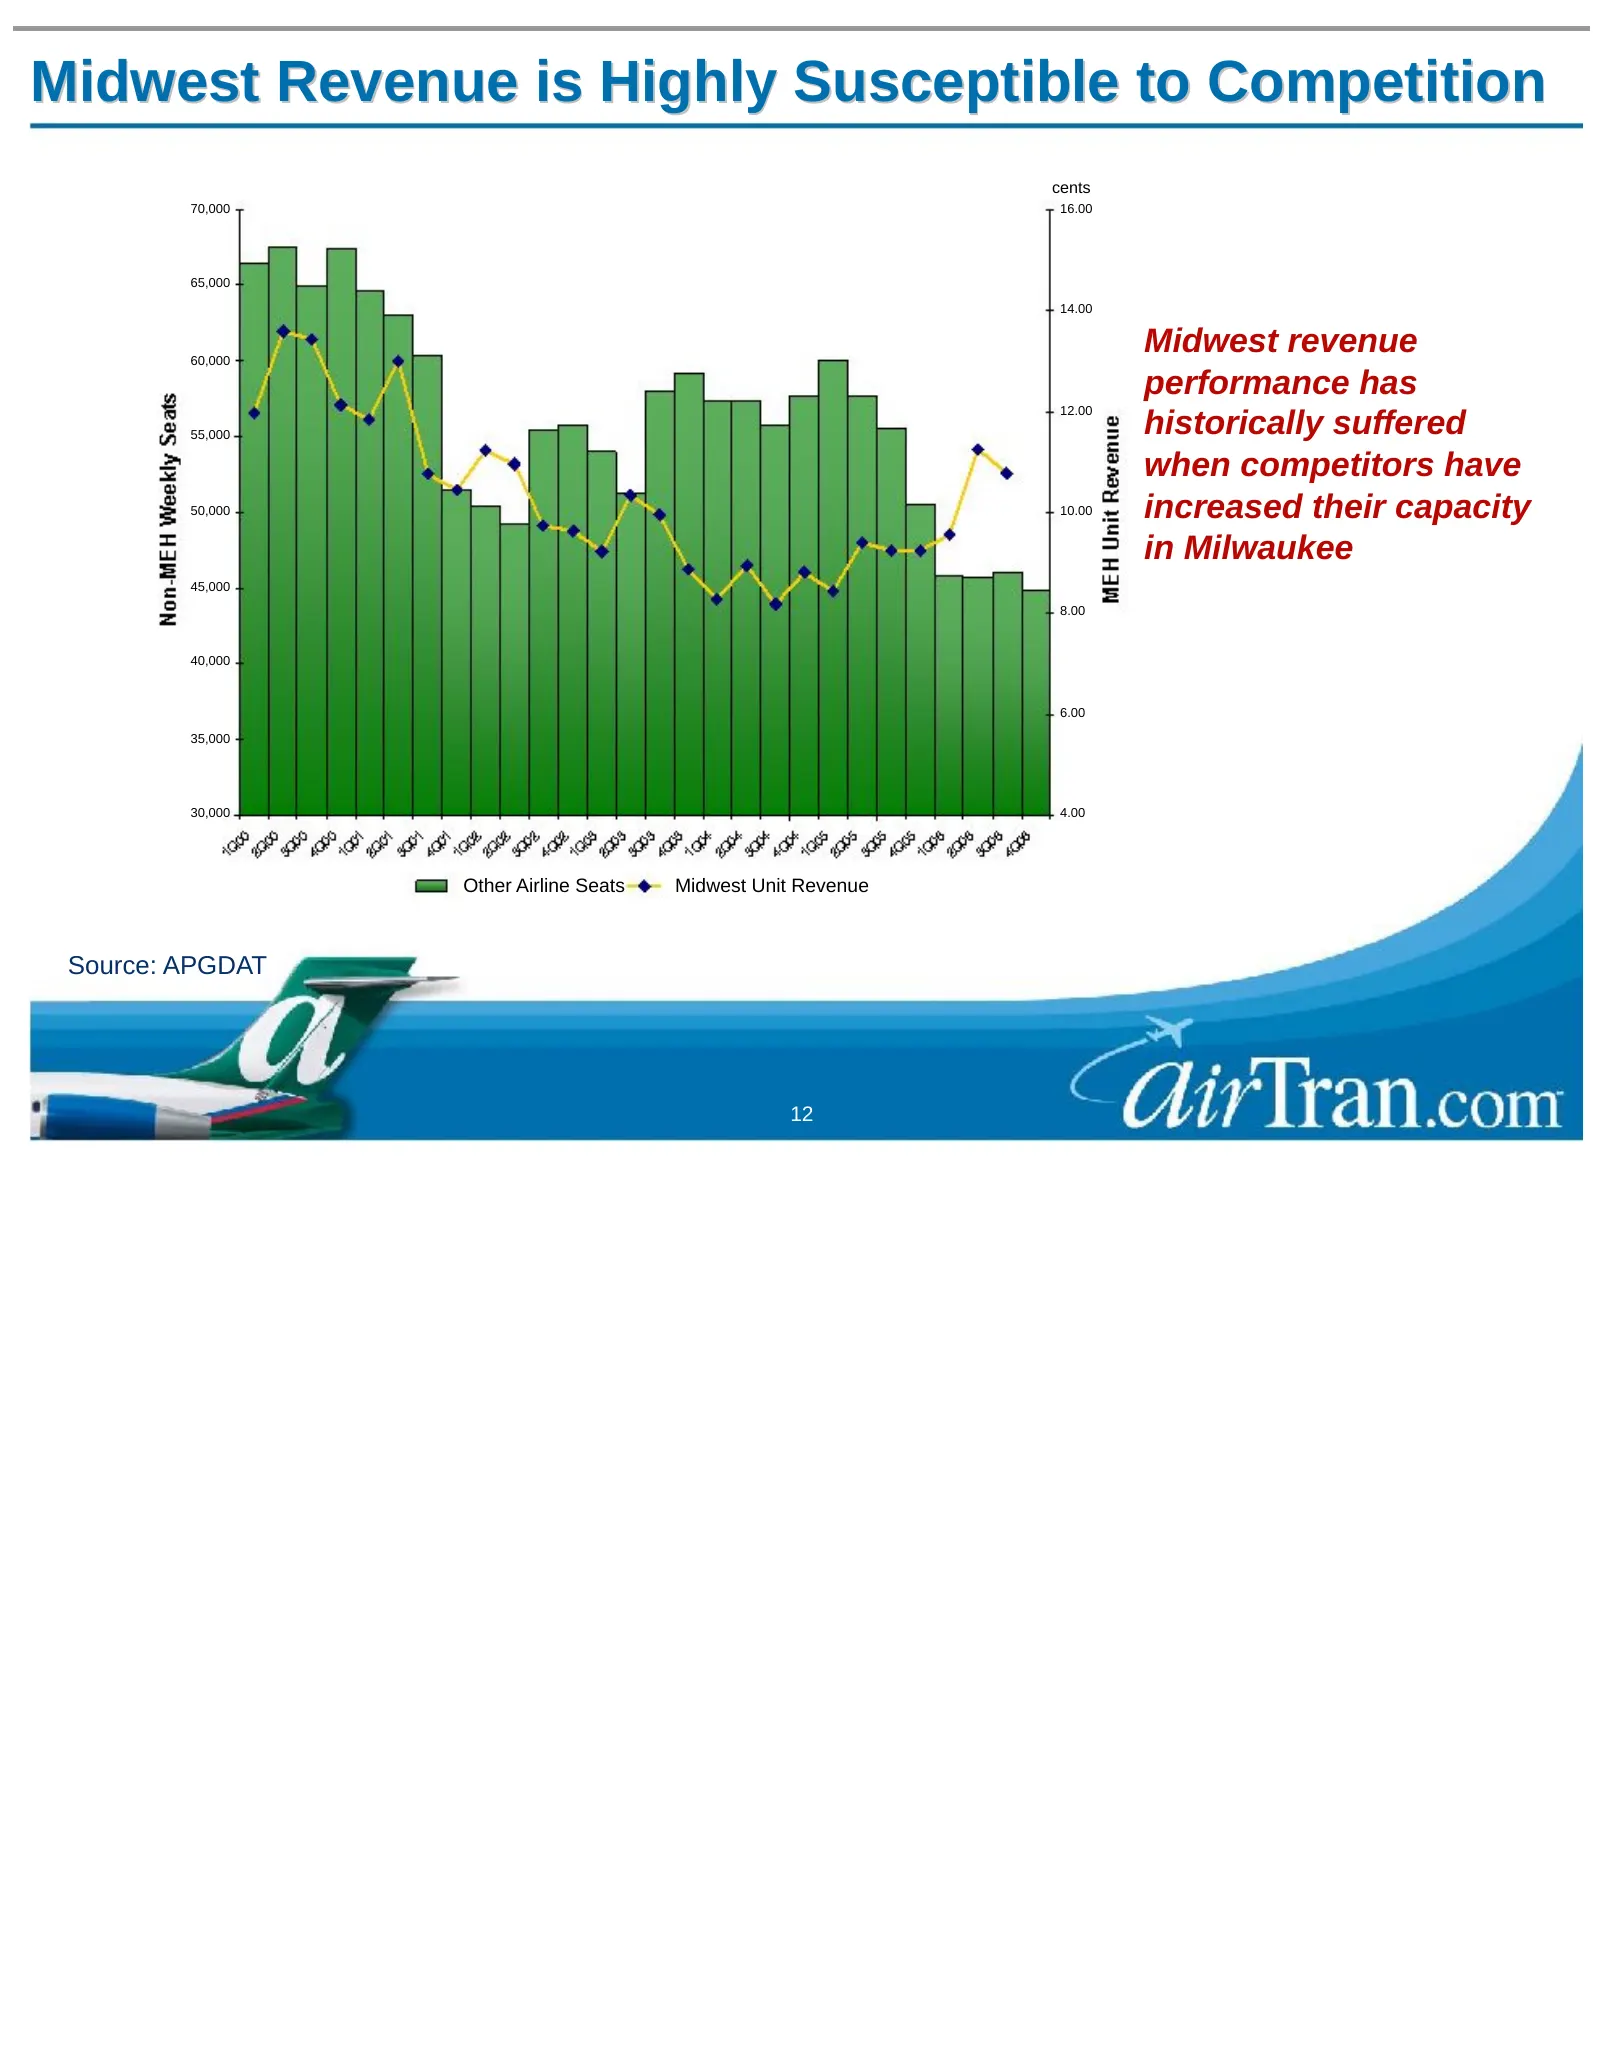
Midwest Revenue is Highly Susceptible to Competition cents 70,000 16.00 65,000 14.00 60,000 Midwest revenue performance has 12.00 55,000 historically suffered when competitors have 50,000 10.00 increased their capacity in Milwaukee 45,000 8.00 40,000 6.00 35,000 30,000 4.00 Other Airline Seats Midwe
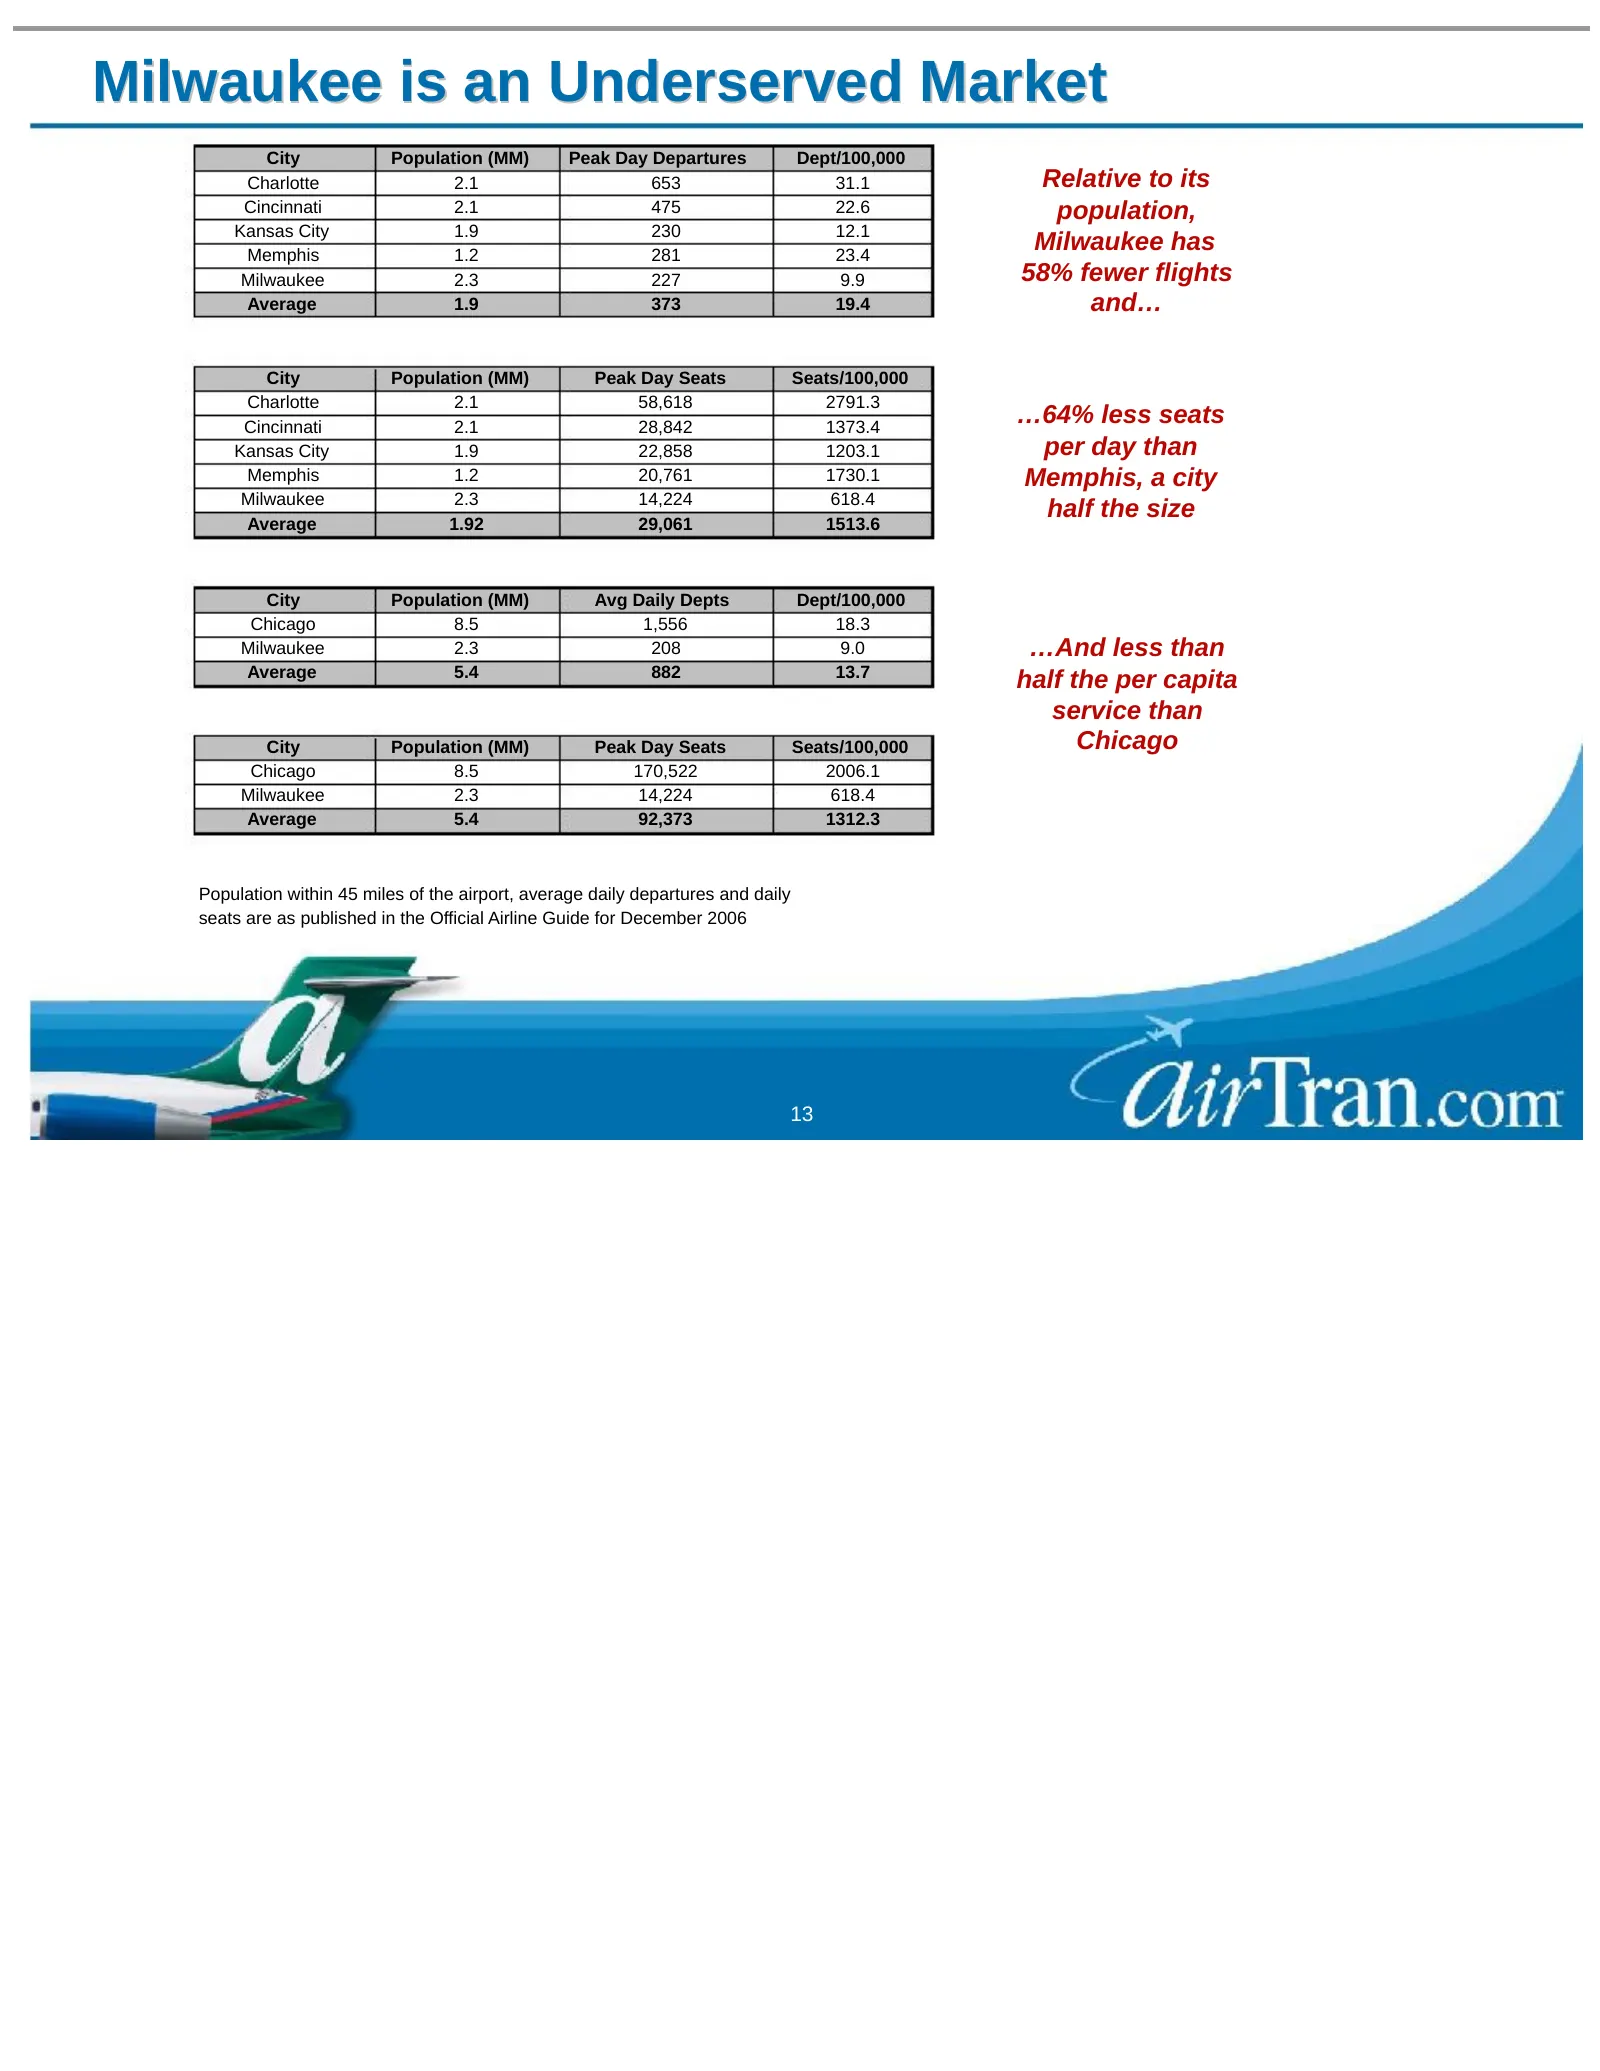
Slide 13: Milwaukee is an Underserved Market
Milwaukee is an Underserved Market City Population (MM) Peak Day Departures Dept/100,000 Charlotte 2.1 653 31.1 Relative to its Cincinnati 2.1 475 22.6 population, Kansas City 1.9 230 12.1 Memphis 1.2 281 23.4 Milwaukee has Milwaukee 2.3 227 9.9 58% fewer flights Average 1.9 373 19.4 and… City Popul
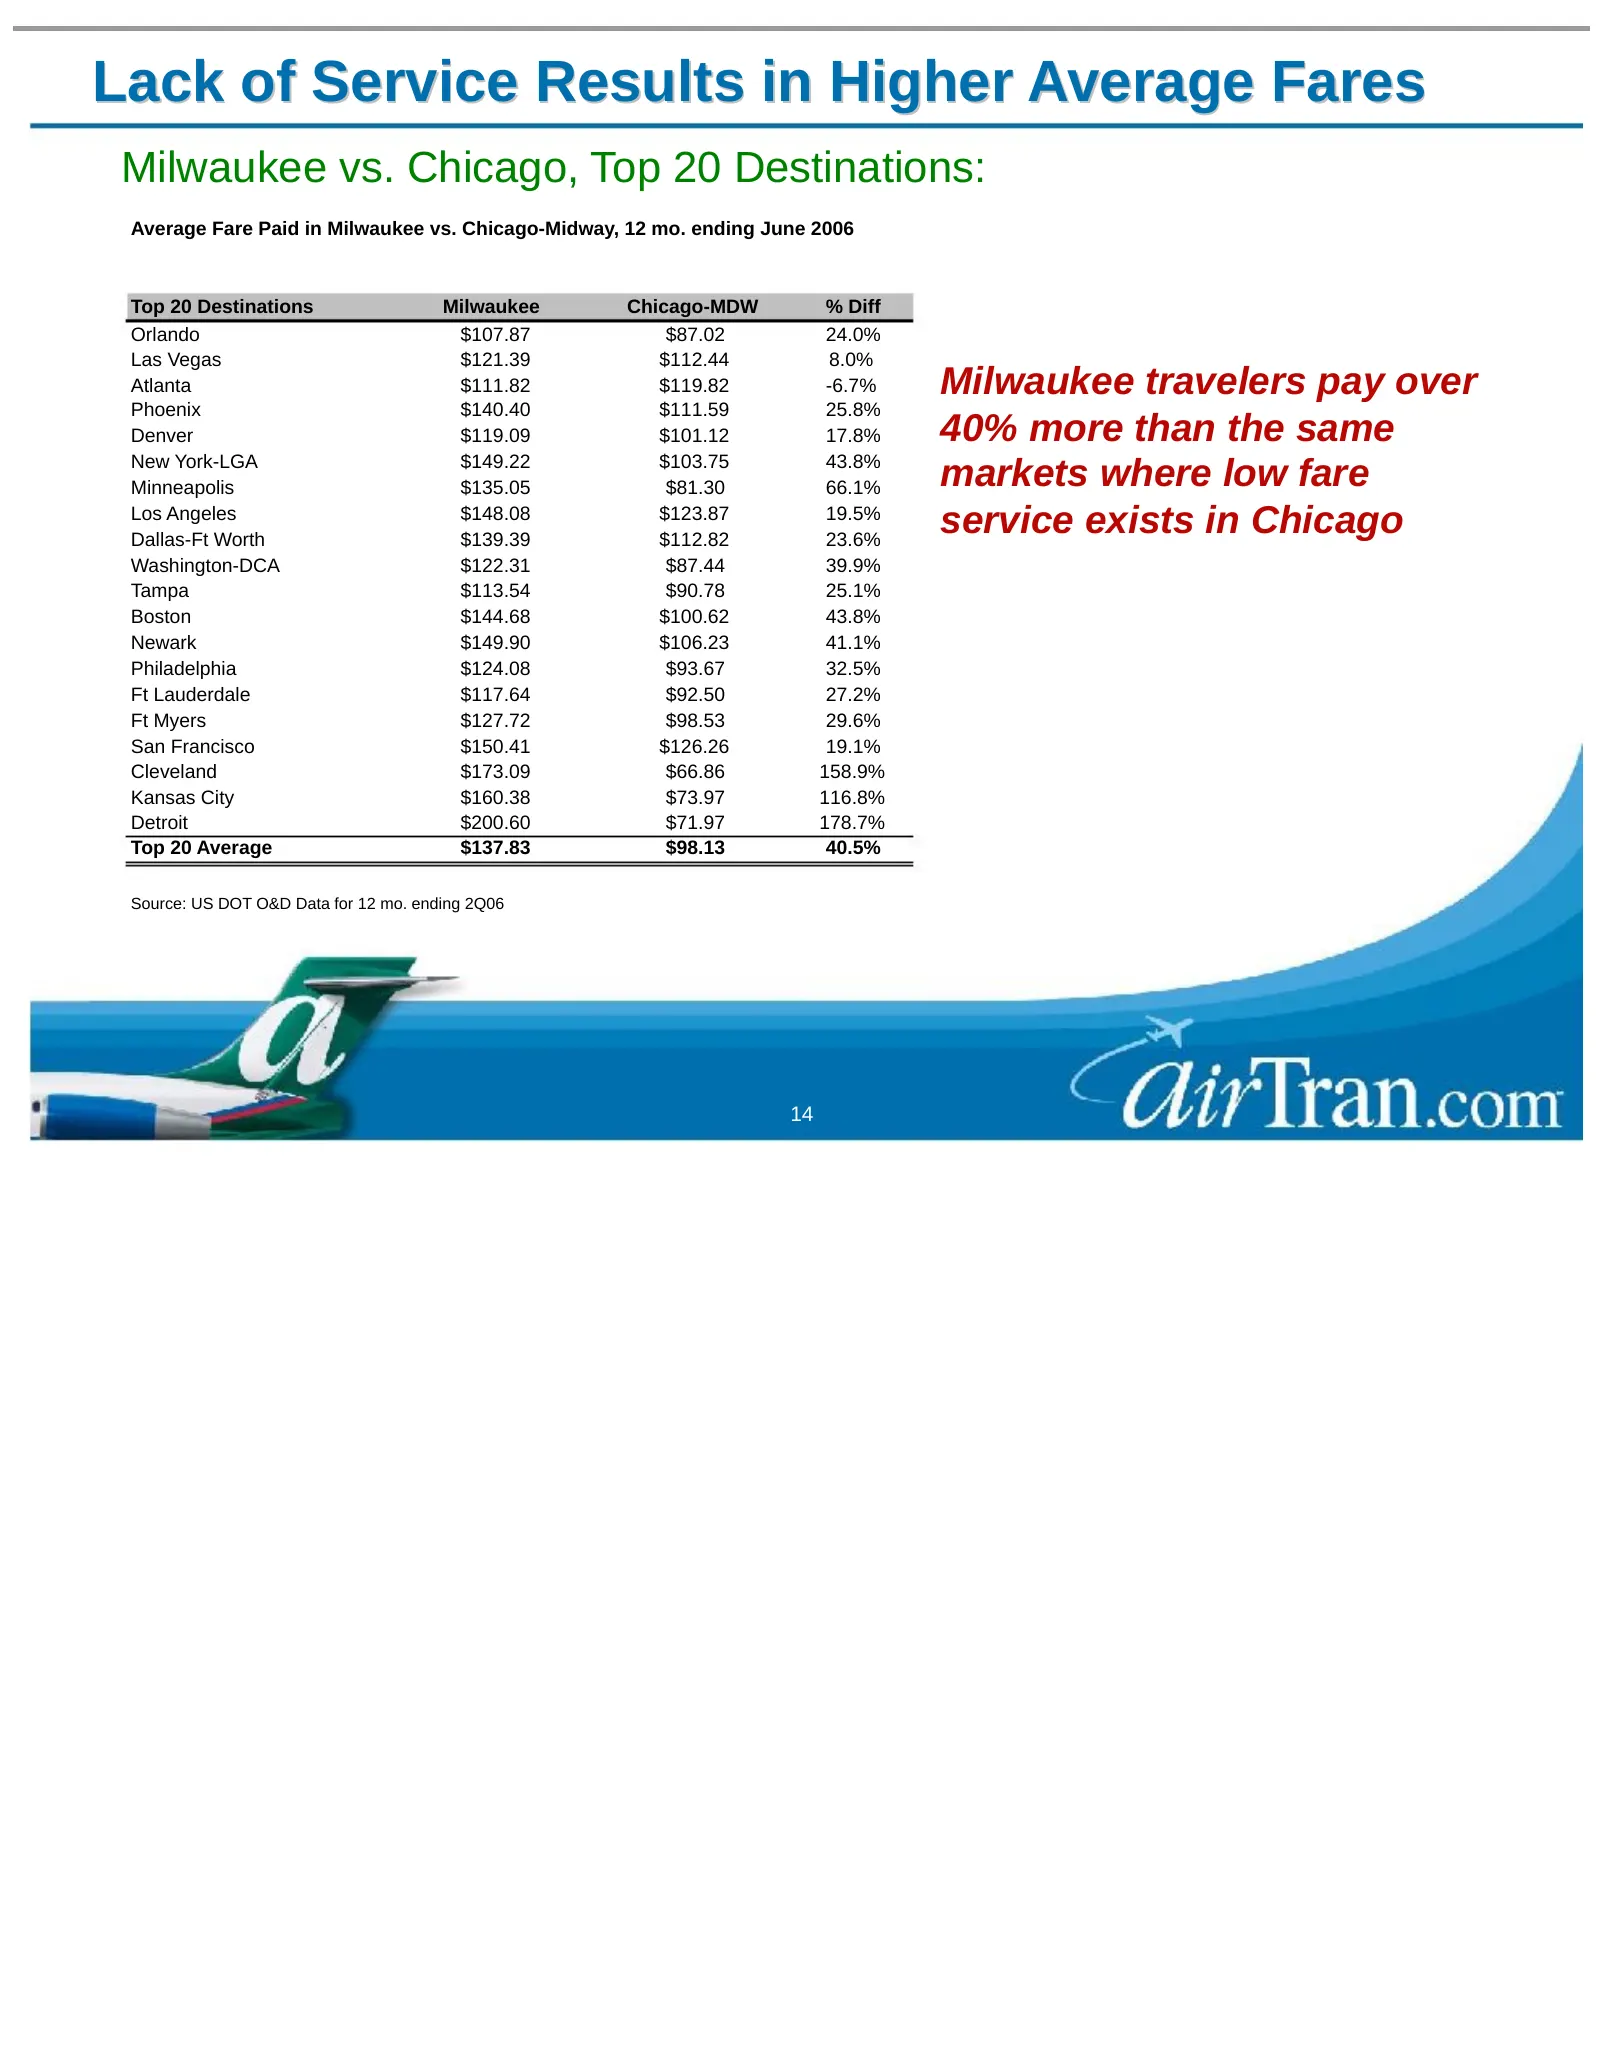
Slide 14: Lack of Service Results in Higher Average Fares
Lack of Service Results in Higher Average Fares Milwaukee vs. Chicago, Top 20 Destinations: Average Fare Paid in Milwaukee vs. Chicago-Midway, 12 mo. ending June 2006 Top 20 Destinations Milwaukee Chicago-MDW % Diff Orlando $107.87 $87.02 24.0% Las Vegas $121.39 $112.44 8.0% Atlanta $111.82 $119.82
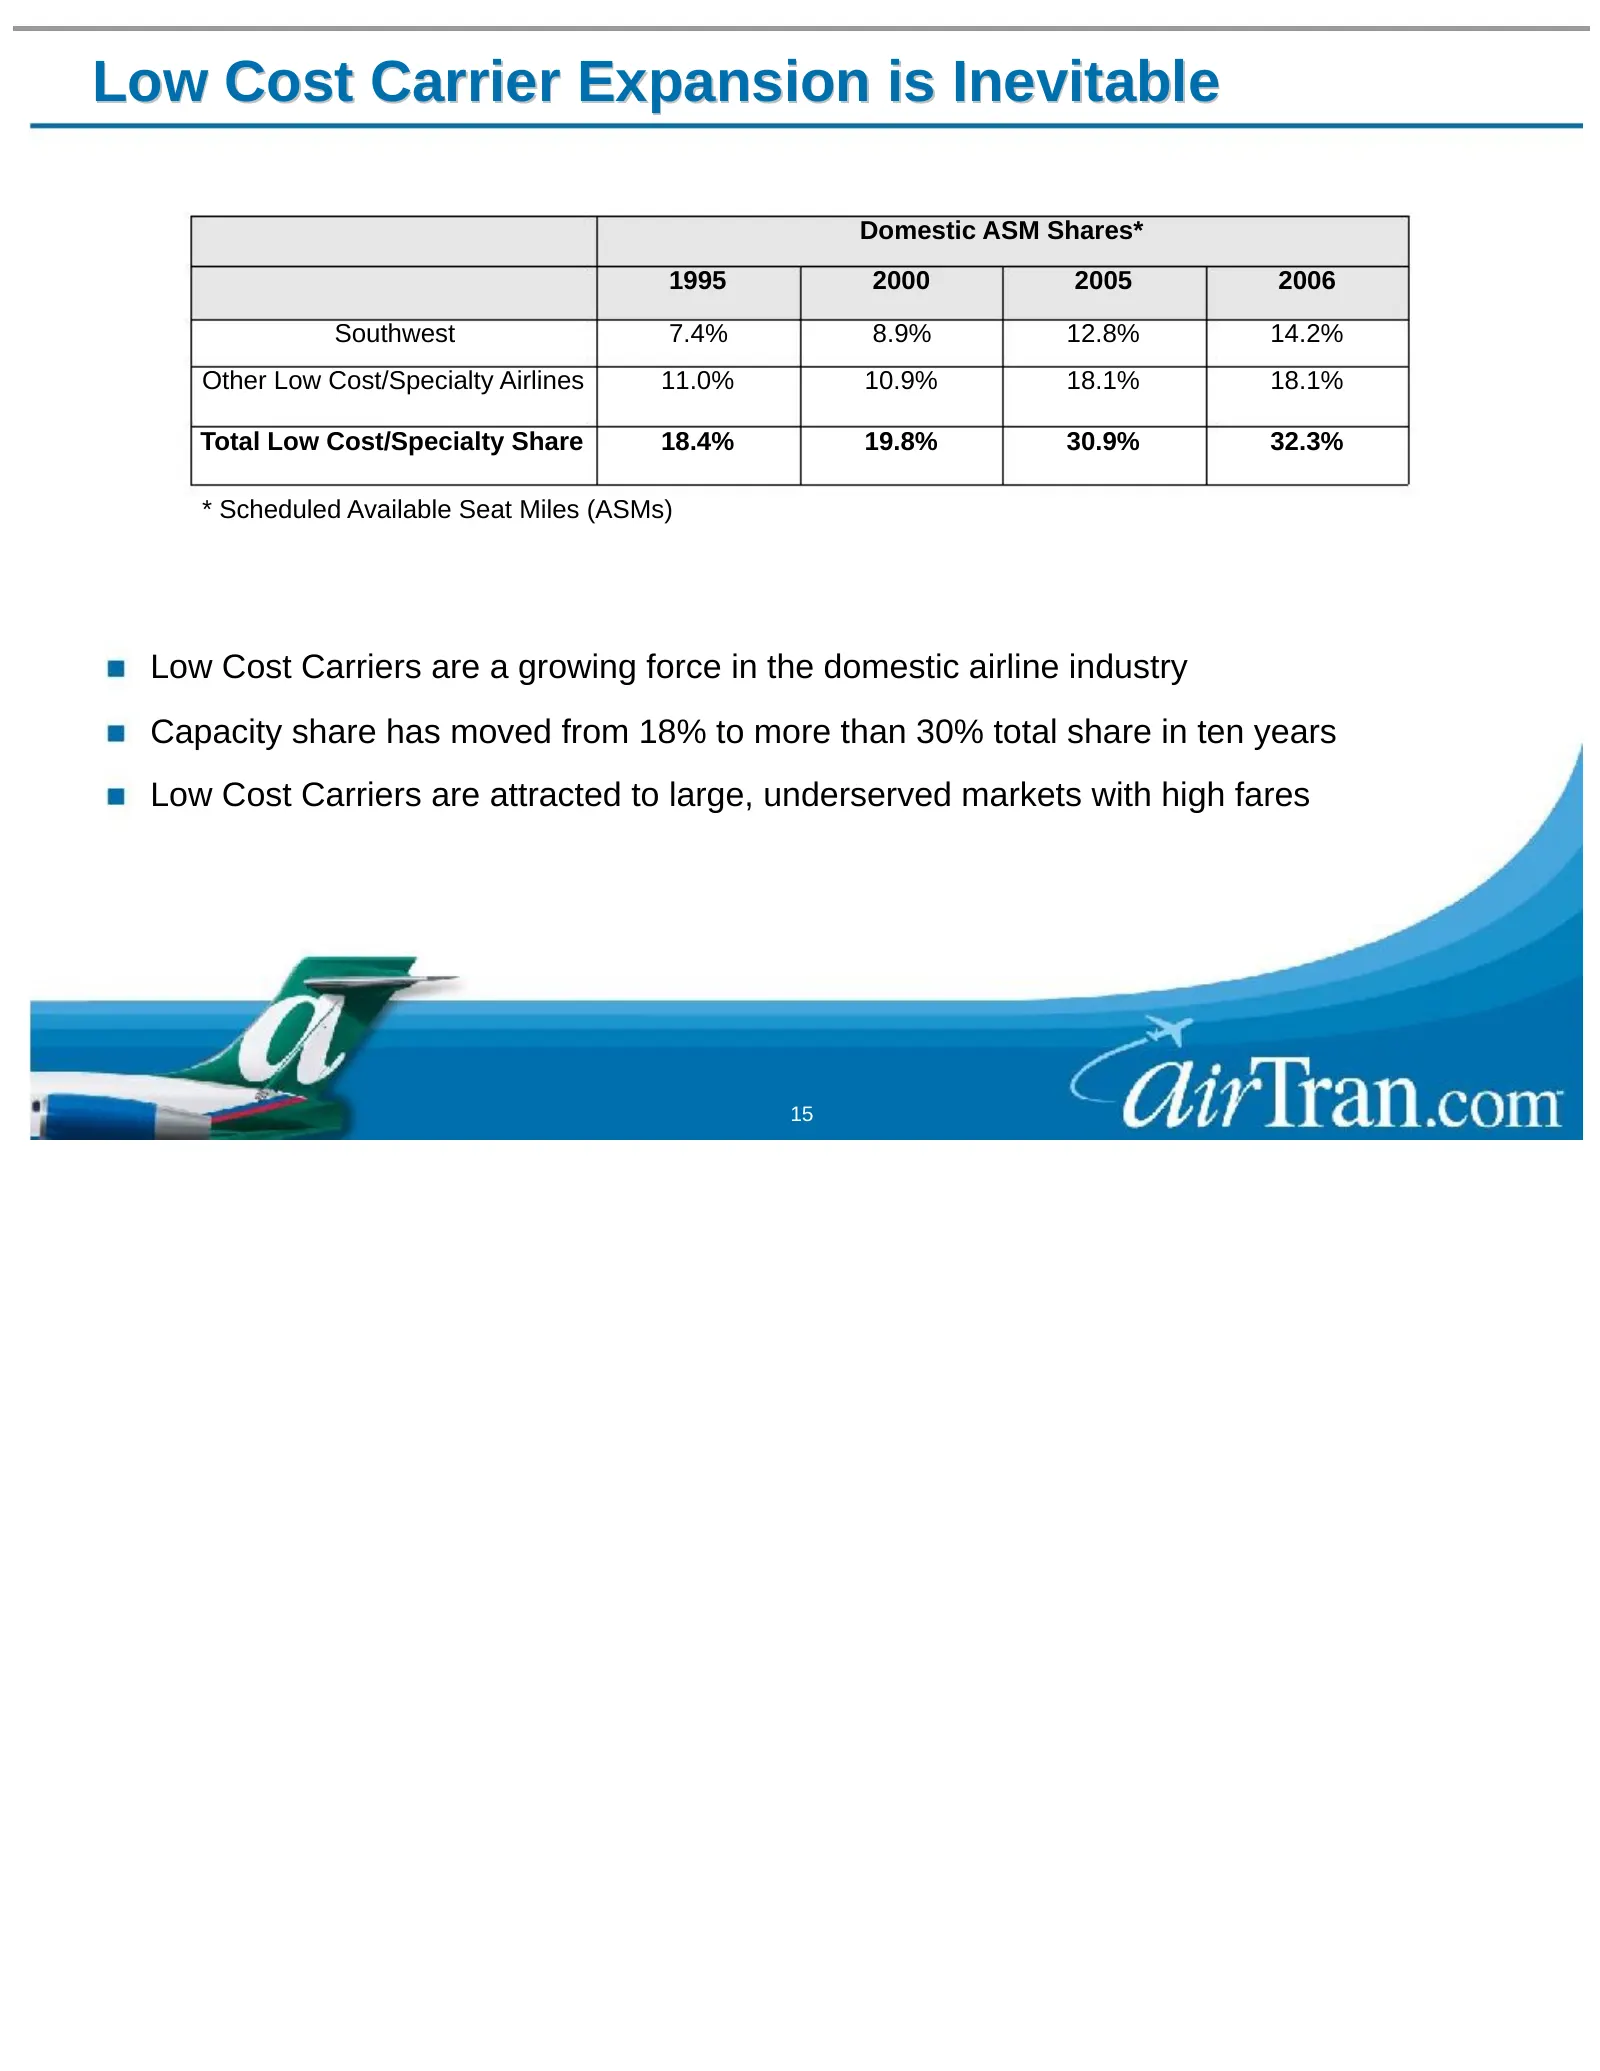
Slide 15: Low Cost Carrier Expansion is Inevitable
Low Cost Carrier Expansion is Inevitable Domestic ASM Shares* 1995 2000 2005 2006 Southwest 7.4% 8.9% 12.8% 14.2% Other Low Cost/Specialty Airlines 11.0% 10.9% 18.1% 18.1% Total Low Cost/Specialty Share 18.4% 19.8% 30.9% 32.3% * Scheduled Available Seat Miles (ASMs) Low Cost Carriers are a growing f
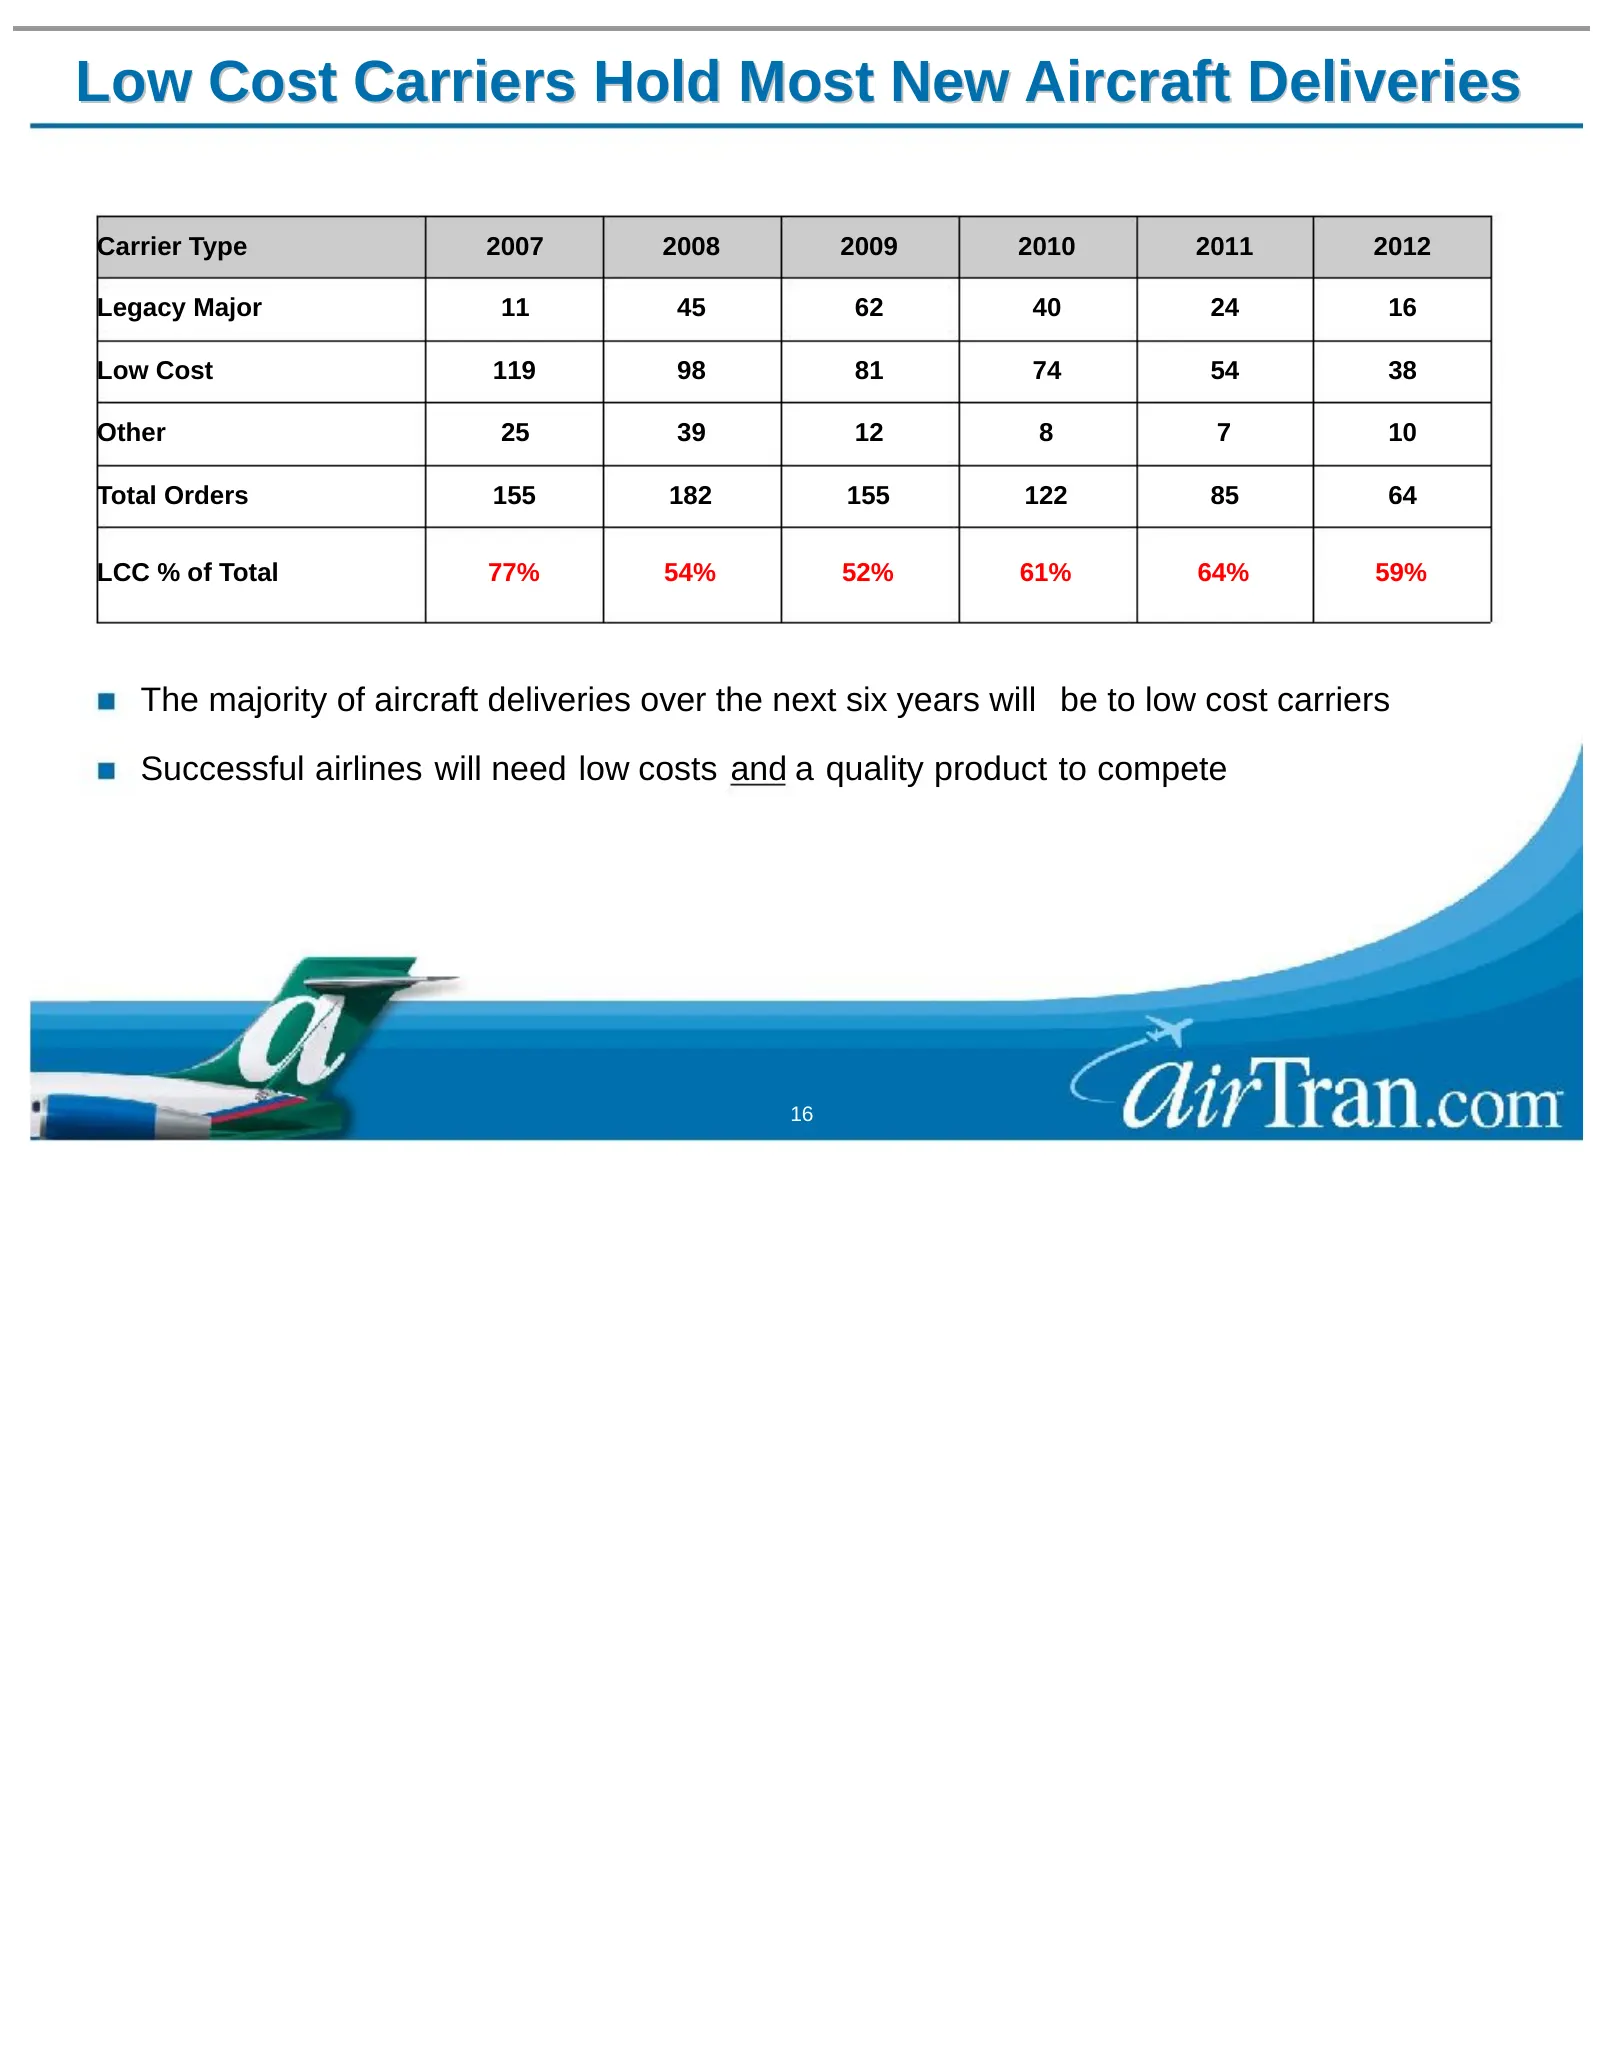
Slide 16: Low Cost Carriers Hold Most New Aircraft Deliveries
Low Cost Carriers Hold Most New Aircraft Deliveries Carrier Type 2007 2008 2009 2010 2011 2012 Legacy Major 11 45 62 40 24 16 Low Cost 119 98 81 74 54 38 Other 25 39 12 8 7 10 Total Orders 155 182 155 122 85 64 LCC % of Total 77% 54% 52% 61% 64% 59% The majority of aircraft deliveries over the next
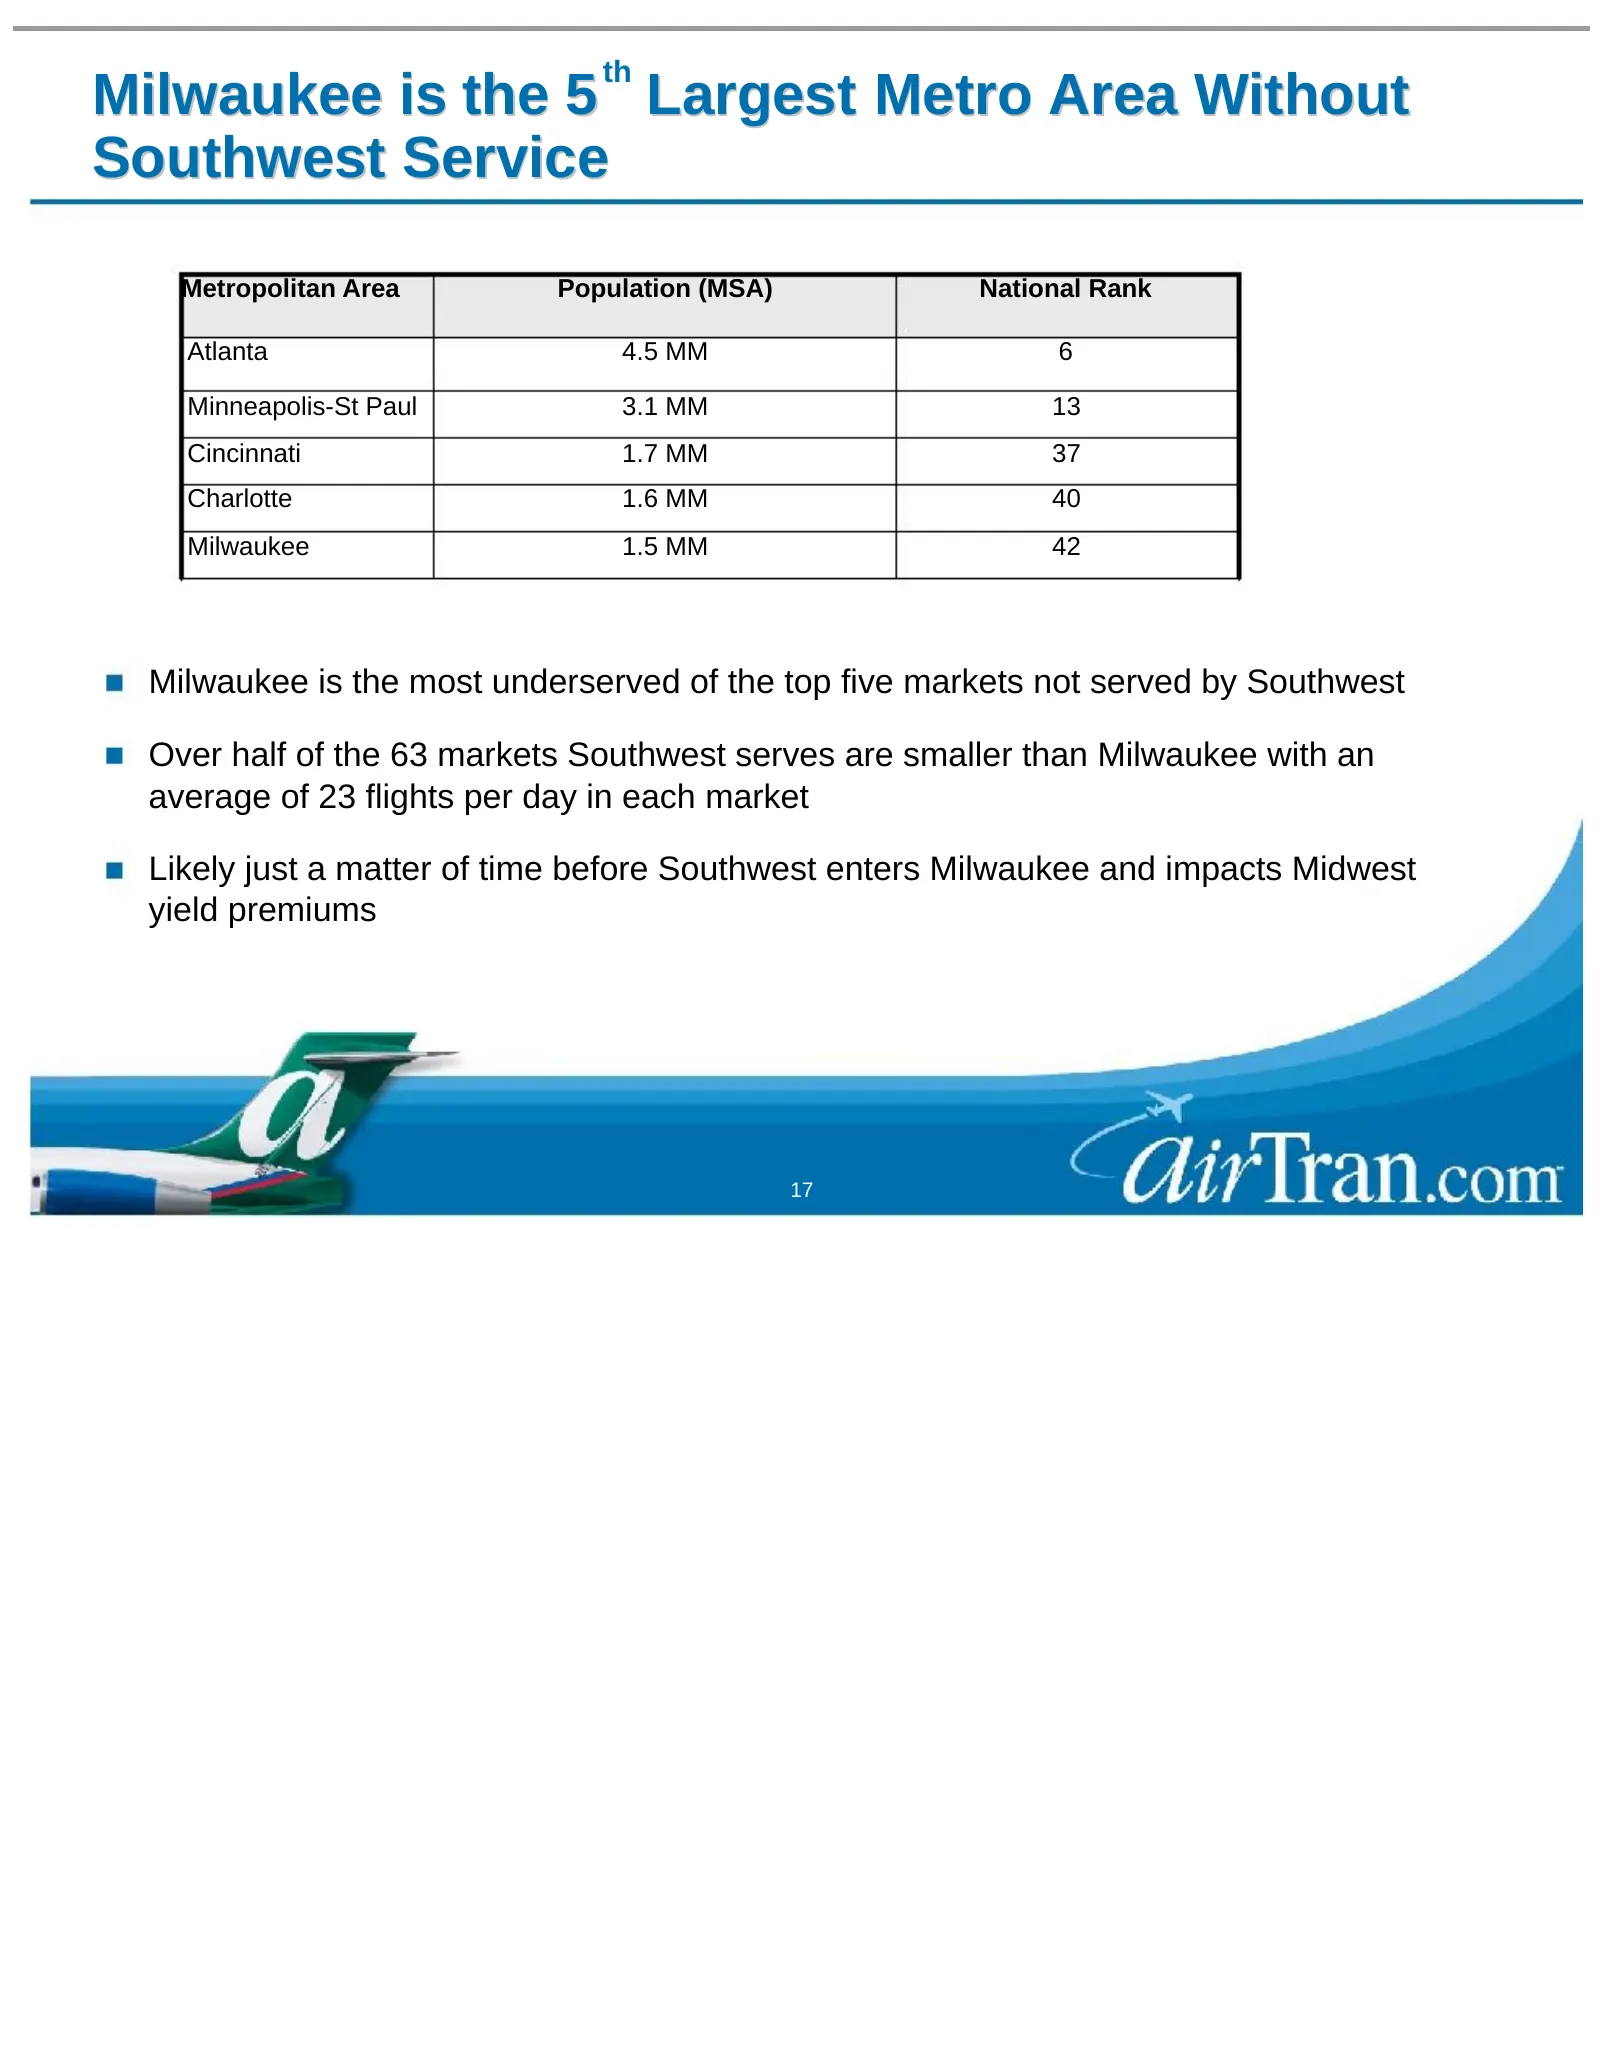
Slide 17: Milwaukee is the Largest Metro Area Without Southwest Service
th Milwaukee is the 5 Largest Metro Area Without Southwest Service Metropolitan Area Population (MSA) National Rank Atlanta 4.5 MM 6 Minneapolis-St Paul 3.1 MM 13 Cincinnati 1.7 MM 37 Charlotte 1.6 MM 40 Milwaukee 1.5 MM 42 Milwaukee is the most underserved of the top five markets not served by Sout
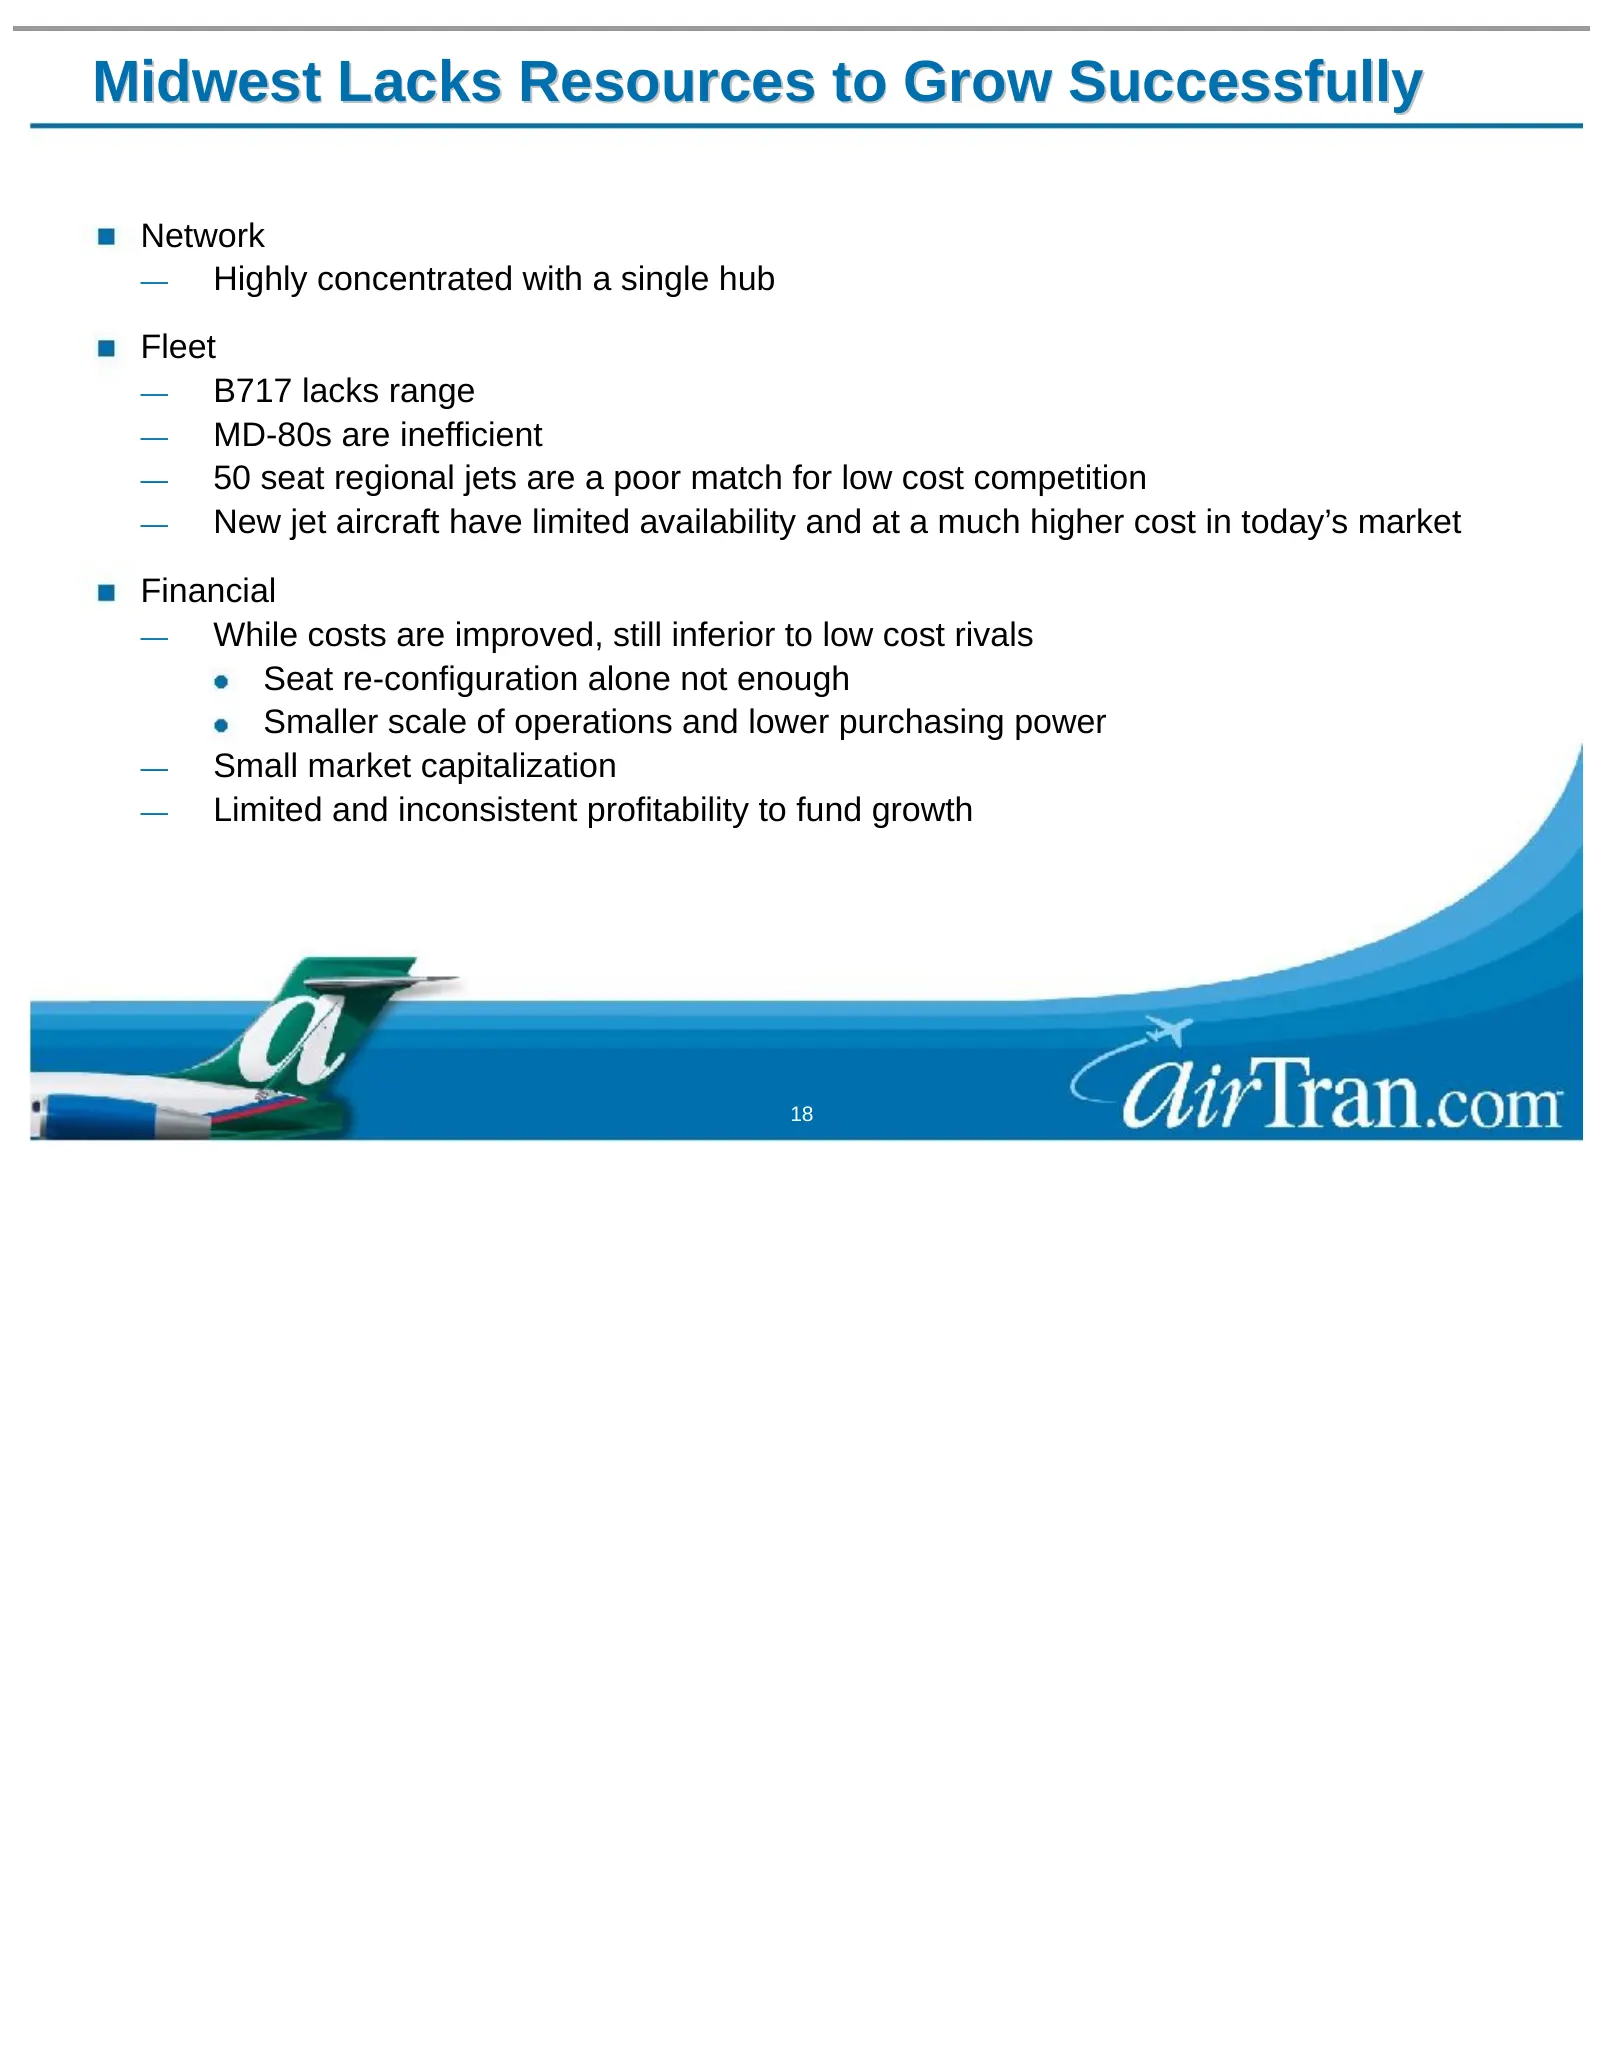
Slide 18: Midwest Lacks Resources to Grow Successfully
Midwest Lacks Resources to Grow Successfully Network — Highly concentrated with a single hub Fleet — B717 lacks range — MD-80s are inefficient — 50 seat regional jets are a poor match for low cost competition — New jet aircraft have limited availability and at a much higher cost in today’s market Fi
Slide 19: Combining Strengths
Combining Strengths Clirlran.com
Slide 20: AirTran and Midwest Can Accomplish More Together Than Either Can Independently
AirTran and Midwest Can Accomplish More Together Than Either Can Independently Combined airline will create a stronger and more flexible competitor — Upper Midwest hub complements AirTran’s east coast presence — Combined network strengthens position in key markets — Amid industry consolidation, scal
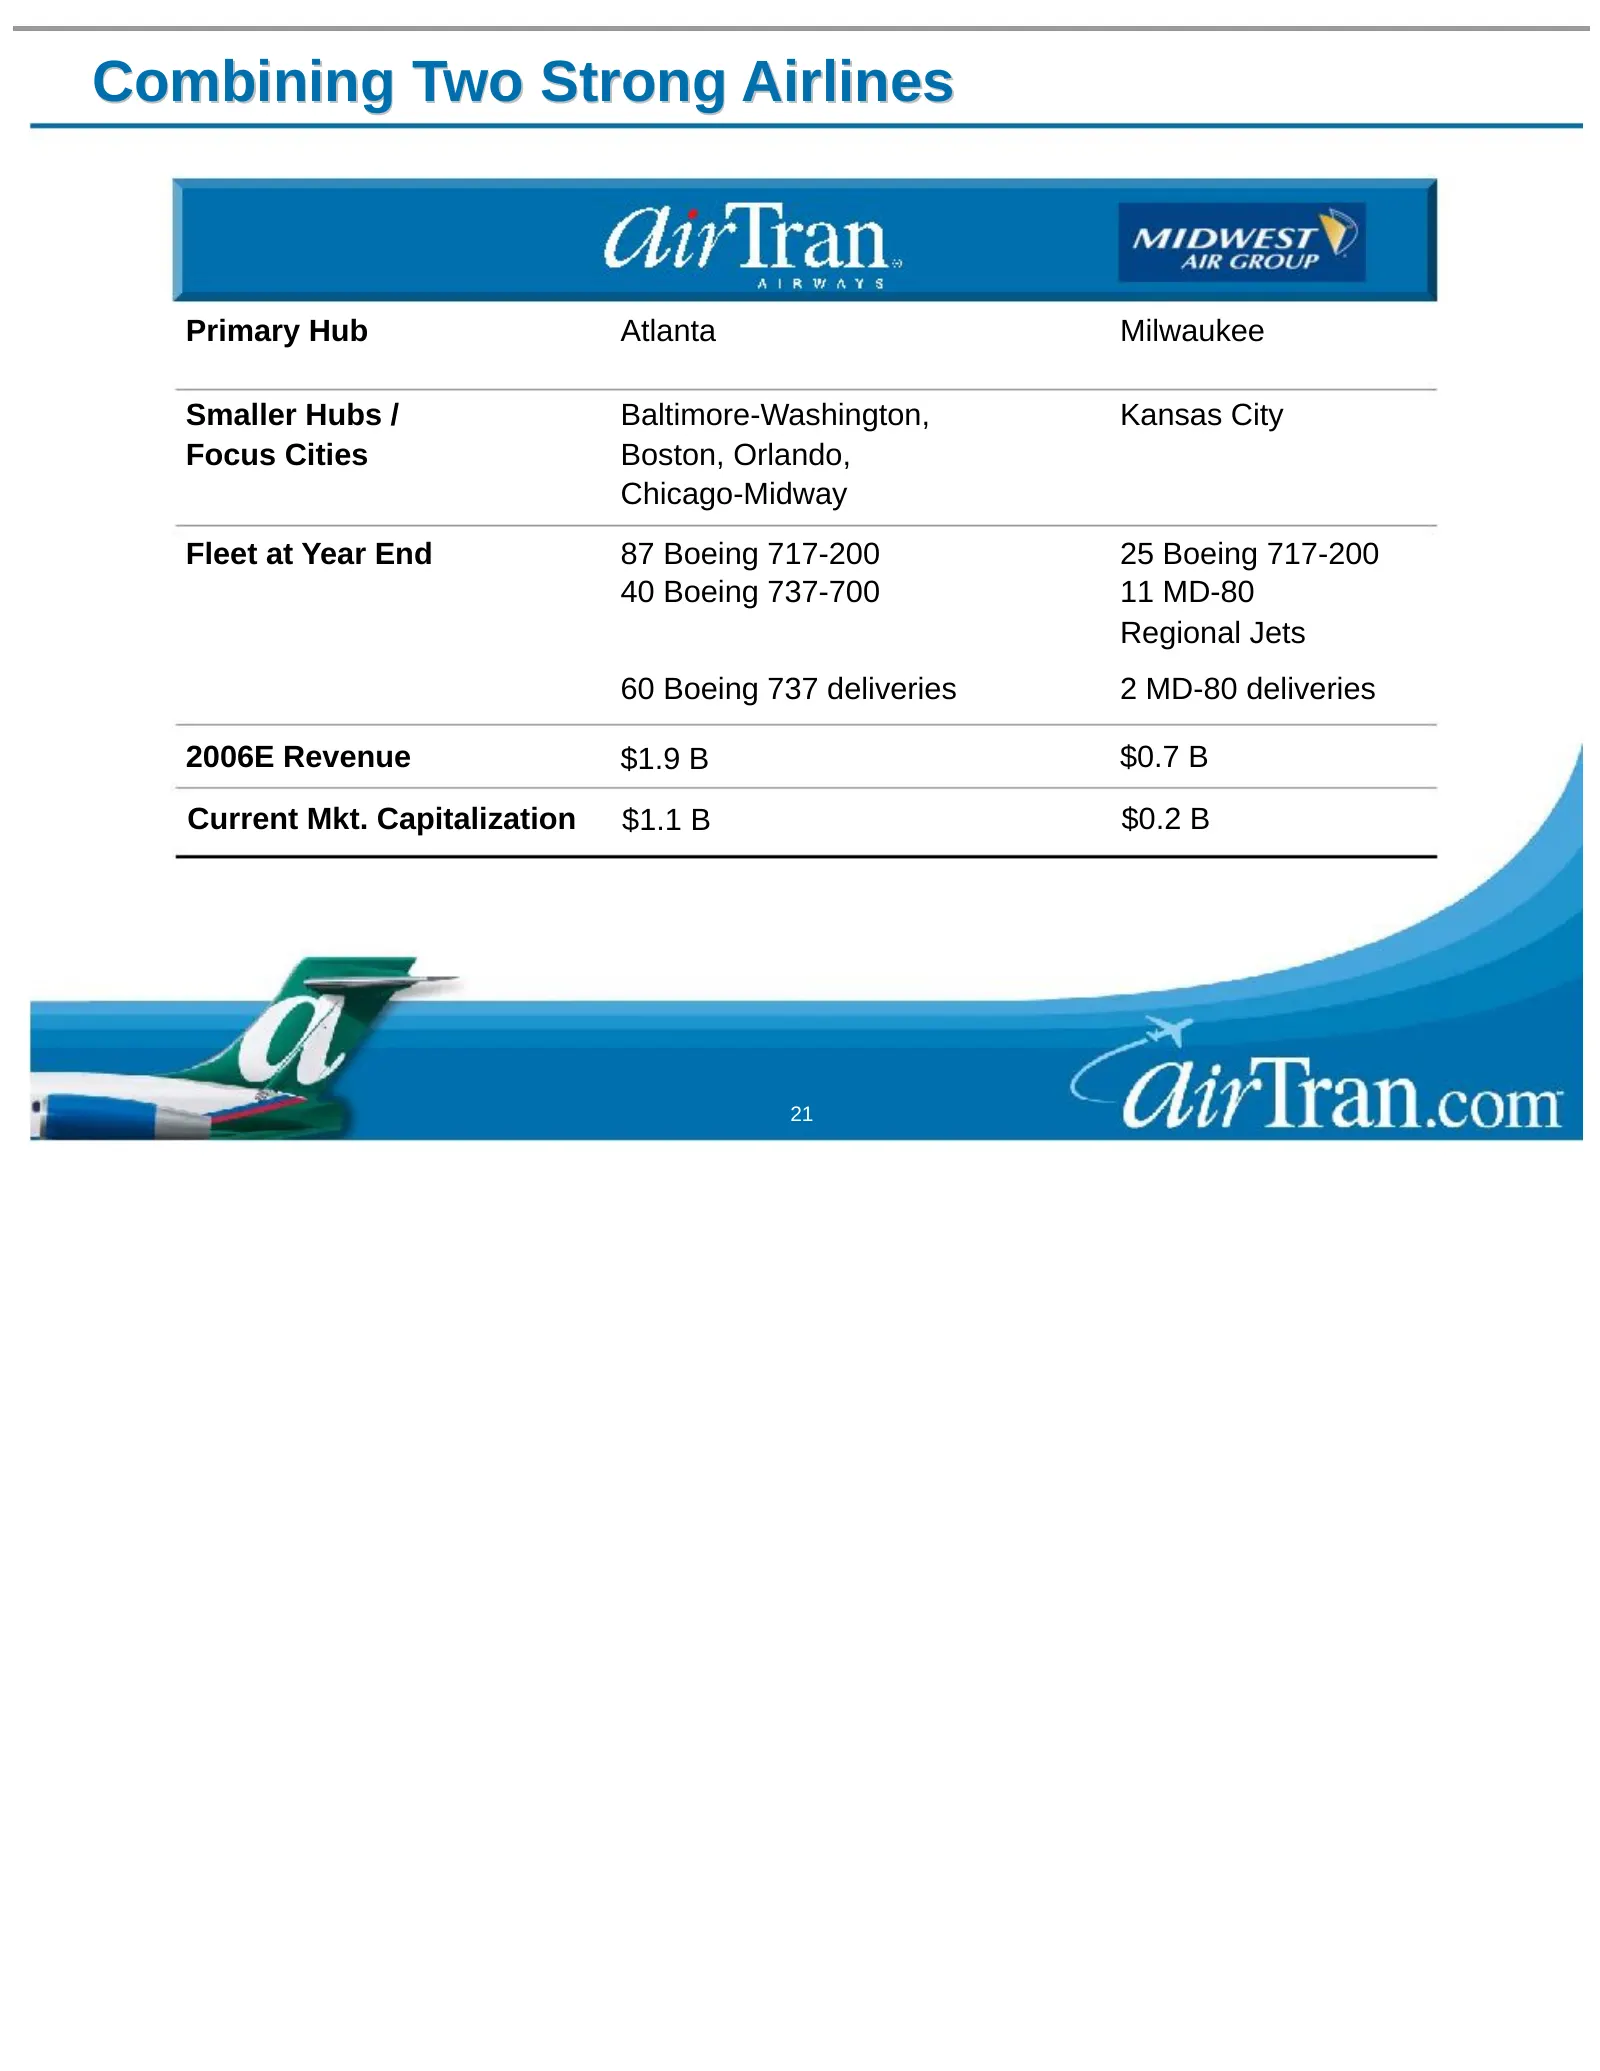
Slide 21: Combining Two Strong Airlines
Combining Two Strong Airlines Primary Hub Atlanta Milwaukee Smaller Hubs / Baltimore-Washington, Kansas City Focus Cities Boston, Orlando, Chicago-Midway Fleet at Year End 87 Boeing 717-200 25 Boeing 717-200 40 Boeing 737-700 11 MD-80 Regional Jets 60 Boeing 737 deliveries 2 MD-80 deliveries 2006E R
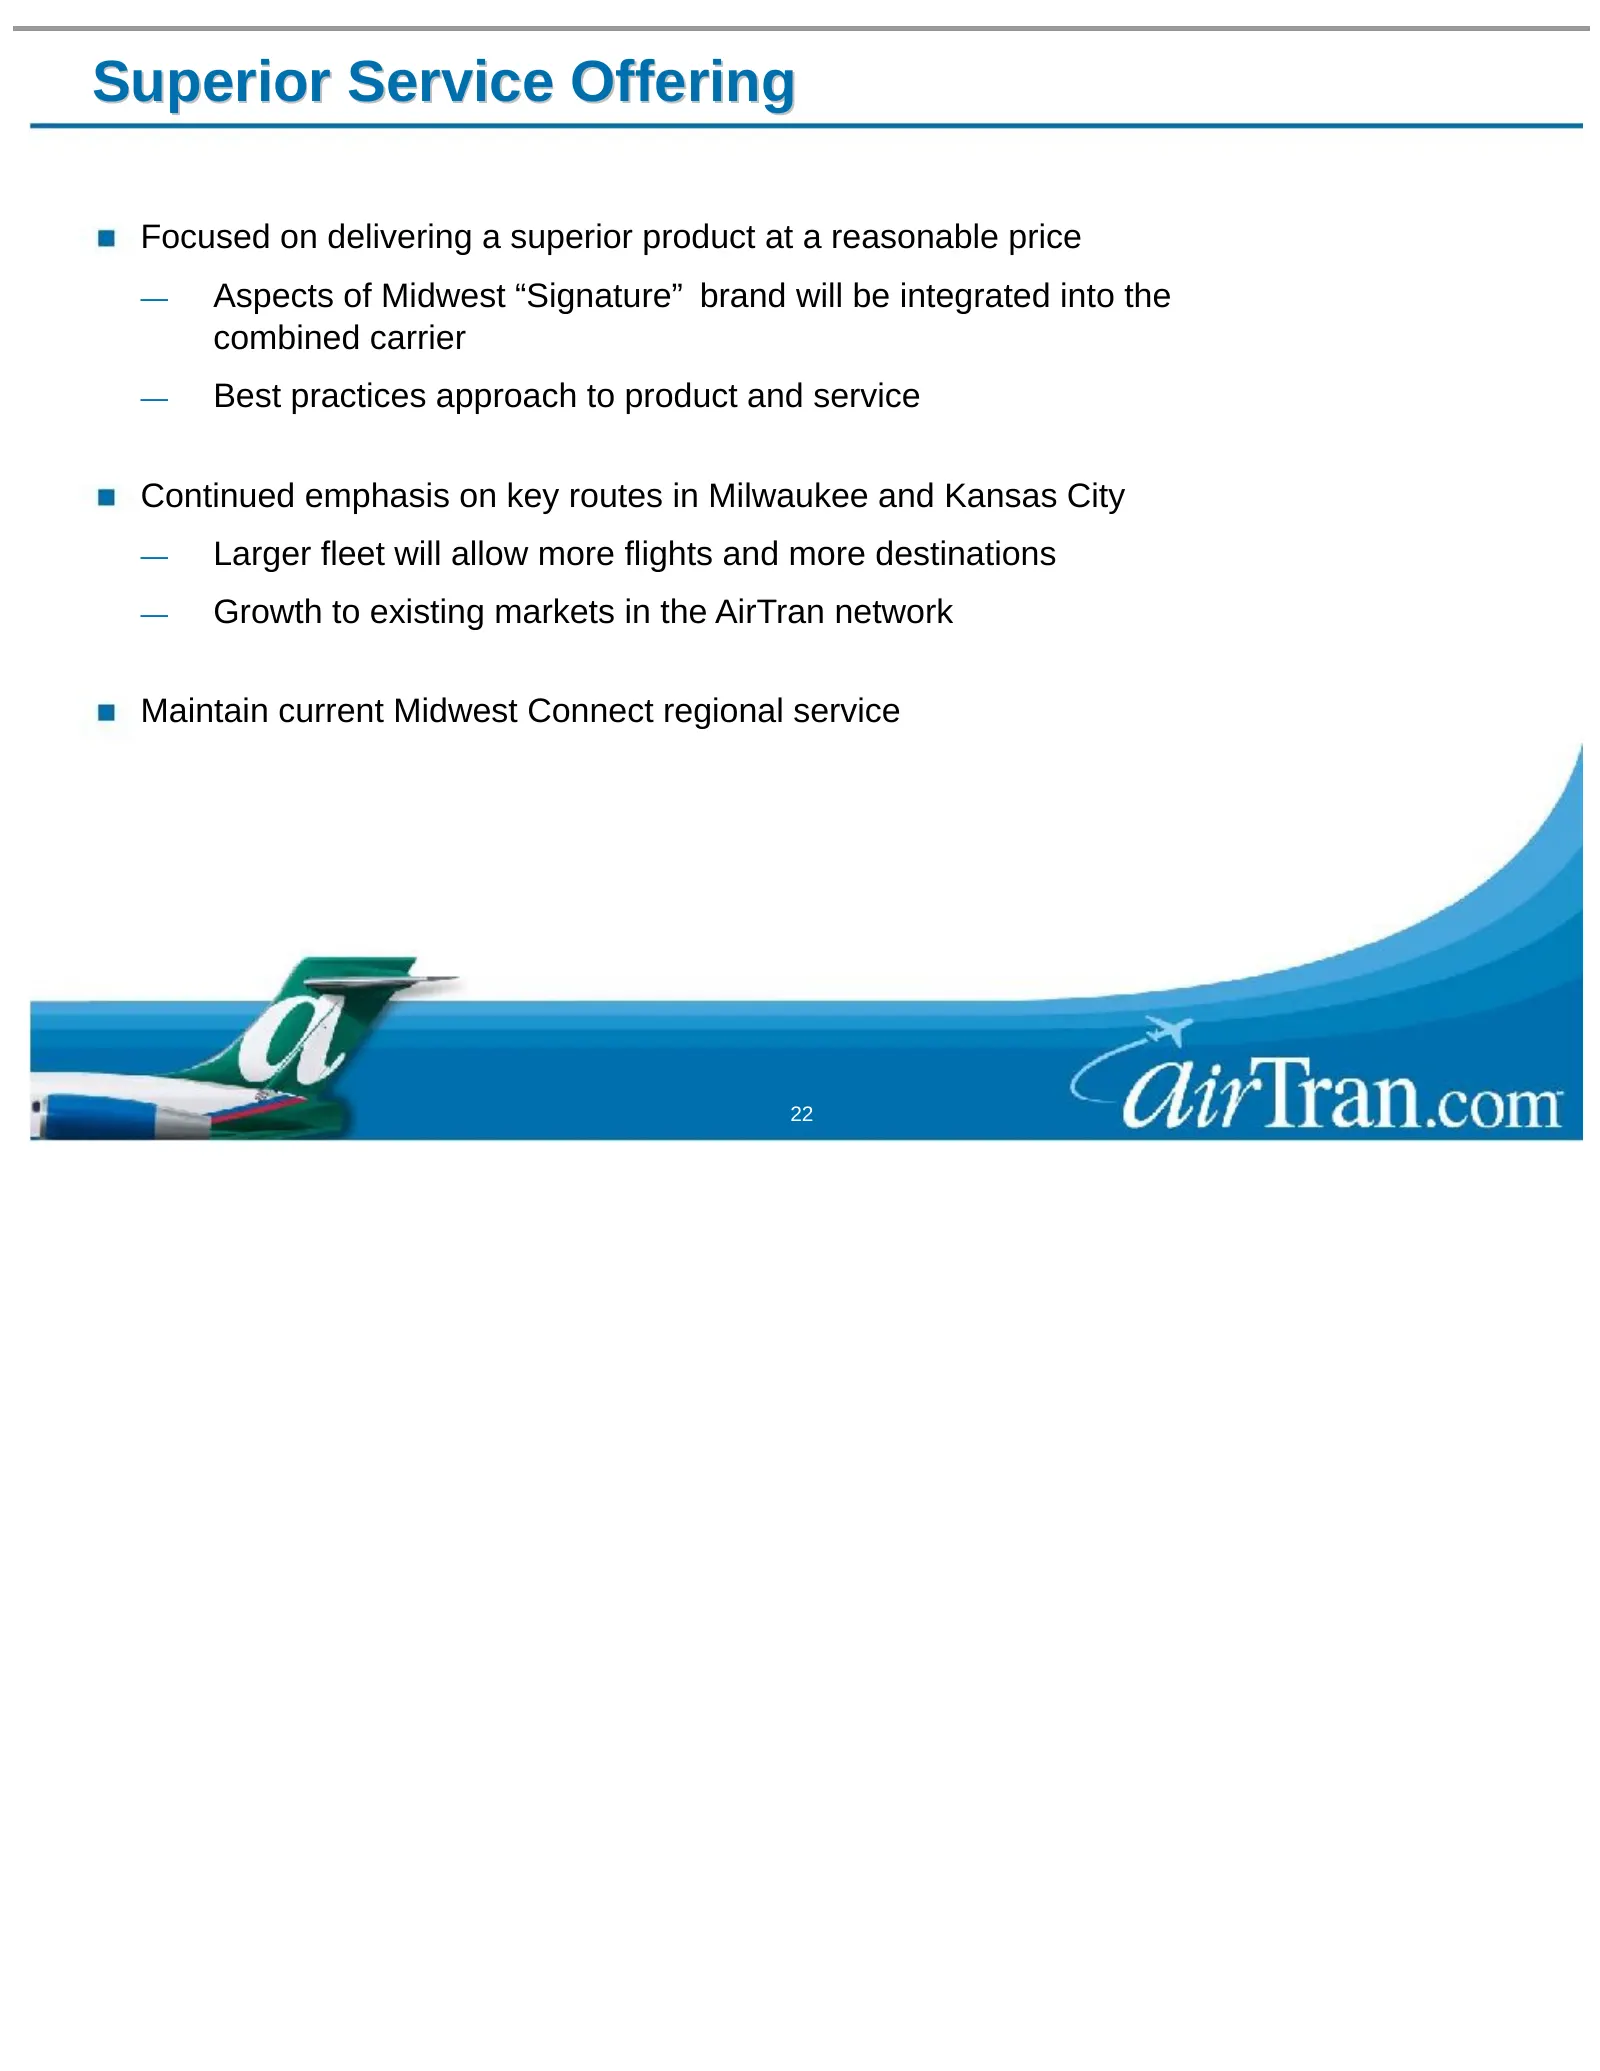
Slide 22: Superior Service Offering
Superior Service Offering Focused on delivering a superior product at a reasonable price — Aspects of Midwest “Signature” brand will be integrated into the combined carrier — Best practices approach to product and service Continued emphasis on key routes in Milwaukee and Kansas City — Larger fleet w
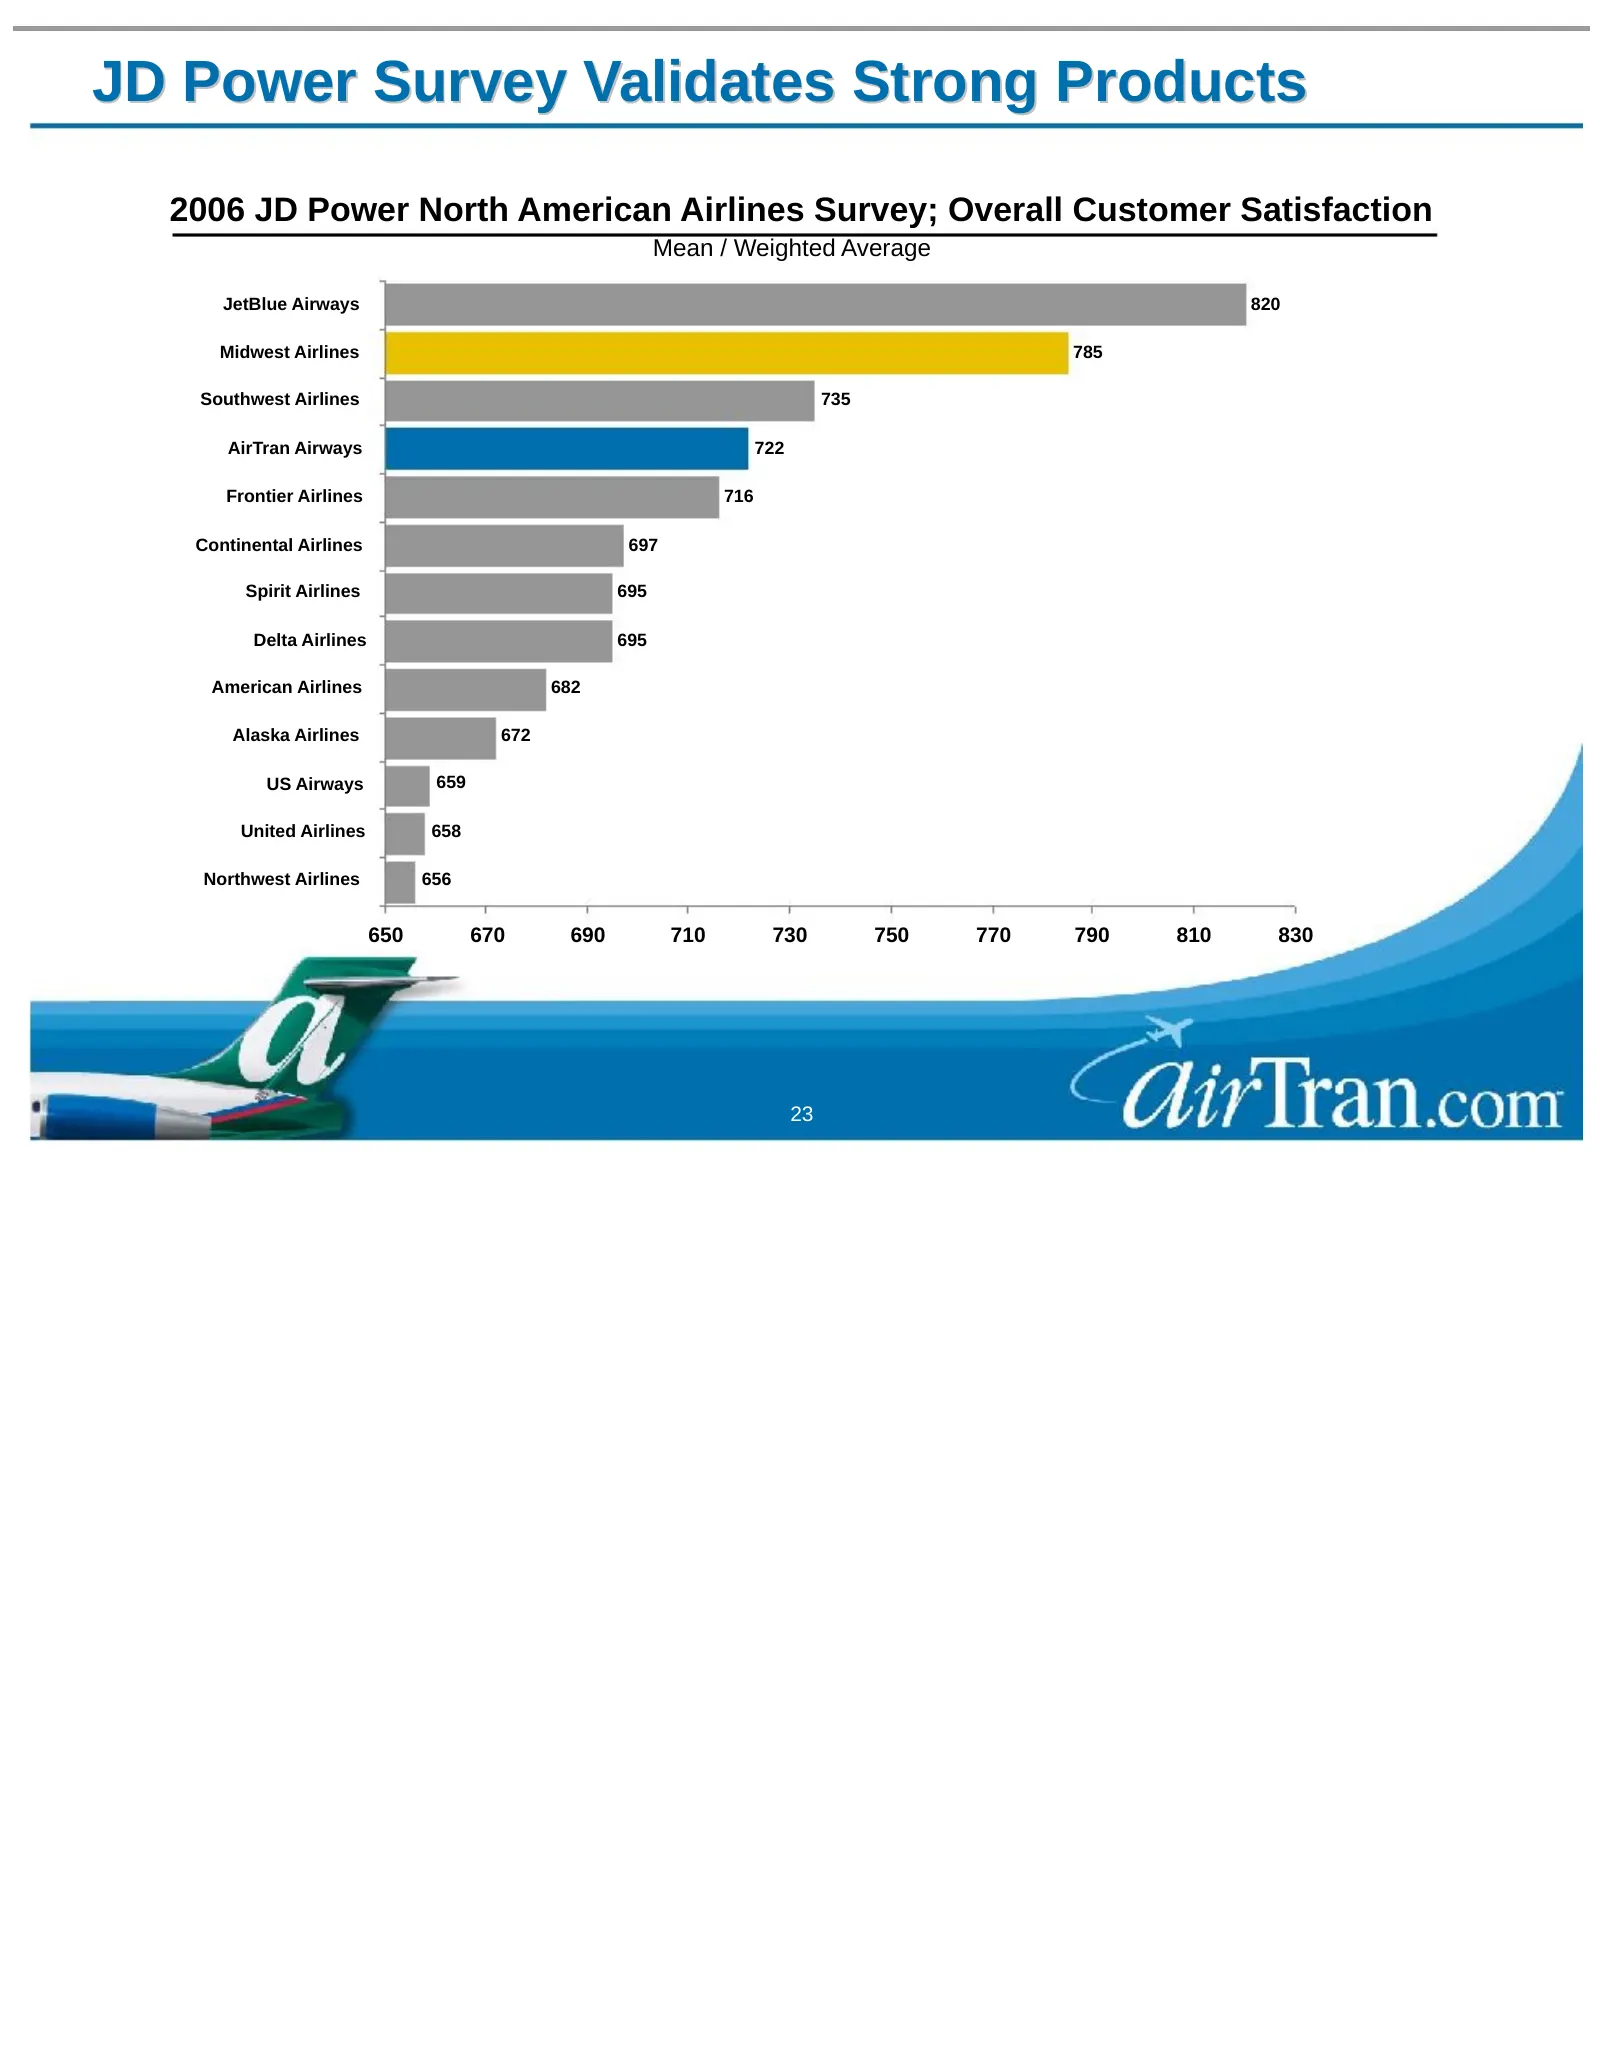
Slide 23: JD Power Survey Validates Strong Products
JD Power Survey Validates Strong Products 2006 JD Power North American Airlines Survey; Overall Customer Satisfaction Mean / Weighted Average JetBlue Airways 820 Midwest Airlines 785 Southwest Airlines 735 AirTran Airways 722 Frontier Airlines 716 Continental Airlines 697 Spirit Airlines 695 Delta A
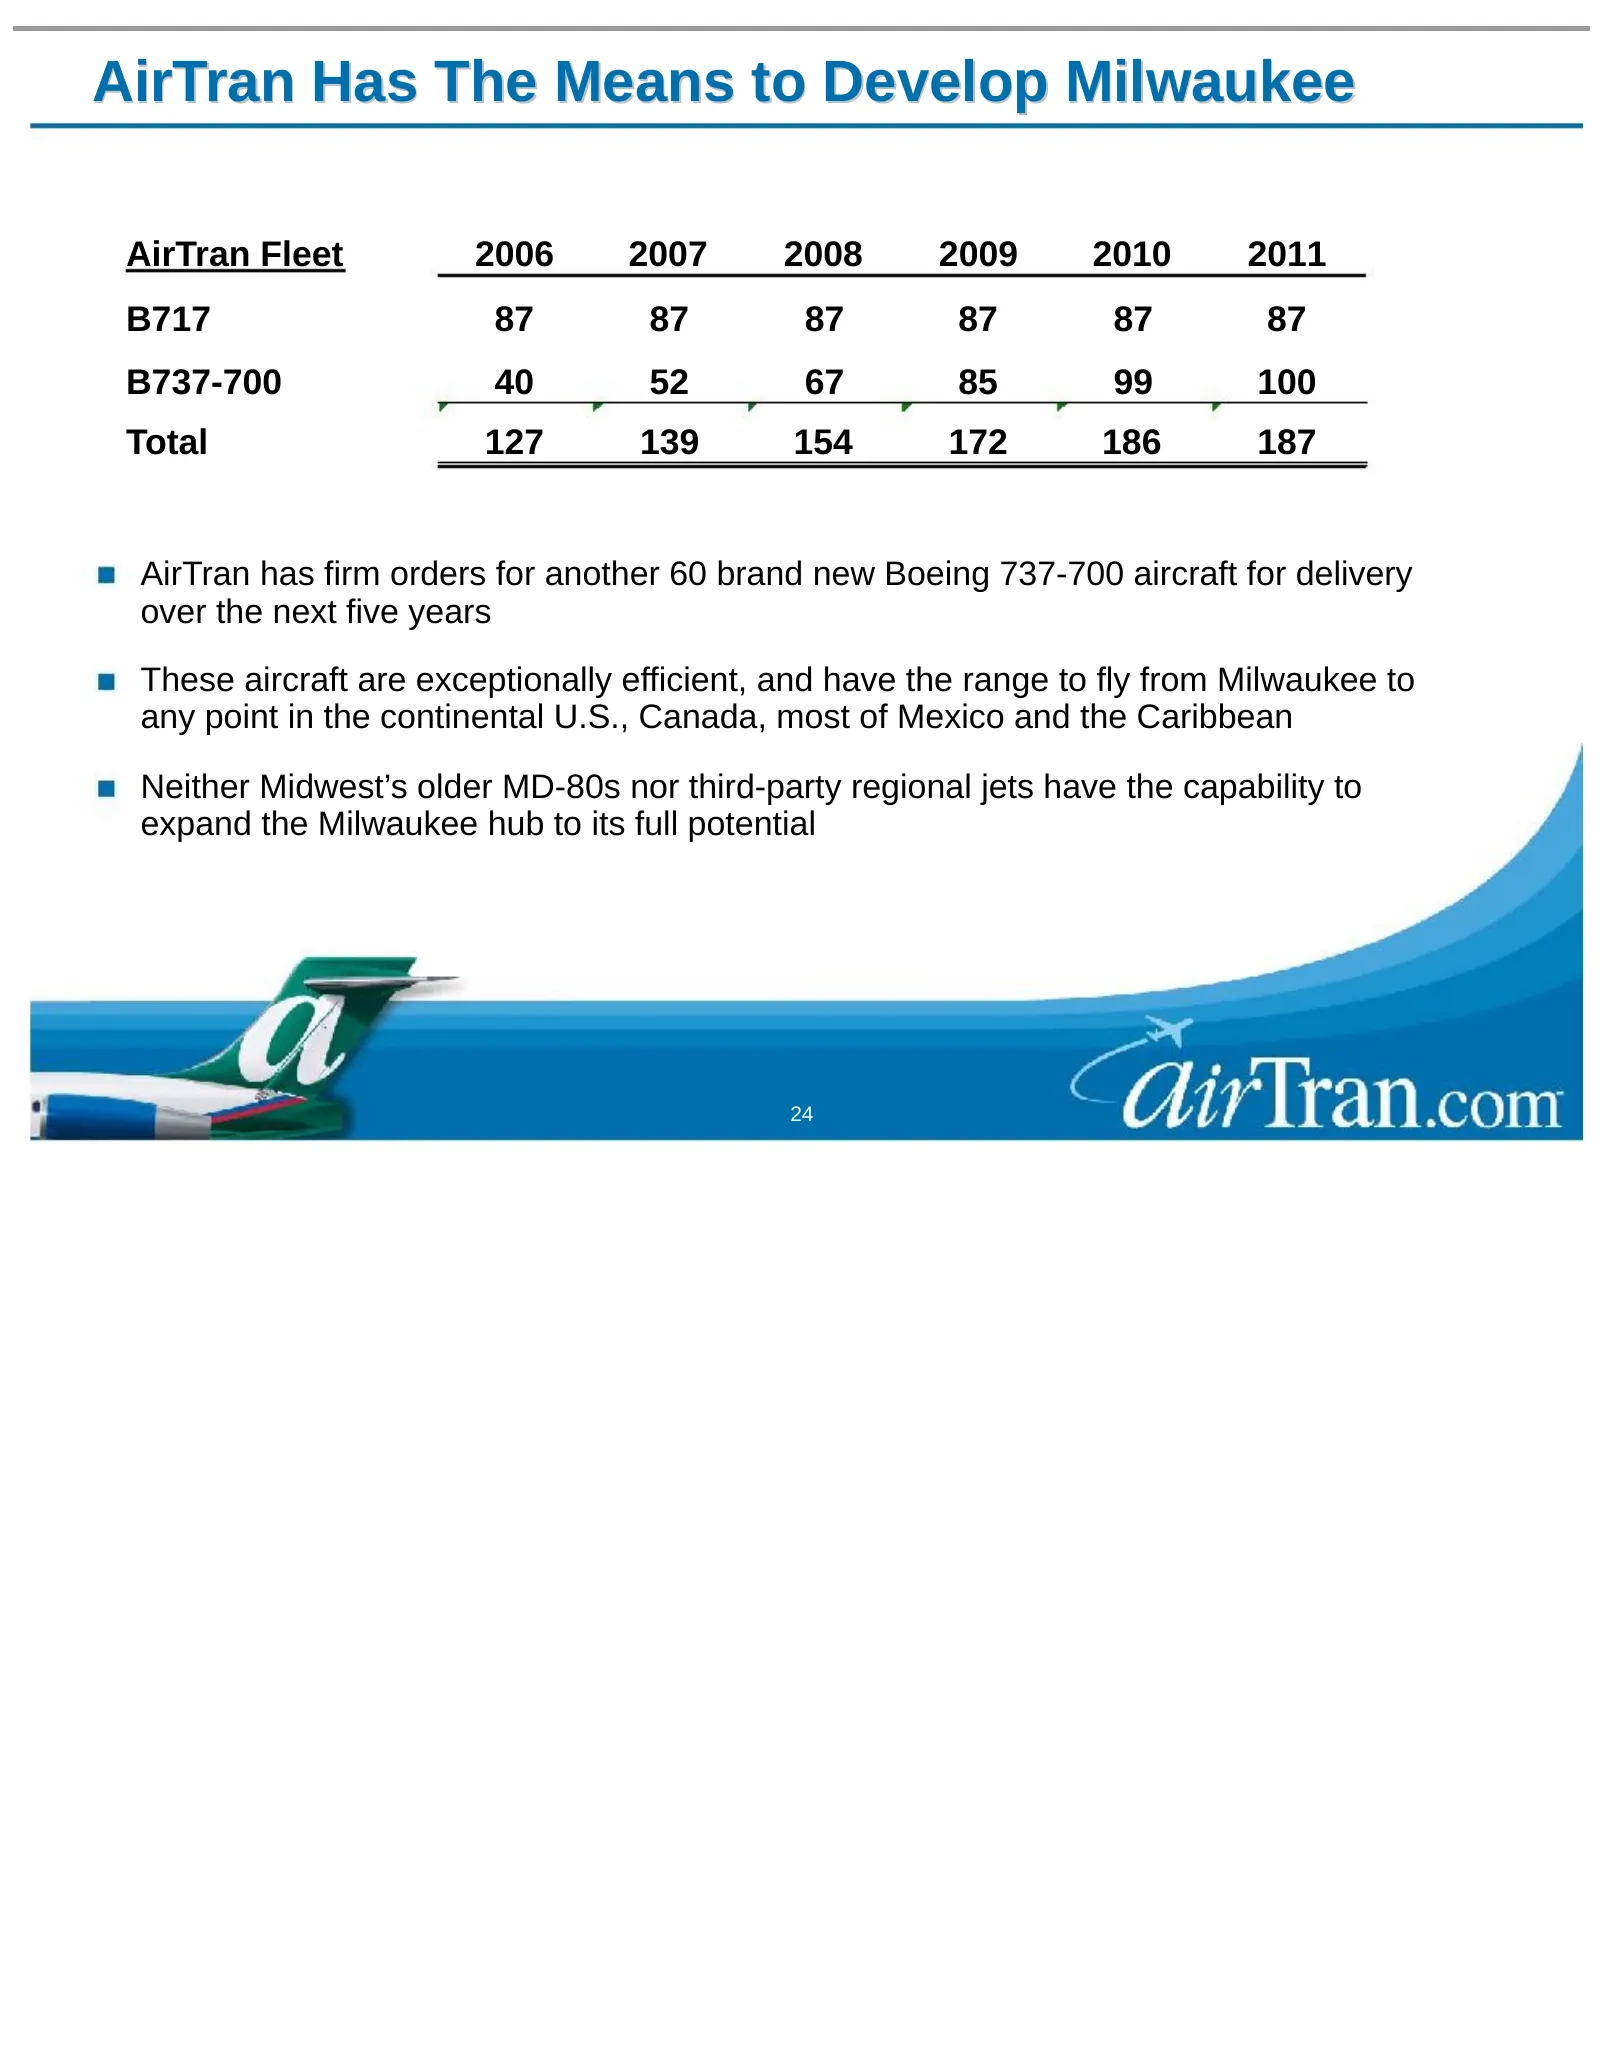
Slide 24: AirTran Has The Means to Develop Milwaukee
AirTran Has The Means to Develop Milwaukee AirTran Fleet 2006 2007 2008 2009 2010 2011 B717 87 87 87 87 87 87 B737-700 40 52 67 85 99 100 Total 127 139 154 172 186 187 AirTran has firm orders for another 60 brand new Boeing 737-700 aircraft for delivery over the next five years These aircraft are ex
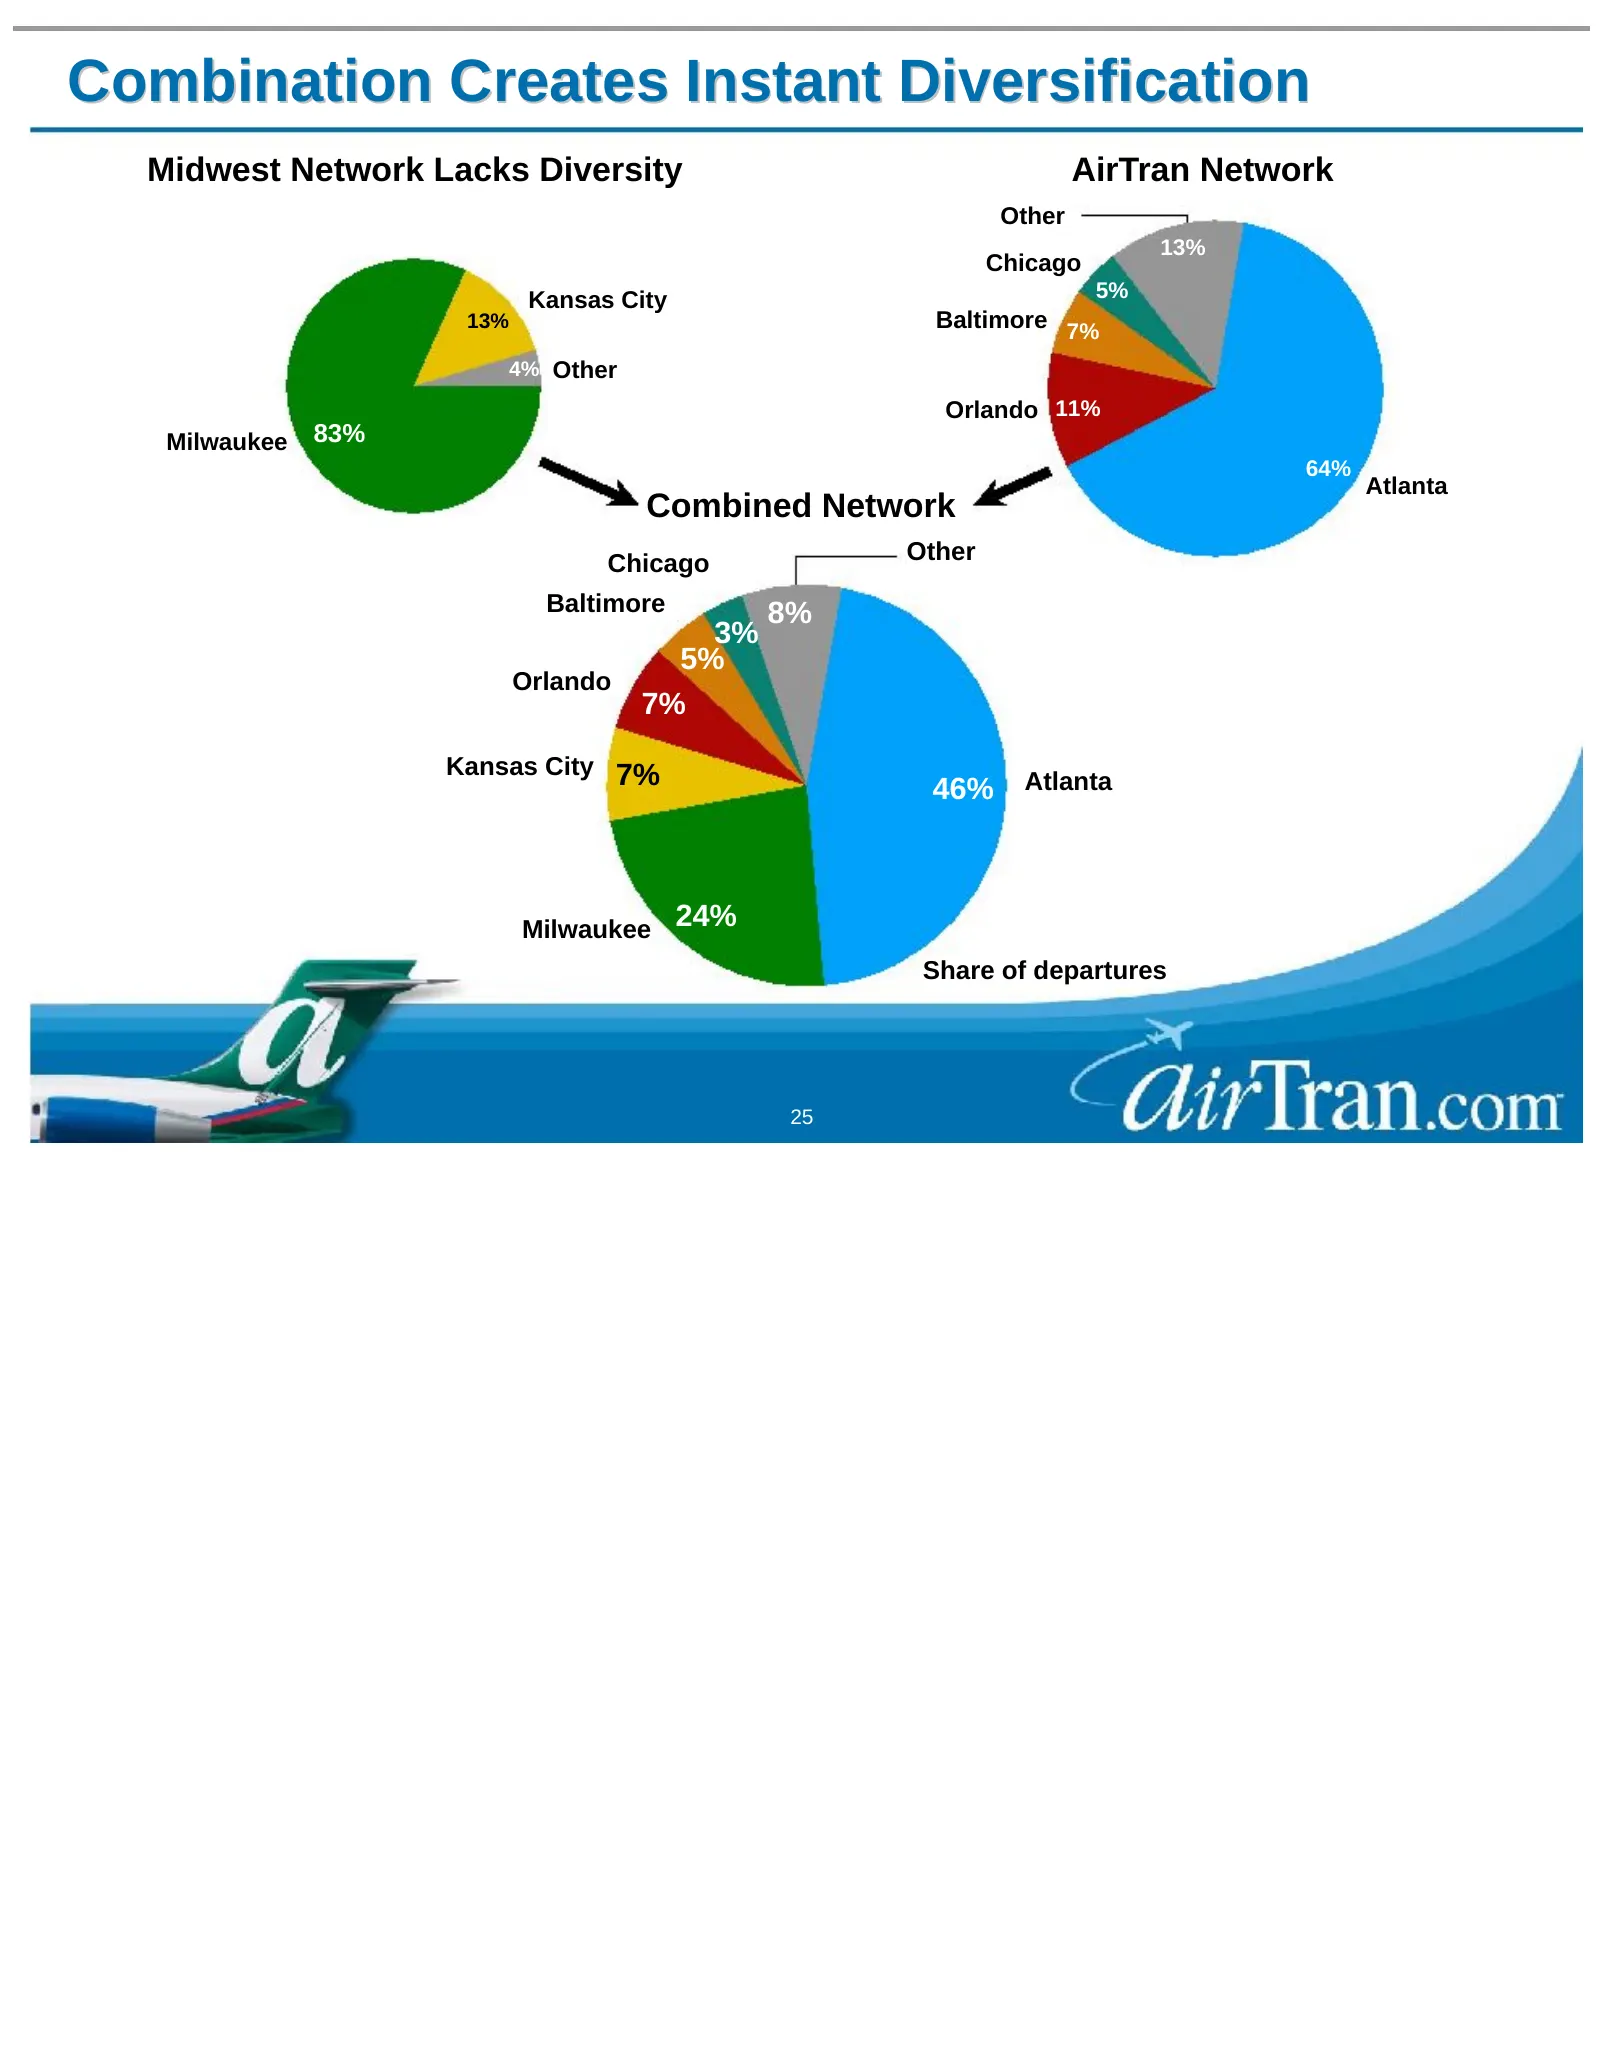
Slide 25: Combination Creates Instant Diversification
Combination Creates Instant Diversification Midwest Network Lacks Diversity AirTran Network Other 13% Chicago Kansas City 5% 13% Baltimore 7% 4% Other Orlando 11% Milwaukee 83% 64% Atlanta Combined Network Chicago Other Baltimore 8% 3% 5% Orlando 7% Kansas City 7% 46% Atlanta Milwaukee 24% Share of
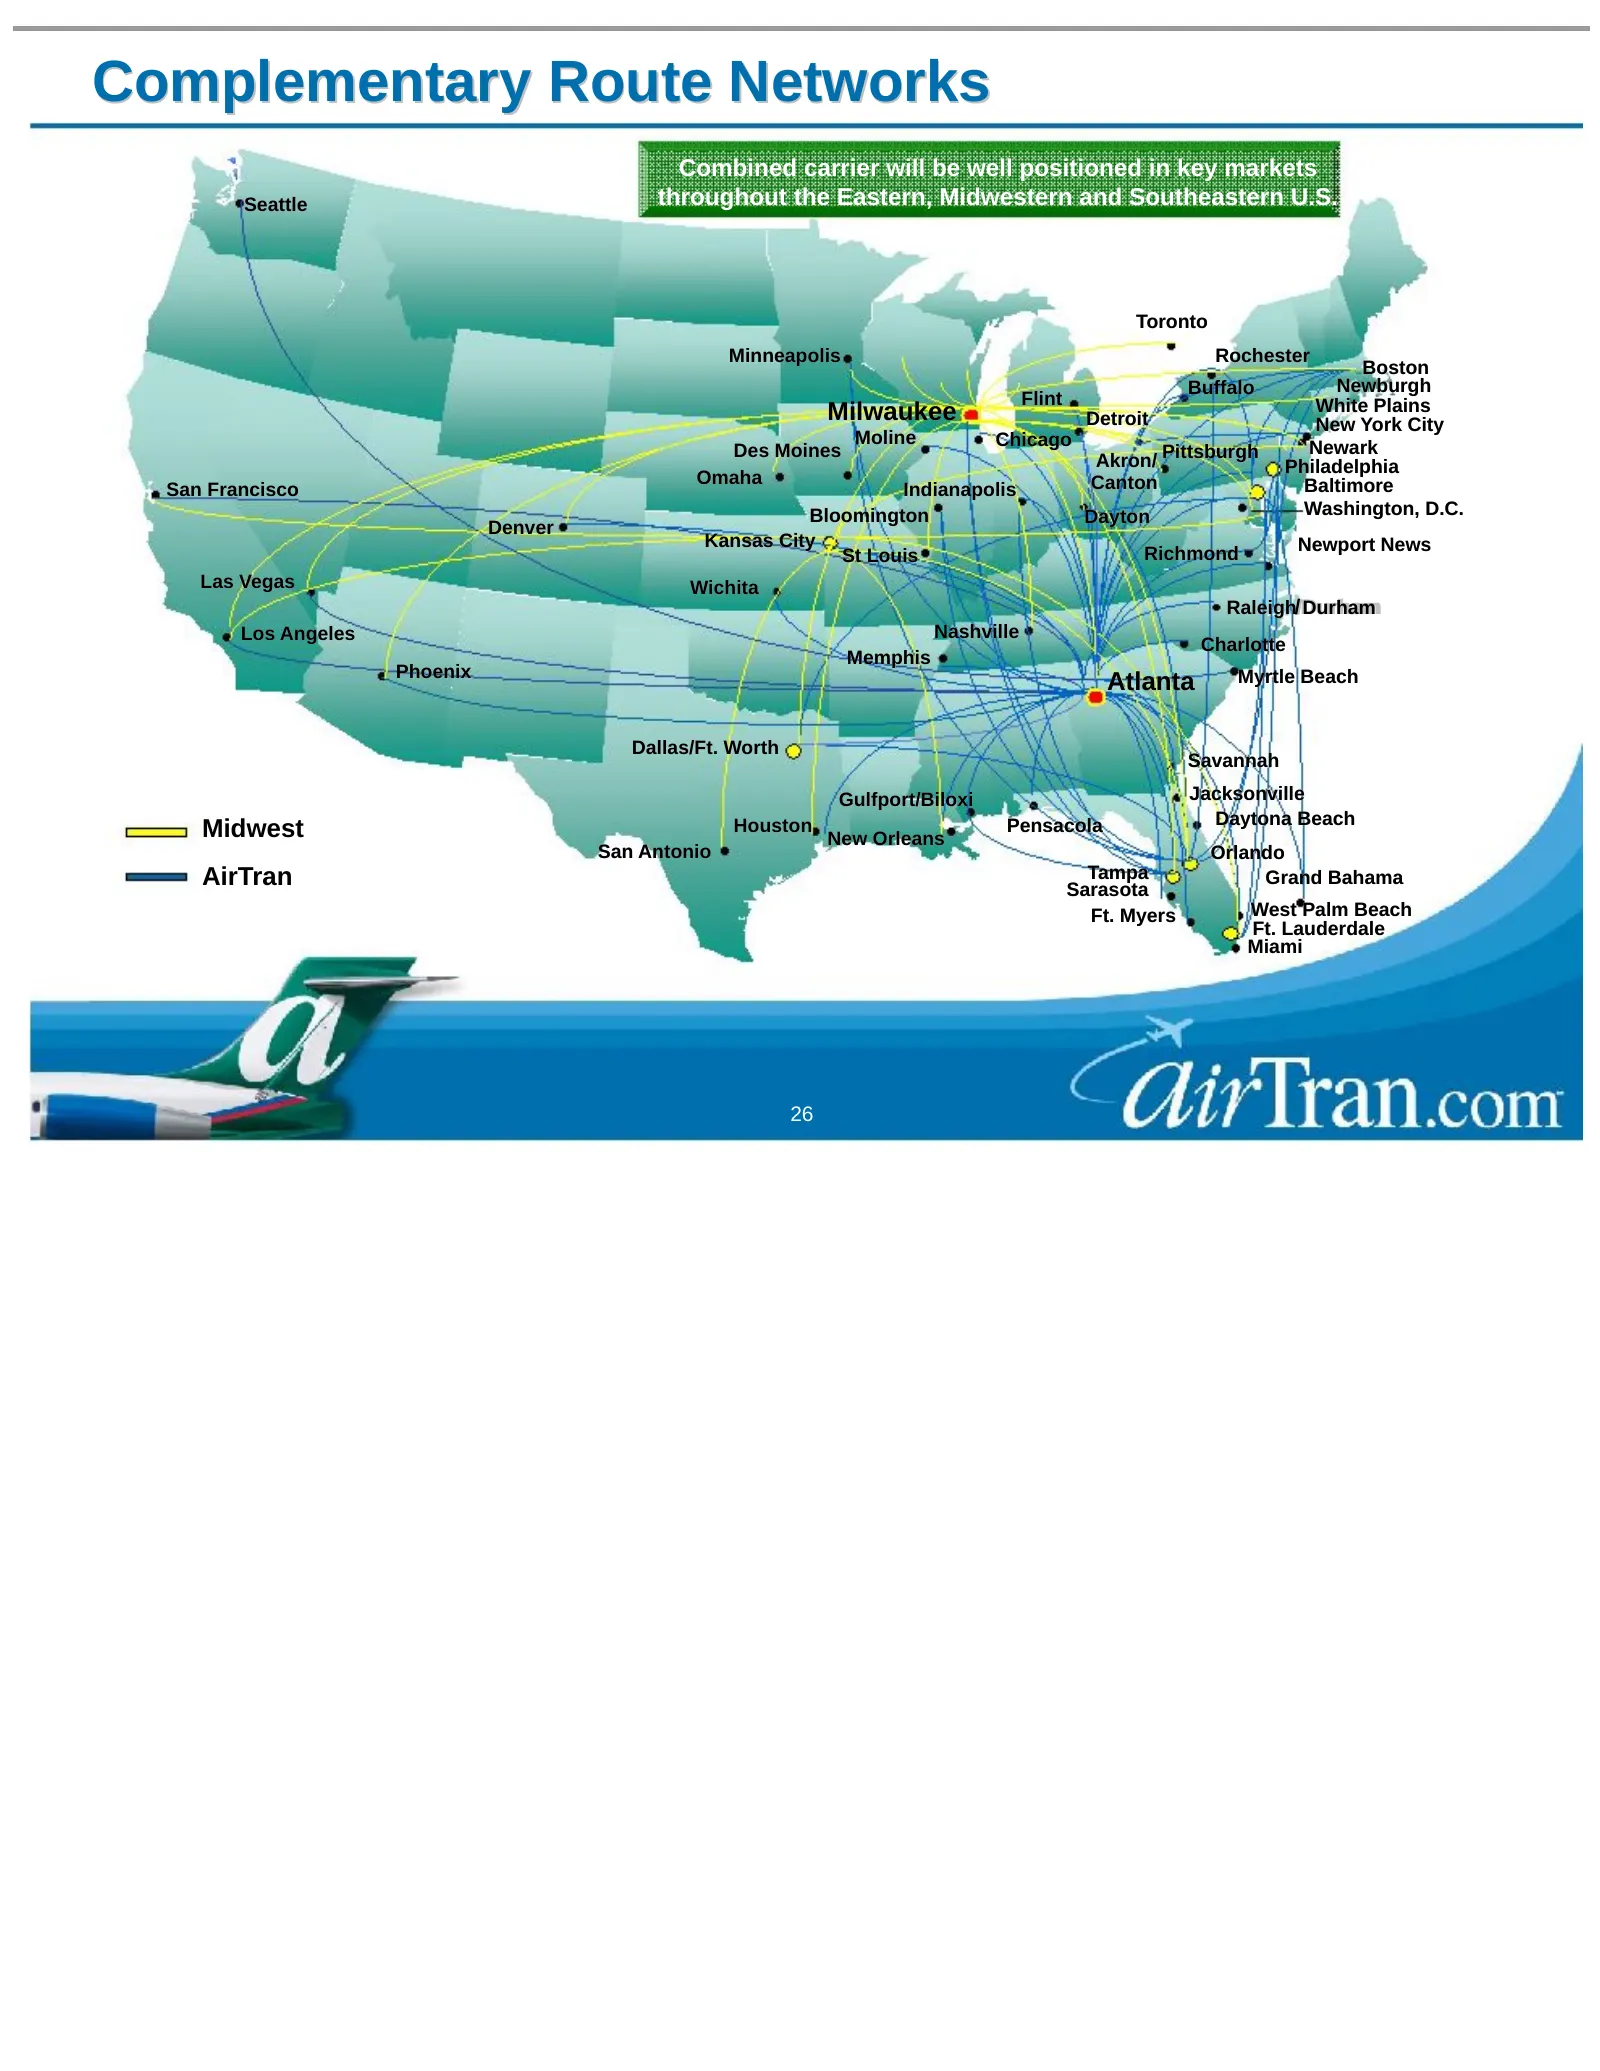
Slide 26: Complementary Route Networks
Complementary Route Networks Combined carrier will be well positioned in key markets Seattle throughout the Eastern, Midwestern and Southeastern U.S. Toronto Minneapolis Rochester Boston Buffalo Newburgh Flint White Plains Milwaukee Detroit New York City Moline Chicago Des Moines Newark Akron/ Pitts
Slide 27: Combination Creates Strength in Key Markets
Combination Creates Strength in Key Markets More low fare flights to a broader array of cities Multiple low fare hubs will allow better service to the continental U.S. — Atlanta and Baltimore: North-South — Milwaukee and Kansas City: East-West Larger, more relevant frequent flyer program throughout
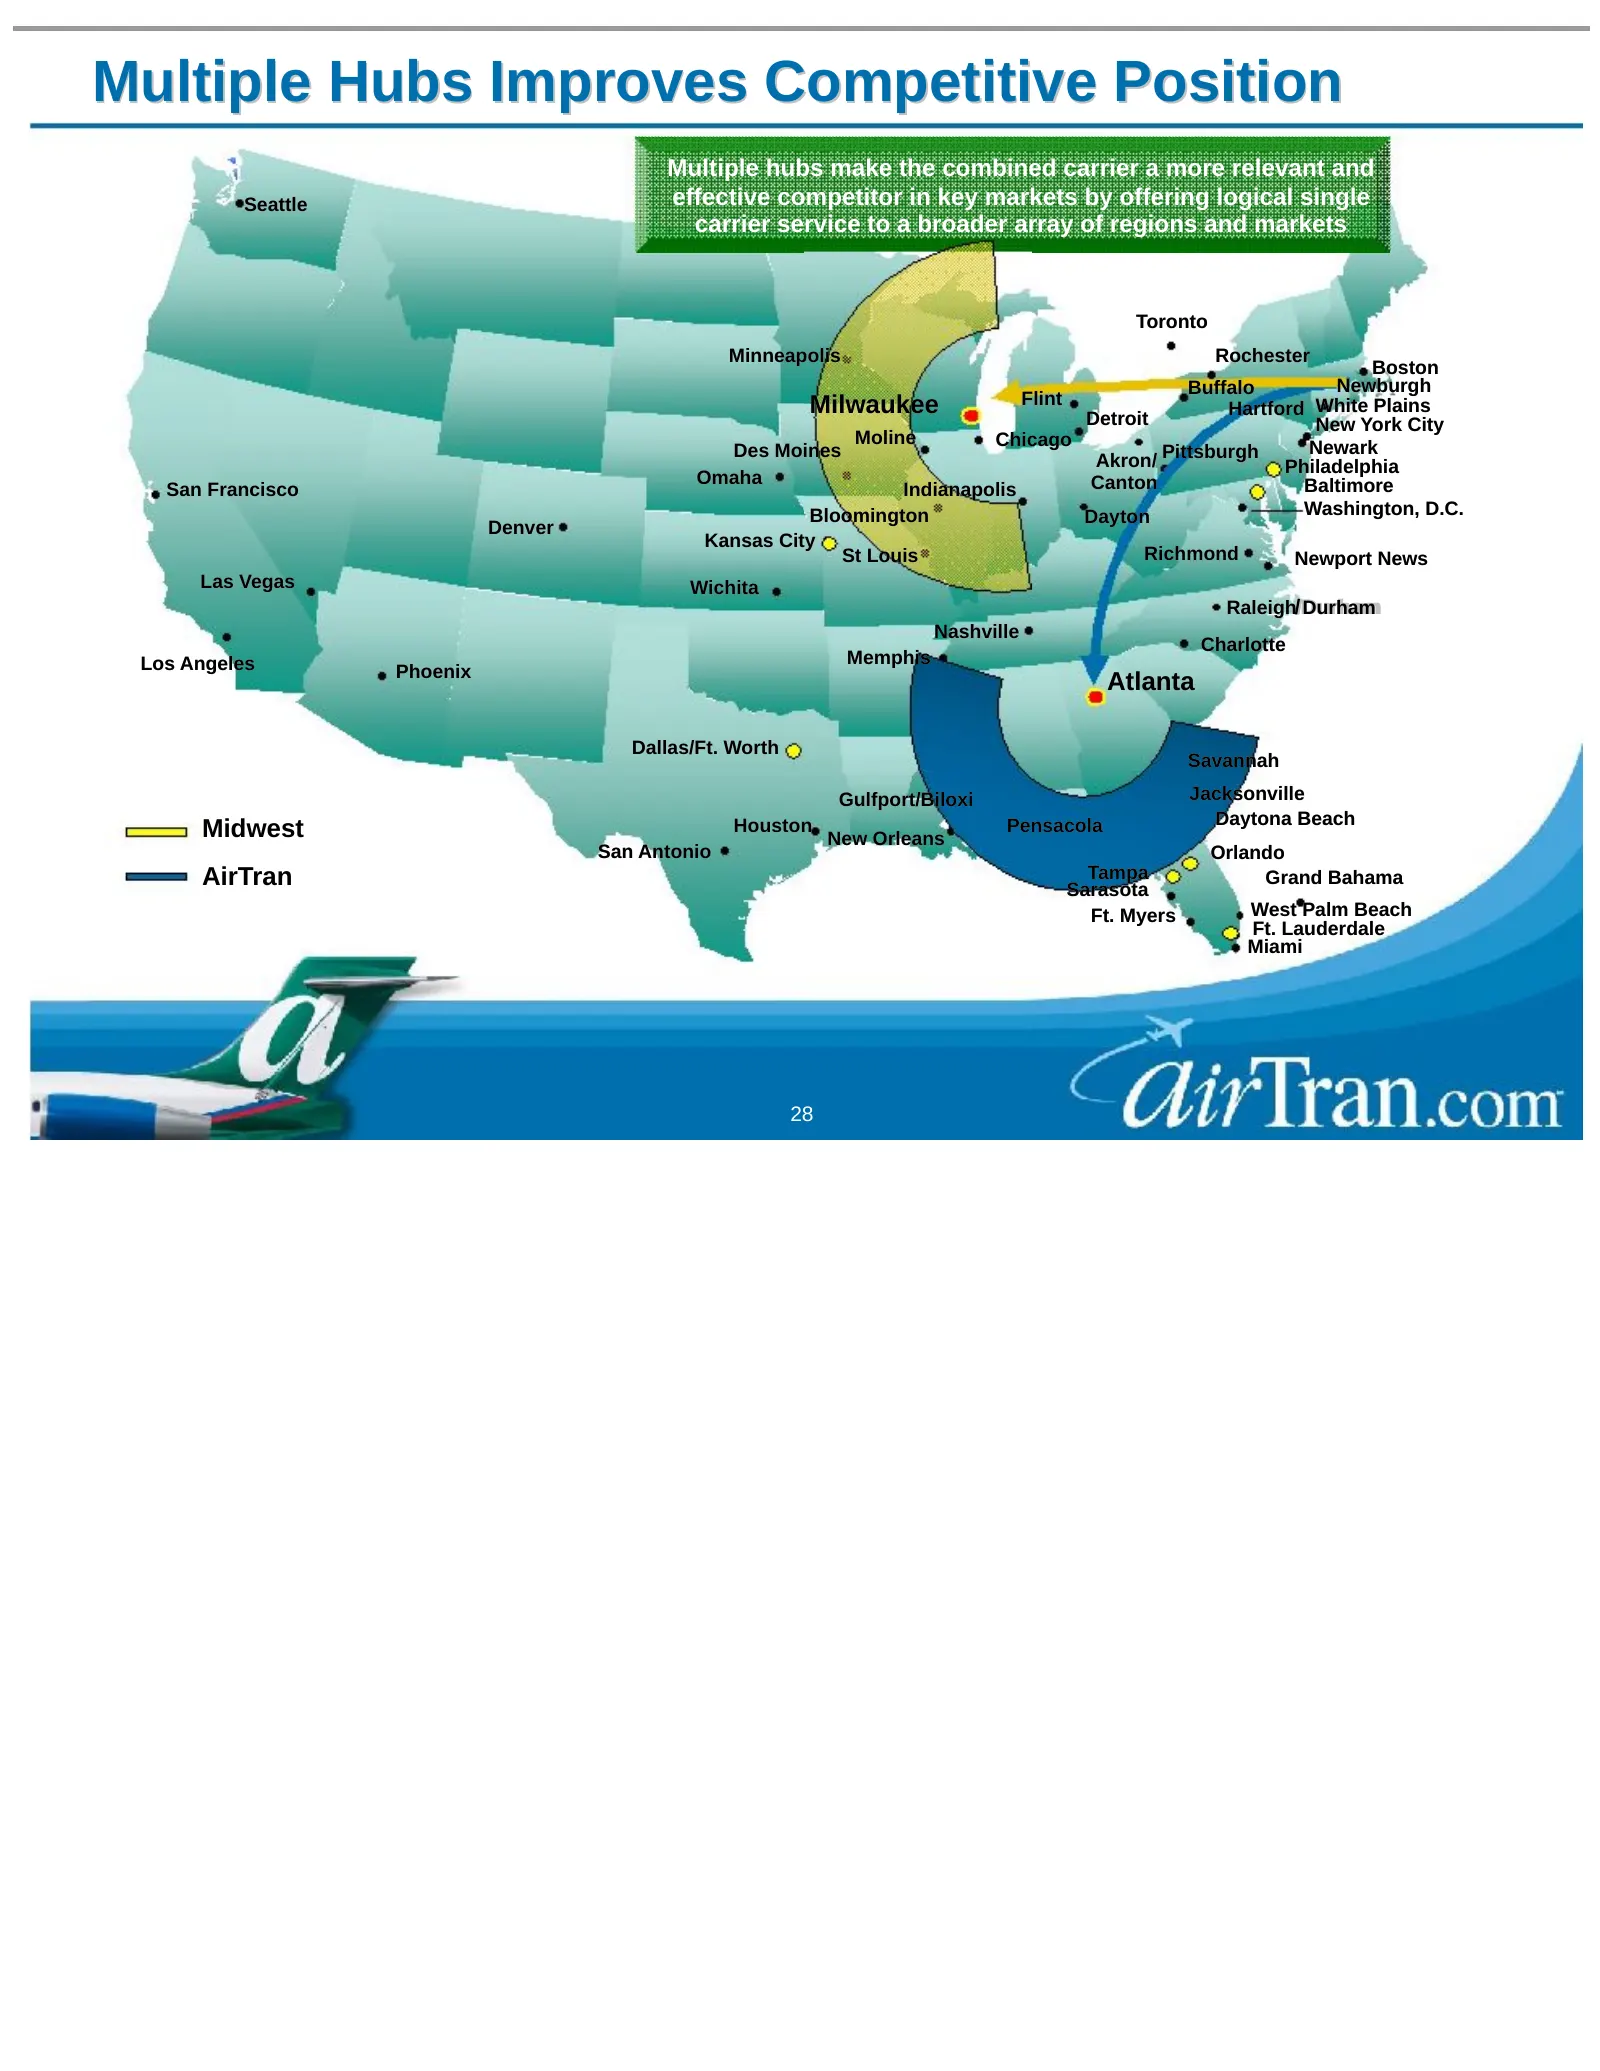
Slide 28: Multiple Hubs Improves Competitive Position
Multiple Hubs Improves Competitive Position Multiple hubs make the combined carrier a more relevant and Seattle effective competitor in key markets by offering logical single carrier service to a broader array of regions and markets Toronto Minneapolis Rochester Boston Buffalo Newburgh Milwaukee Fli
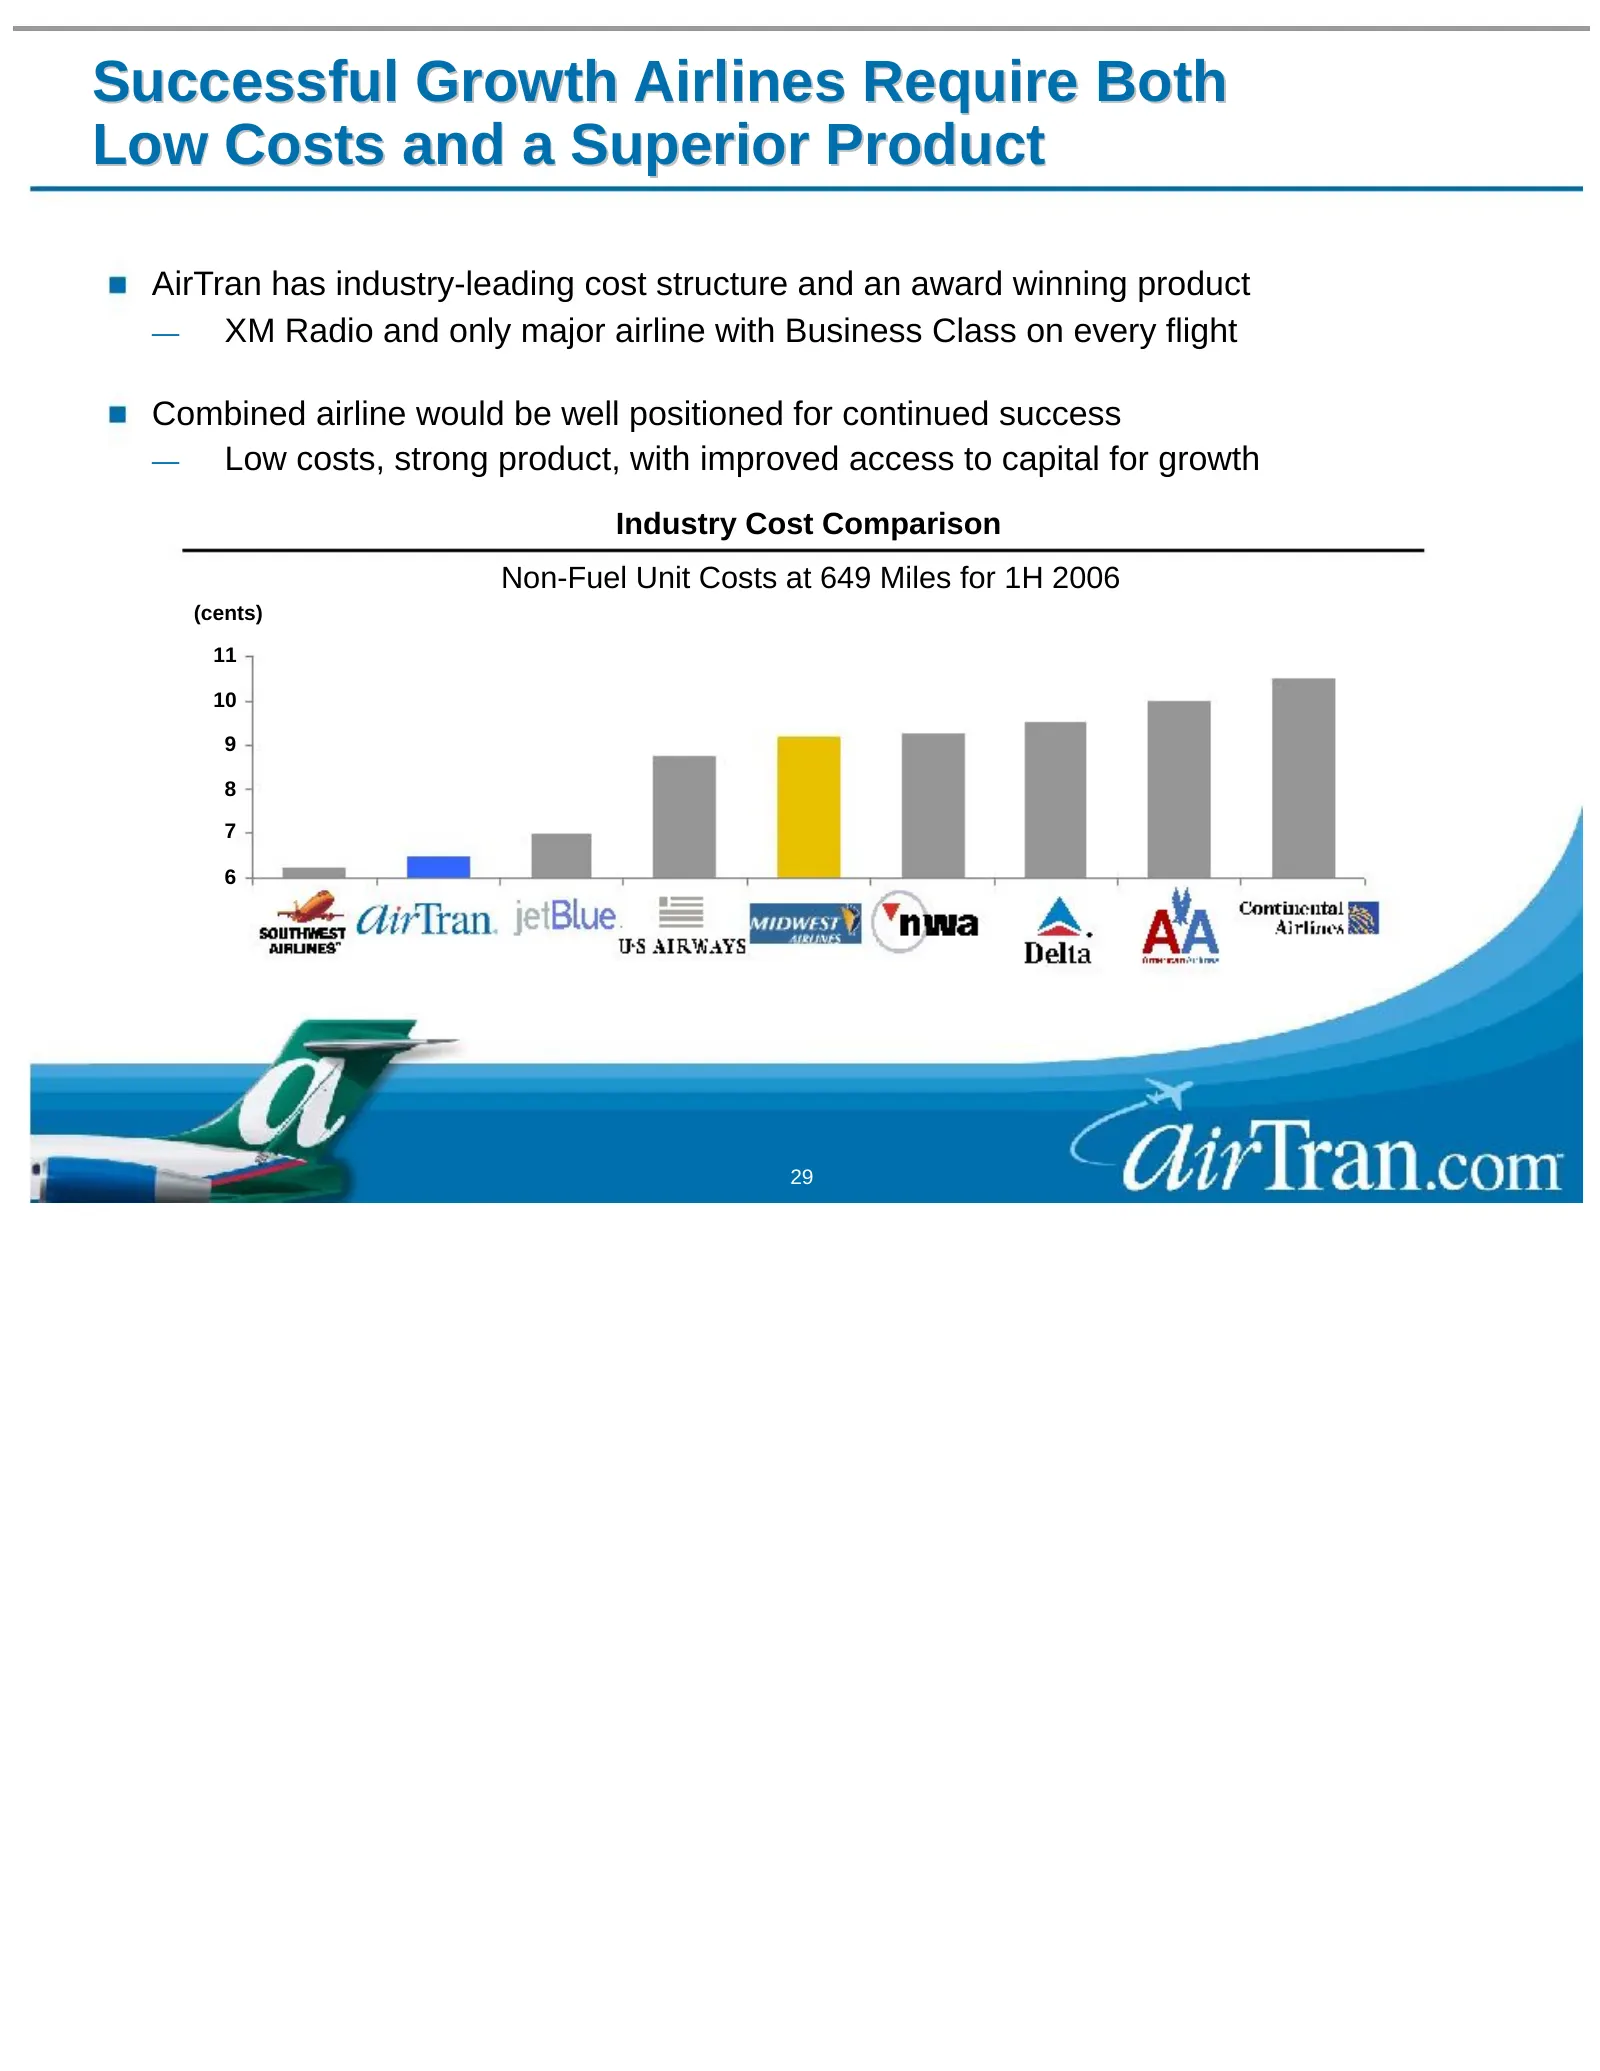
Slide 29: Successful Growth Airlines Require Both Low Costs and a Superior Product
Successful Growth Airlines Require Both Low Costs and a Superior Product AirTran has industry-leading cost structure and an award winning product — XM Radio and only major airline with Business Class on every flight Combined airline would be well positioned for continued success — Low costs, strong
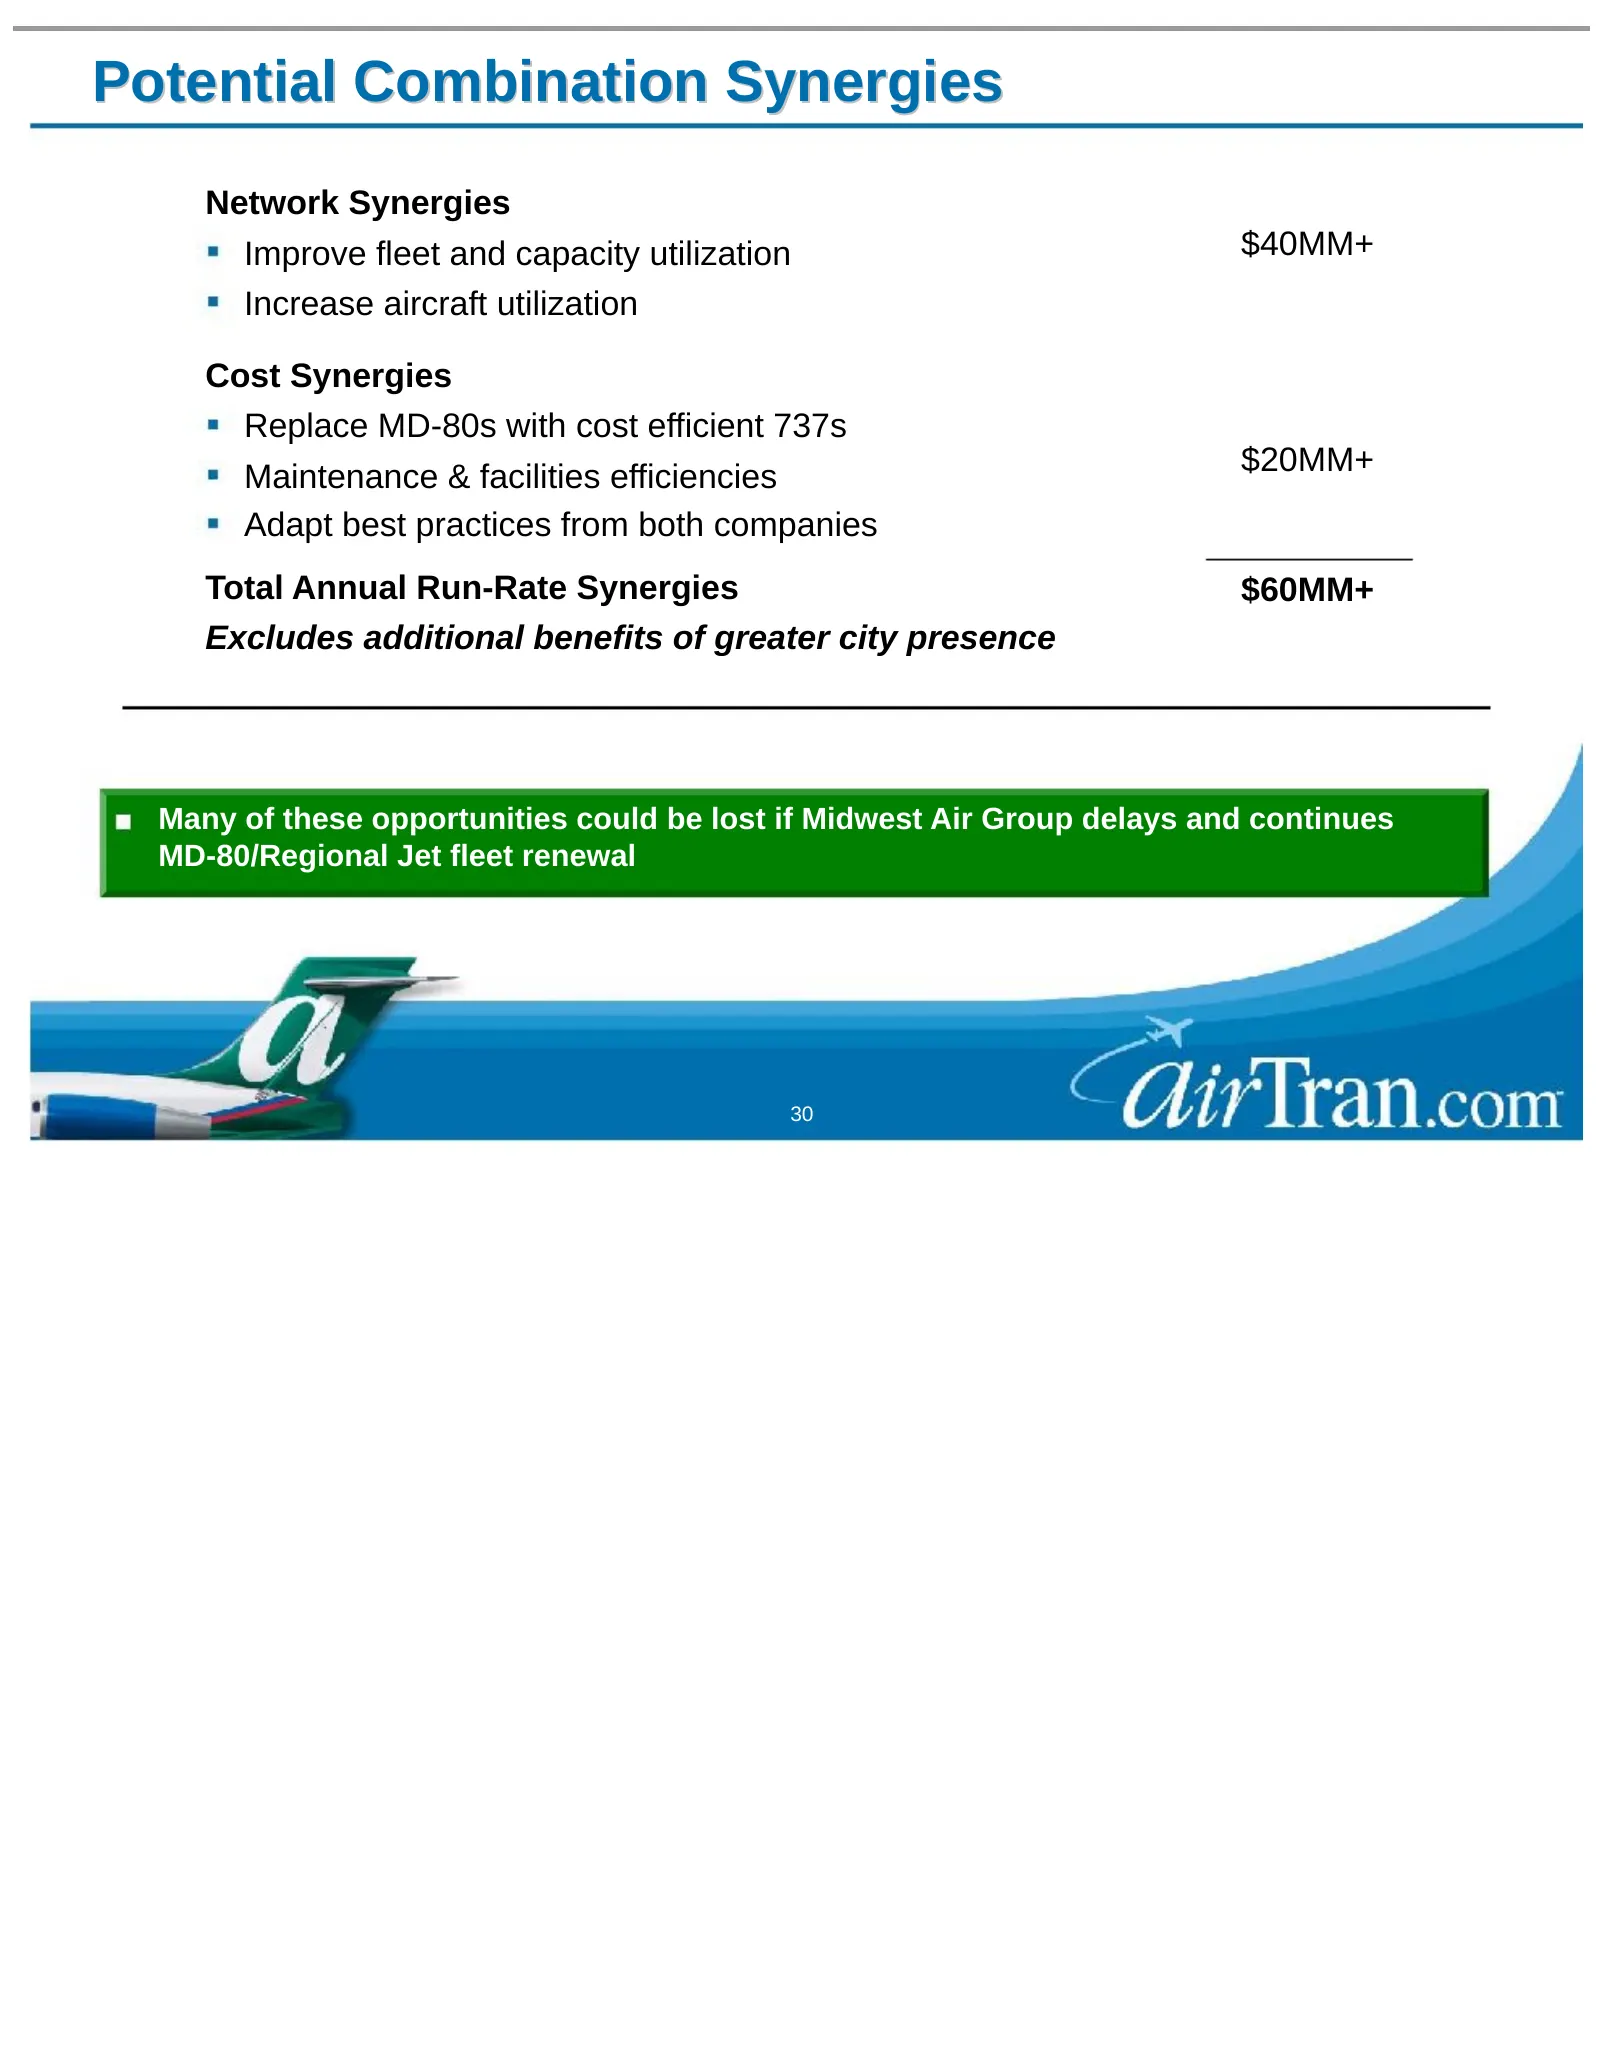
Slide 30: Potential Combination Synergies
Potential Combination Synergies Network Synergies Improve fleet and capacity utilization $40MM+ Increase aircraft utilization Cost Synergies Replace MD-80s with cost efficient 737s Maintenance & facilities efficiencies $20MM+ Adapt best practices from both companies Total Annual Run-Rate Synergies $
Slide 31: Conclusion
Conclusion Clirlran.com
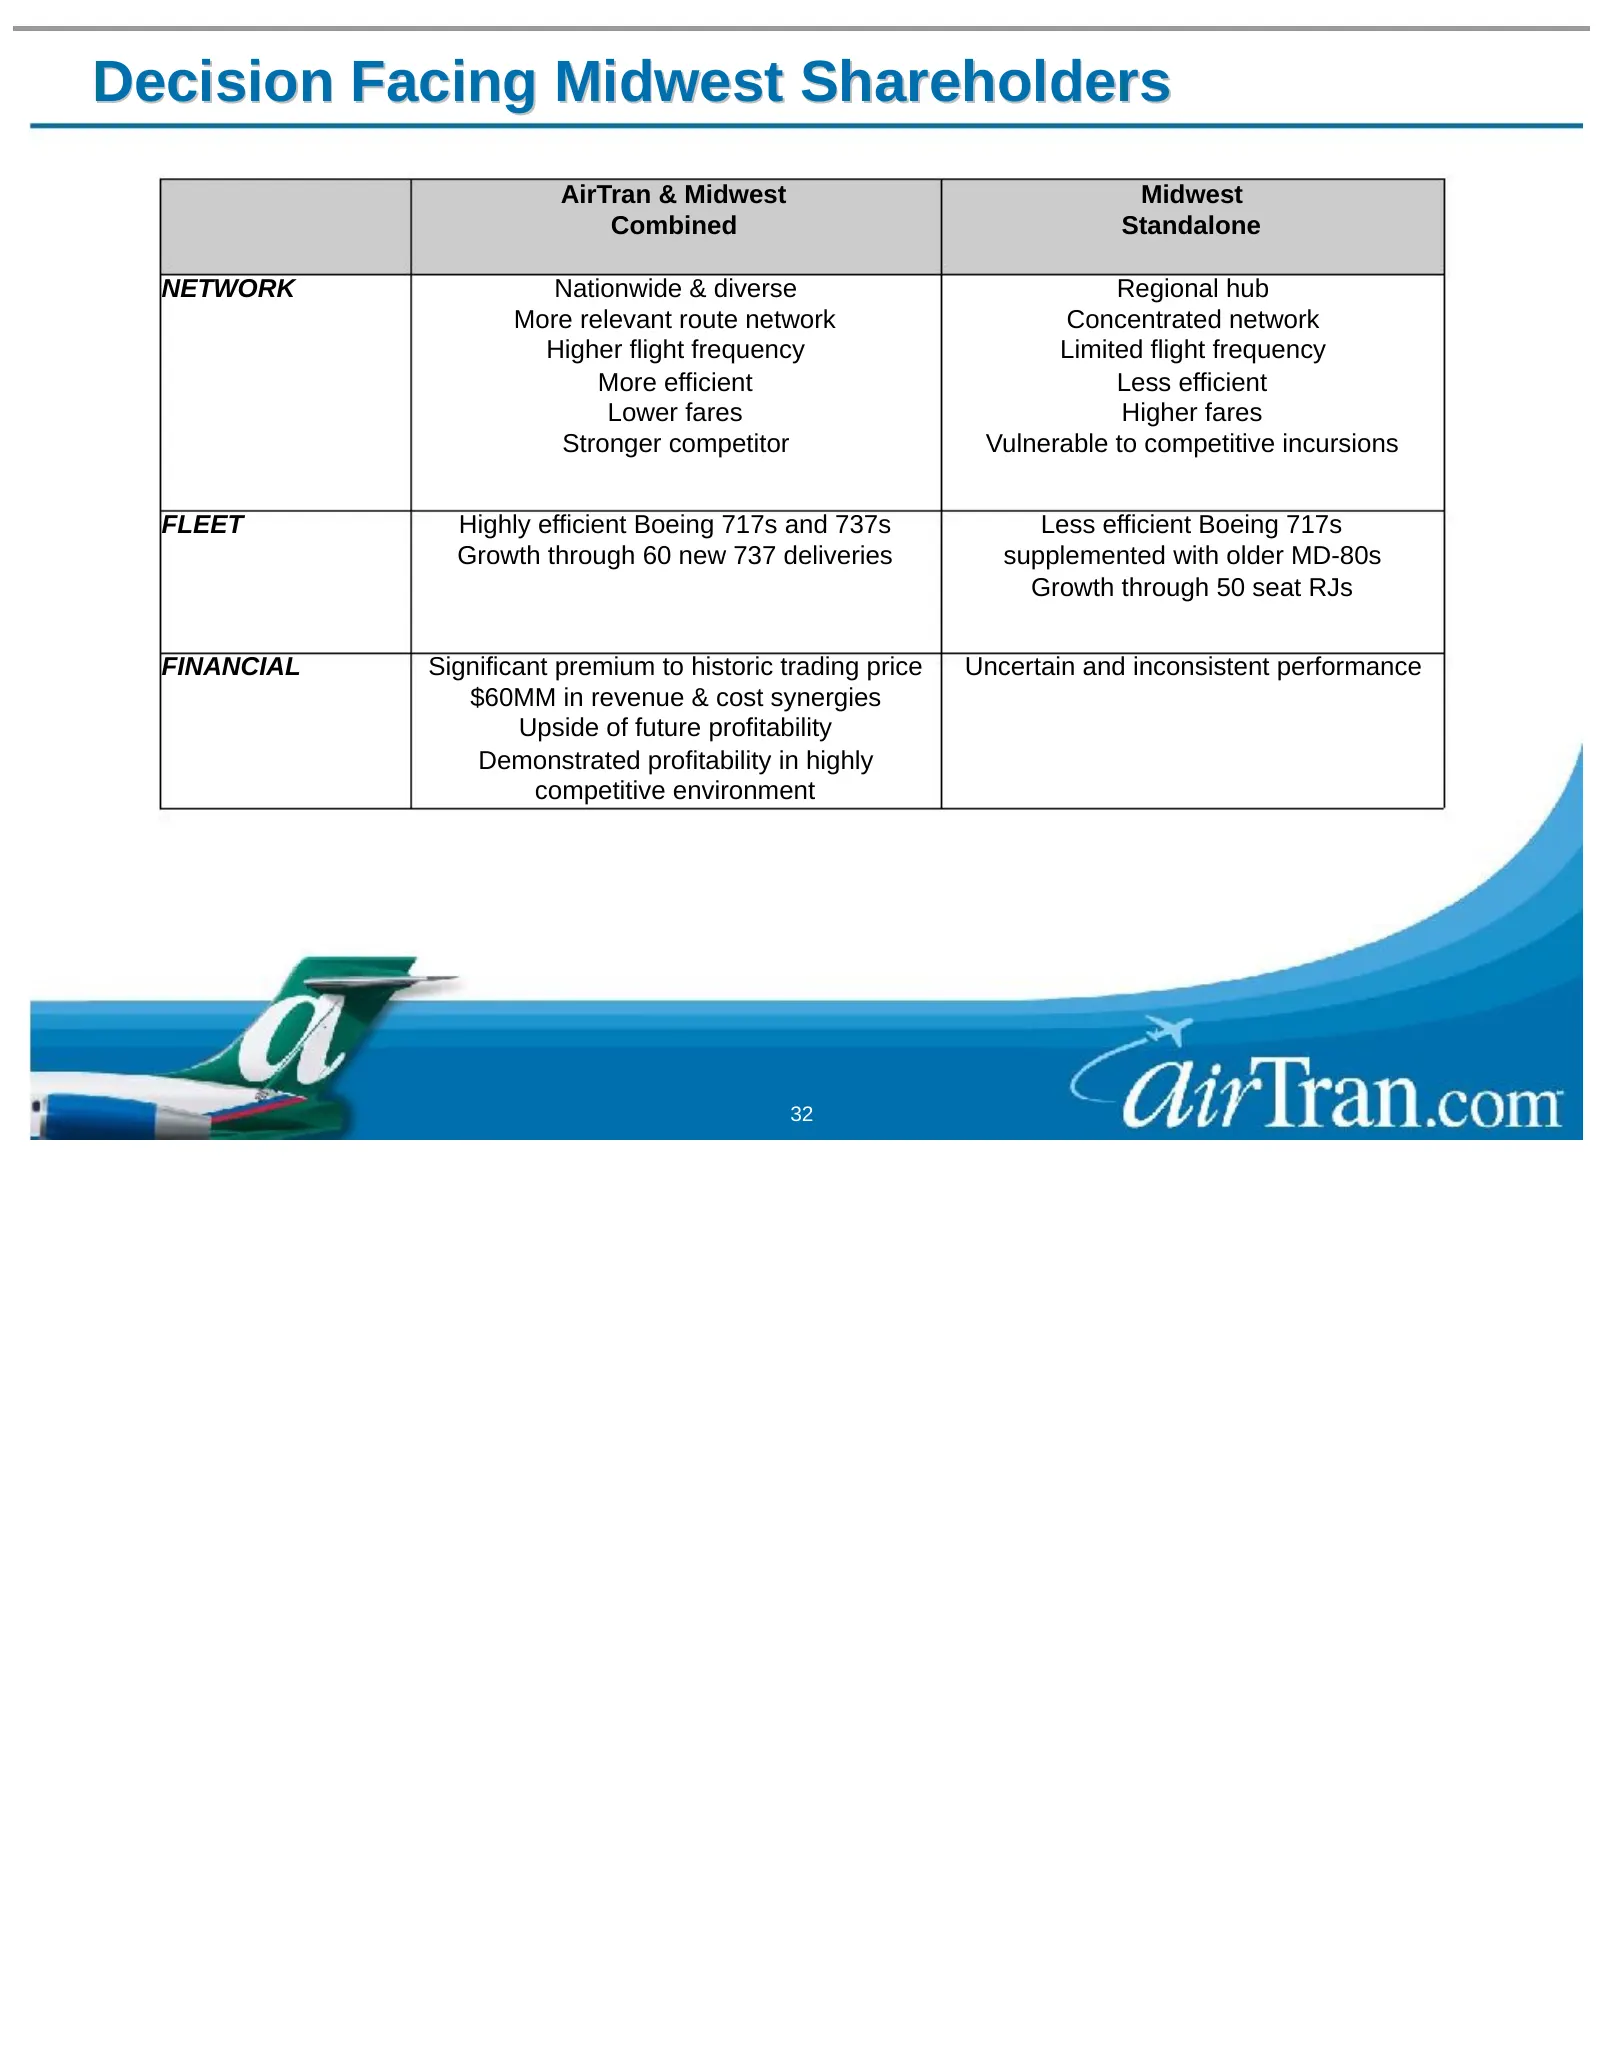
Slide 32: Decision Facing Midwest Shareholders
Decision Facing Midwest Shareholders AirTran & Midwest Midwest Combined Standalone NETWORK Nationwide & diverse Regional hub More relevant route network Concentrated network Higher flight frequency Limited flight frequency More efficient Less efficient Lower fares Higher fares Stronger competitor Vu
Slide 33: Summary
Summary Opportunity to create a stronger combined competitor — A truly national low cost carrier with complementary hubs — Well positioned for future growth opportunities Significant value to all Midwest stakeholders — Shareholders receive significant premium and improved profit potential — Employee
Slide 34: Benefits to All Midwest and AirTran Stakeholders
Benefits to All Midwest and AirTran Stakeholders Shareholders Significant premium and potential for greater future returns Stronger network and lower costs improve profit potential Employees Employees enjoy benefits of a stronger combined company — AirTran has hired over 2,000 new employees in the l
Source: SEC EDGAR · 8-K filed Jan 11, 2007
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010