Hughes Supply — Investor Presentation (February 2004)
39 slides from Hughes Supply's investor presentation, Feb 2, 2004
Slide 1: Investor Presentation January 2004
((UGHES Investor Presentation January 2004
Slide 2: Forward Looking Statements
FORWARD Certain involve performance, other include 1 reports statements adjusted known LOOKING filed and and financial achievements with set unknown forth the STATEMENT measures Securities inrisks, this expressed presentation uncertainties, governed and Exchange or implied byconsist Regulation andCo
Slide 3: Company Overview
({UGHES Company Overview
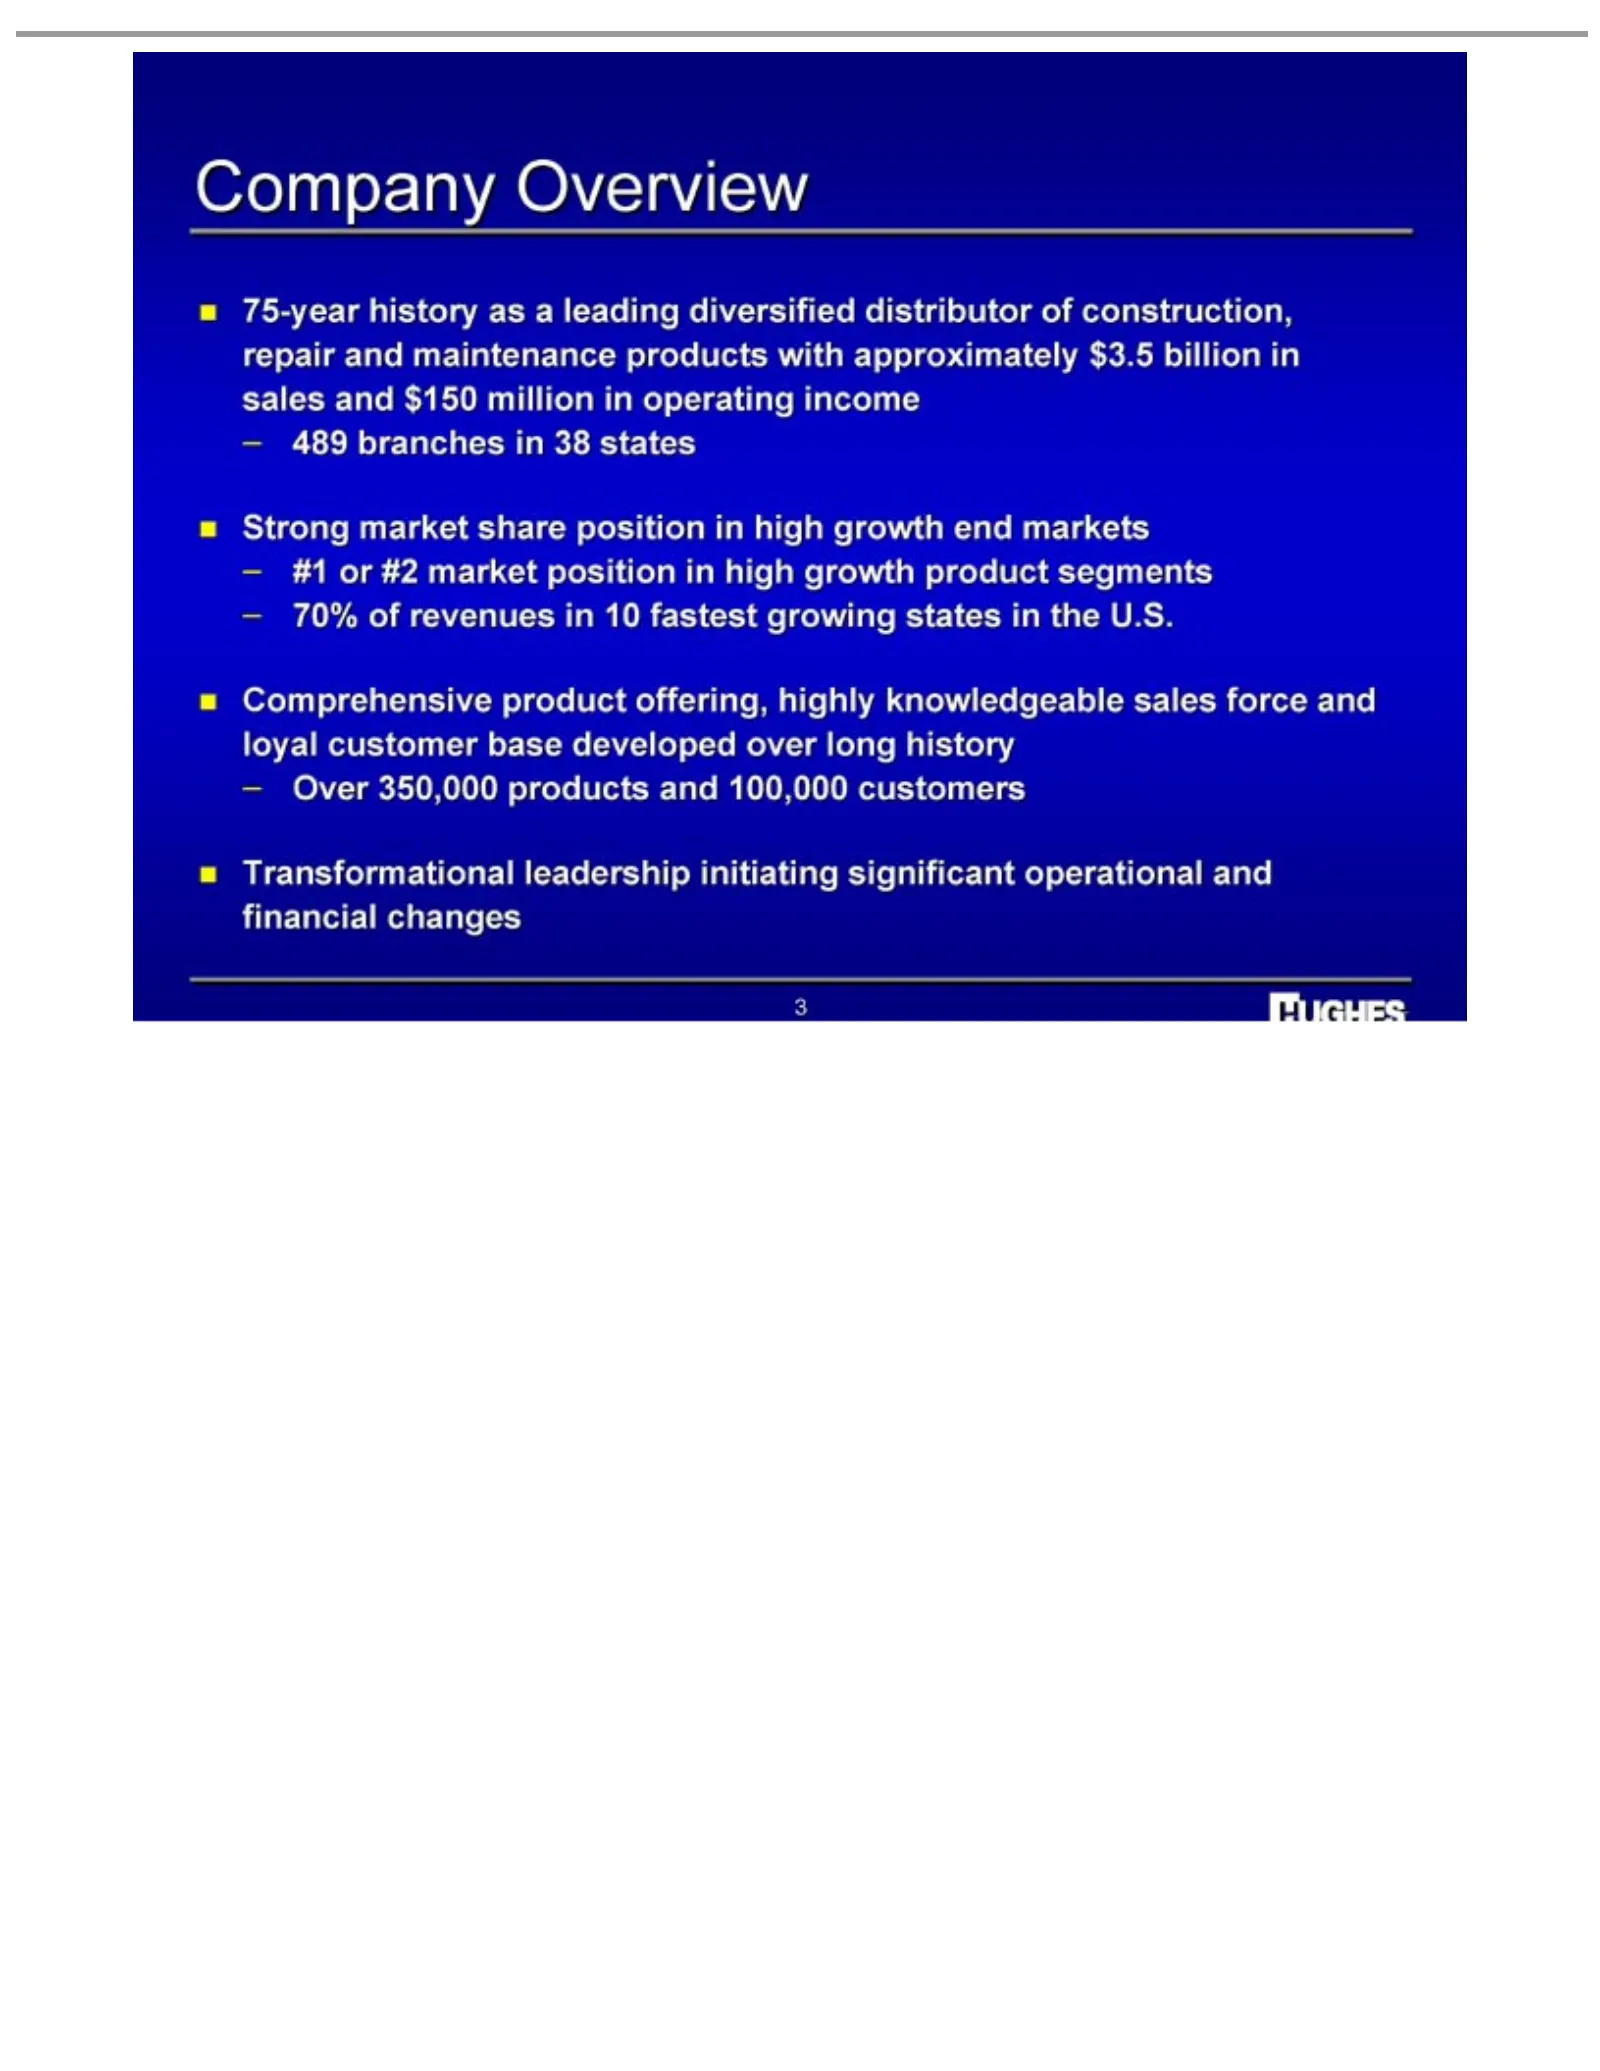
Slide 4: Company Overview
Company 75-year Strong Comprehensive – Transformational 3 489orbranches #1 70% Over of market 350,000 #2 history revenues Overview market share in as products product leadership 38 position ainleading position states 10 offering, fastest and indiversified initiating in high 100,000 growing high high
Slide 5: Key Investment Highlights
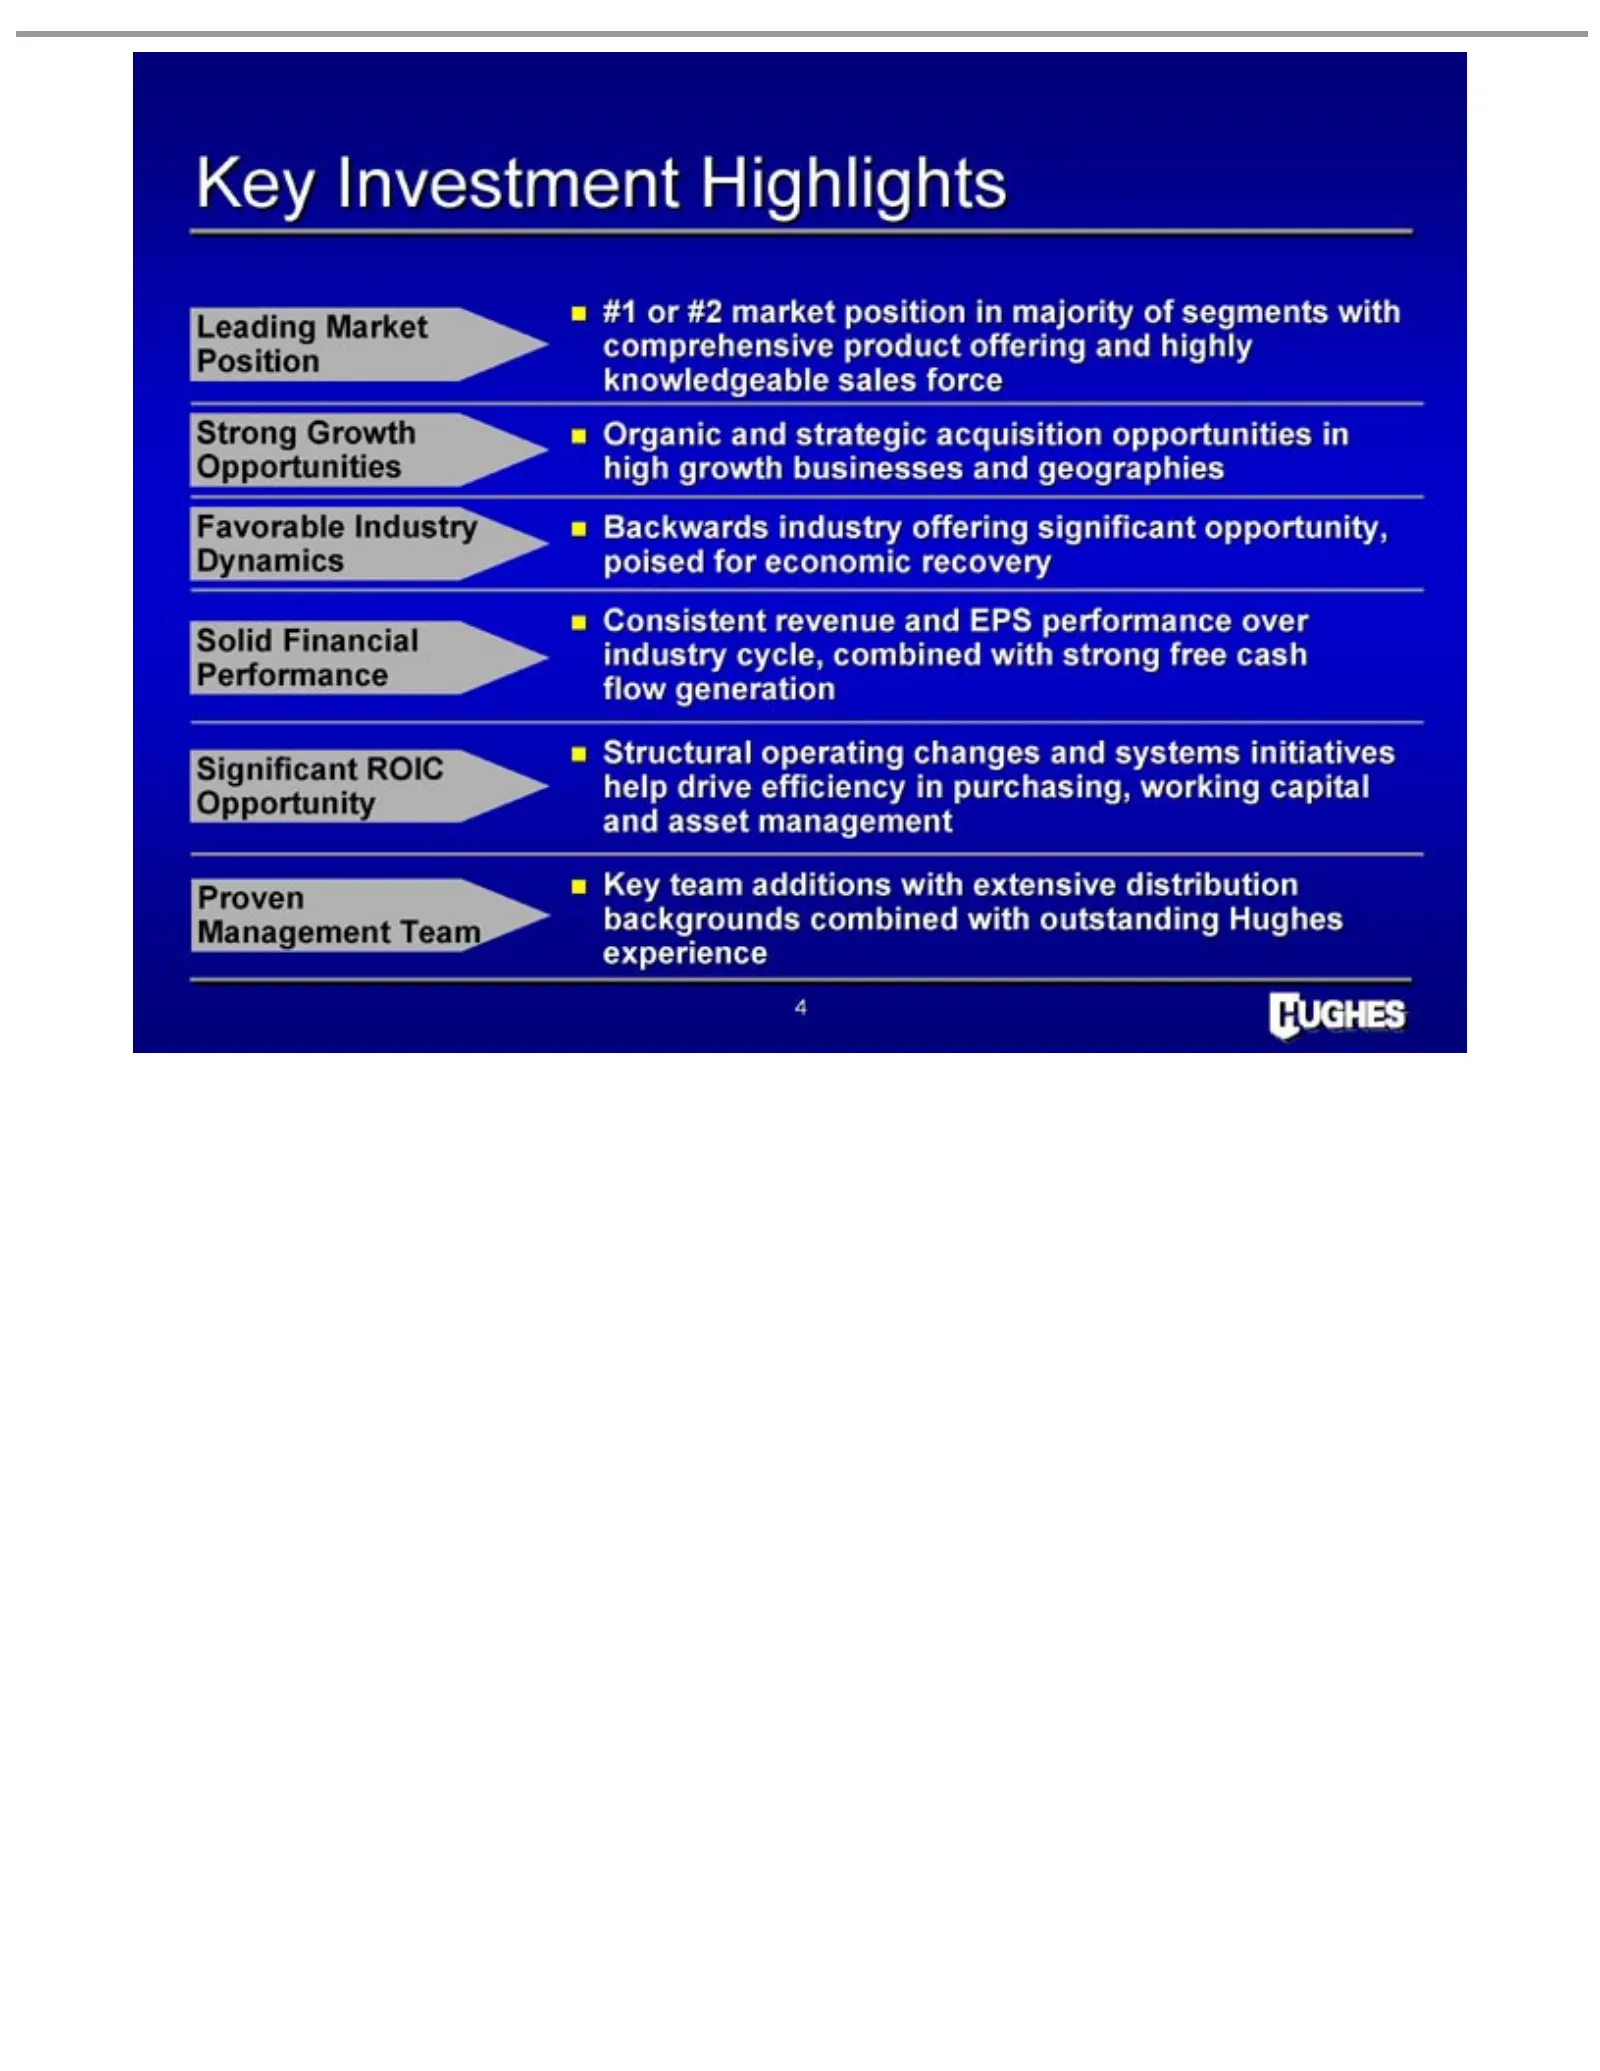
Keyorasset #1 Leading comprehensive knowledgeable Position Strong Opportunities Favorable Dynamics Consistent Solid Performance Structural Significant help and Opportunity Proven Management 4 experience Investment drive #2 Financial Growth Key Market market management operating Industry efficiency p
Slide 6: Transformational Leadership Team
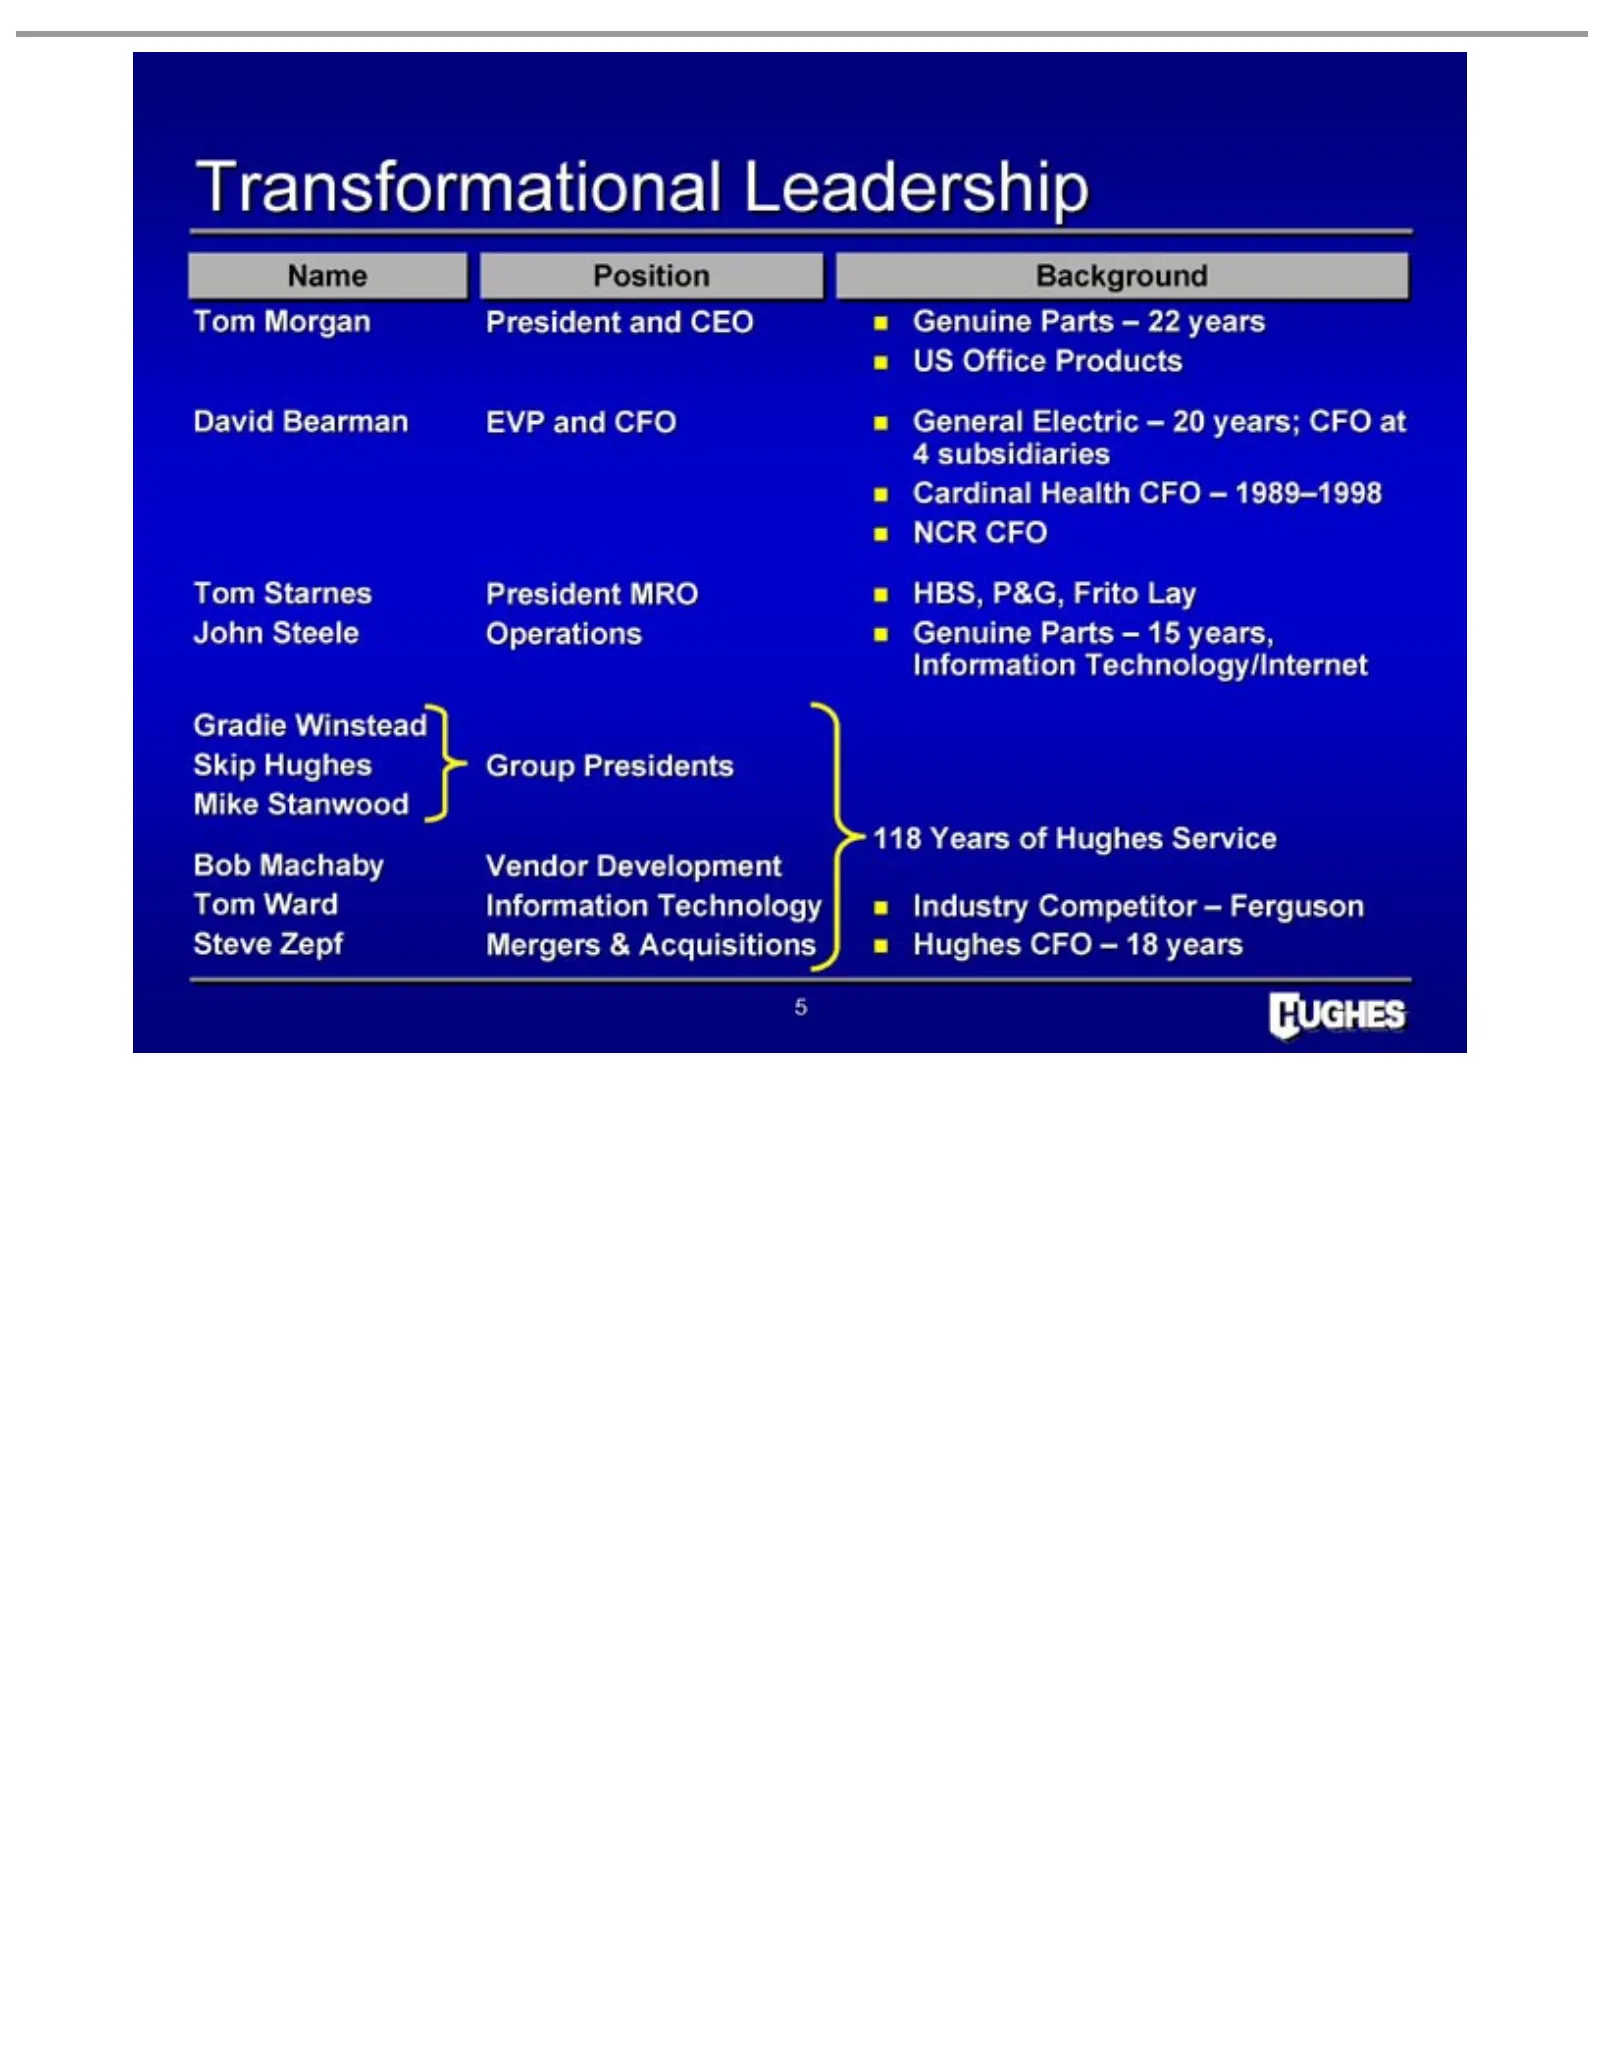
Transformational Name US David 4 Cardinal NCR John Information Gradie Skip Mike 118 Bob Tom Steve 5 subsidiaries Office Years Machaby Ward Morgan Starnes Hughes Steele CFO Stanwood Zepf Position Bearman Winstead Health of Products Information Mergers Operations Technology/Internet Hughes President G
Slide 7: Industry & Business Overview
Industry & Business Overview
Slide 8: Large, Highly Fragmented Market
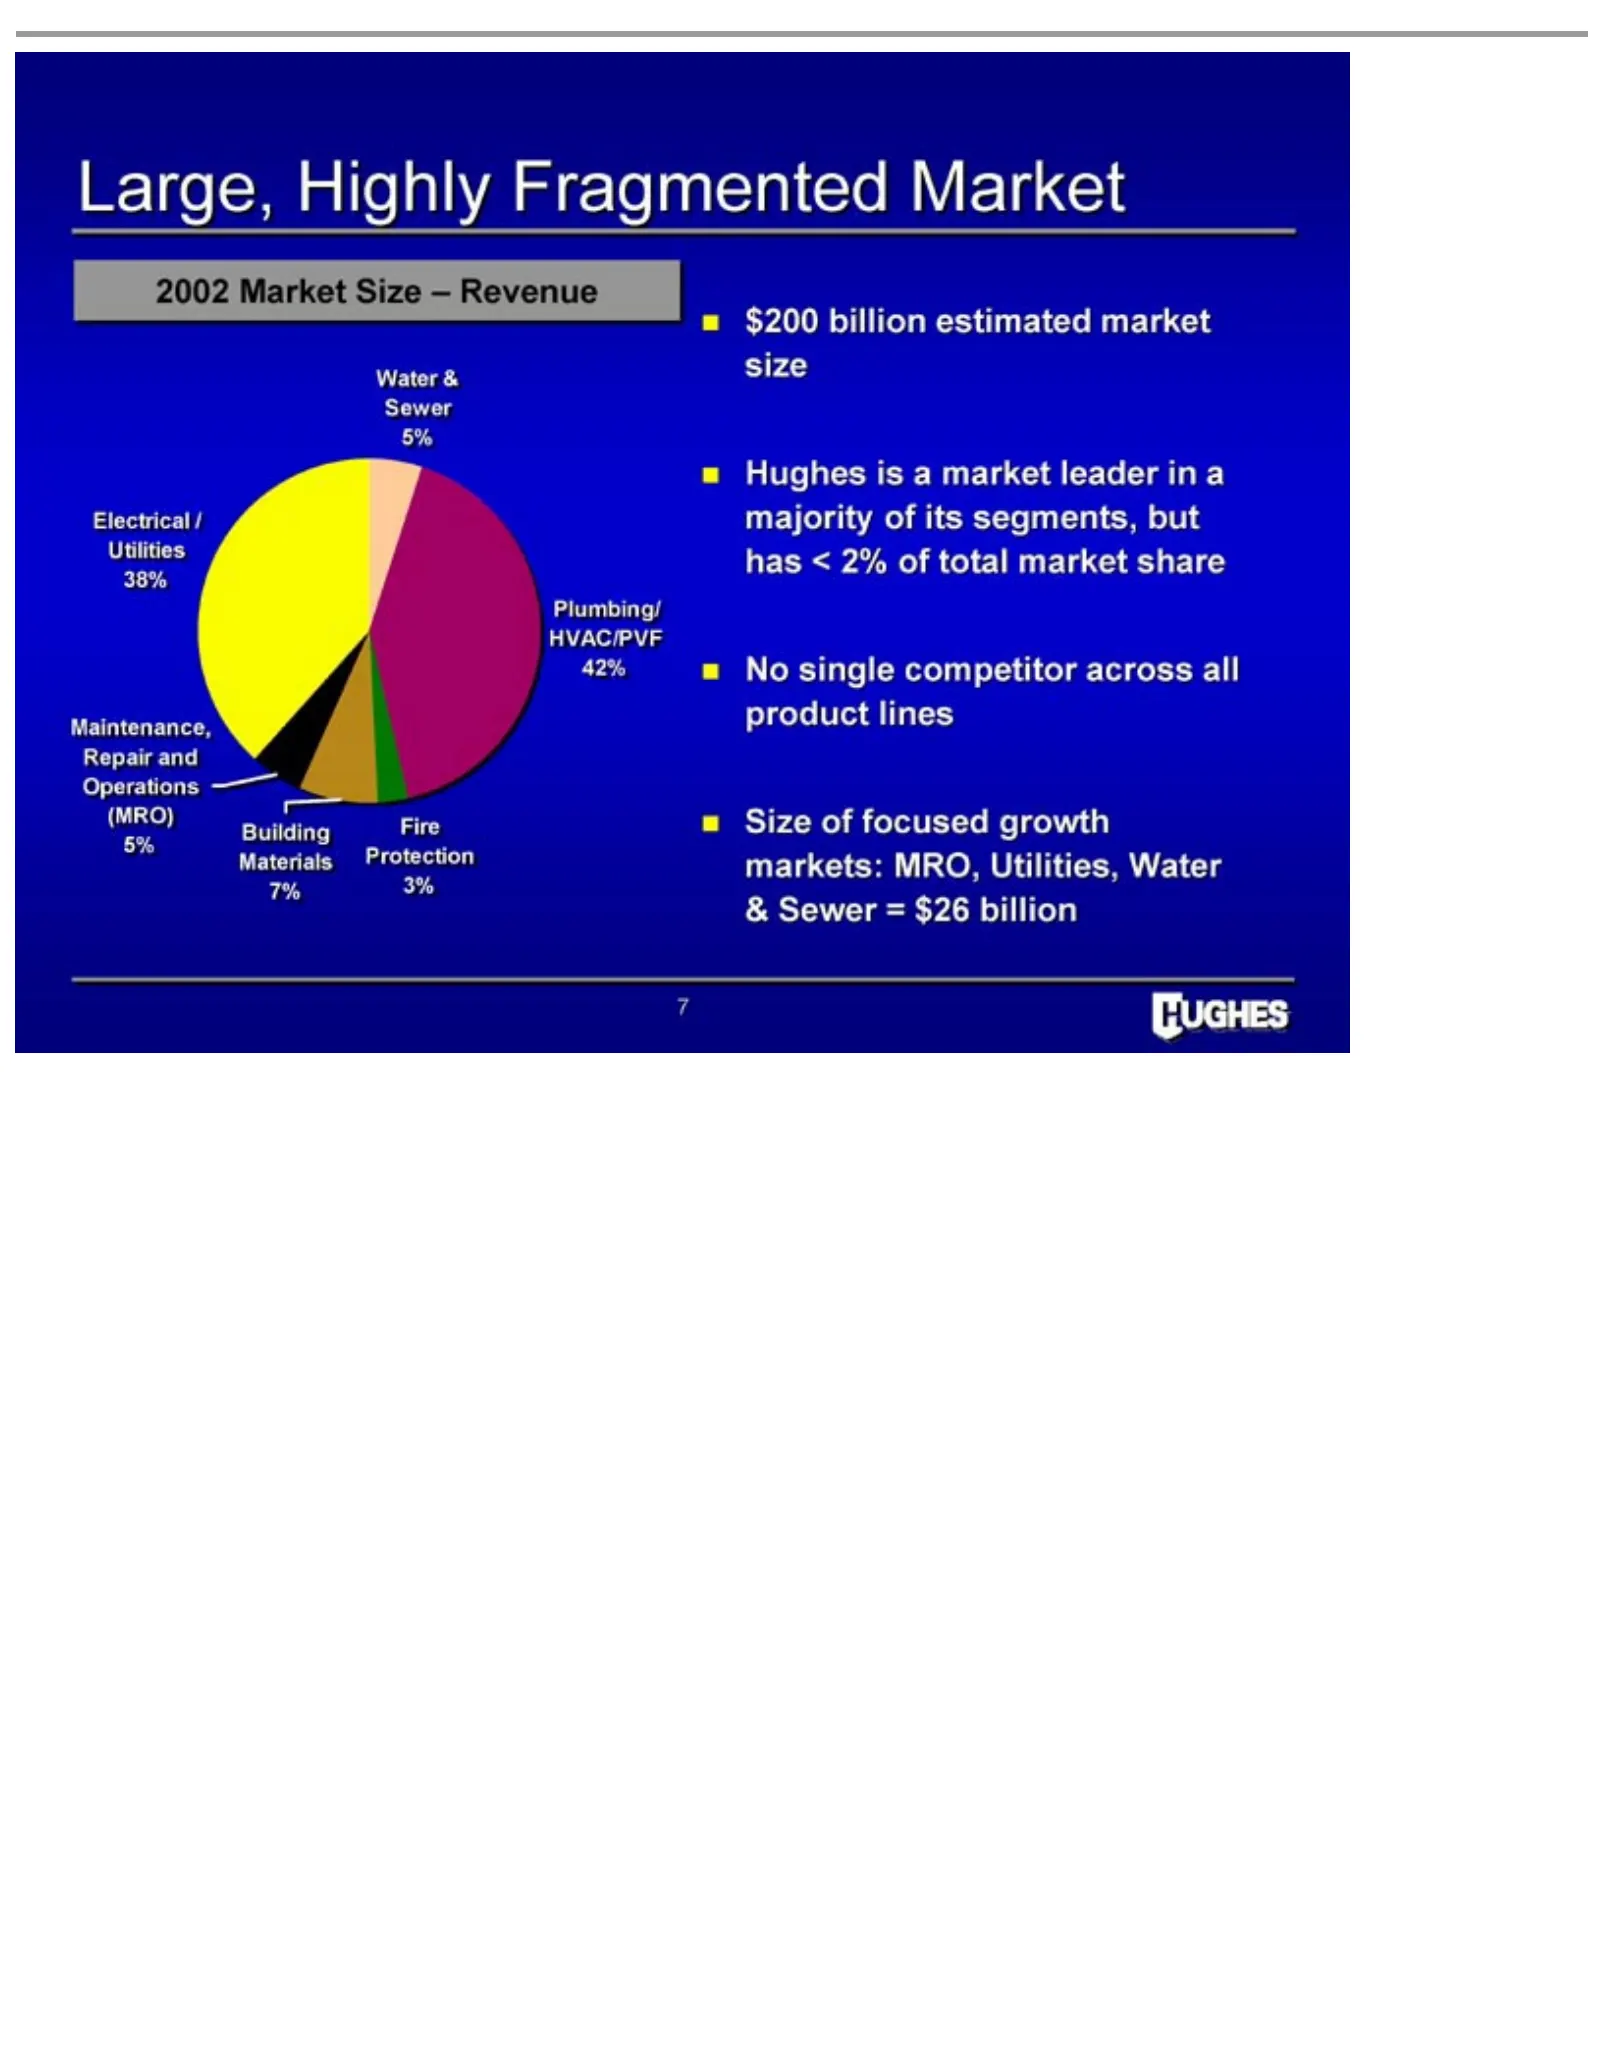
Large, 2002 Water S Hughes Electrical Utilities 42% HVAC/PVF Plumbing/ 38% product Repair Maintenance, (MRO) Operations Building Materials 5% 7% & 7 ewer Sewer 3%No Market & Highly and Size lines is has single size Fire =Protection /a$26 /market <majority of Size Fragmented 2% competitor focused bil
Slide 9: Attractive Industry Trends / Poised for Economic Recovery
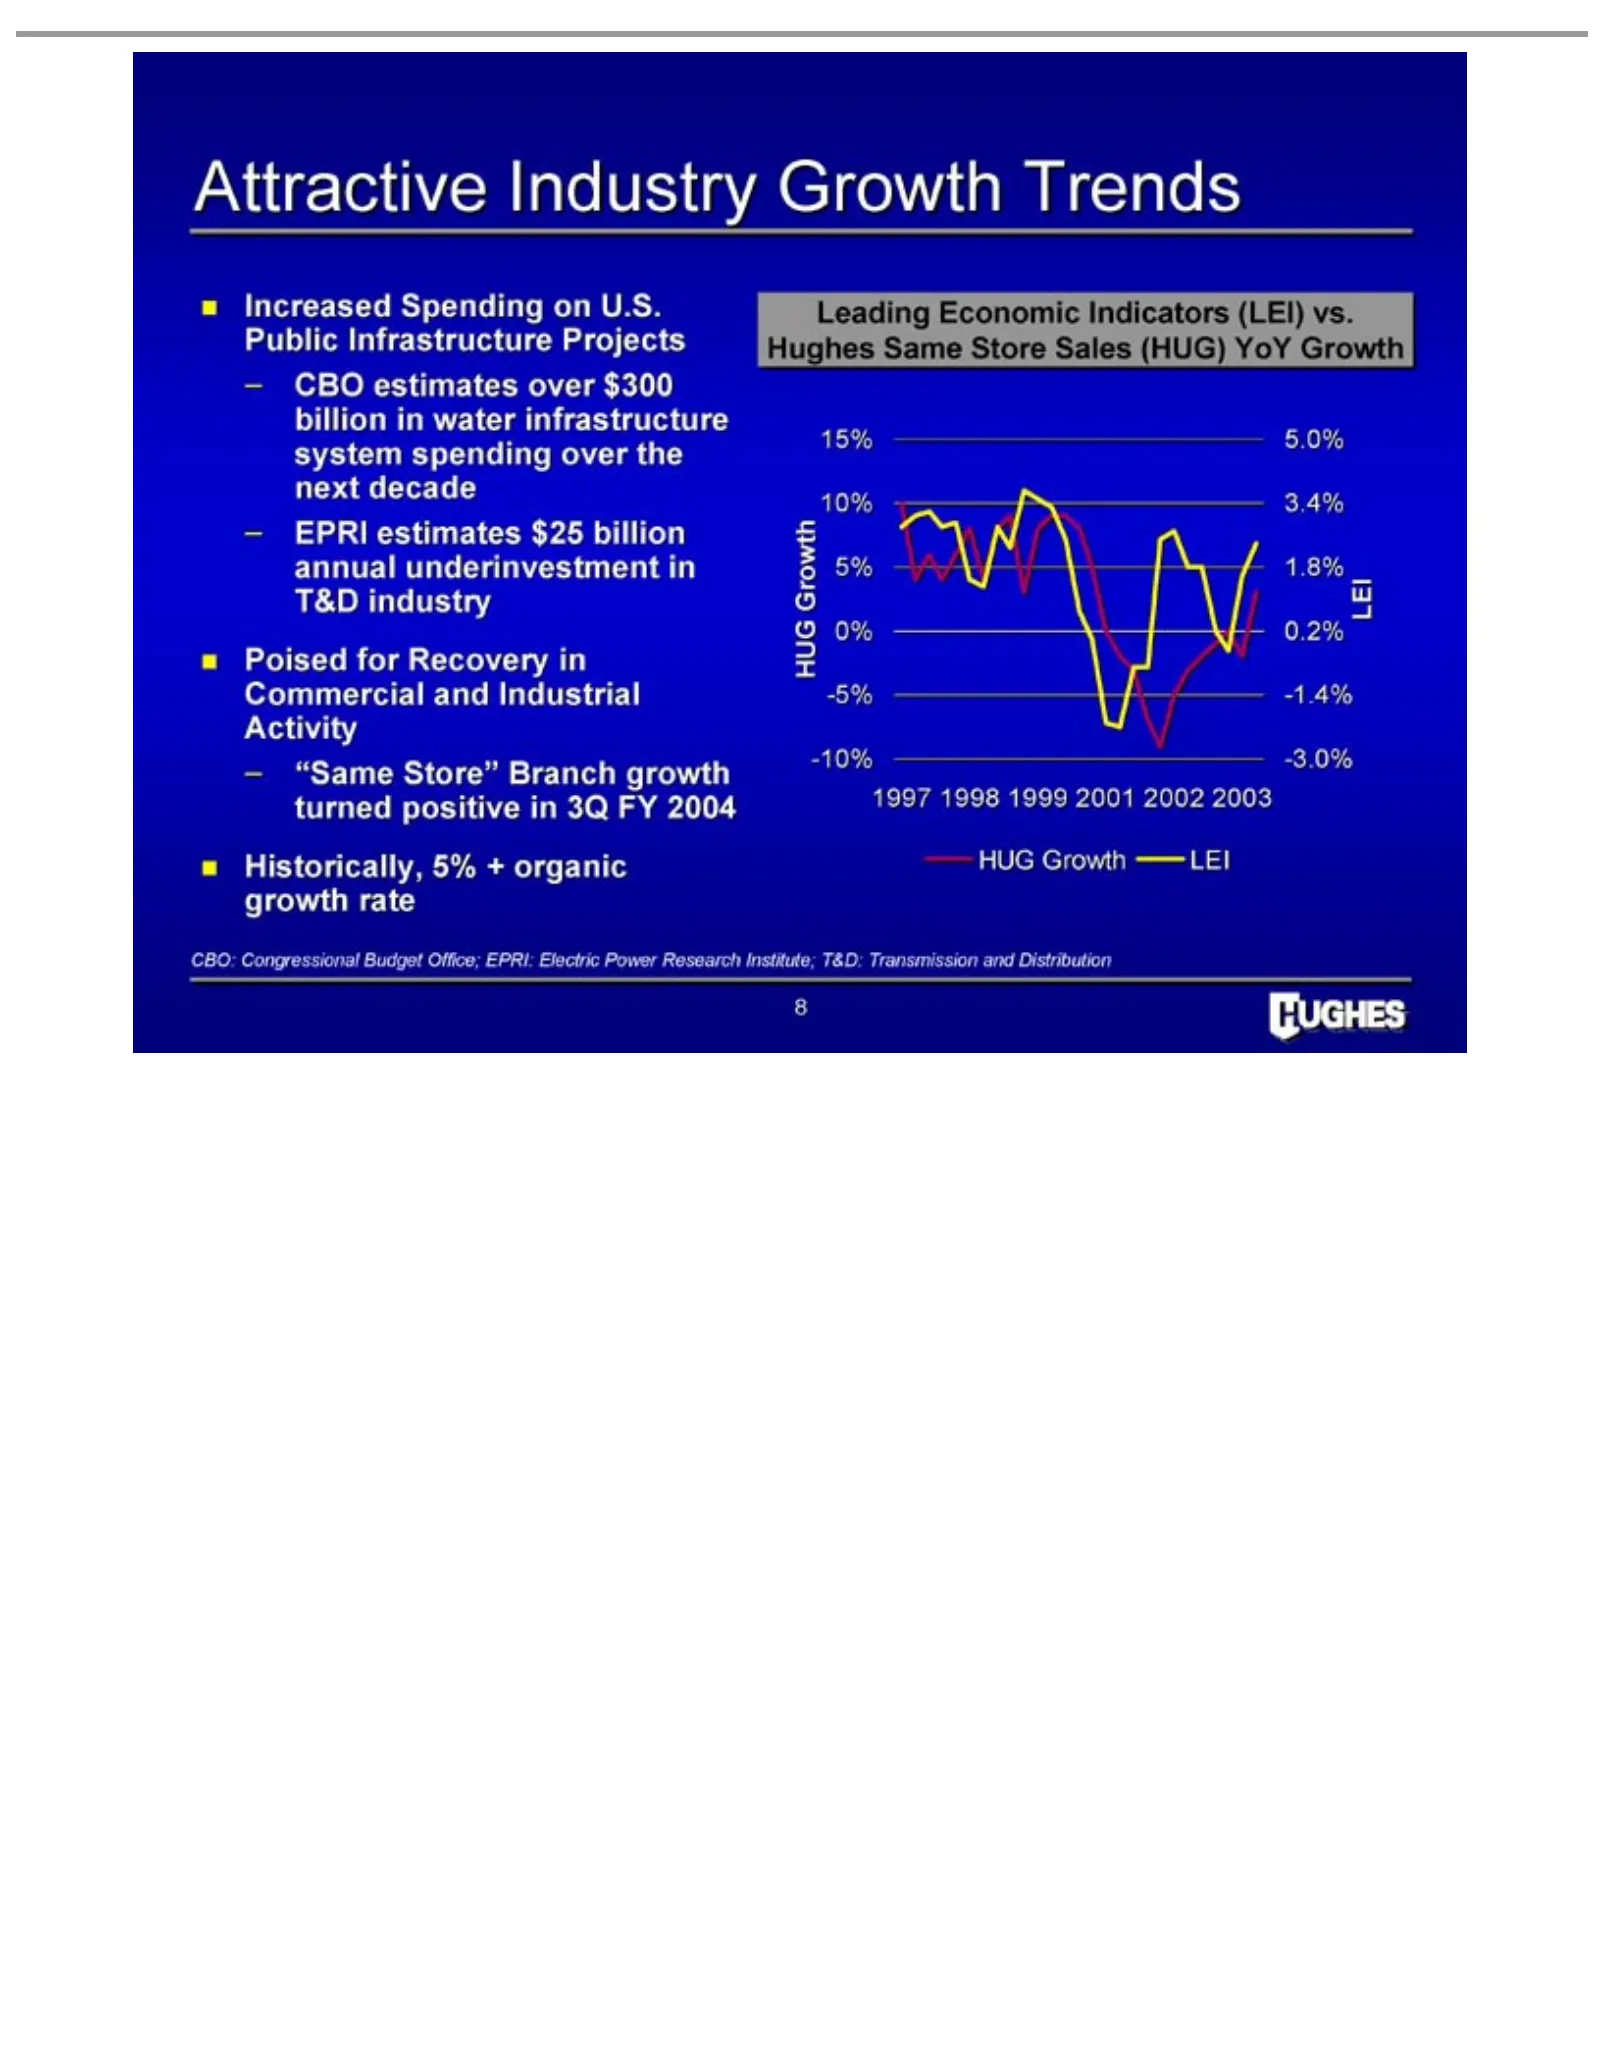
Attractive Increased Poised – Historically, Leading CBO: 8 CBOCongressional EPRI “Same for estimates estimates Economic Store” Spending Industry Recovery 5%Branch +over $25 organic Indicators Growth on in Budget billion $300 U.S. Commercial growth growth Trends billion Public Office; annual (LEI) tu
Slide 10: Strong Projected Population Growth in Focused Markets
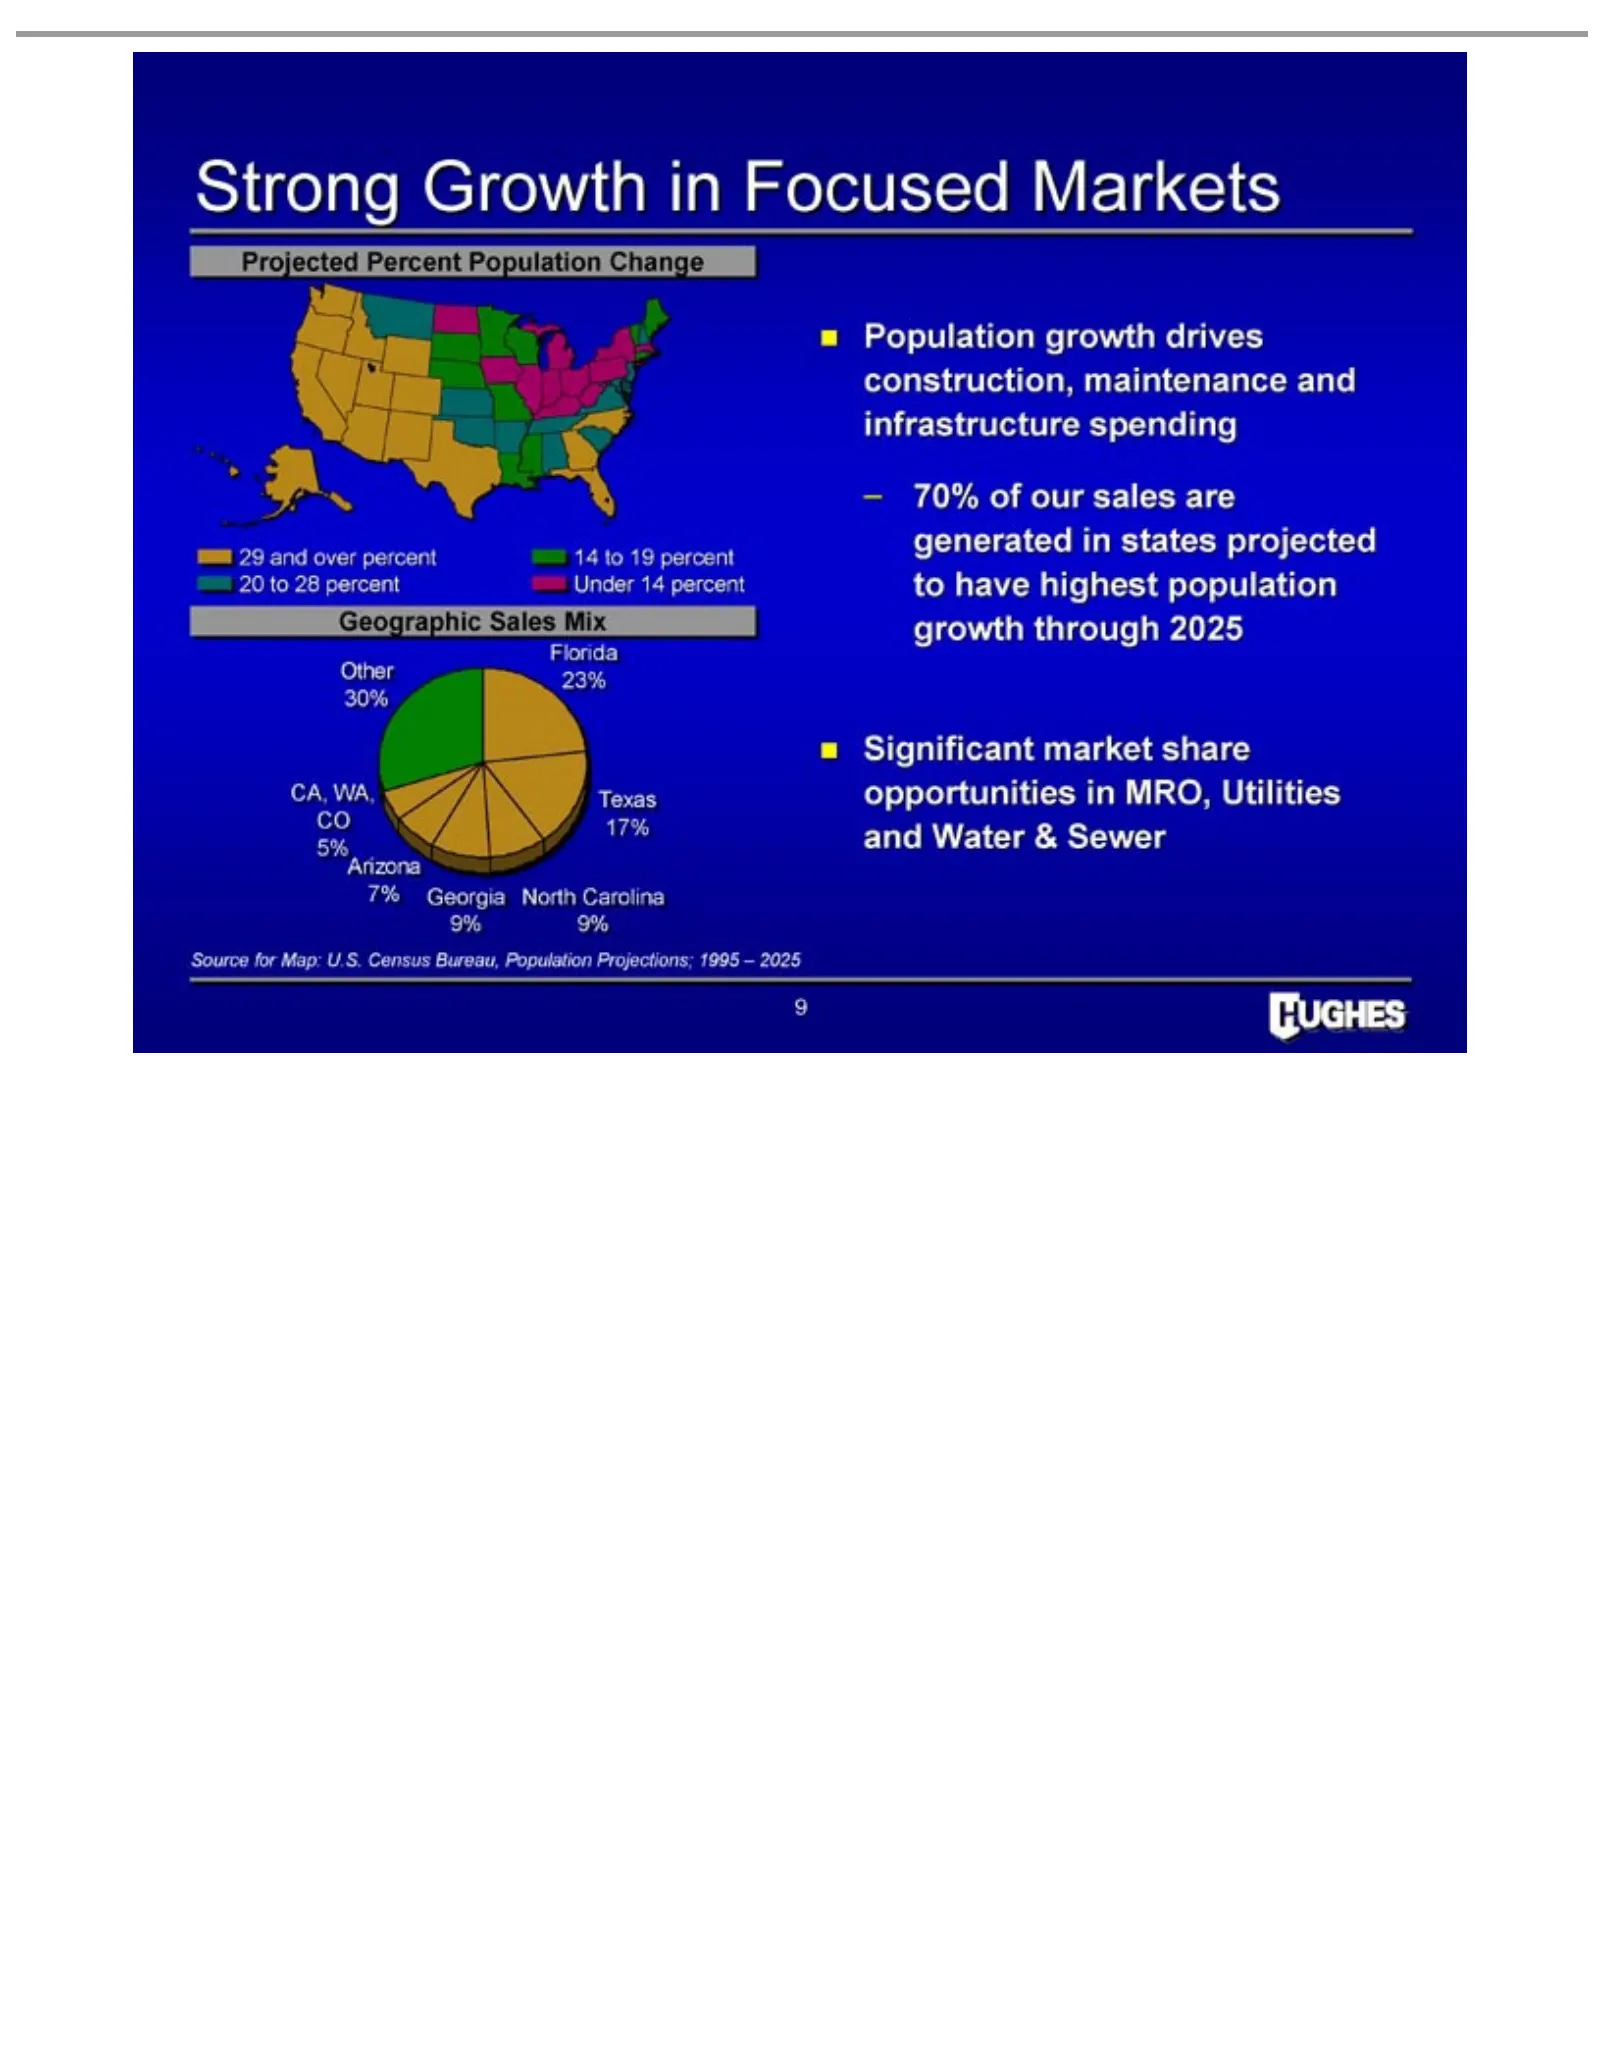
Strong Projected 29 Geographic Population – Significant Source 9 70% and of Growth over forour Percent Map: growth market Sales percent sales inU.S. Focused Population Mix share drives are 14Census generated toopportunities construction, 19 Markets percent Change Bureau, in states 20 Population in m
Slide 11: Leading Geographic and Product Market Positions
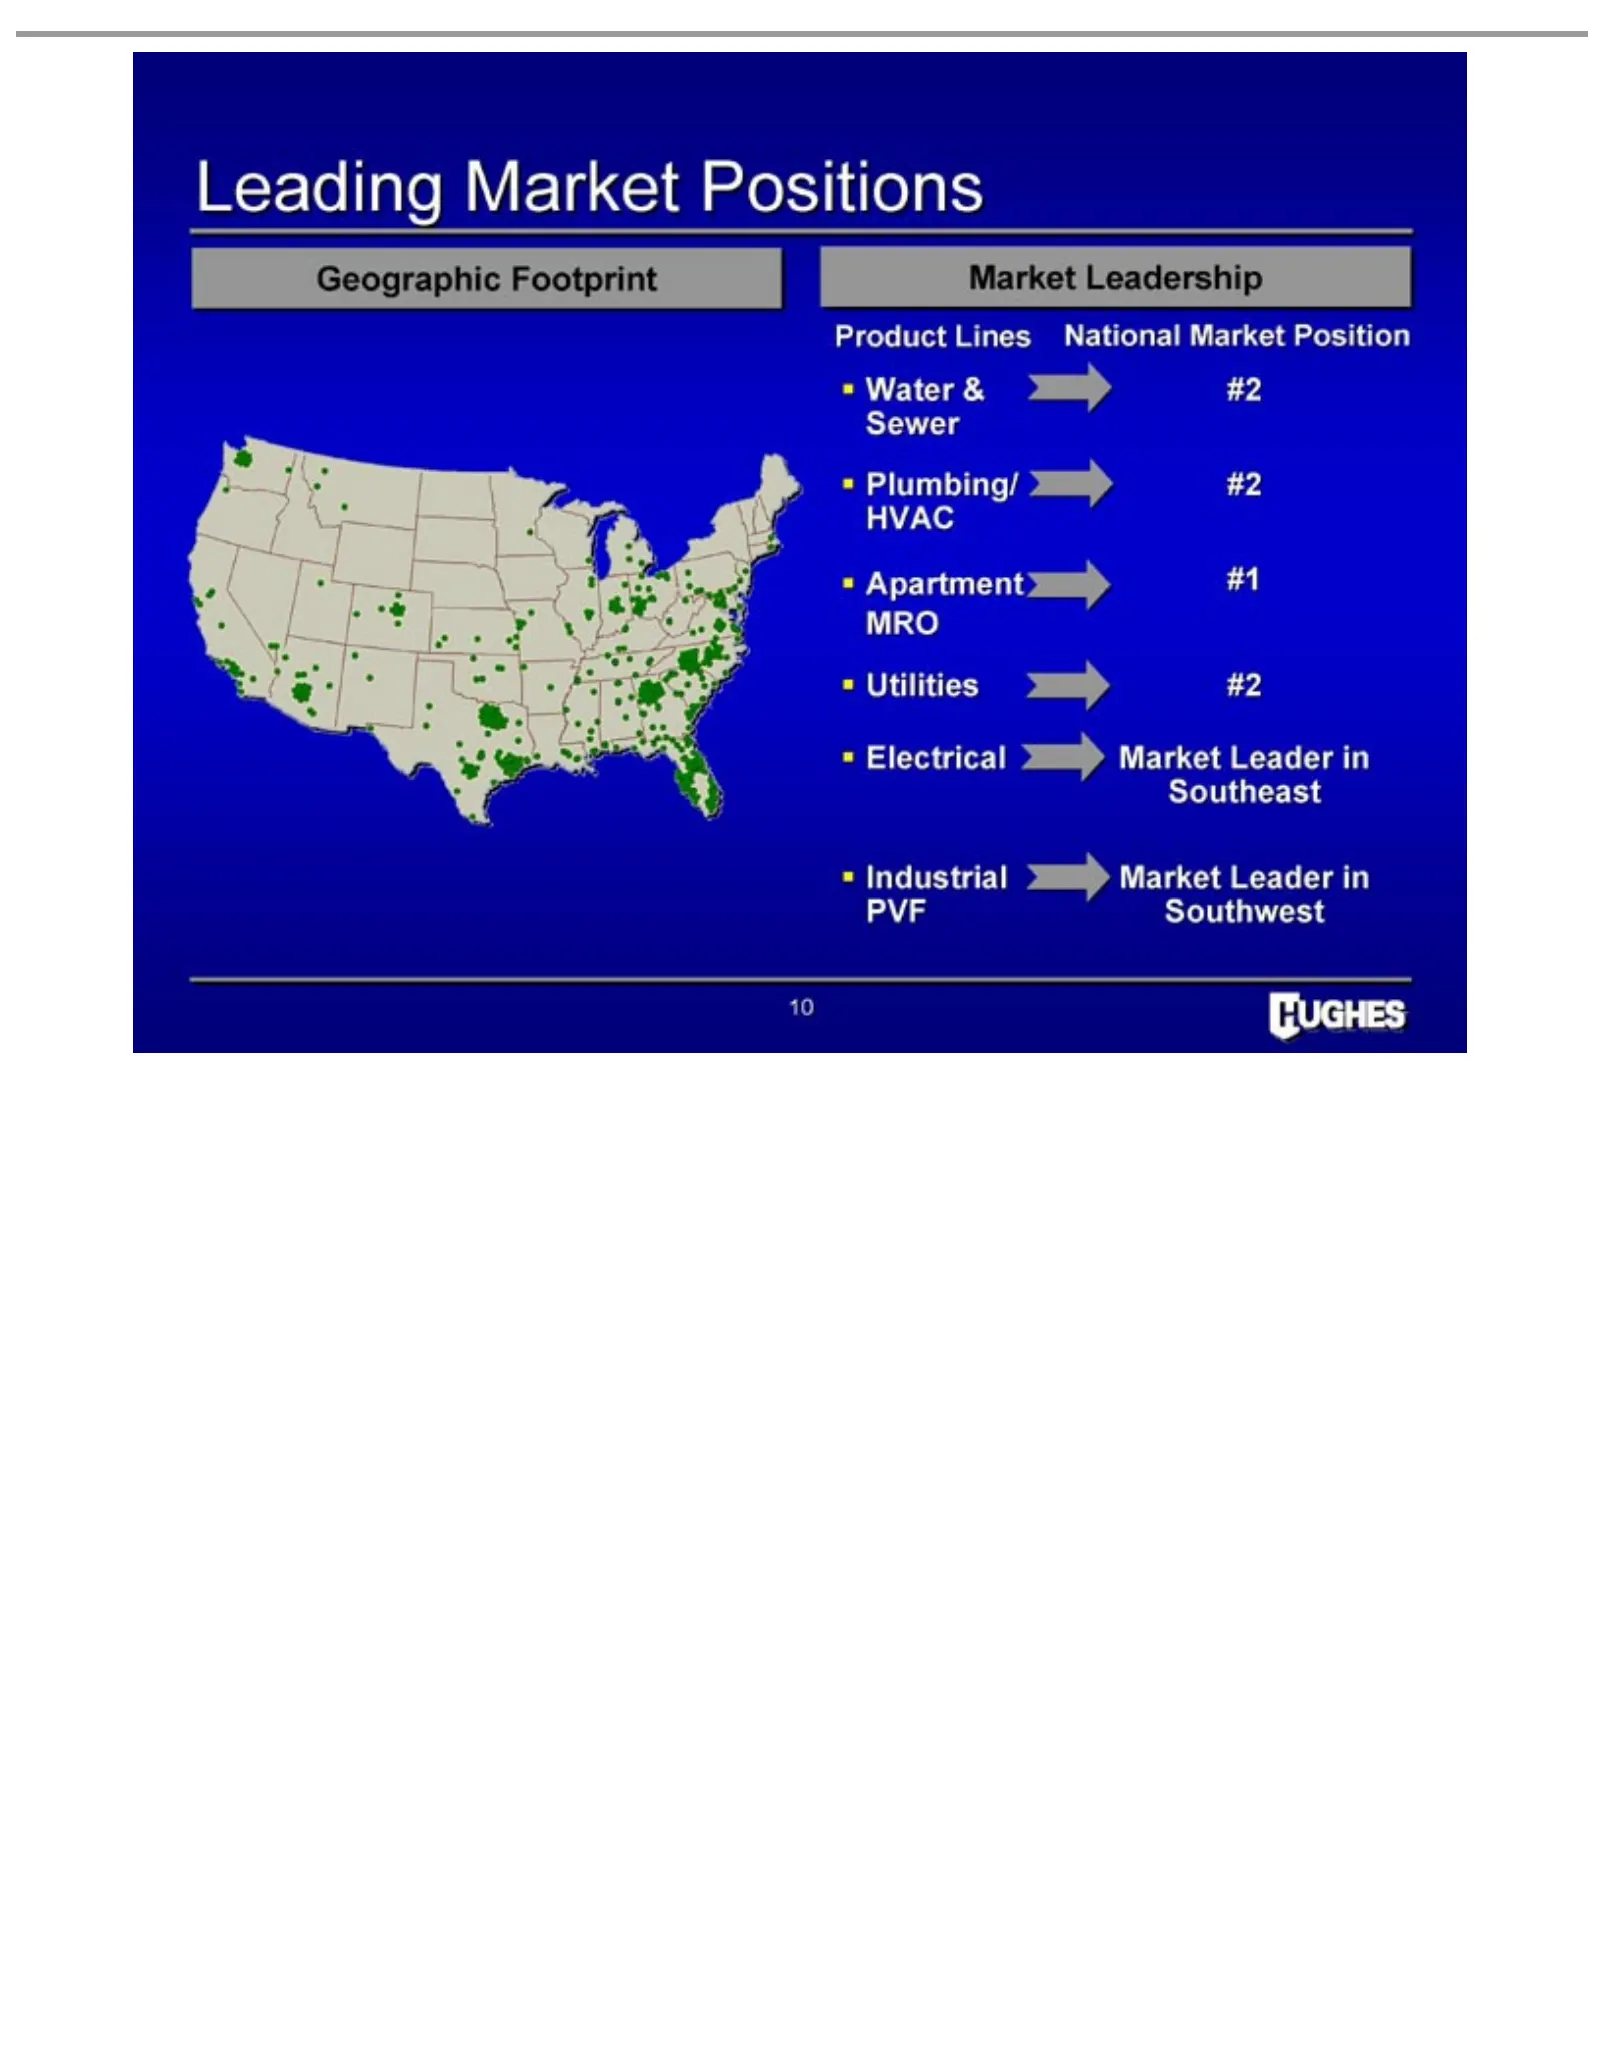
Leading Geographic Market Product Water Plumbing/ Sewer Apartment HVAC Utilities MRO Electrical Industrial Southeast PVF 10 Southwest &Leadership Lines #2 Market #2 Market #2 #1 Footprint National Positions LeaderMarket in Position
Slide 12: Diverse Pro Forma End Markets and Product Portfolio
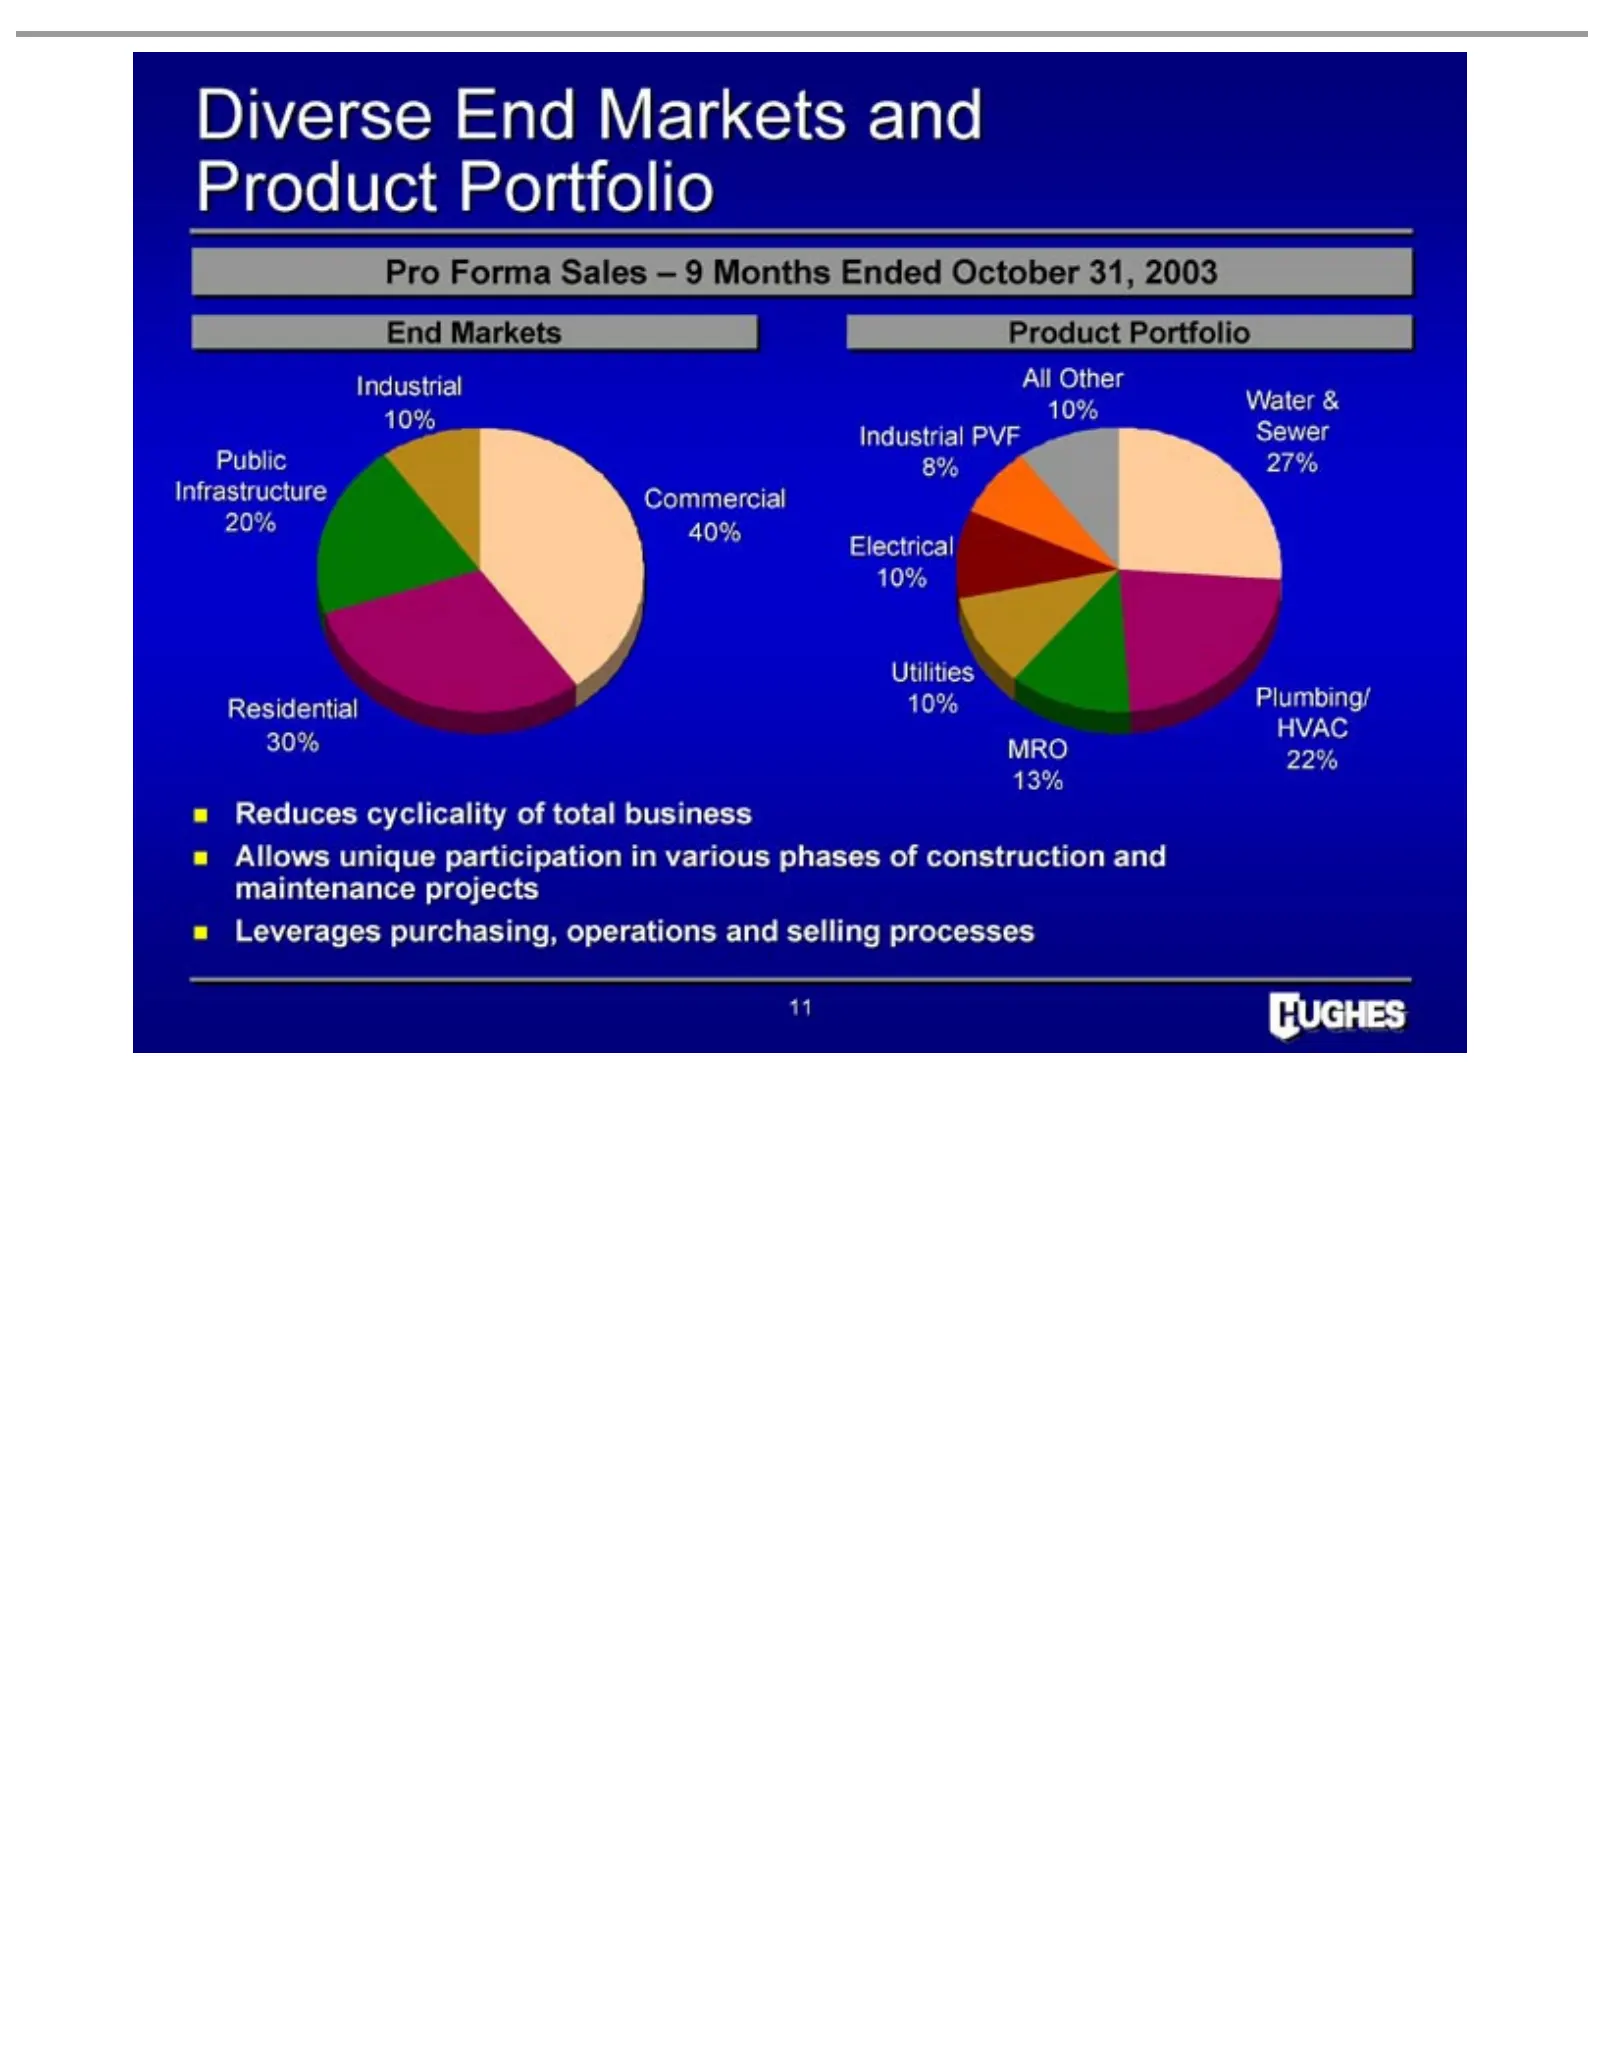
Diverse Pro End Industrial Public Infrastructure 20% Residential Utilities 10% Electrical 30% HVAC Reduces 13% 22% Allows Leverages 11 Forma Markets Water 40% MRO 8% unique End cyclicality All PVF purchasing, 27% Sales & 10% Markets Product Other Commercial participation Sewer Plumbing/ – 9of Months
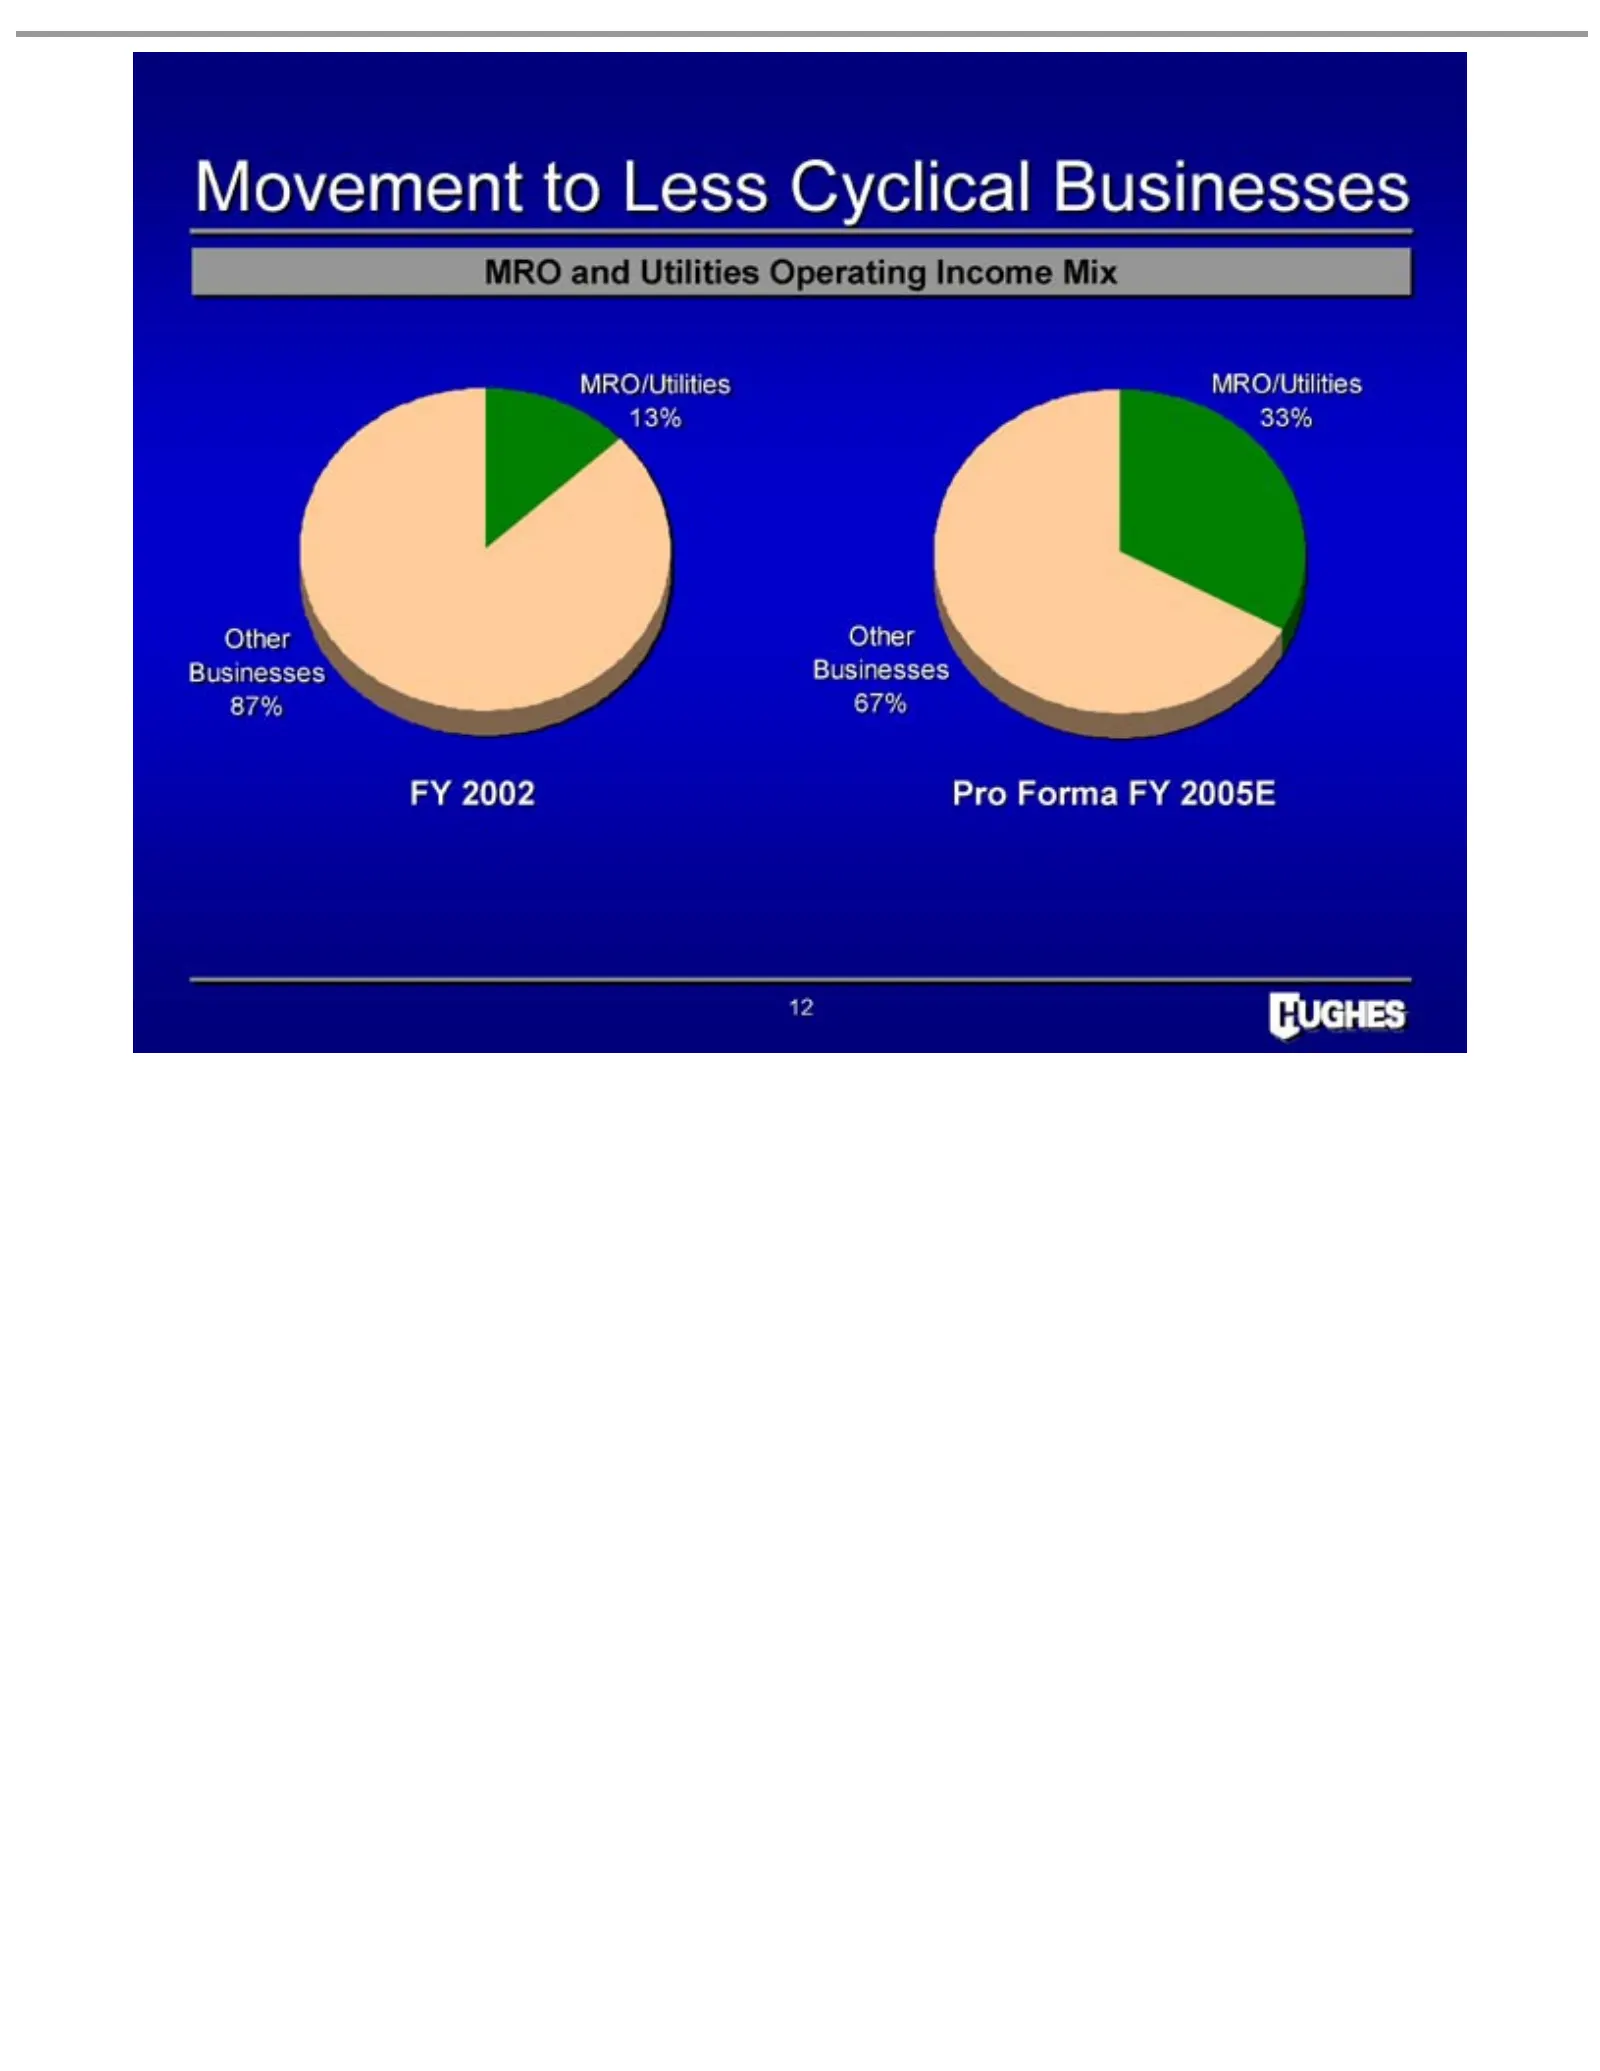
Slide 13: Movement to Less Cyclical MRO/Utilities Businesses
Movement MRO MRO/Utilities 13% Other Businesses 87% FY 12 2002 33% 67% Other andPro Utilities to Businesses Forma Less MRO/Utilities Cyclical Operating FY 2005EBusinesses Income Mix
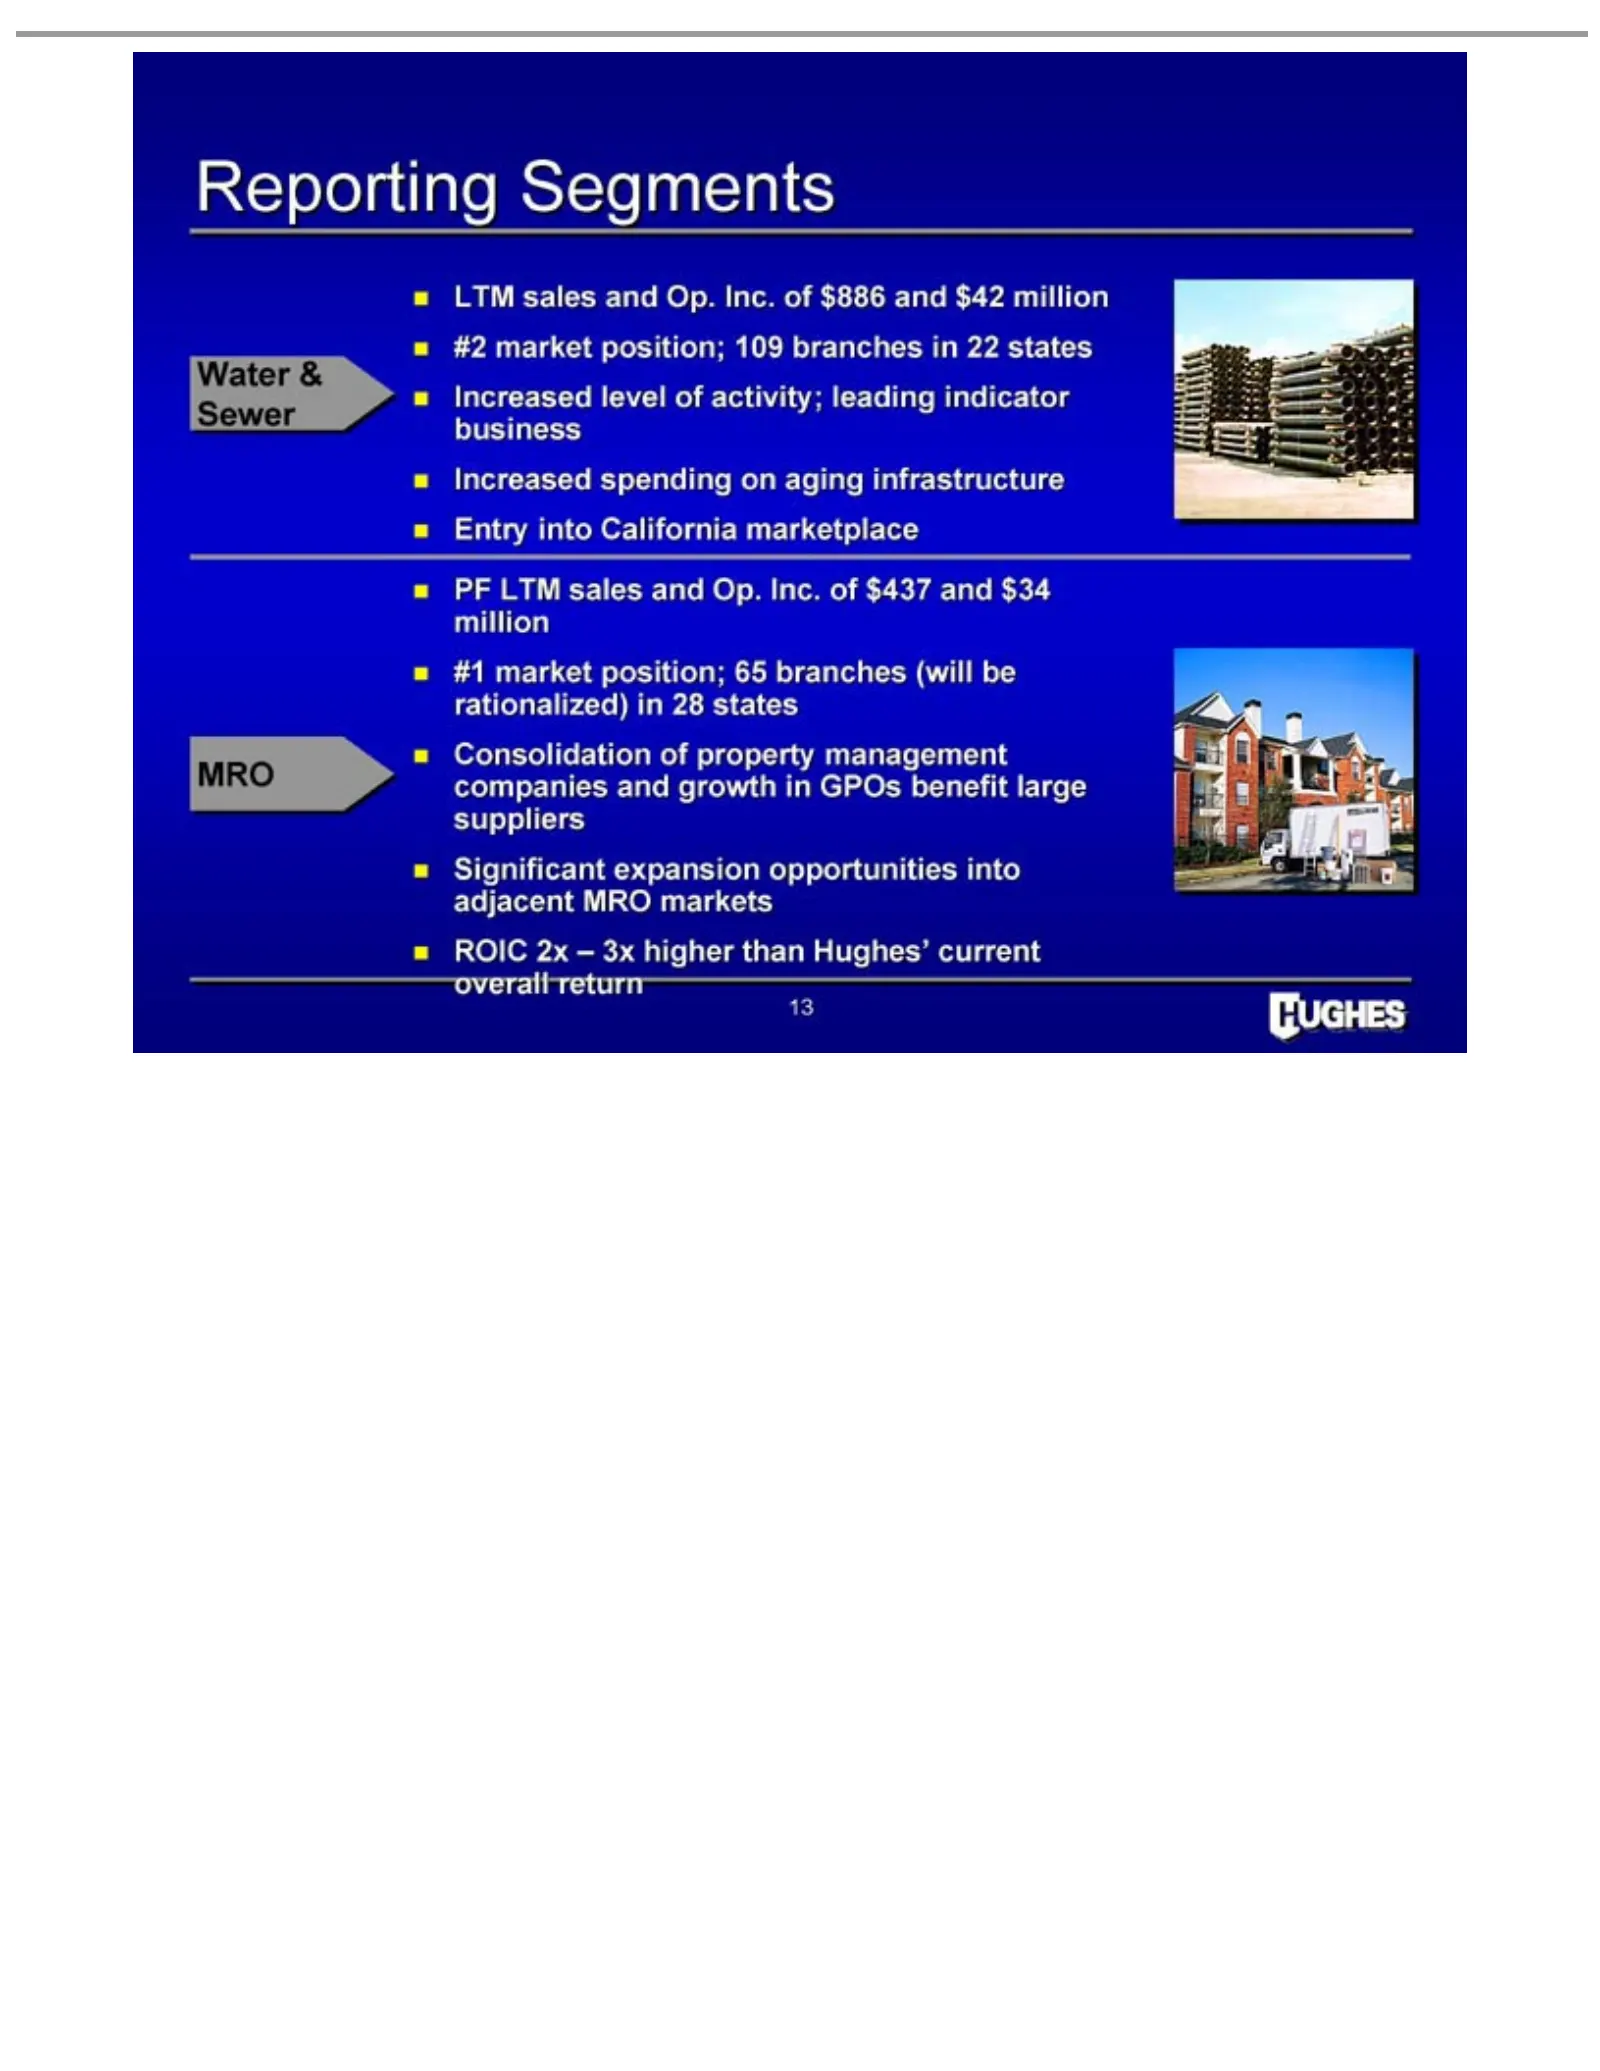
Slide 14: Reporting Segments: Water & Sewer
Reporting LTM #2 Water Increased business Sewer Entry PF #1 rationalized) Consolidation companies MRO Significant adjacent ROIC overall 13 market LTM sales into suppliers & 2x return MRO sales –spending level Segments position; California and expansion 3xinand of higher markets EBIT growth of 28prop
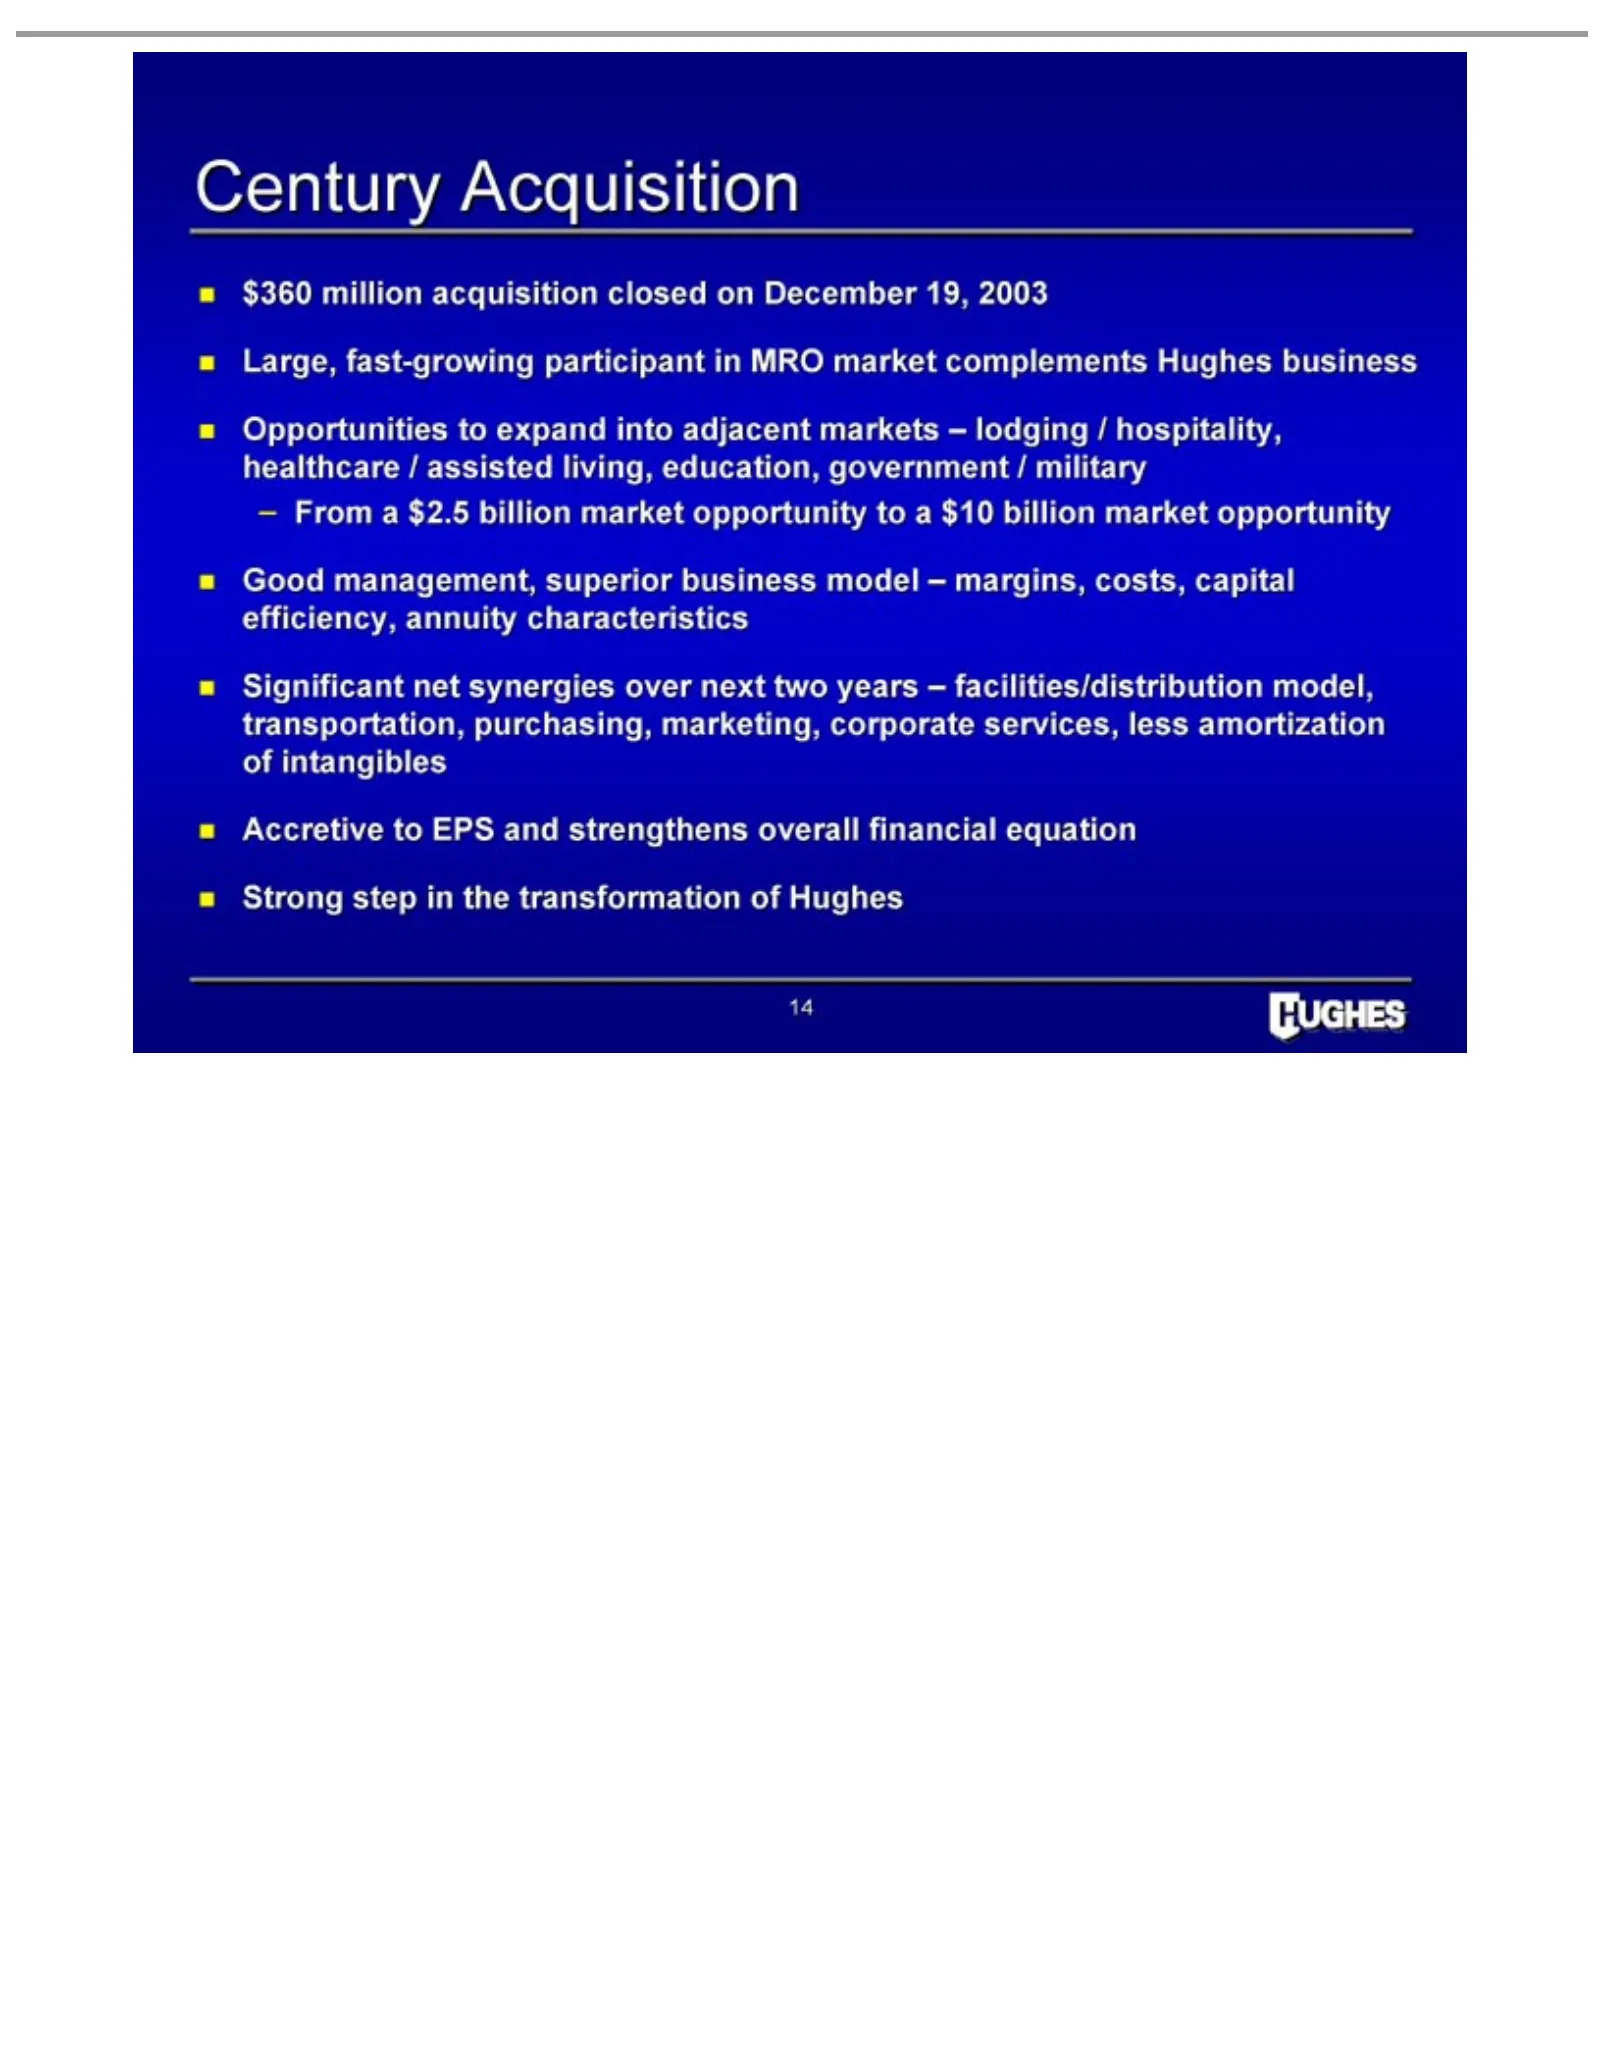
Slide 15: Century Acquisition
Century $ Large, Opportunities – Good Significant Accretive Strong 14360 management, Frommillion fast-growing step aAcquisition $2.5 tonet inEPS acquisition to the billion synergies expand and transformation superior participant market strengthens into over closed business adjacent opportunity next
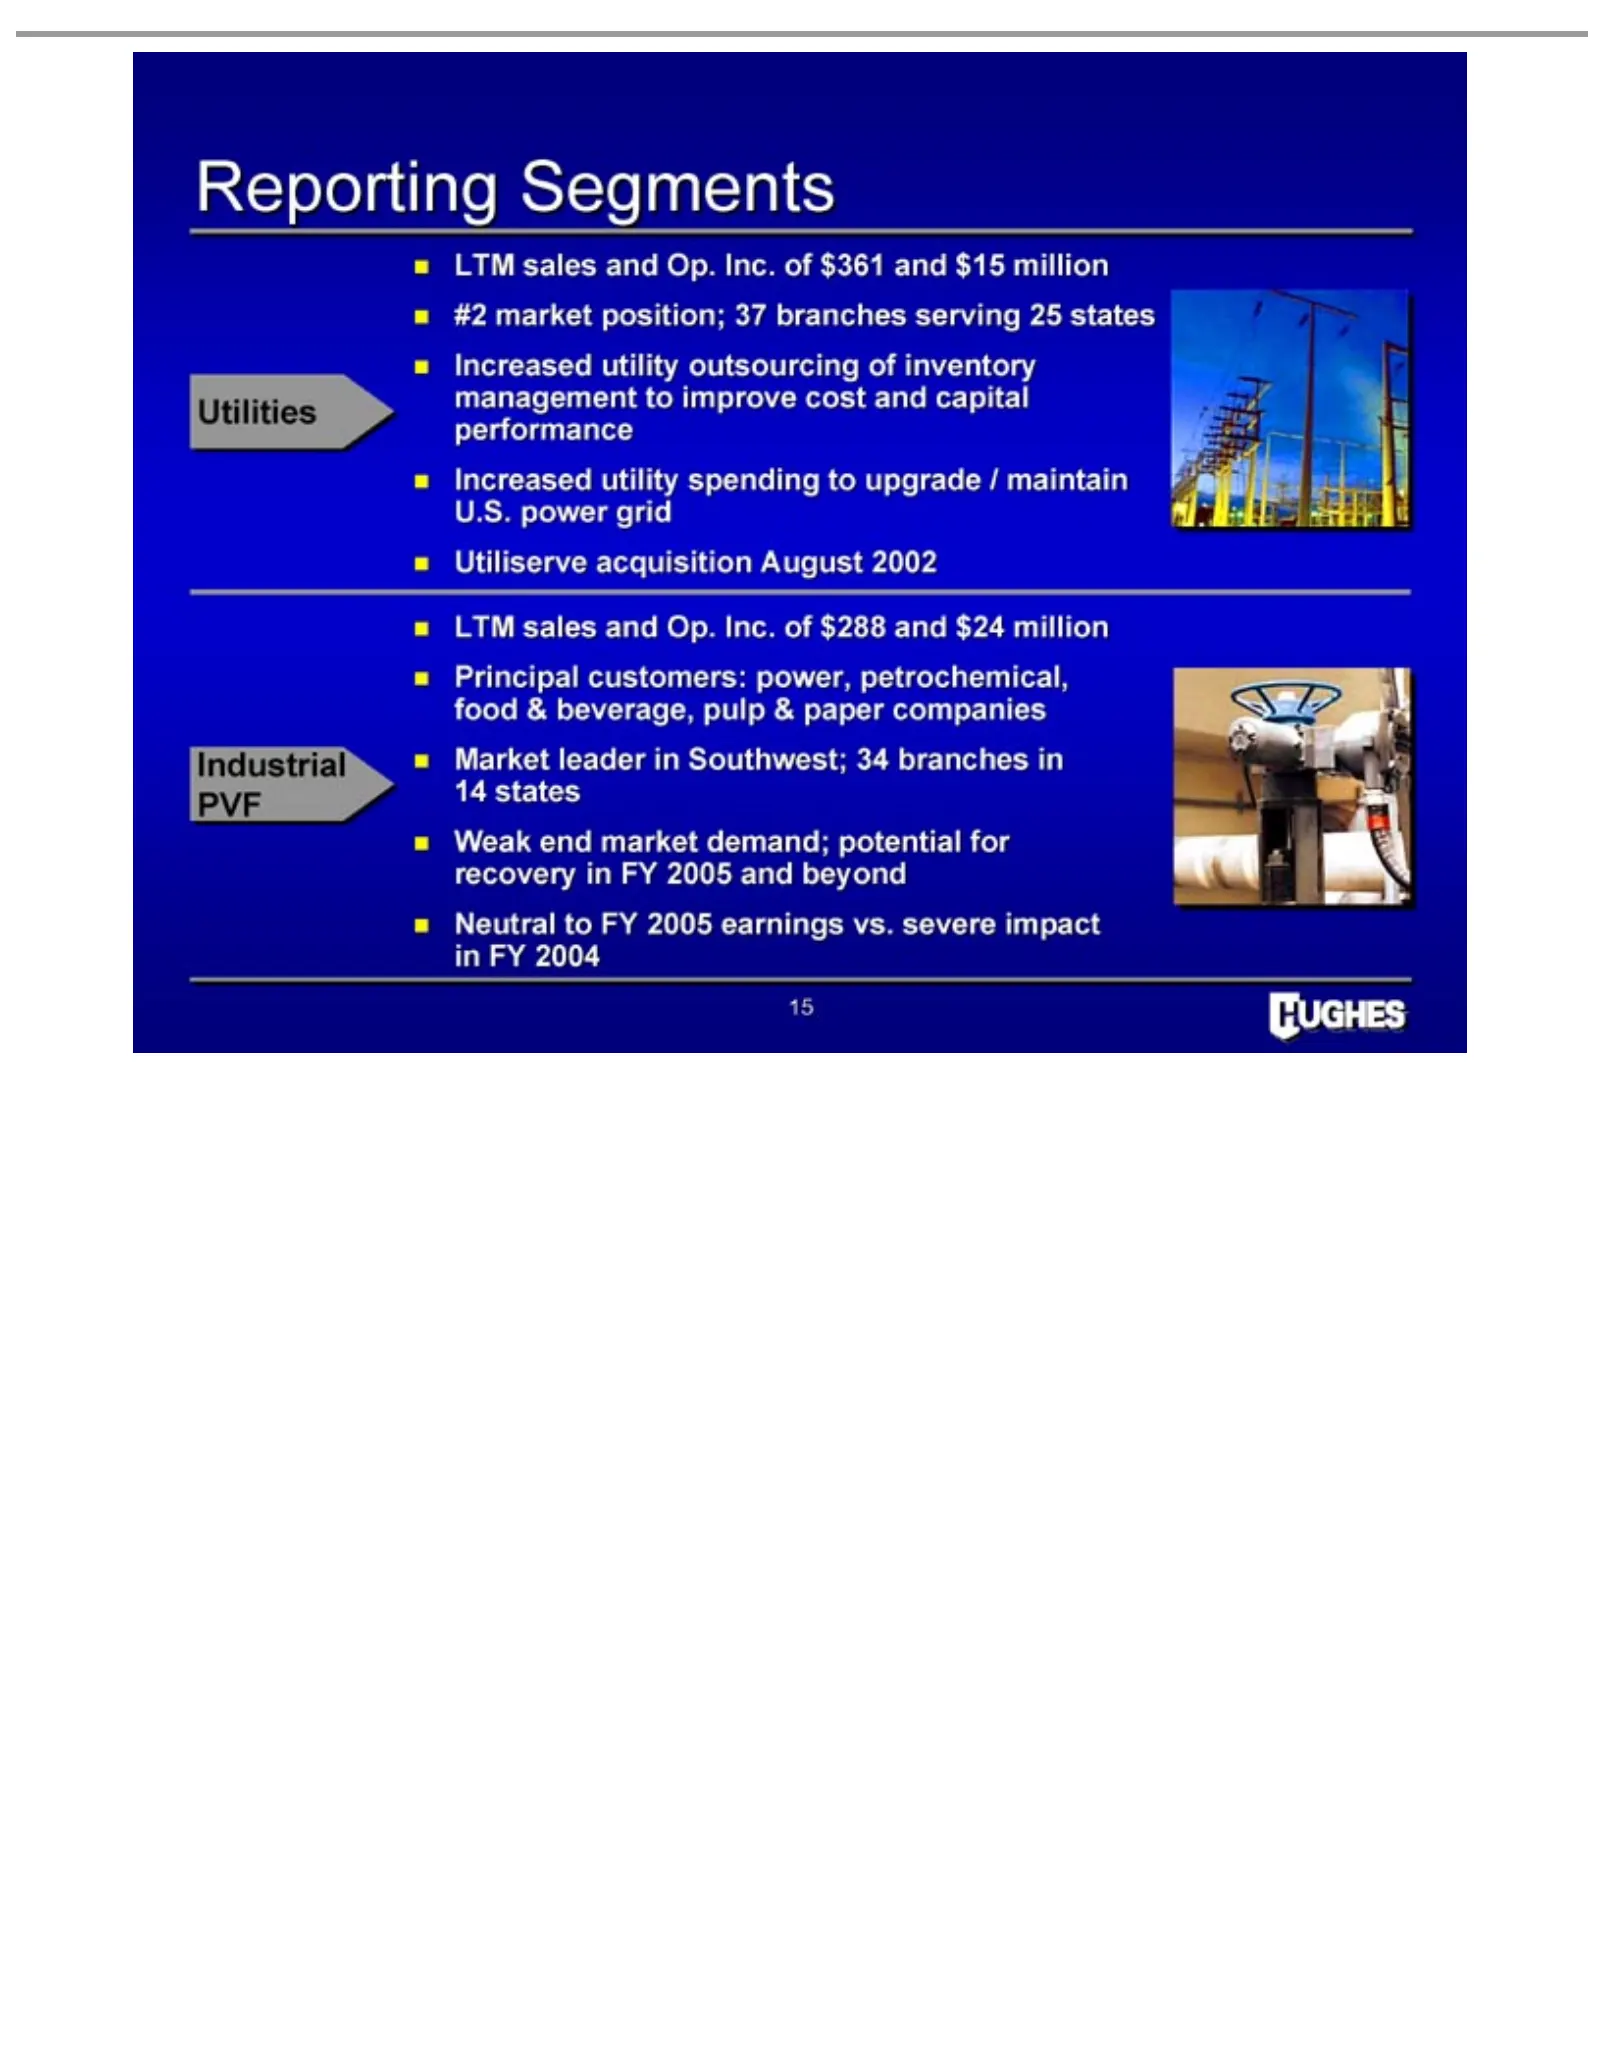
Slide 16: Reporting Segments: Utilities
Reporting #2 Utilities Increased performance U.S. Utiliserve LTM Principal food Industrial PVF Weak recovery Neutral in 15 FY market power & 14 sales end 2004 beverage, to states management in customers: utility Market acquisition market Segments position; FY and FY grid 2005 EBIT 2005 outsourcing s
Slide 17: Reporting Segments: Plumbing/HVAC
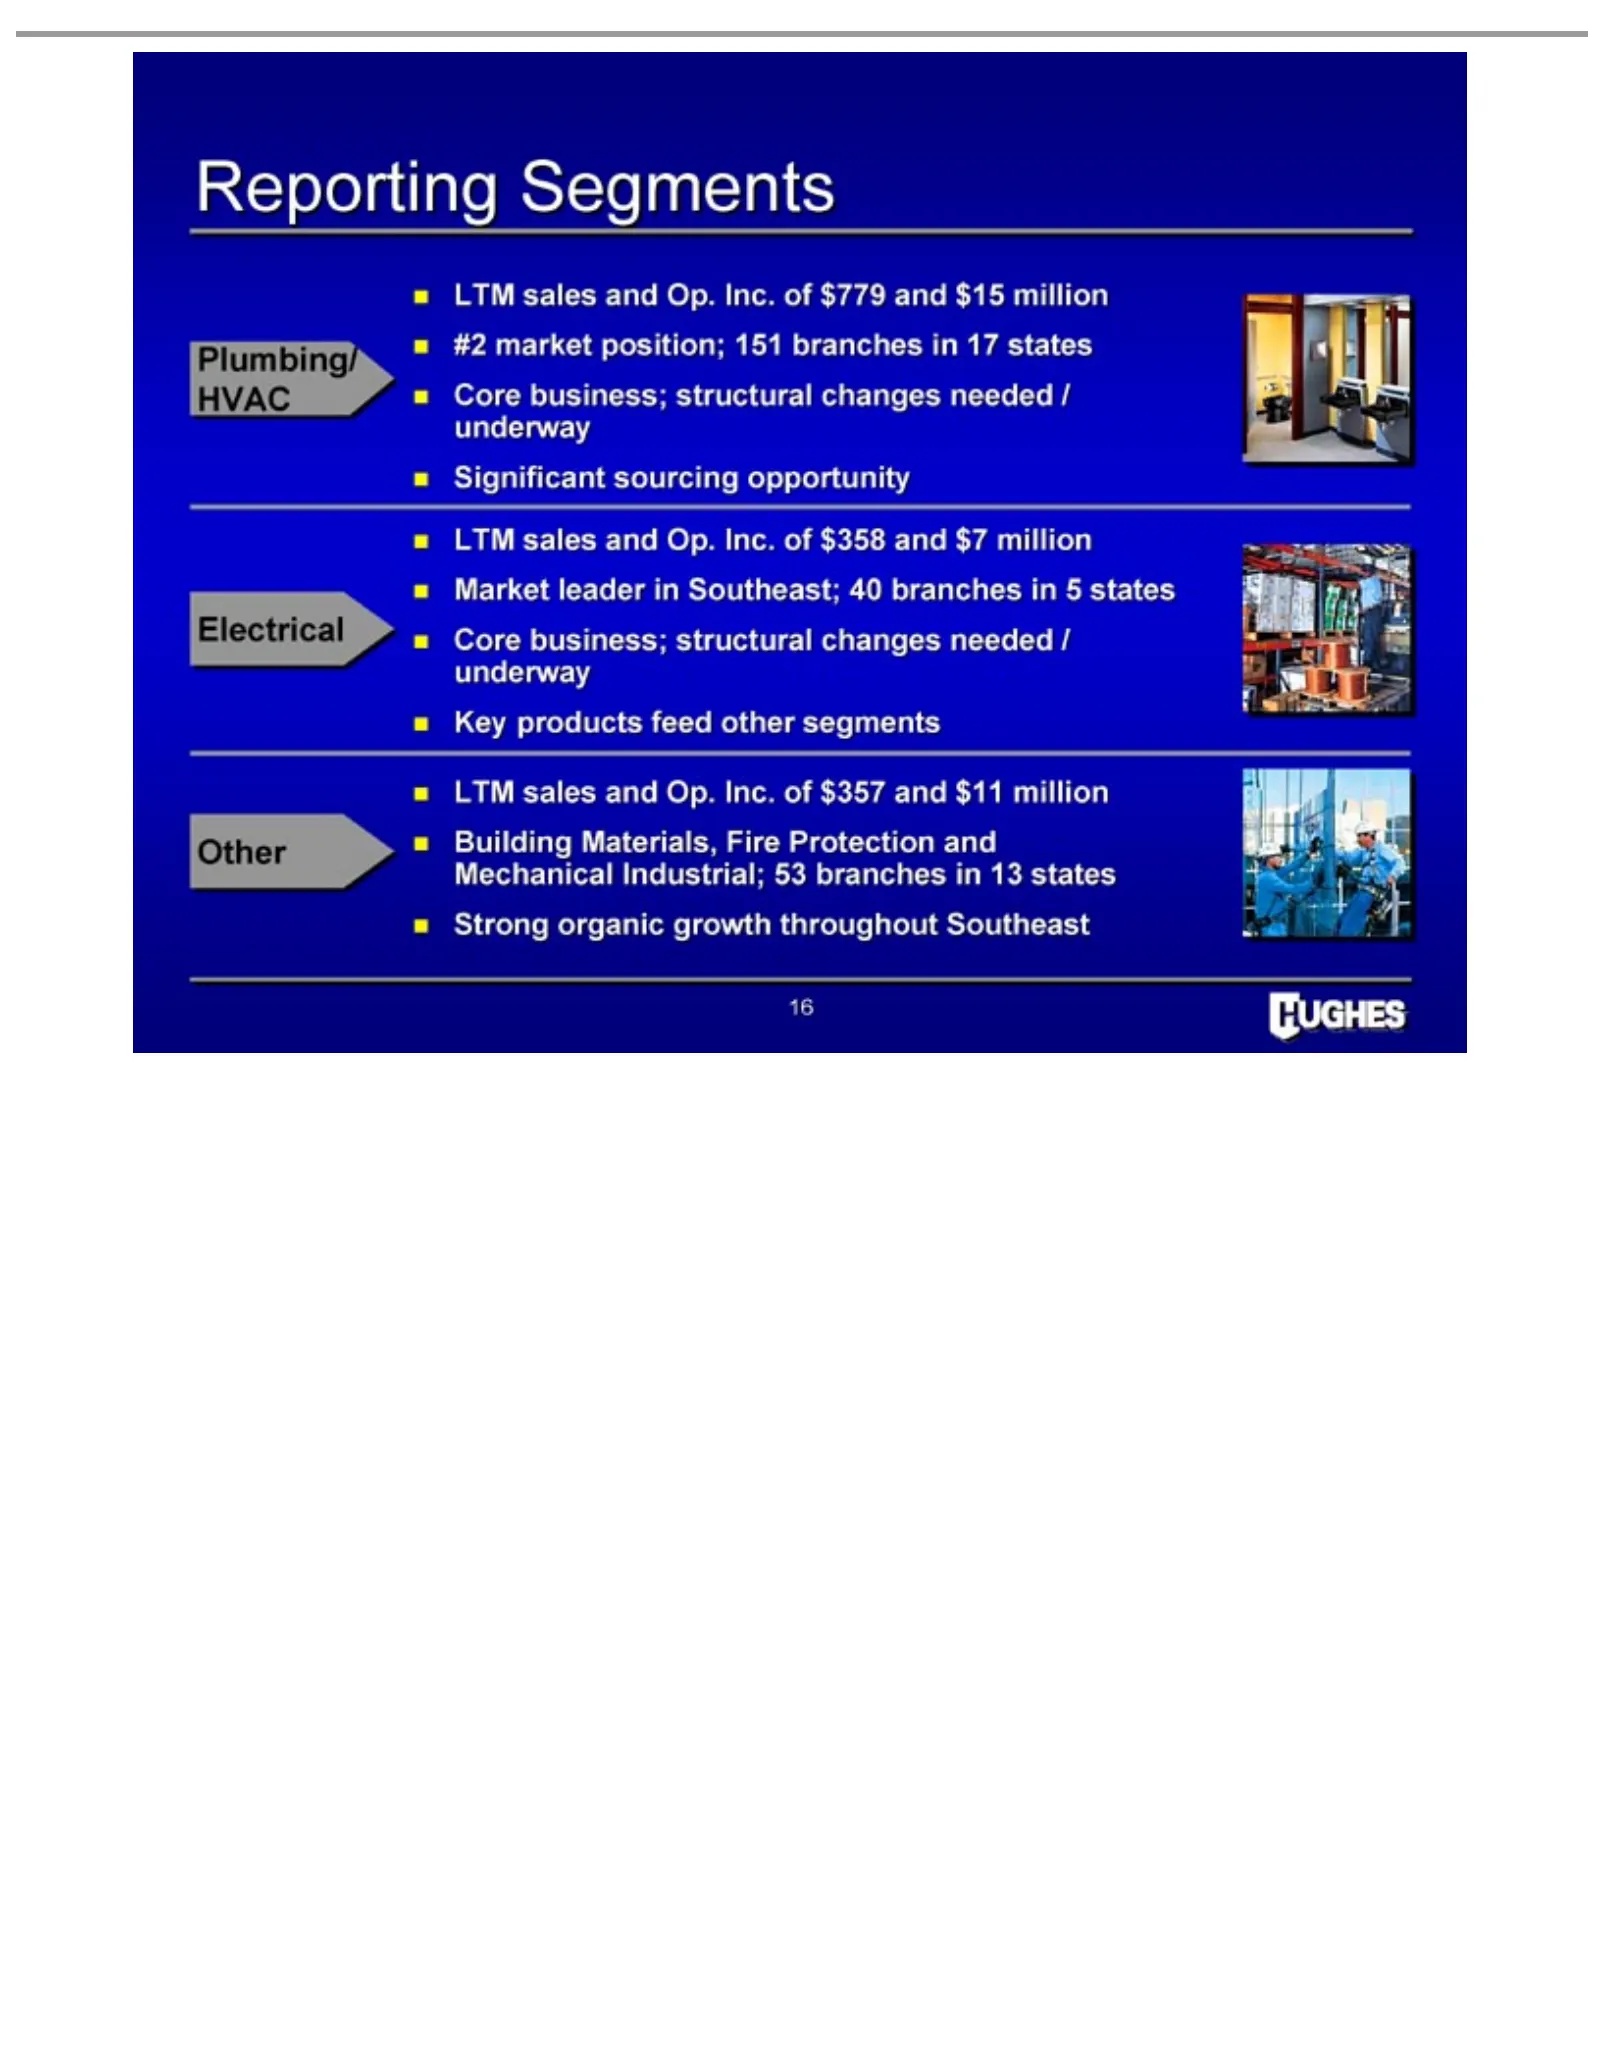
Reporting Plumbing/ HVAC Significant Market Electrical Key underway LTM Other Mechanical Strong 16 products sales Building organic Core leader Core Segments #2 and sourcing Industrial; business; feed market ingrowth EBIT business; Materials, Southeast; other opportunity of position; structural throu
Slide 18: Business Strategy
({UGHES Business Strategy
Slide 19: Significant Change Underway
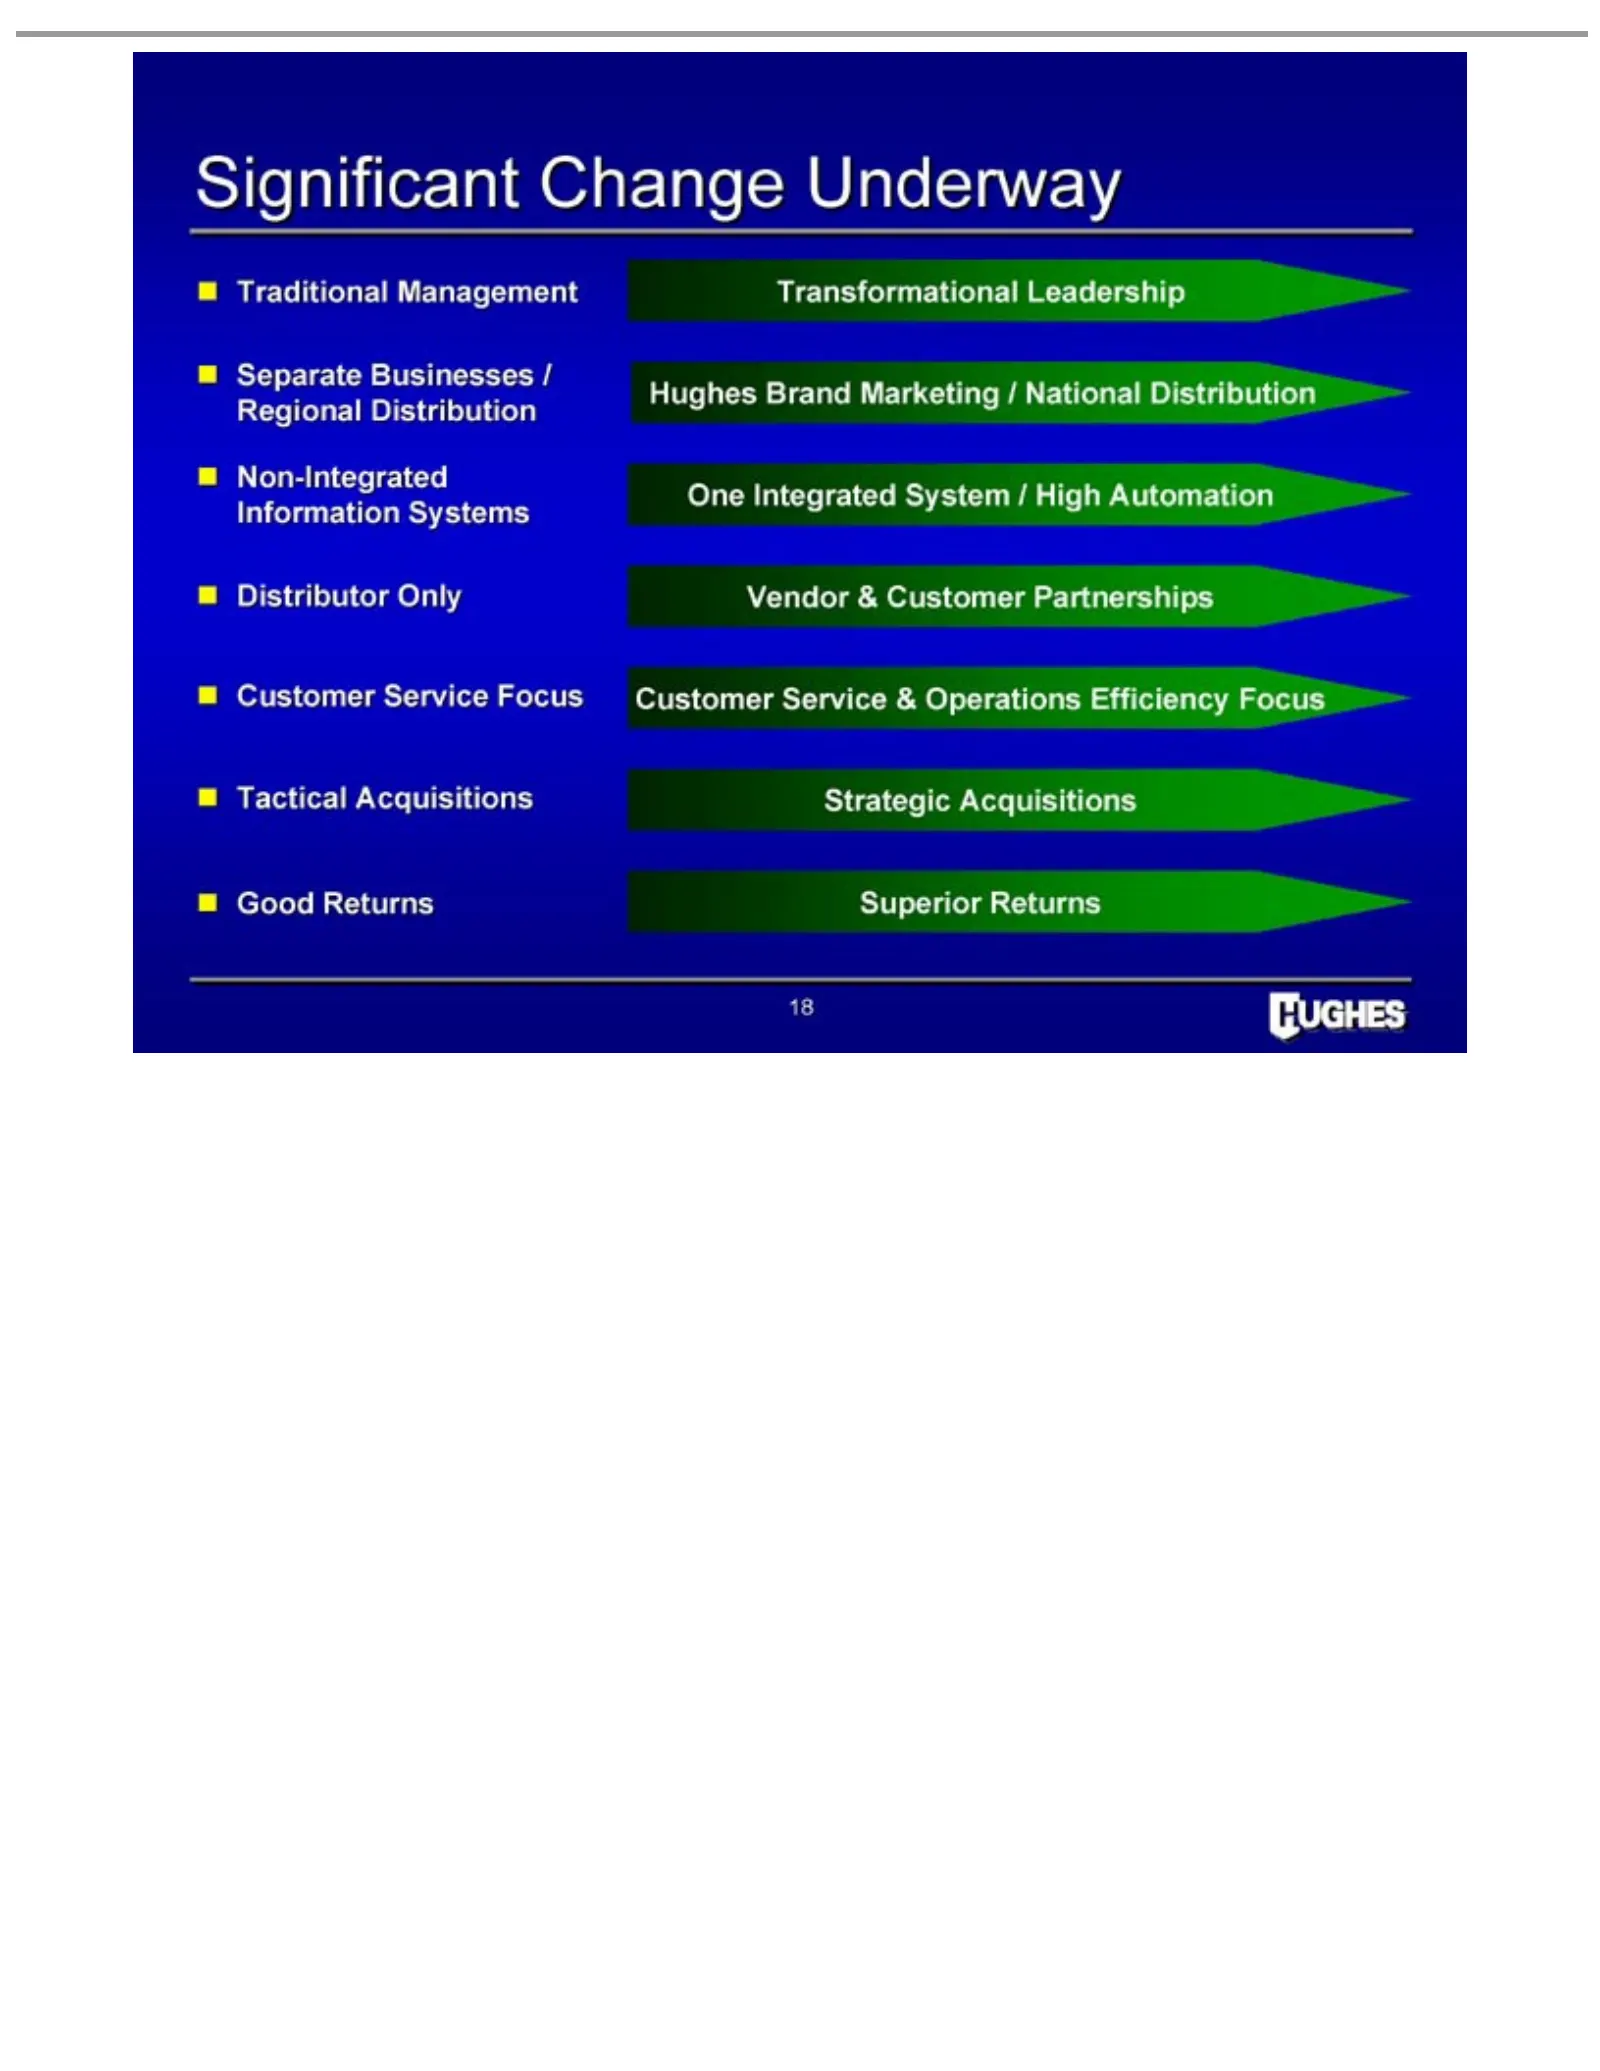
Significant Traditional Separate Hughes Regional One Non-Integrated Information Distributor Customer Tactical Good 18 Integrated Returns Brand Acquisitions Businesses Distribution Service Change Only Management Systems Superior Marketing System Vendor Focus Underway / Strategic /Returns High & Custo
Slide 20: Business Strategy
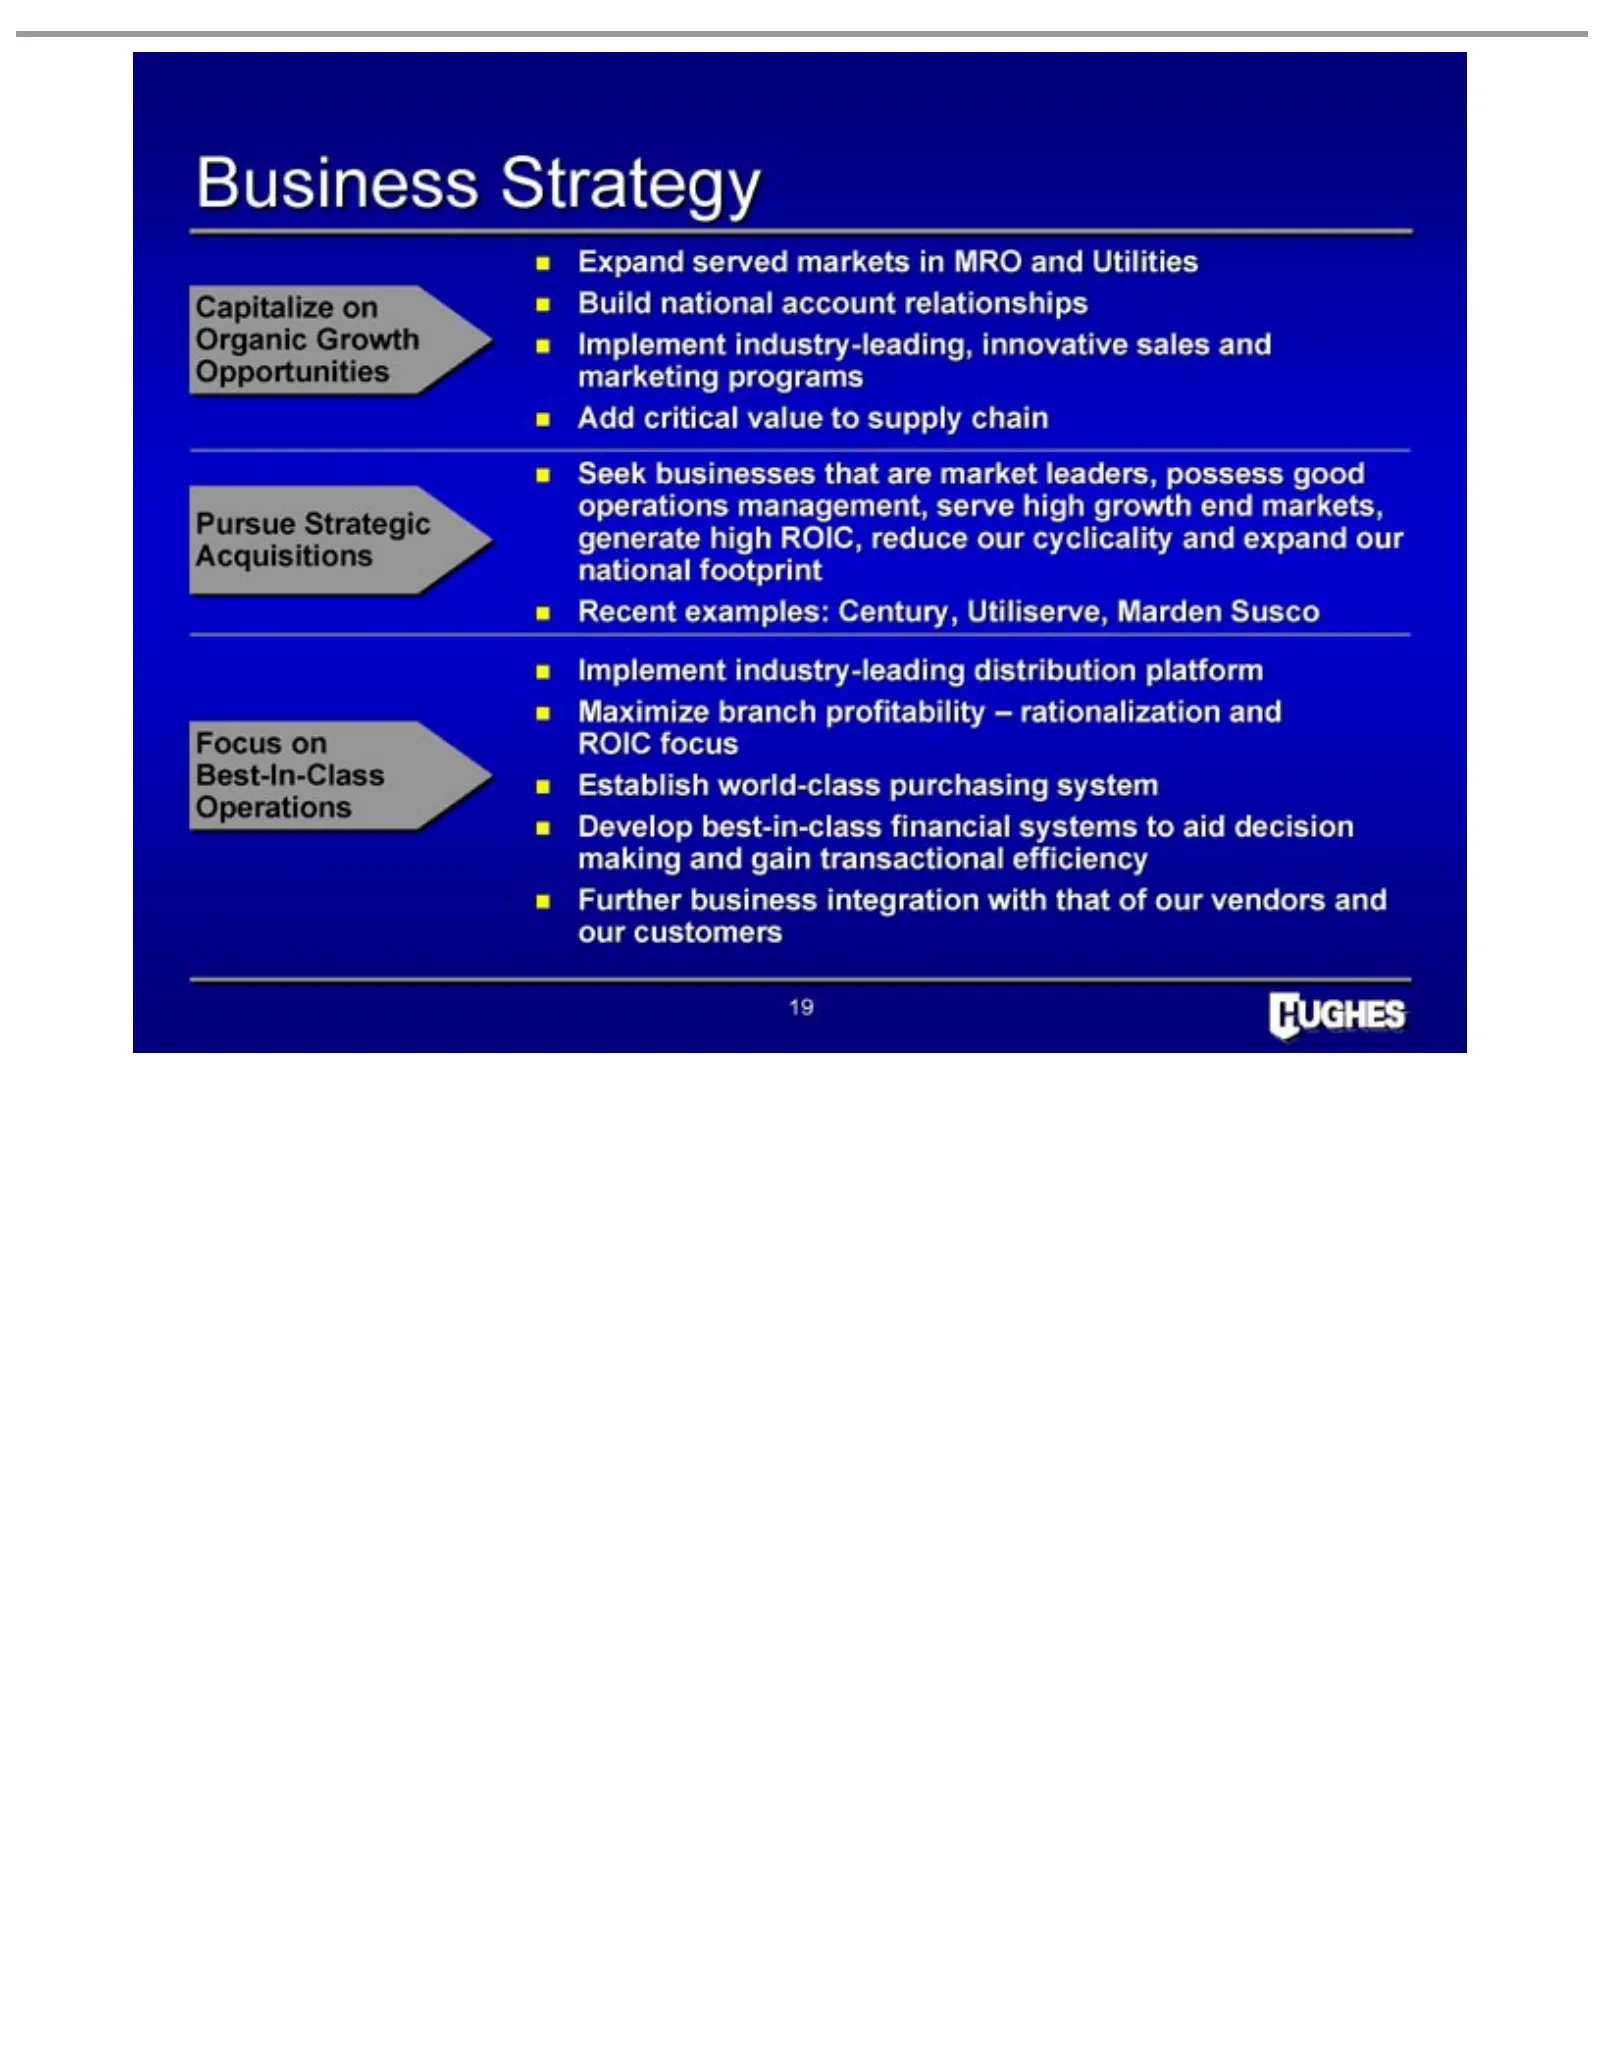
Business Expand Capitalize Organic Opportunities Add Seek operations Pursue generate national Acquisitions Recent Implement Maximize Focus Best-In-Class—- Develop Operations making Further our 19 customers critical businesses on Strategic examples: business and served Growth footprint high best-in-c
Slide 21: Organic Growth Opportunities
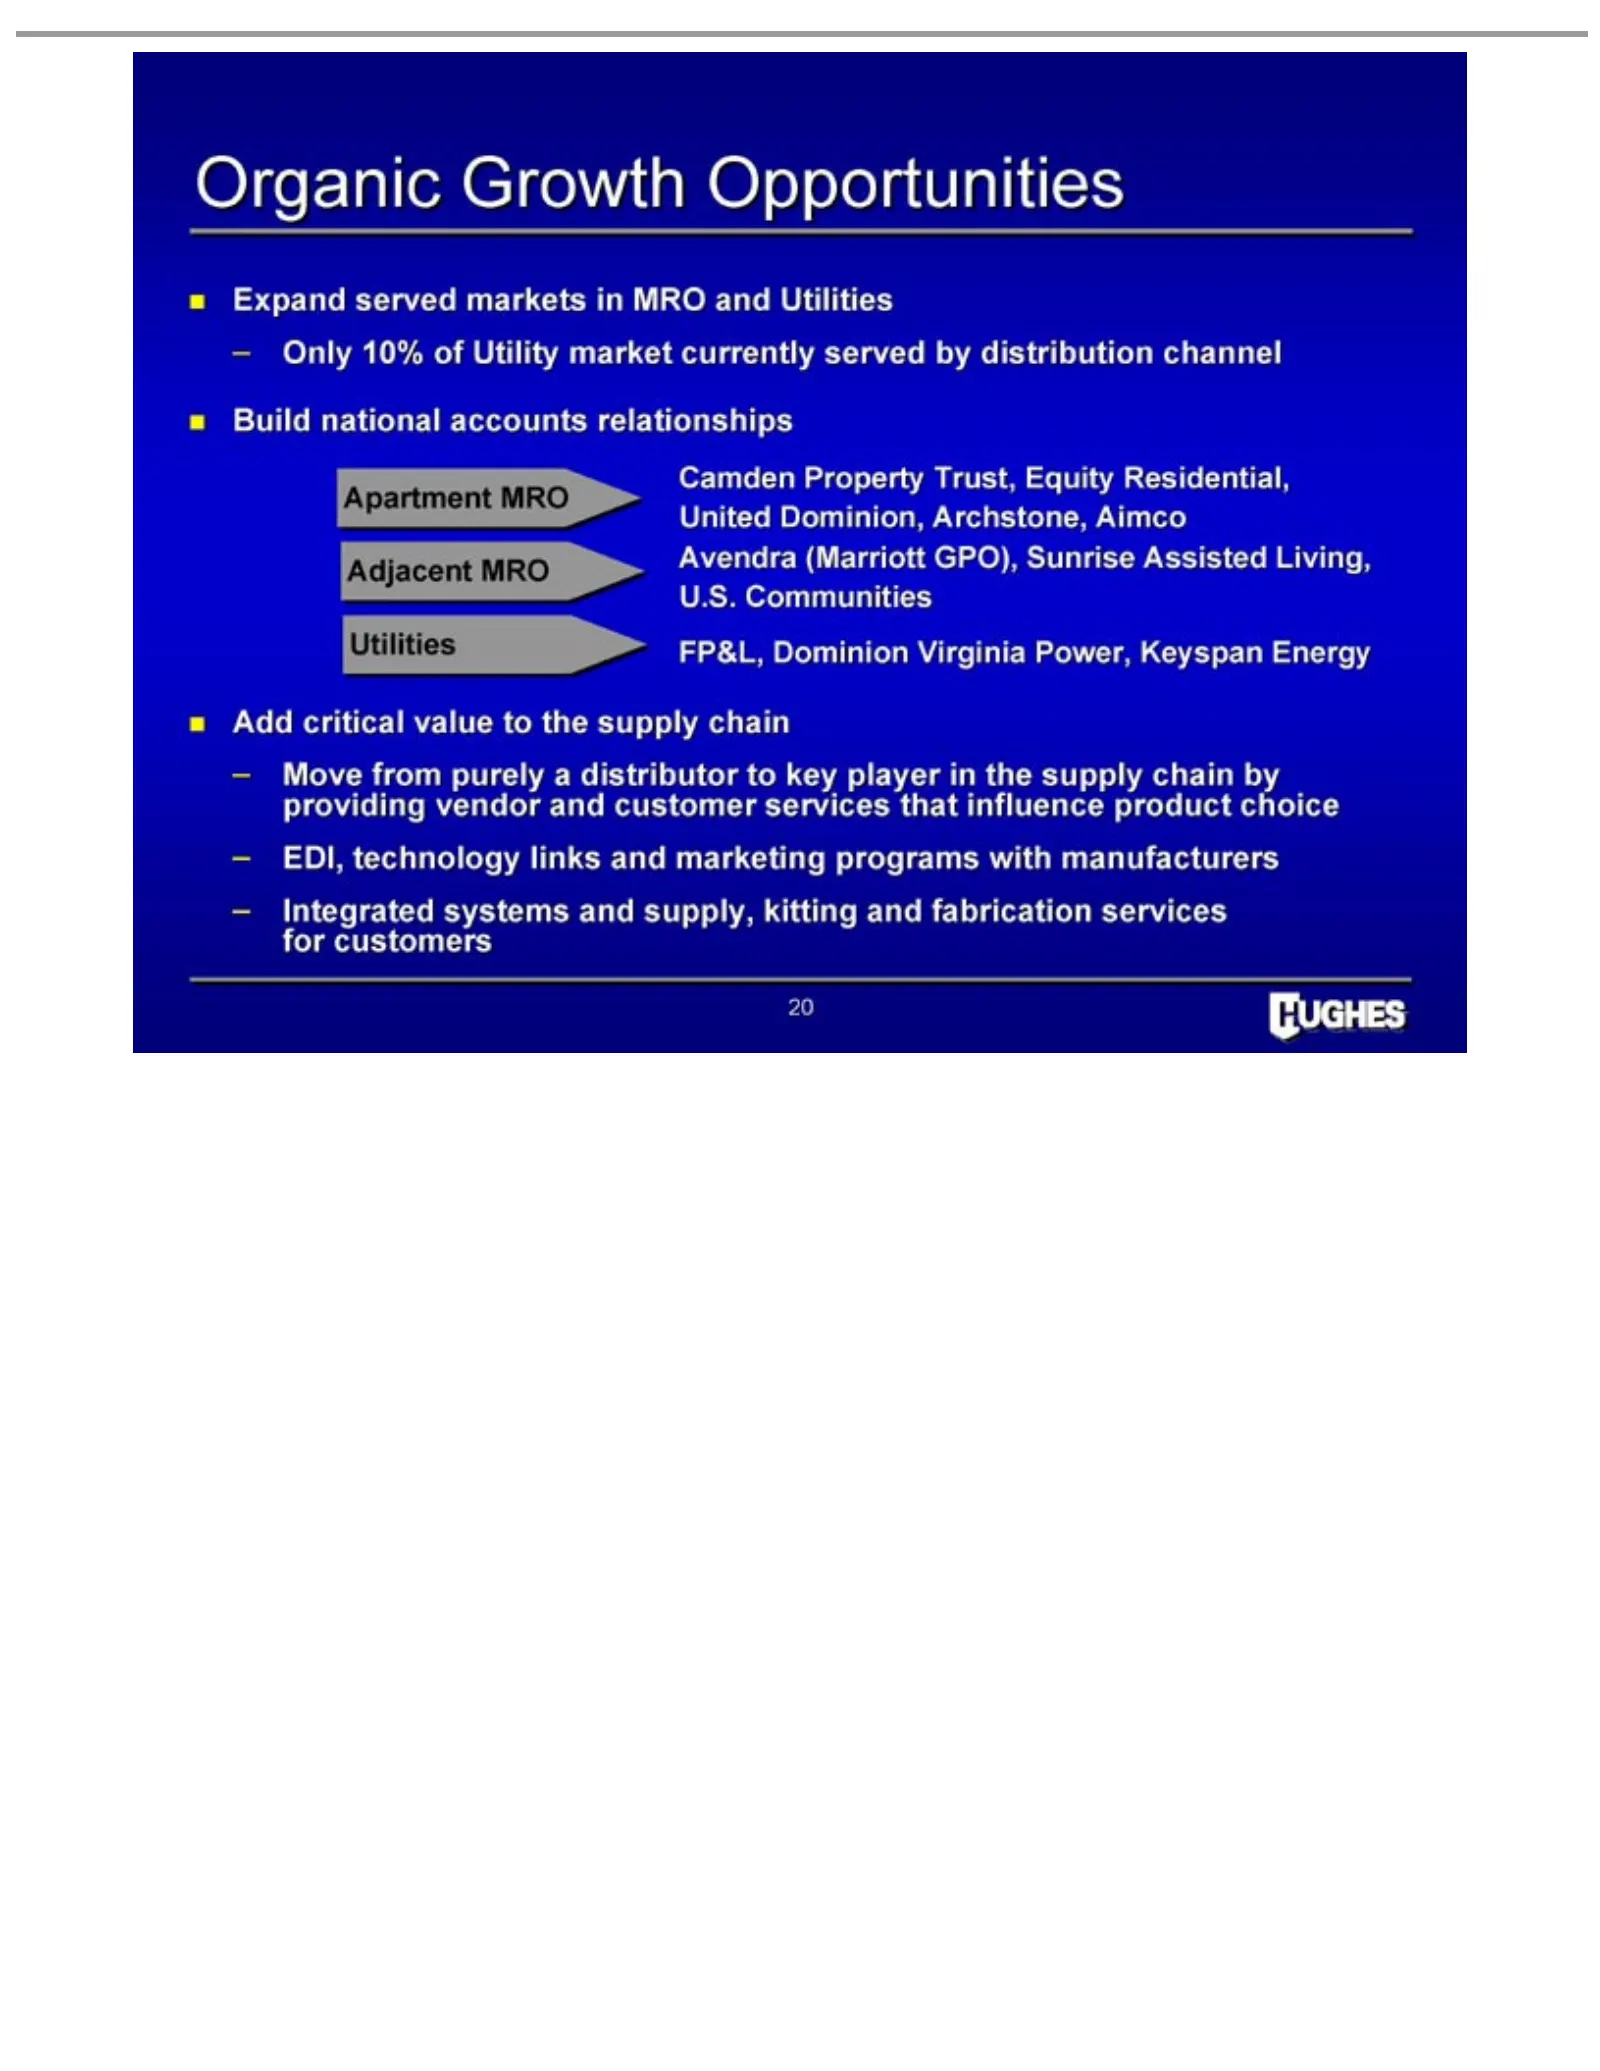
Organic Expand Build Camden Apartment United Adjacent U.S. Utilities Add – 20Only Move EDI, Integrated critical Communities national technology Dominion, 10% served from Growth FP&L, Property MRO MRO value systems ofpurely accounts markets Utility Avendra Dominion Opportunities Trust, to Archstone,
Slide 22: Innovative Marketing Programs
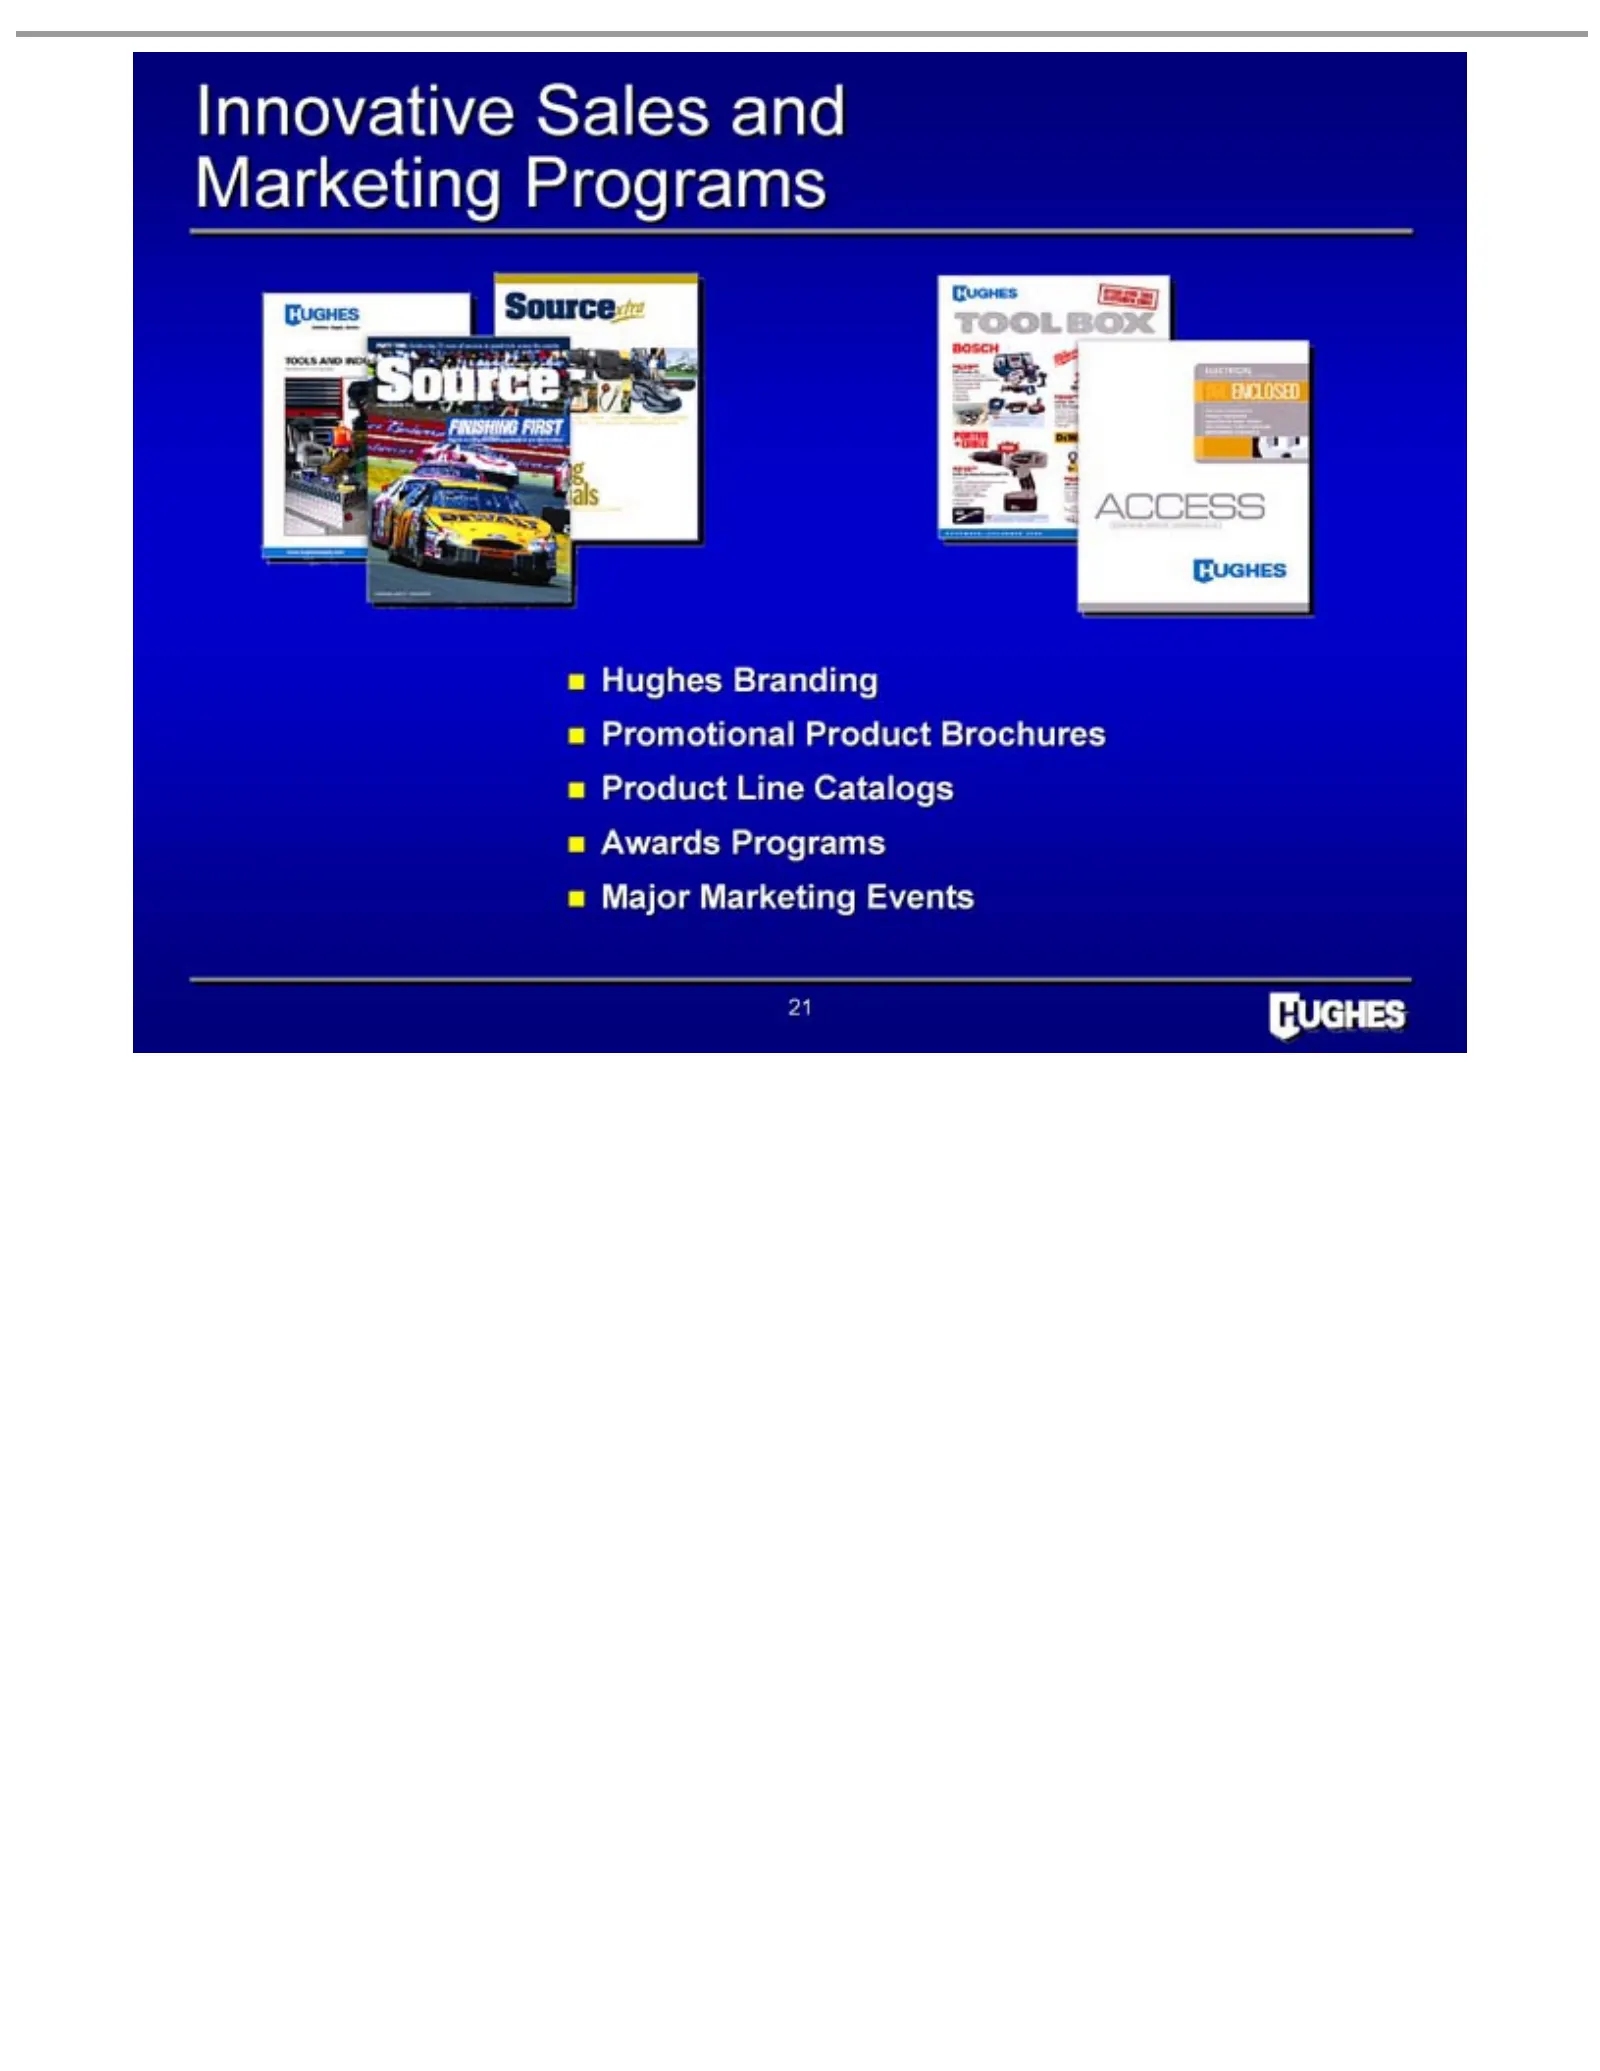
Innovative Hughes Promotional Product Awards Major 21 Marketing Programs Branding Line Sales Product Catalogs and Events Brochures Marketing Programs
Slide 23: Strategic Acquisitions
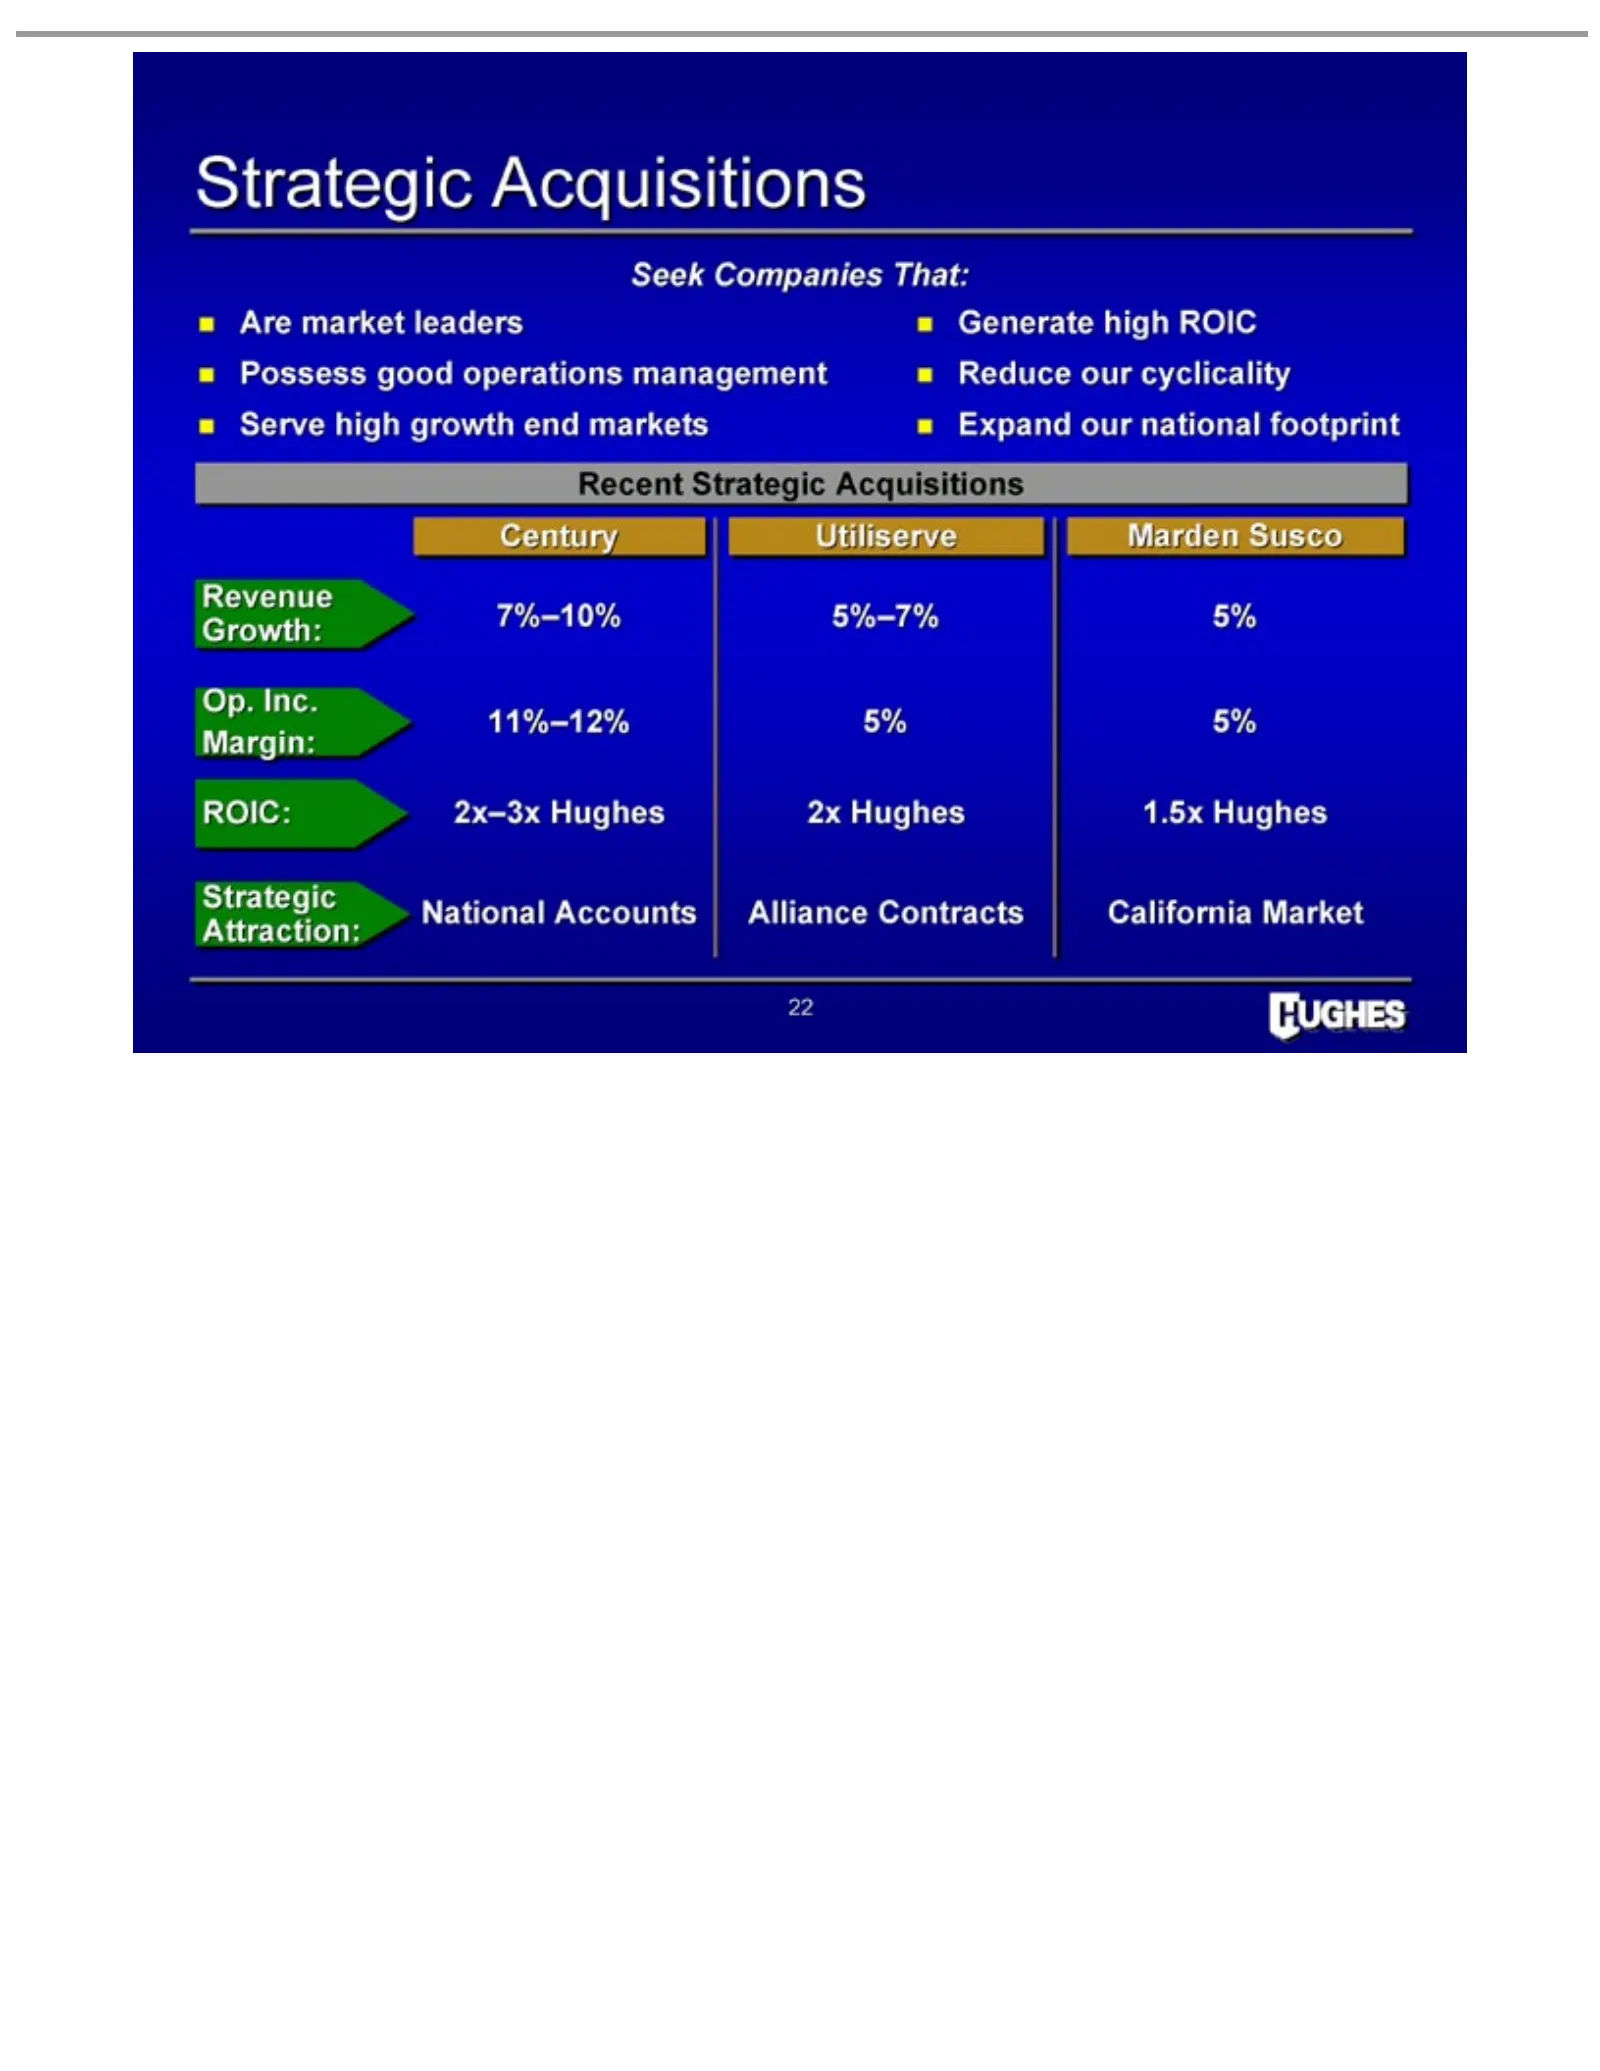
Seekmarket Are Possess Serve Recent Century 7%–10% Revenue 11%–12% EBIT Growth: ROIC: Margin: National Strategic 22 Attraction: Companies high 2x–3x Strategic good Utiliserve Accounts Acquisitions 5%–7% 5% growth leaders operations Hughes 5%Acquisitions That: 5%Alliance end Marden Generate 2x market
Slide 24: Operations Strategy
({UGHES Operations Strategy
Slide 25: Operations Strategy
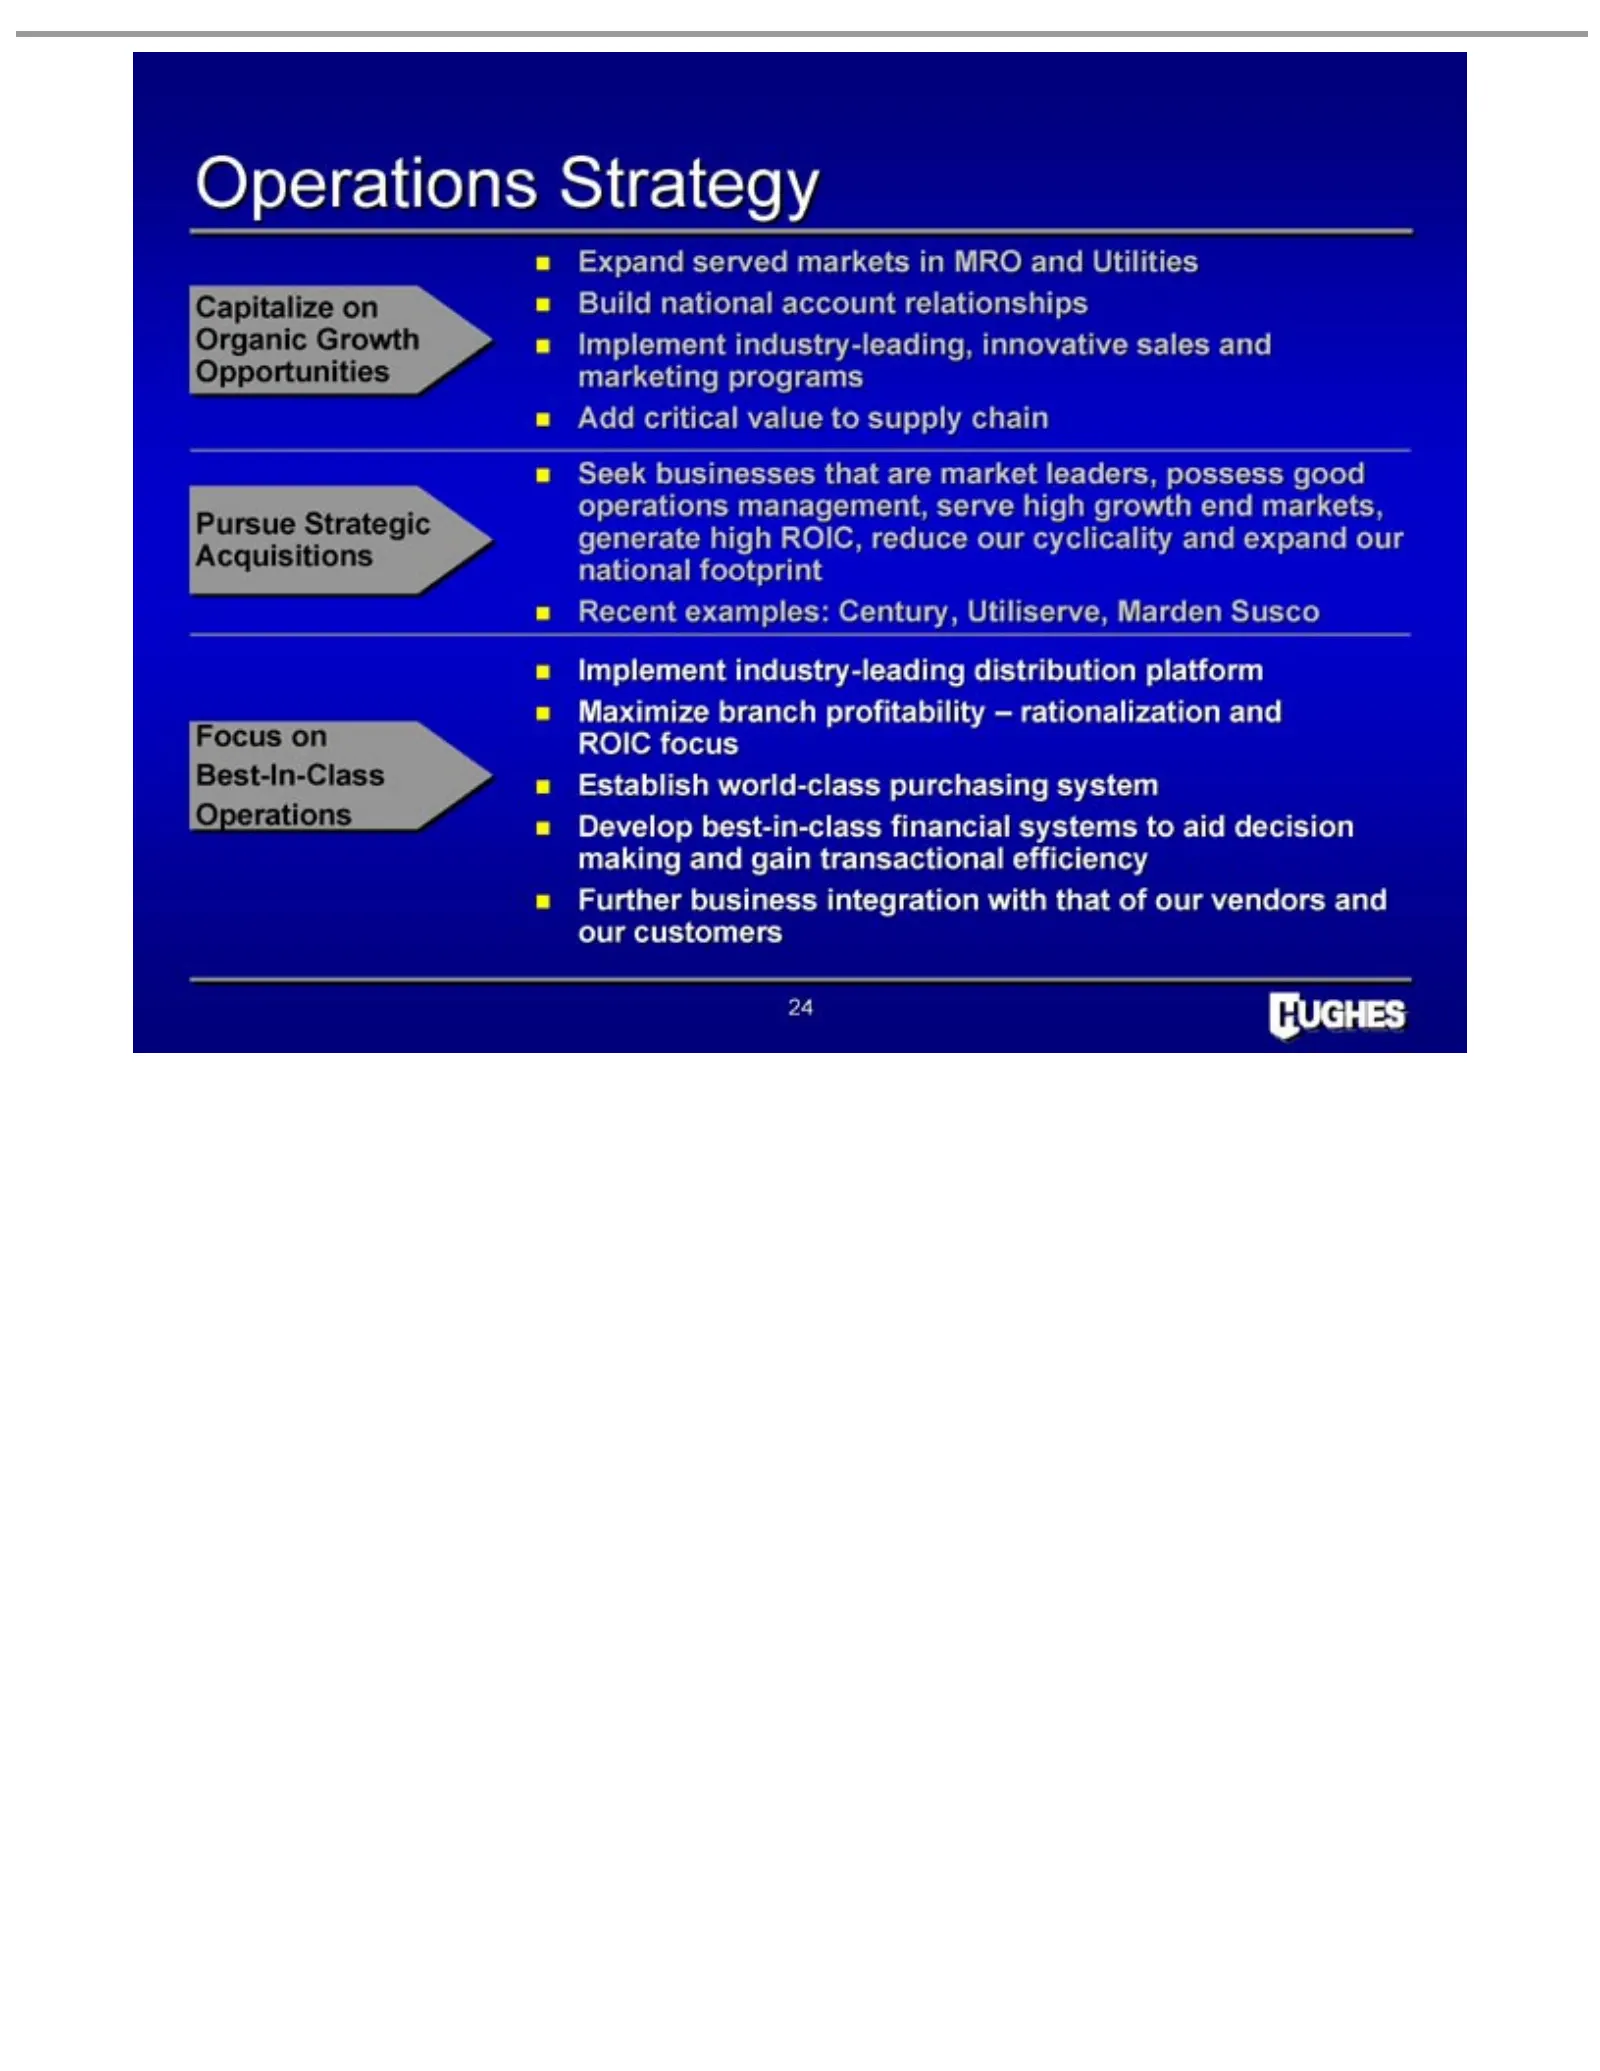
Expand Capitalize Organic Opportunities Add Seek operations Pursue generate national Acquisitions Recent Implement Maximize Focus Best-In-Class—- Operations making Further our 24 customers critical businesses on Strategic examples: business and served Growth footprint high ROIC on branch management,
Slide 26: Best-In-Class Implementation Timeline
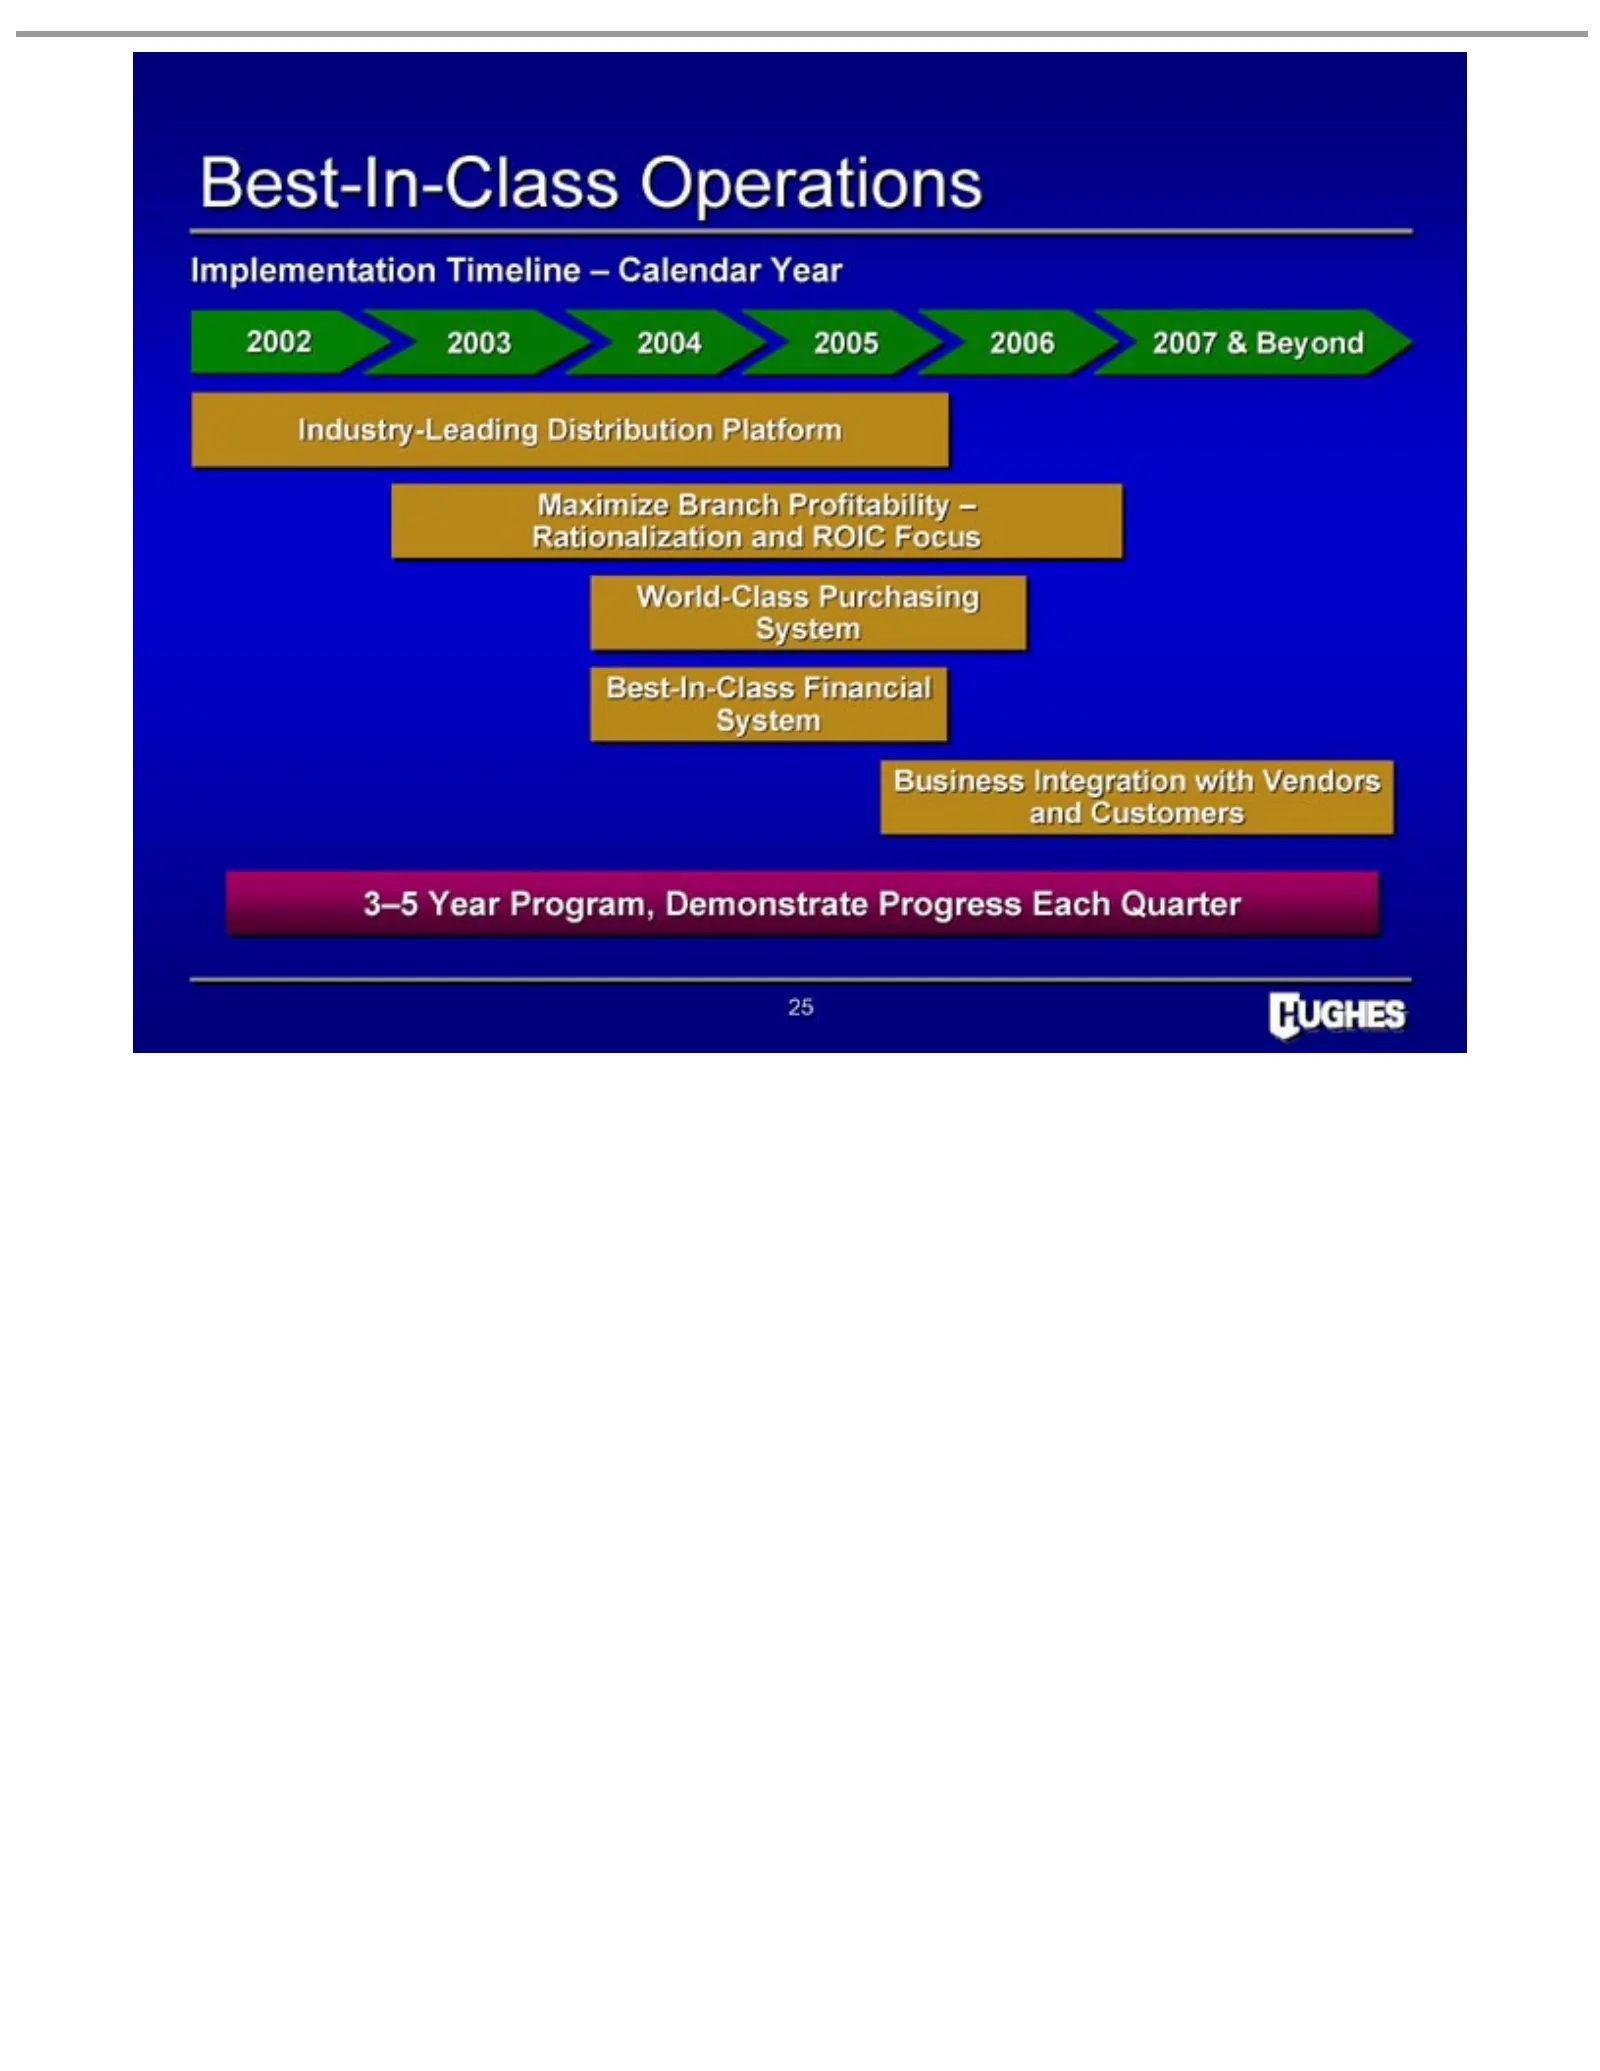
Best-In-Class Implementation 2002 Industry-Leading Maximize Business 3–5 25 Year 2003Program, Integration Branch 2004 Operations Timeline 2005 Distribution Profitability Demonstrate with 2006–Vendors Calendar 2007Platform –Rationalization Progress &and Beyond Year Customers Each Quarter and ROIC Foc
Slide 27: Integrated Business Systems
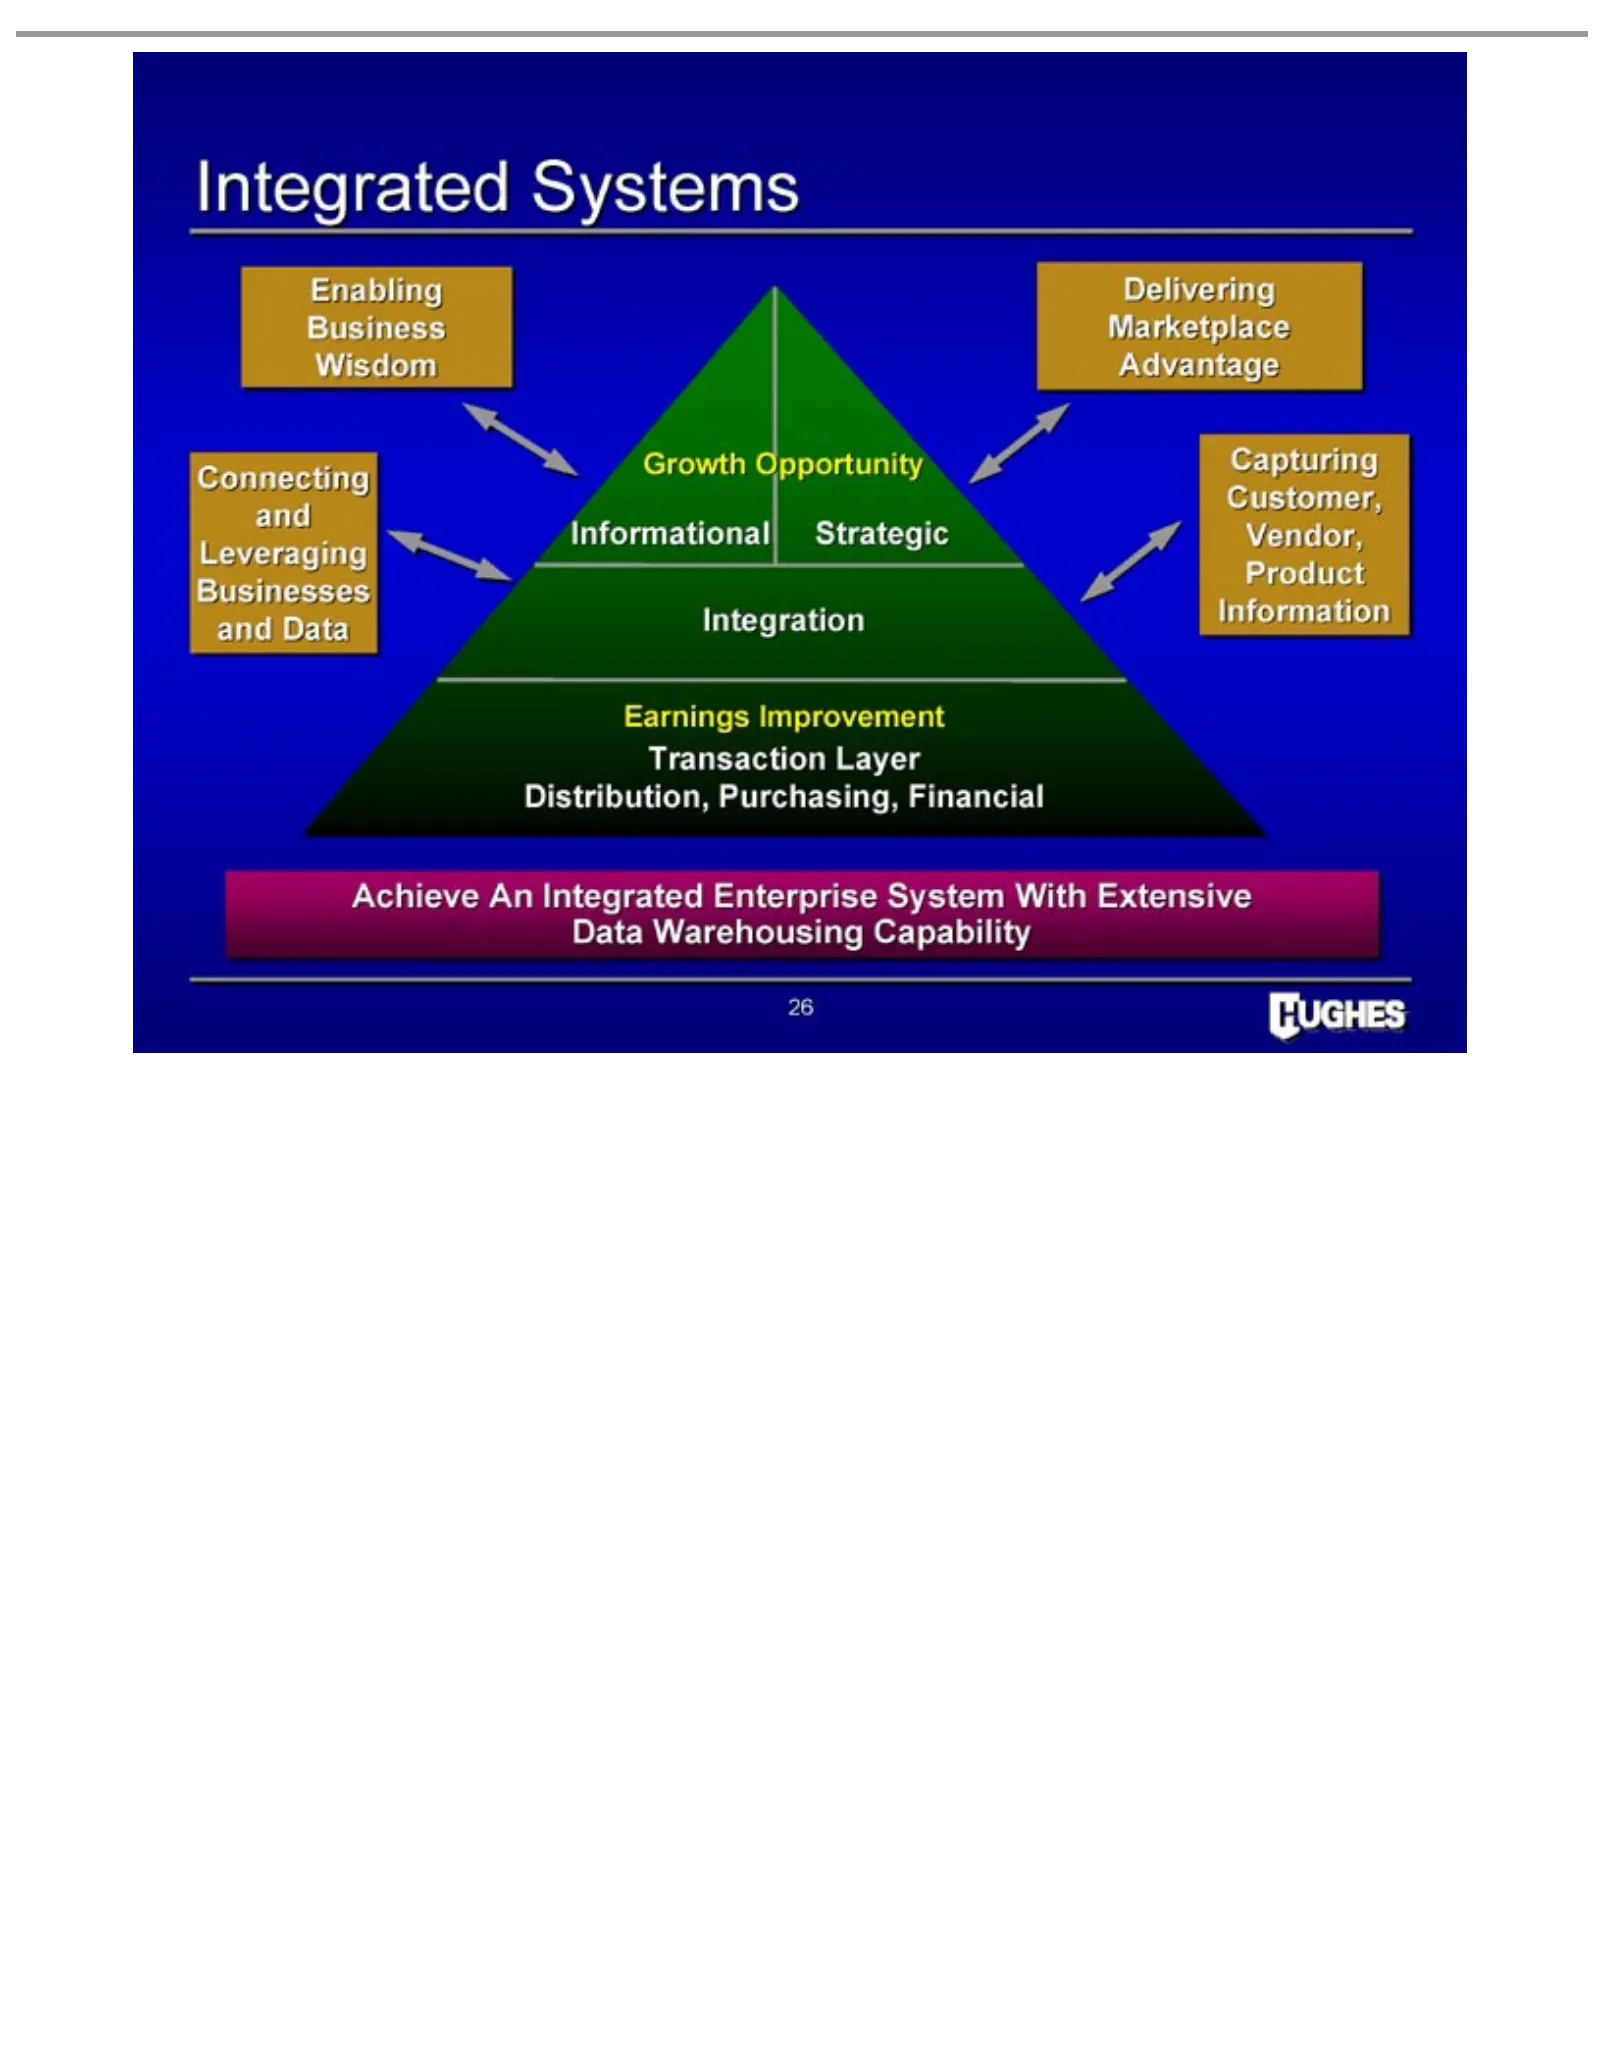
Integrated Enabling Business Wisdom Growth Informational Customer, Connecting Integration Businesses Product Leveraging and Earnings Transaction Distribution, Achieve 26 DataOpportunity An Advantage Improvement Marketplace Delivering Systems Information Layer Integrated Purchasing, Strategic Capturi
Slide 28: Maximize Branch Profitability
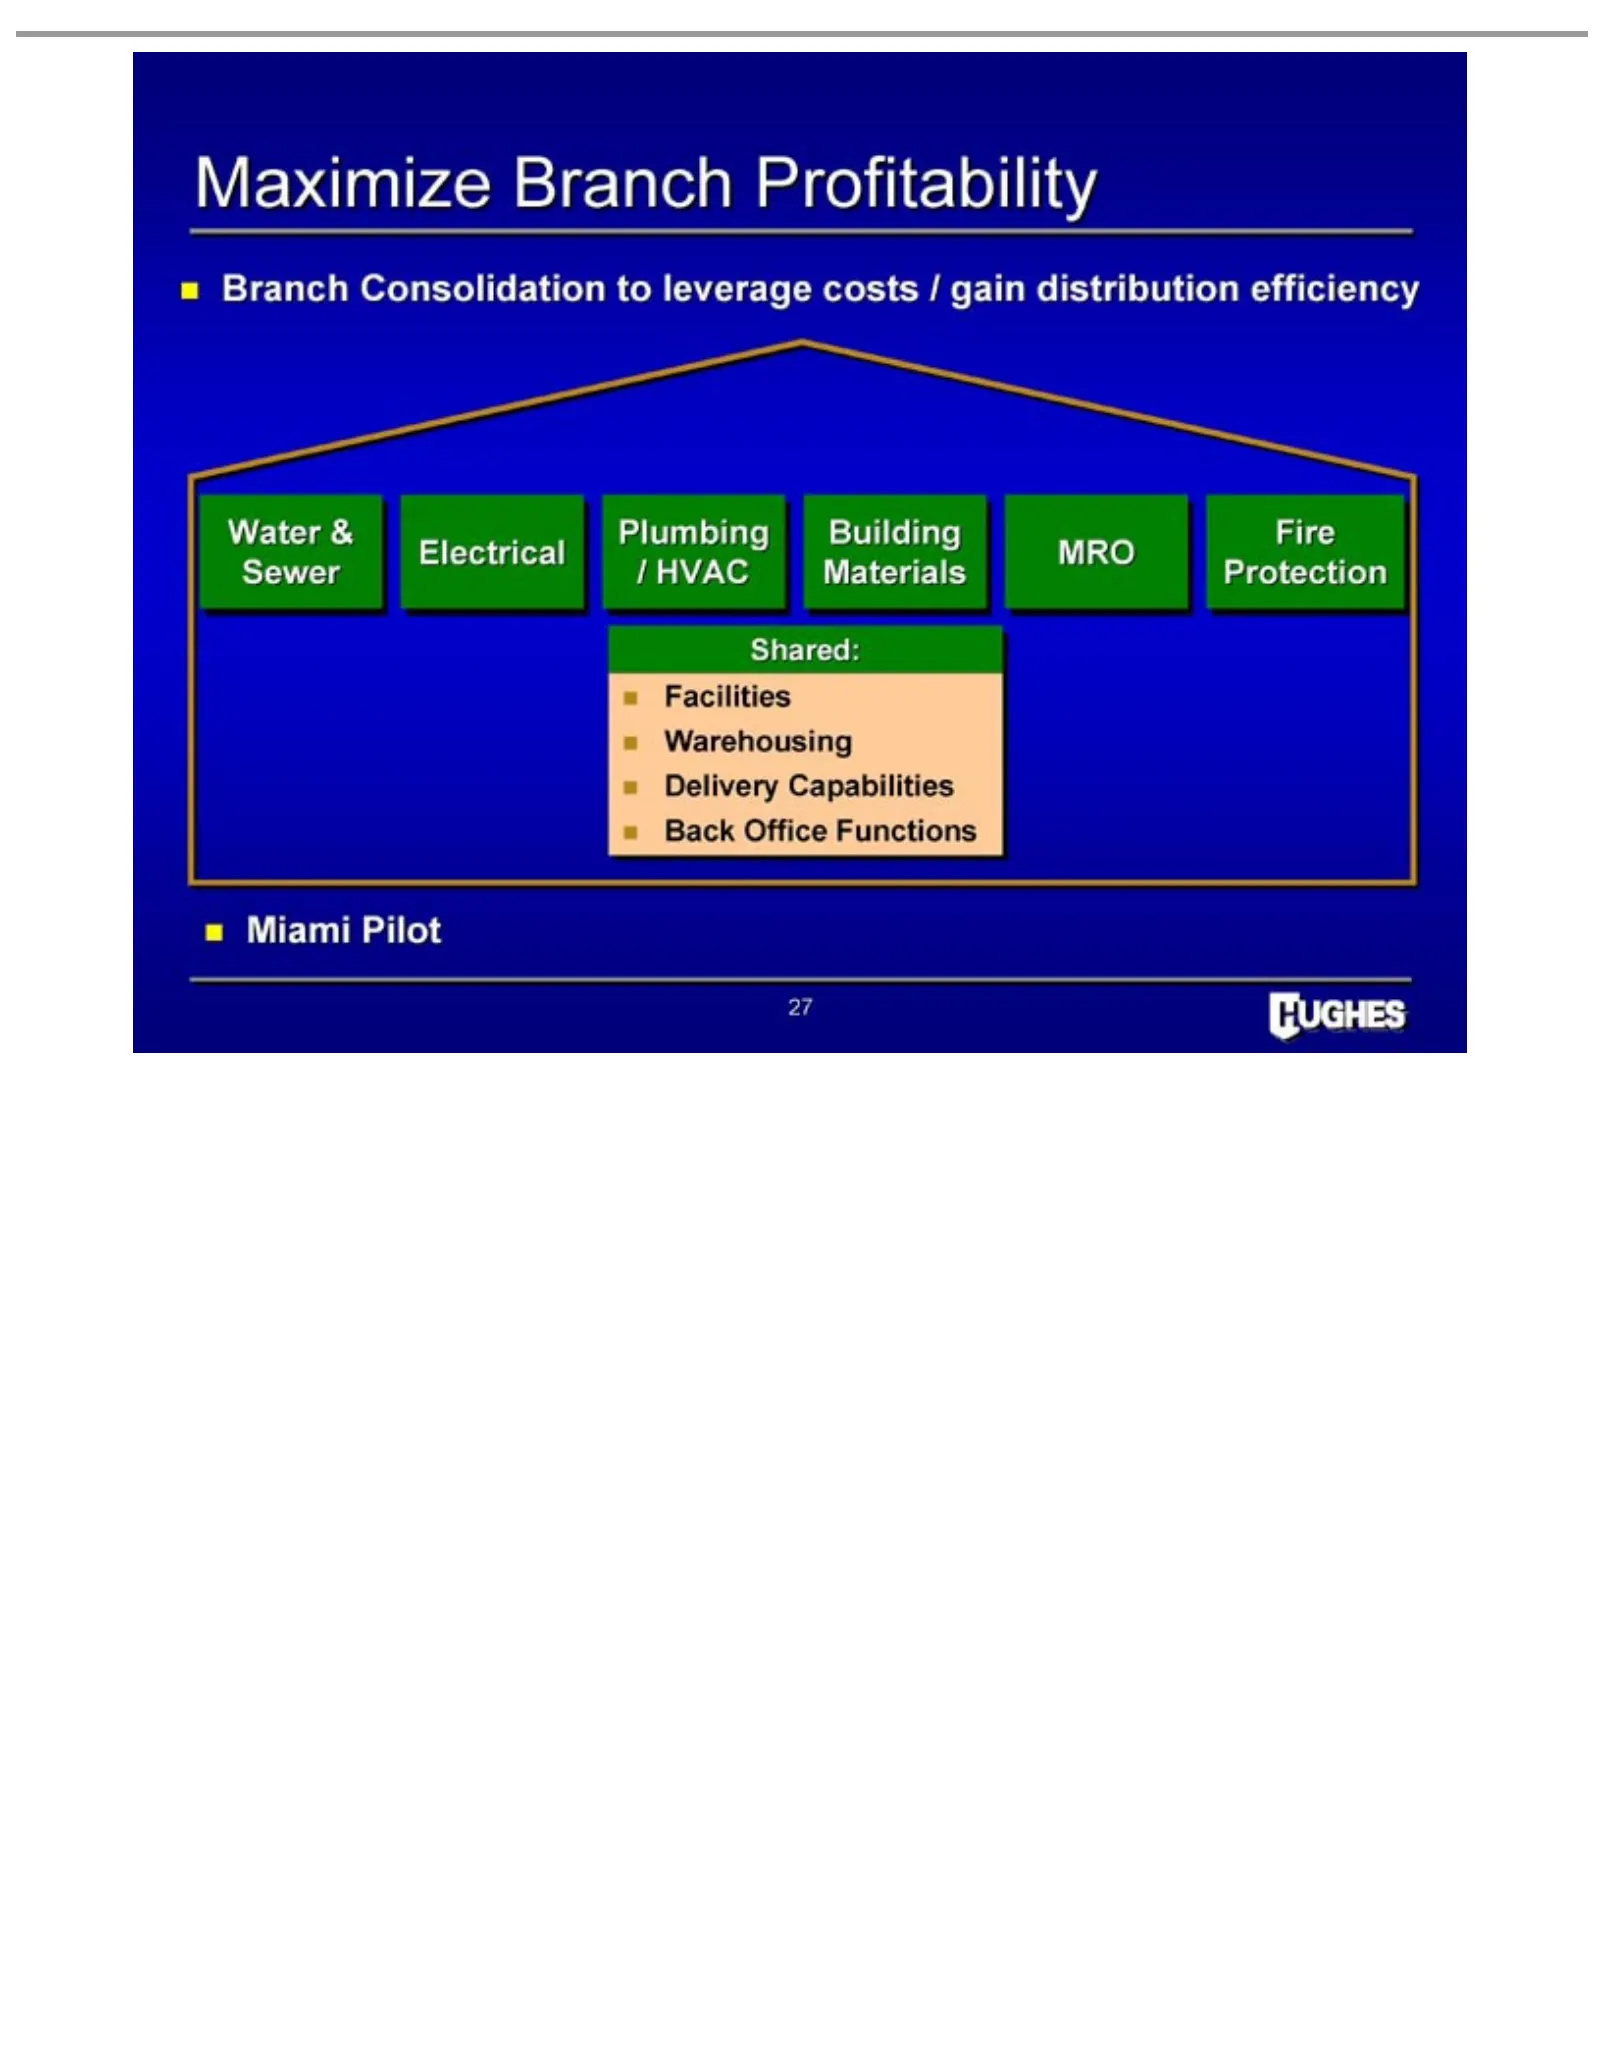
Maximize Branch Water Electrical Sewer Delivery Warehousing Facilities Shared: Back Miami 27 Office &/Pilot Consolidation HVAC Plumbing Capabilities MRO Branch Functions Materials Profitability Building to leverage Protection Fire costs / gain distribution efficiency
Slide 29: Financial Review
({UGHES Financial Review
Slide 30: Historical Sales and Performance
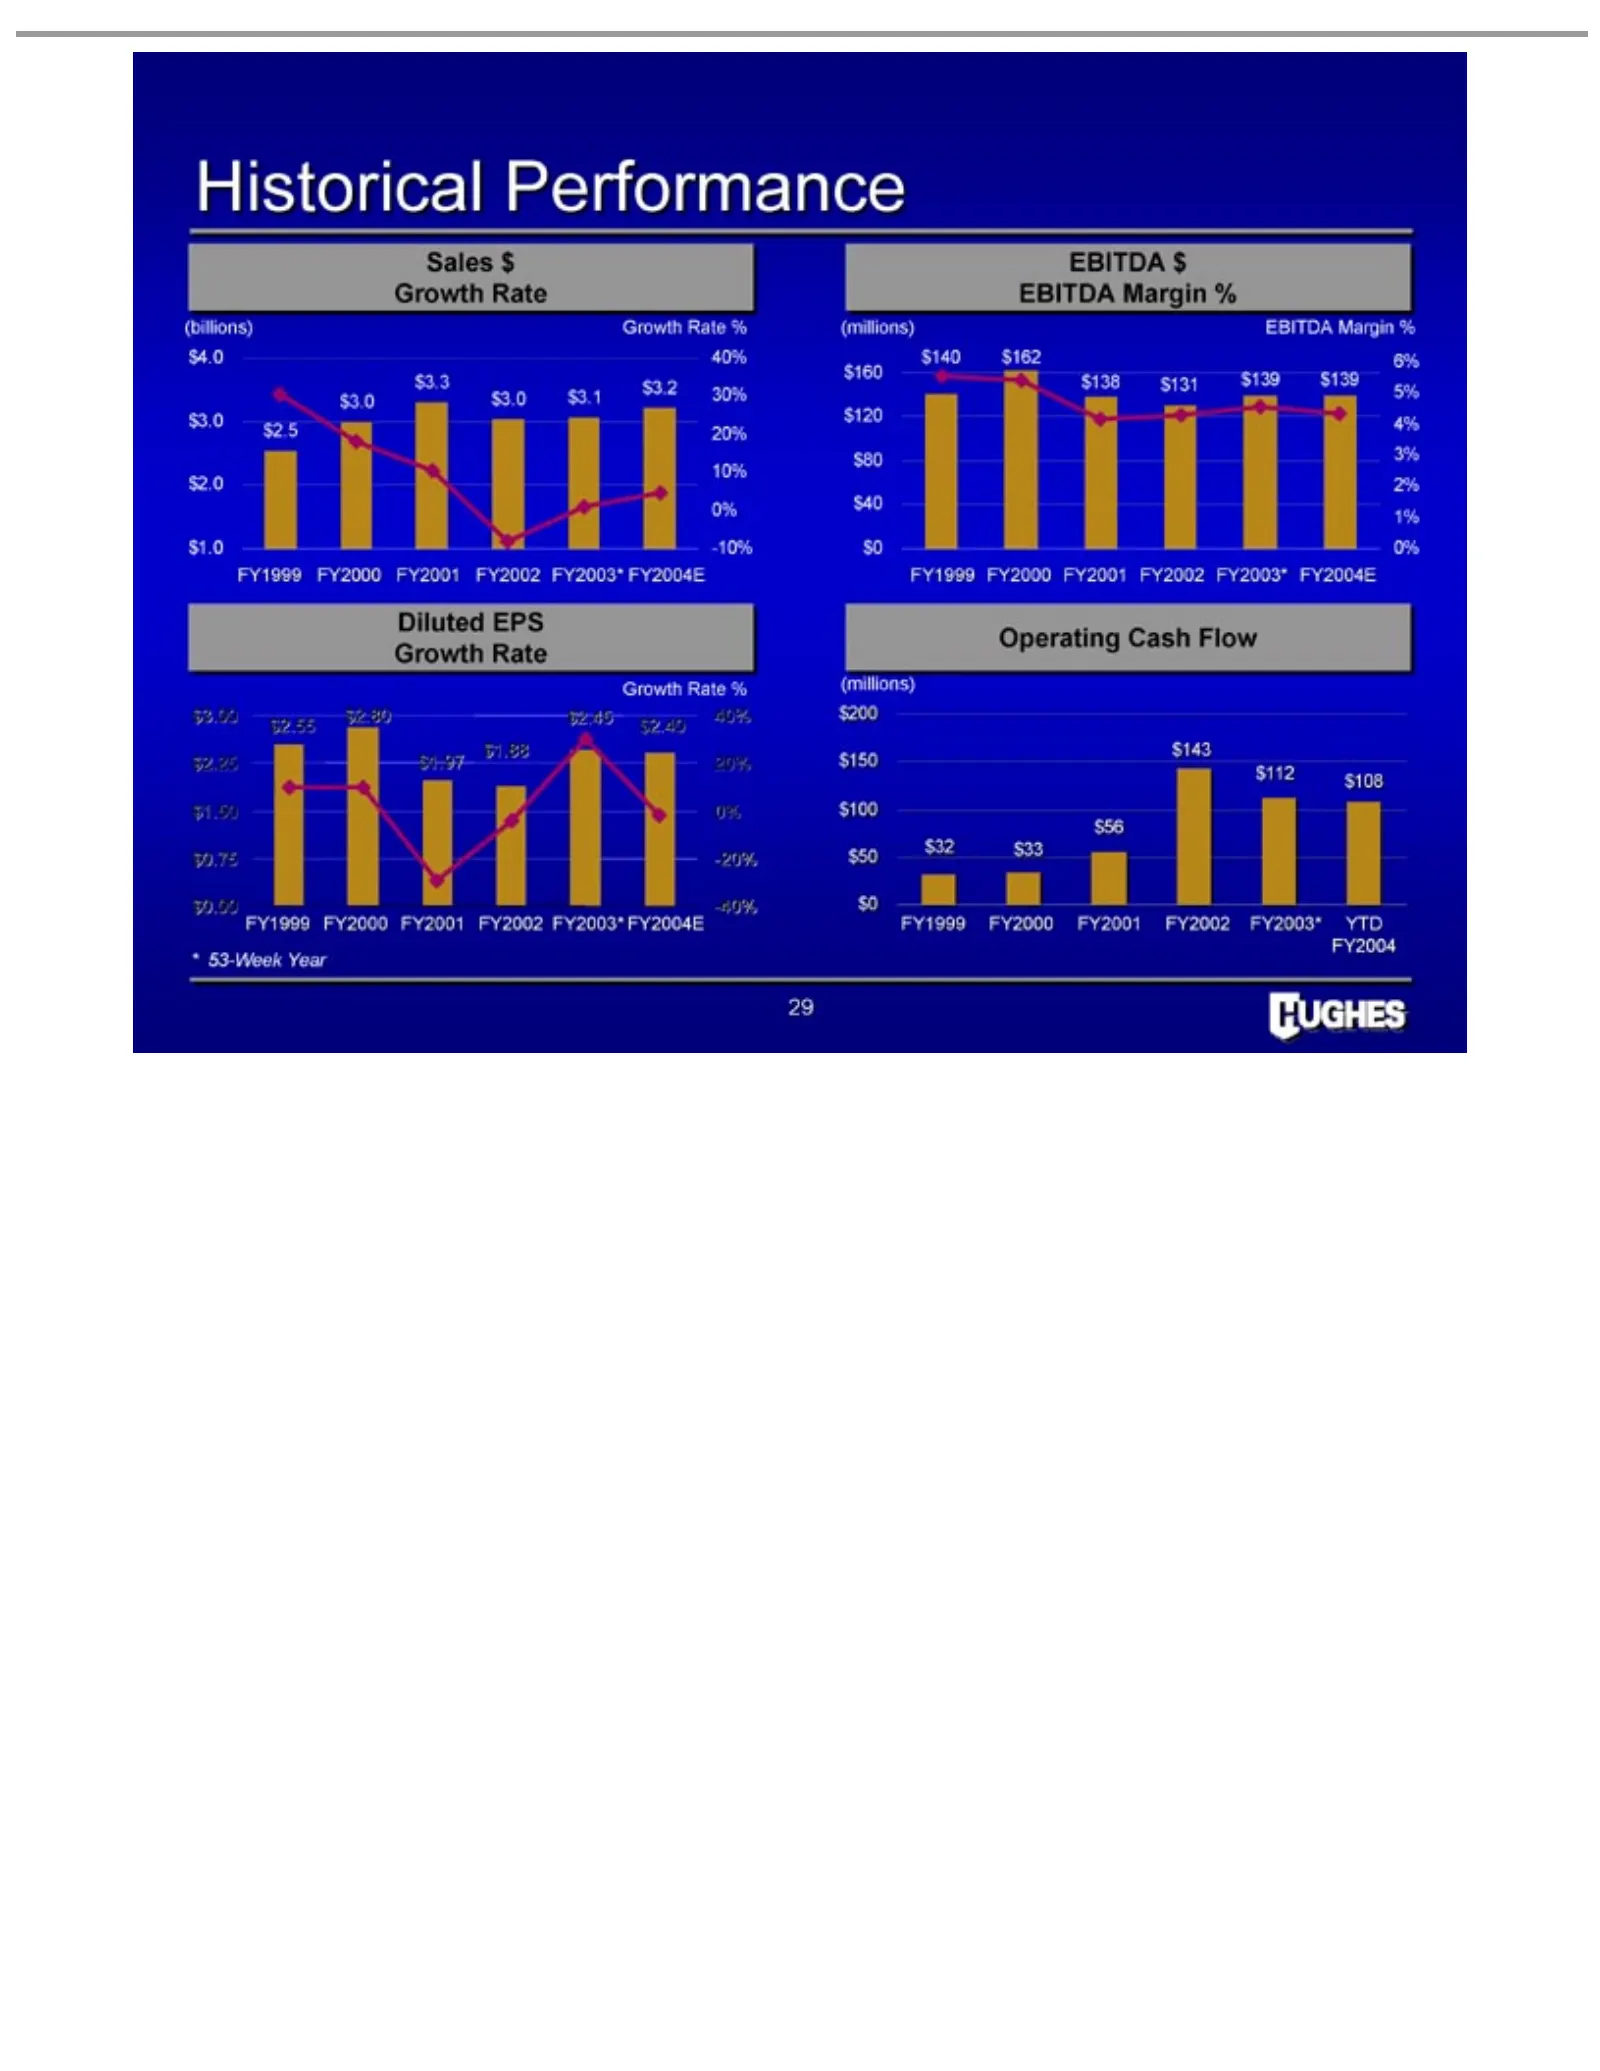
Historical Sales (billions) Diluted Operating Growth * 2953-Week $ EPS Rate Growth Performance Cash Year EBITDA EBITDA Flow %Rate (millions) Margin $ % (millions) % EBITDA Margin %
Slide 31: Same Store Sales Growth
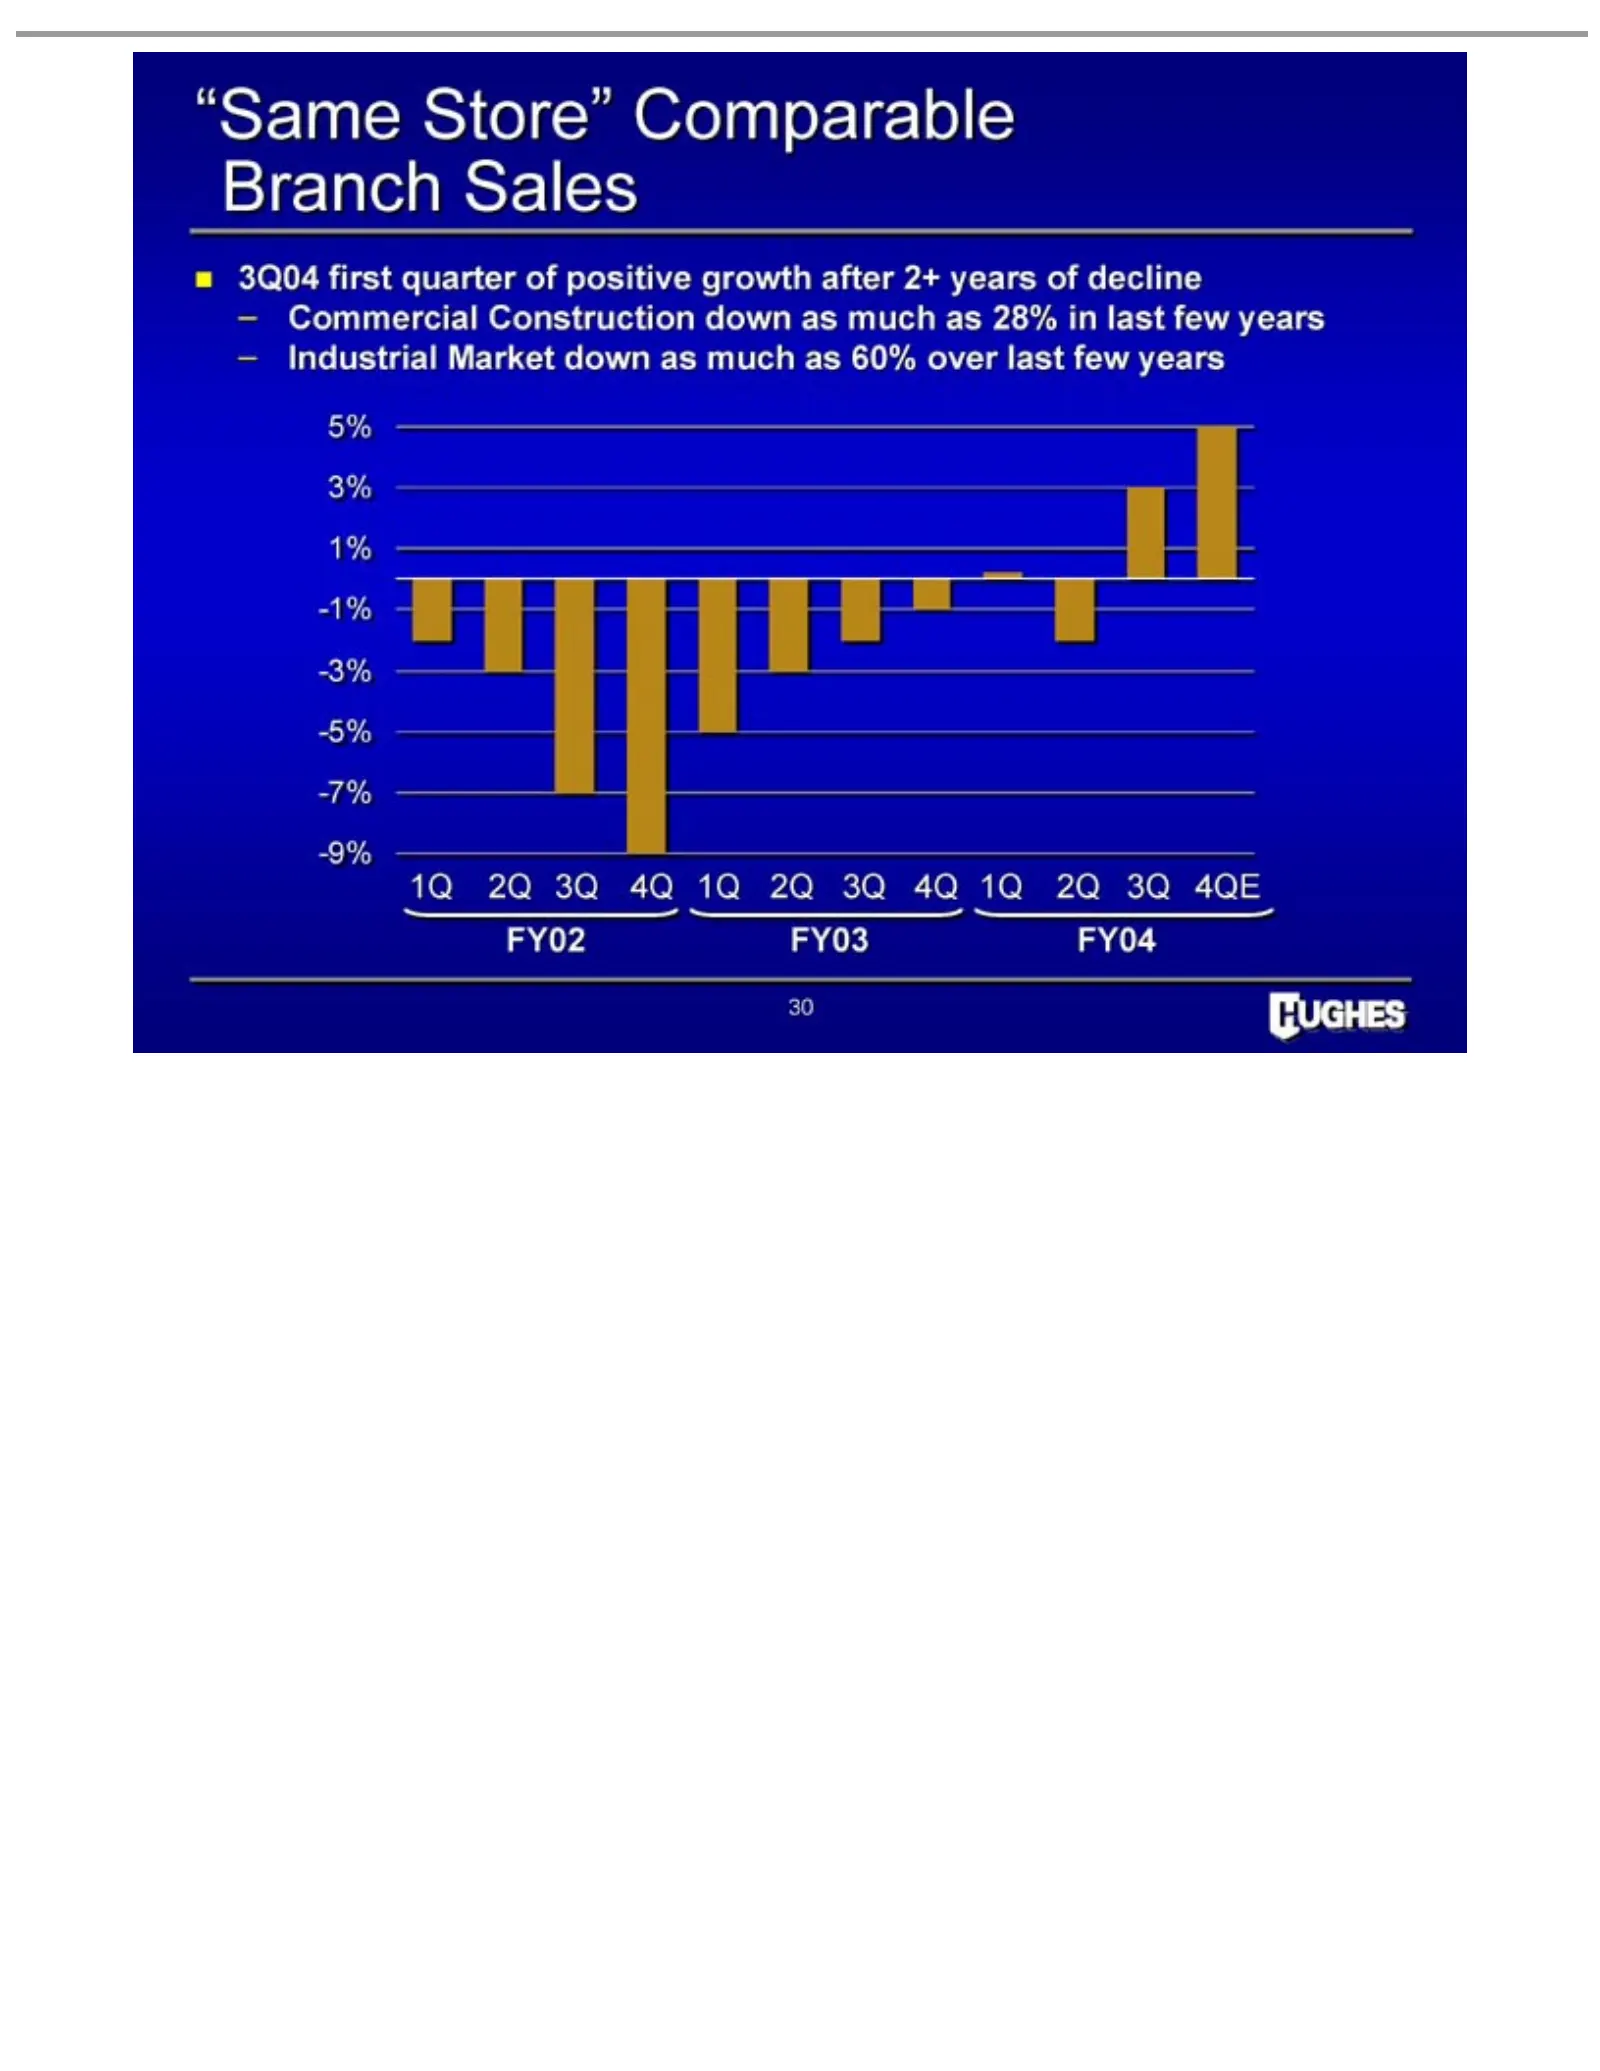
“Same 3Q04 – 1Q FY02 30Commercial Industrial 2Qfirst FY03 Store” 3Q quarter 4Q Market FY04 Comparable 1Q Construction 2Q ofdown positive 3Q 4Q asBranch down much 1Q growth 2Qas Sales as3Q much after 60%4QE2+ over as years 28% lastin of few last decline years few years
Slide 32: Profitability
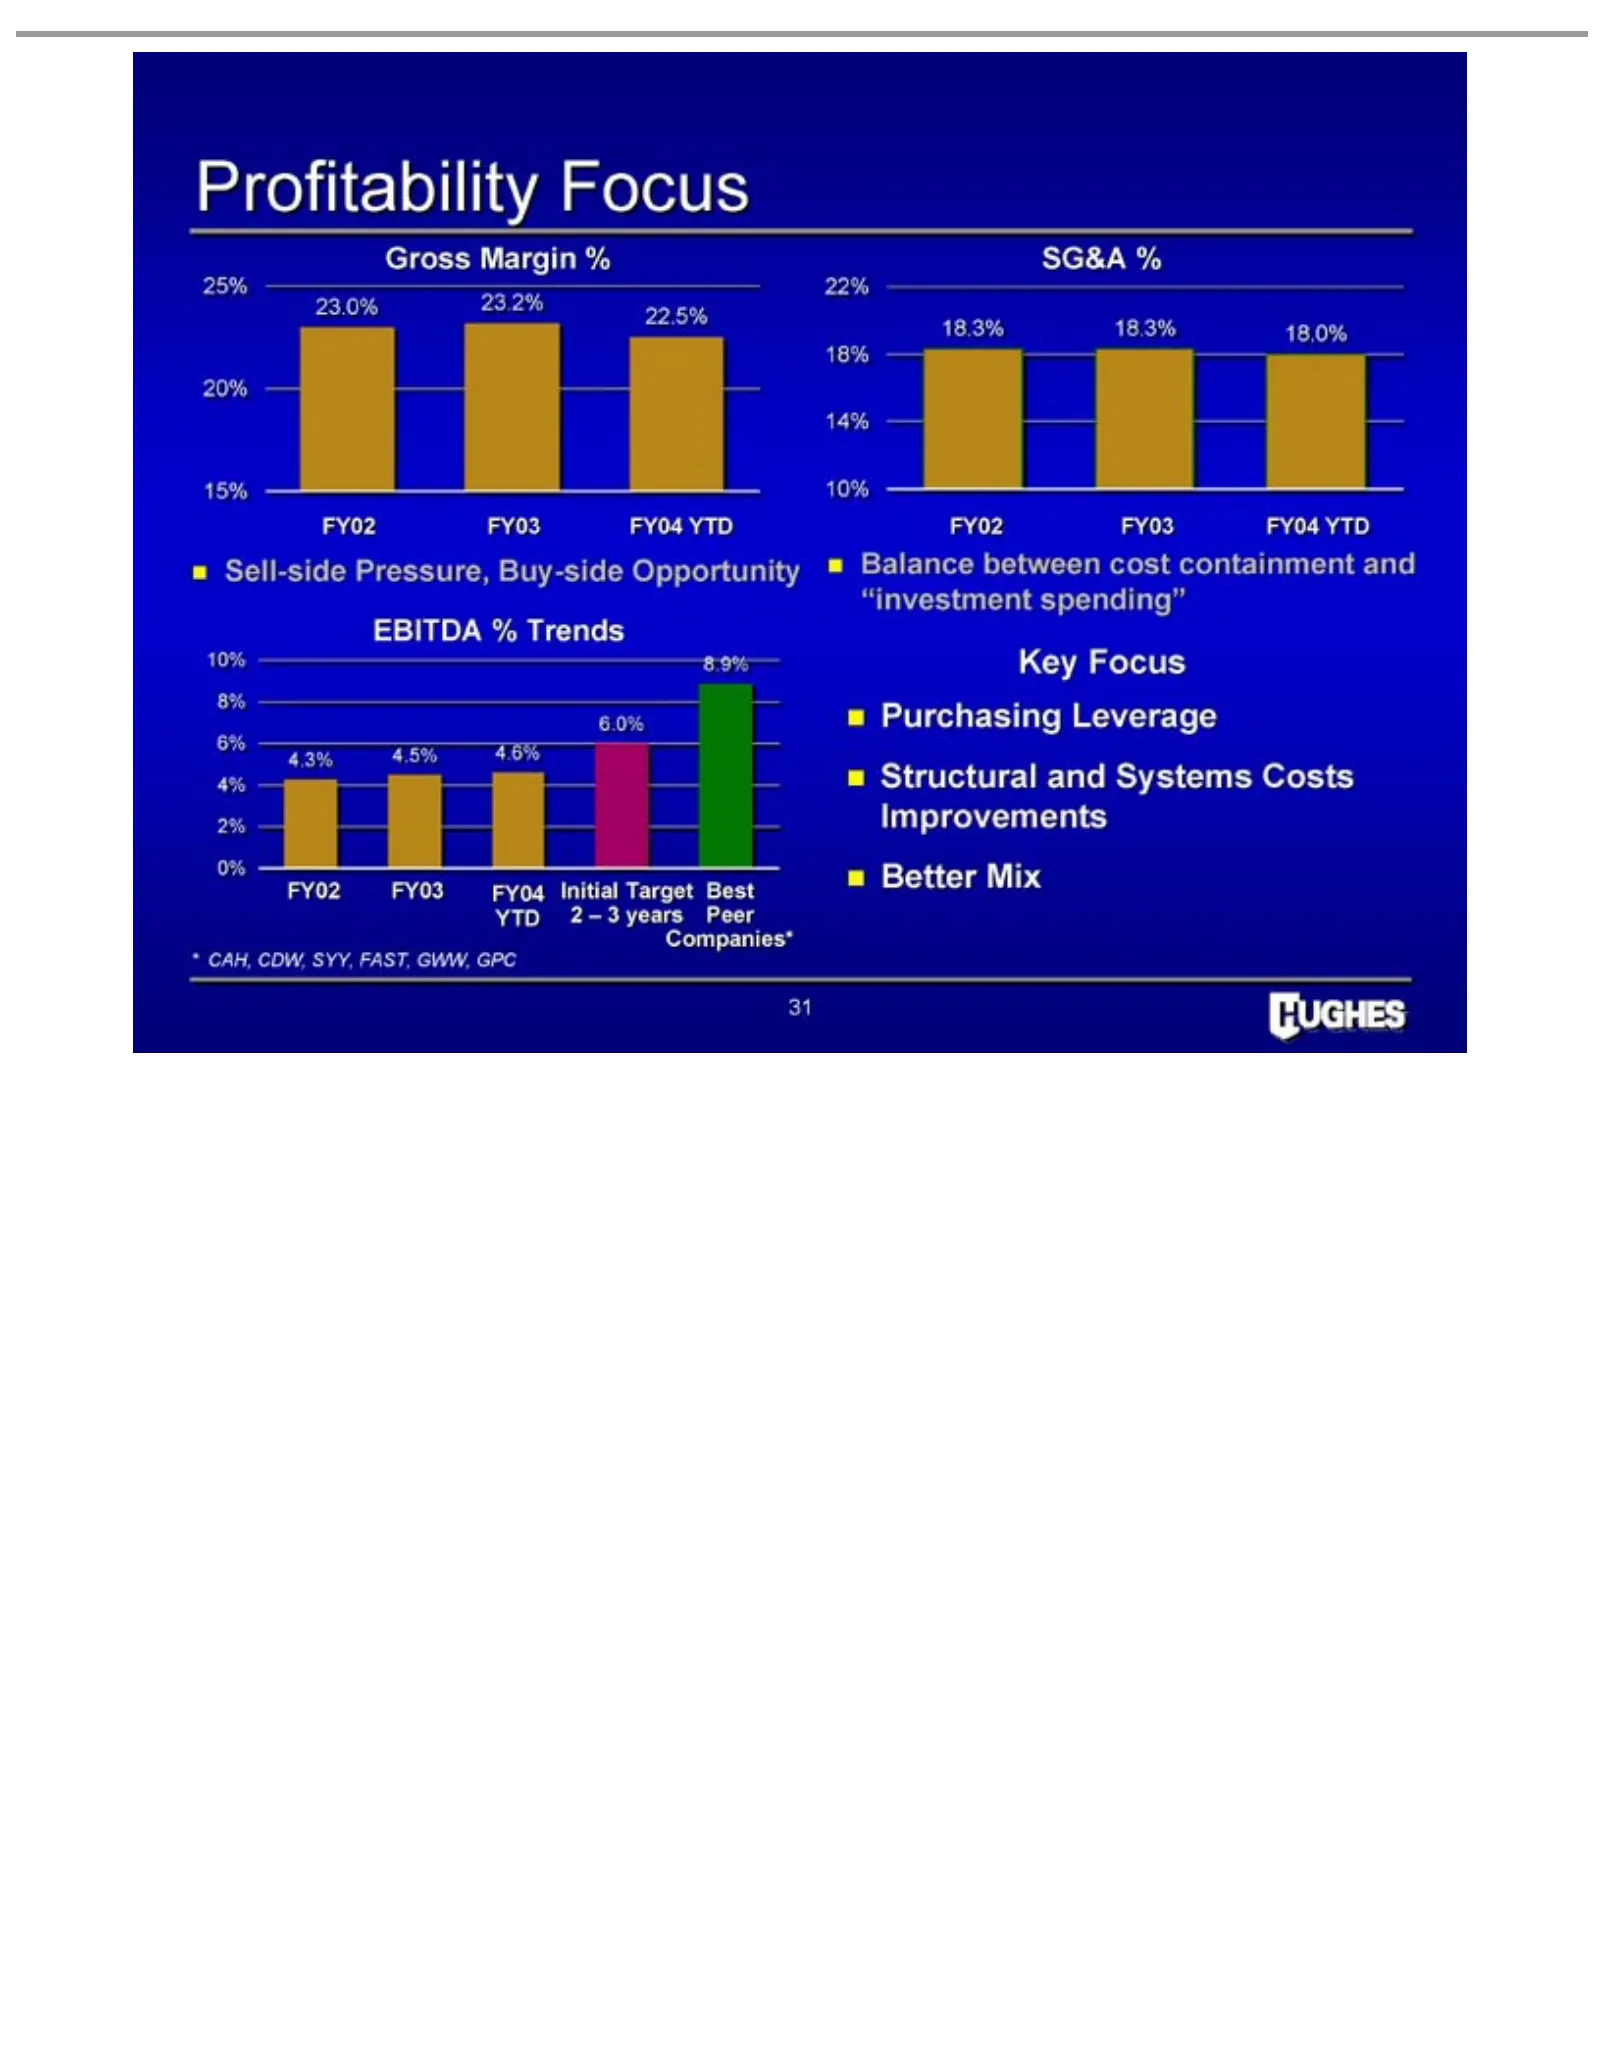
Profitability Gross Sell-side “investment EBITDA FY02 YTD * Companies* Key Purchasing Structural Better 31CAH, Focus 2FY03 Margin Mix –CDW, Pressure, 3and years Leverage FY04 spending” Focus %Systems SYY, Trends Peer % Initial Buy-side FAST, SG&A Costs Target GWW, Opportunity Improvements Best % GPC
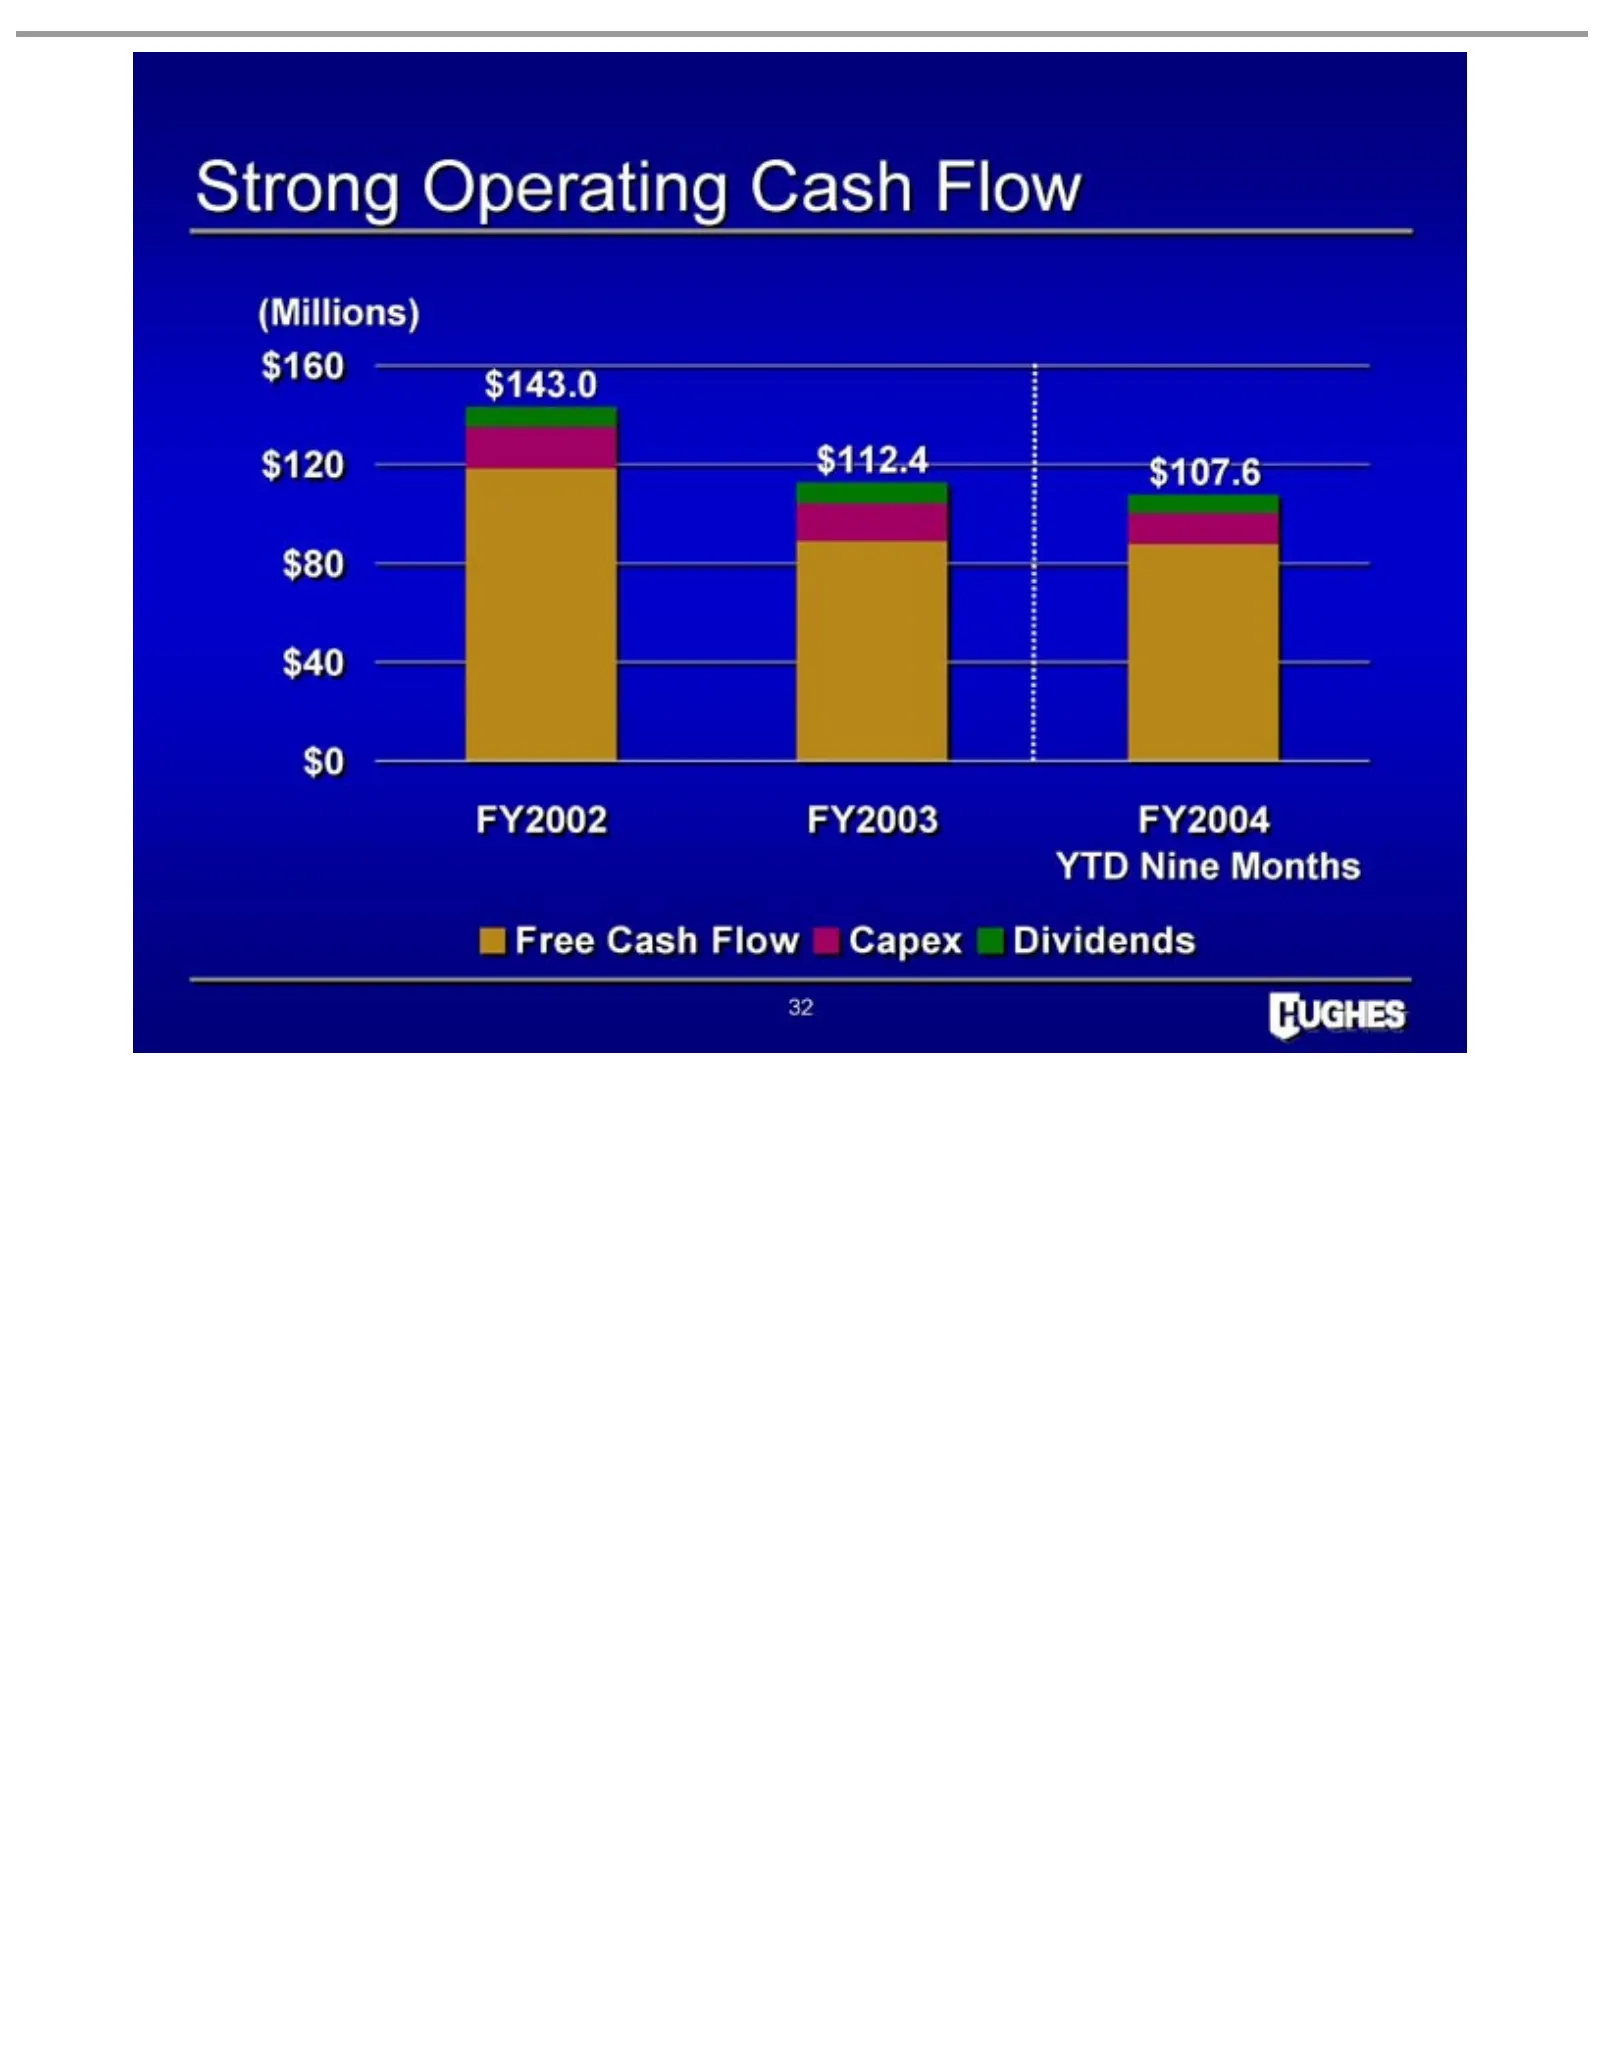
Slide 33: Strong Free Cash Flow
Strong FY2002 (Millions) YTD Free 32 Cash Nine Operating FY2003 Flow Months Capex FY2004 Cash Dividends Flow
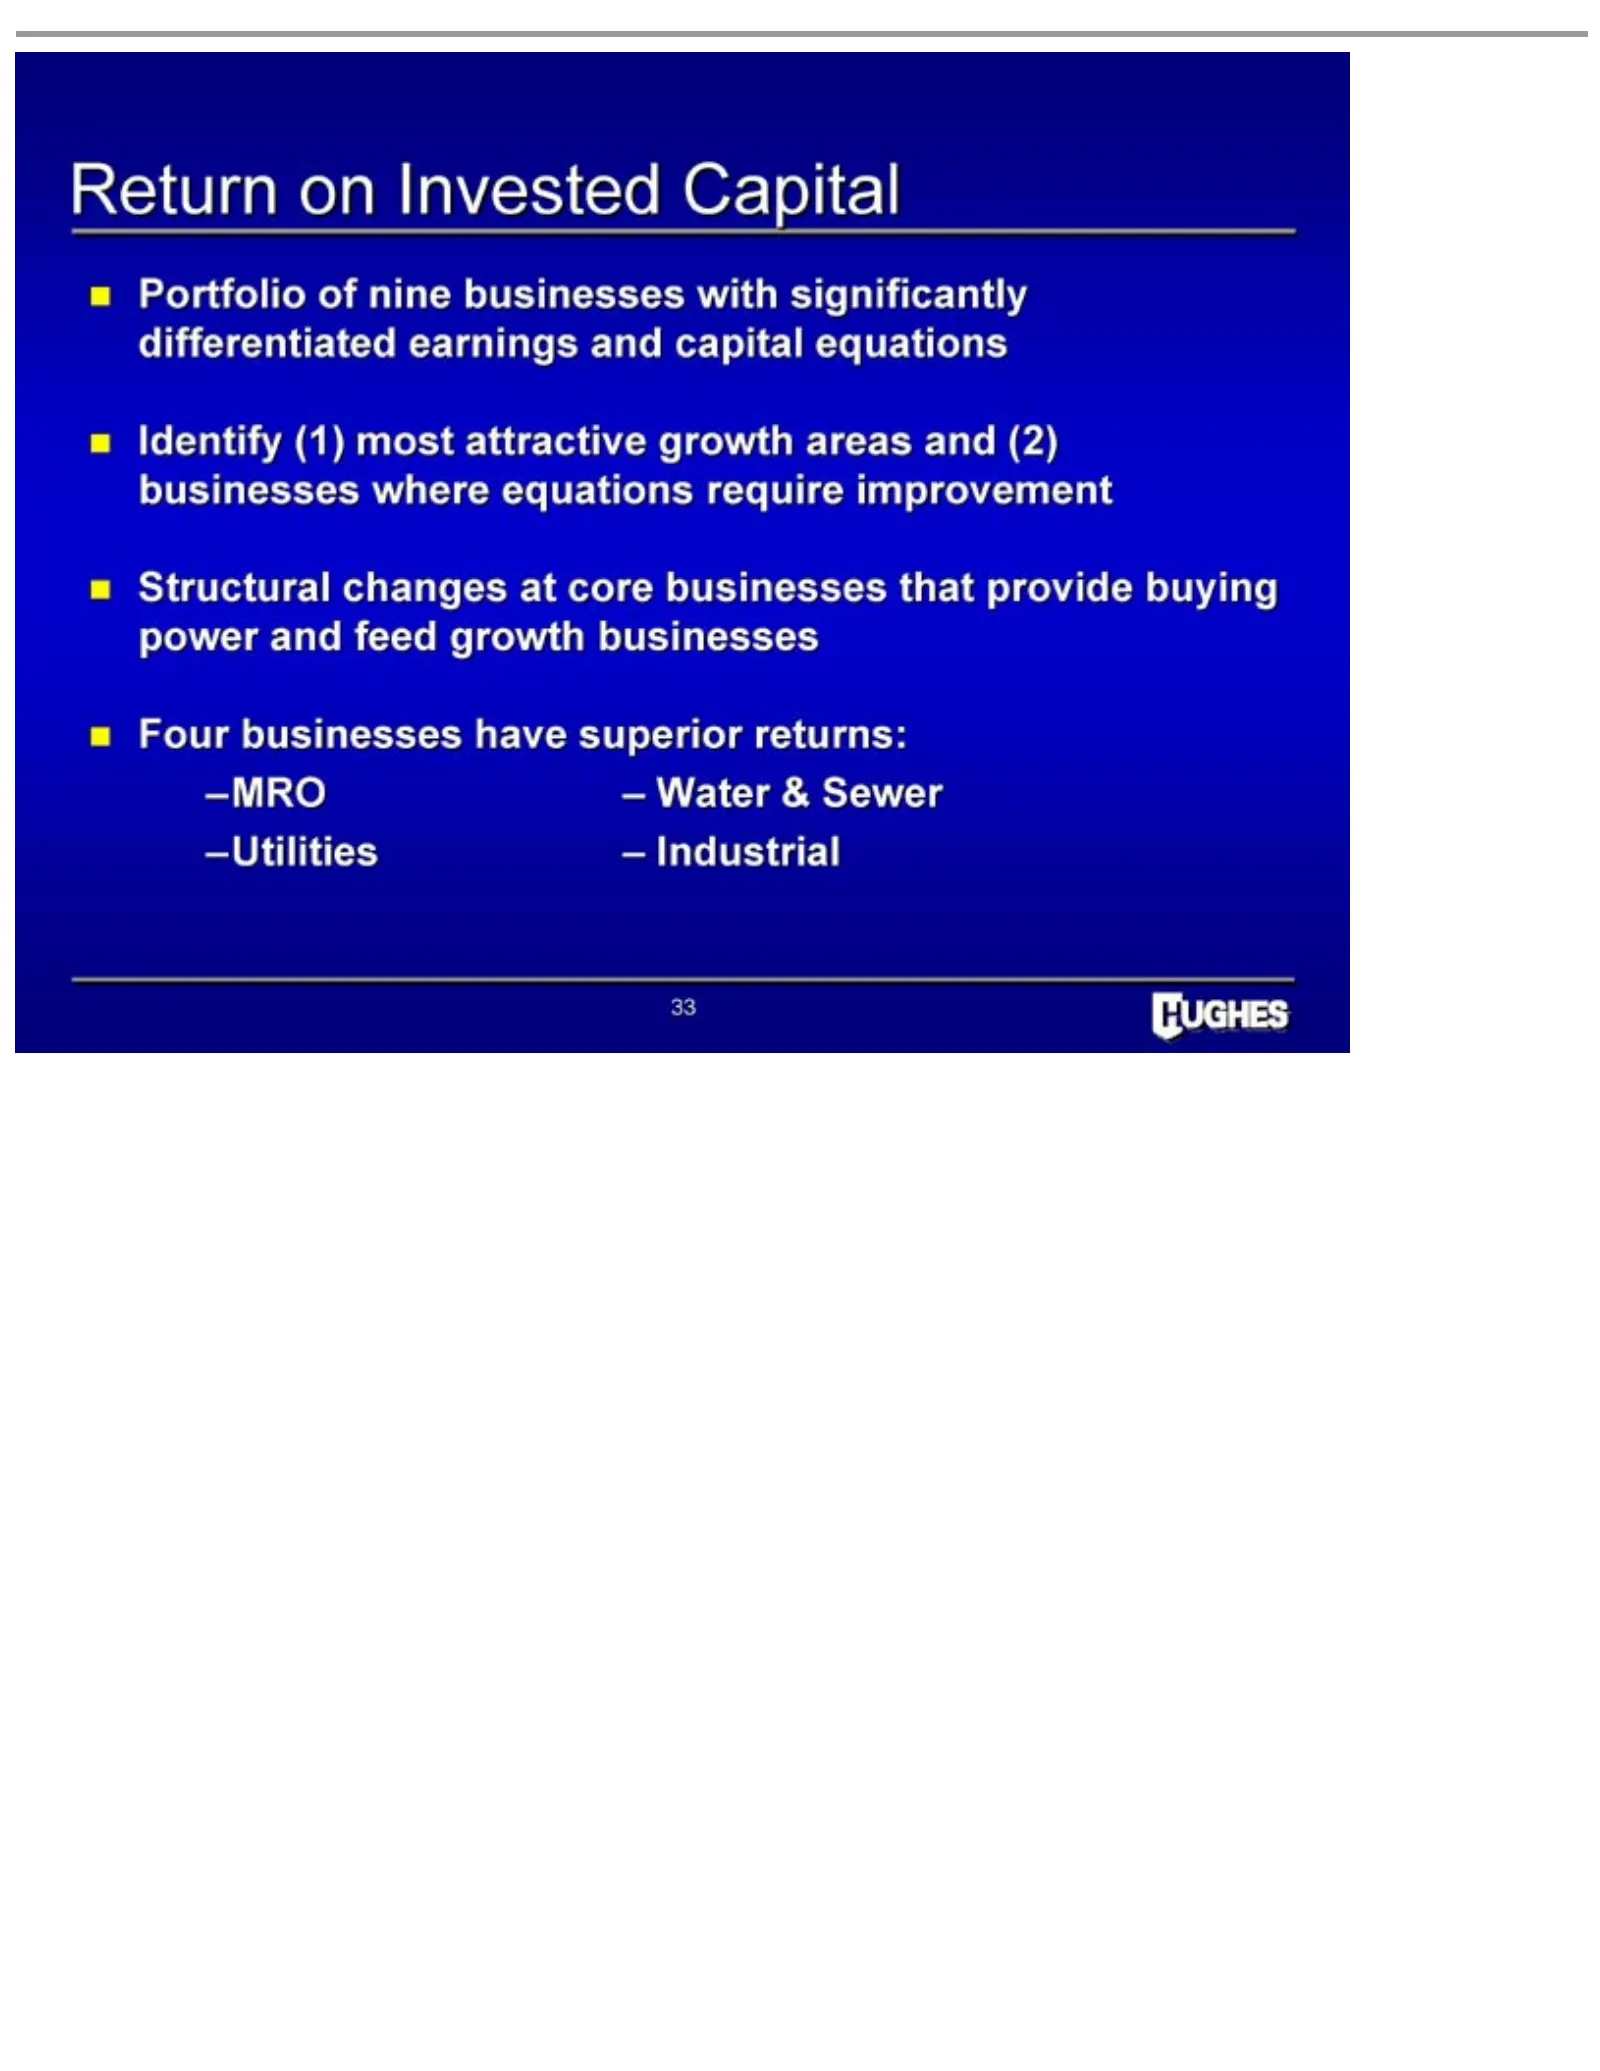
Slide 34: Return on Invested Capital Portfolio
Return Portfolio Identify Structural Four –MRO –Utilities 33 businesses on –(1) Water of –changes Invested Industrial most nine& have businesses attractive Sewer at Capital core superior businesses growth with returns: significantly areas thatand provide (2) differentiated businesses buying power wh
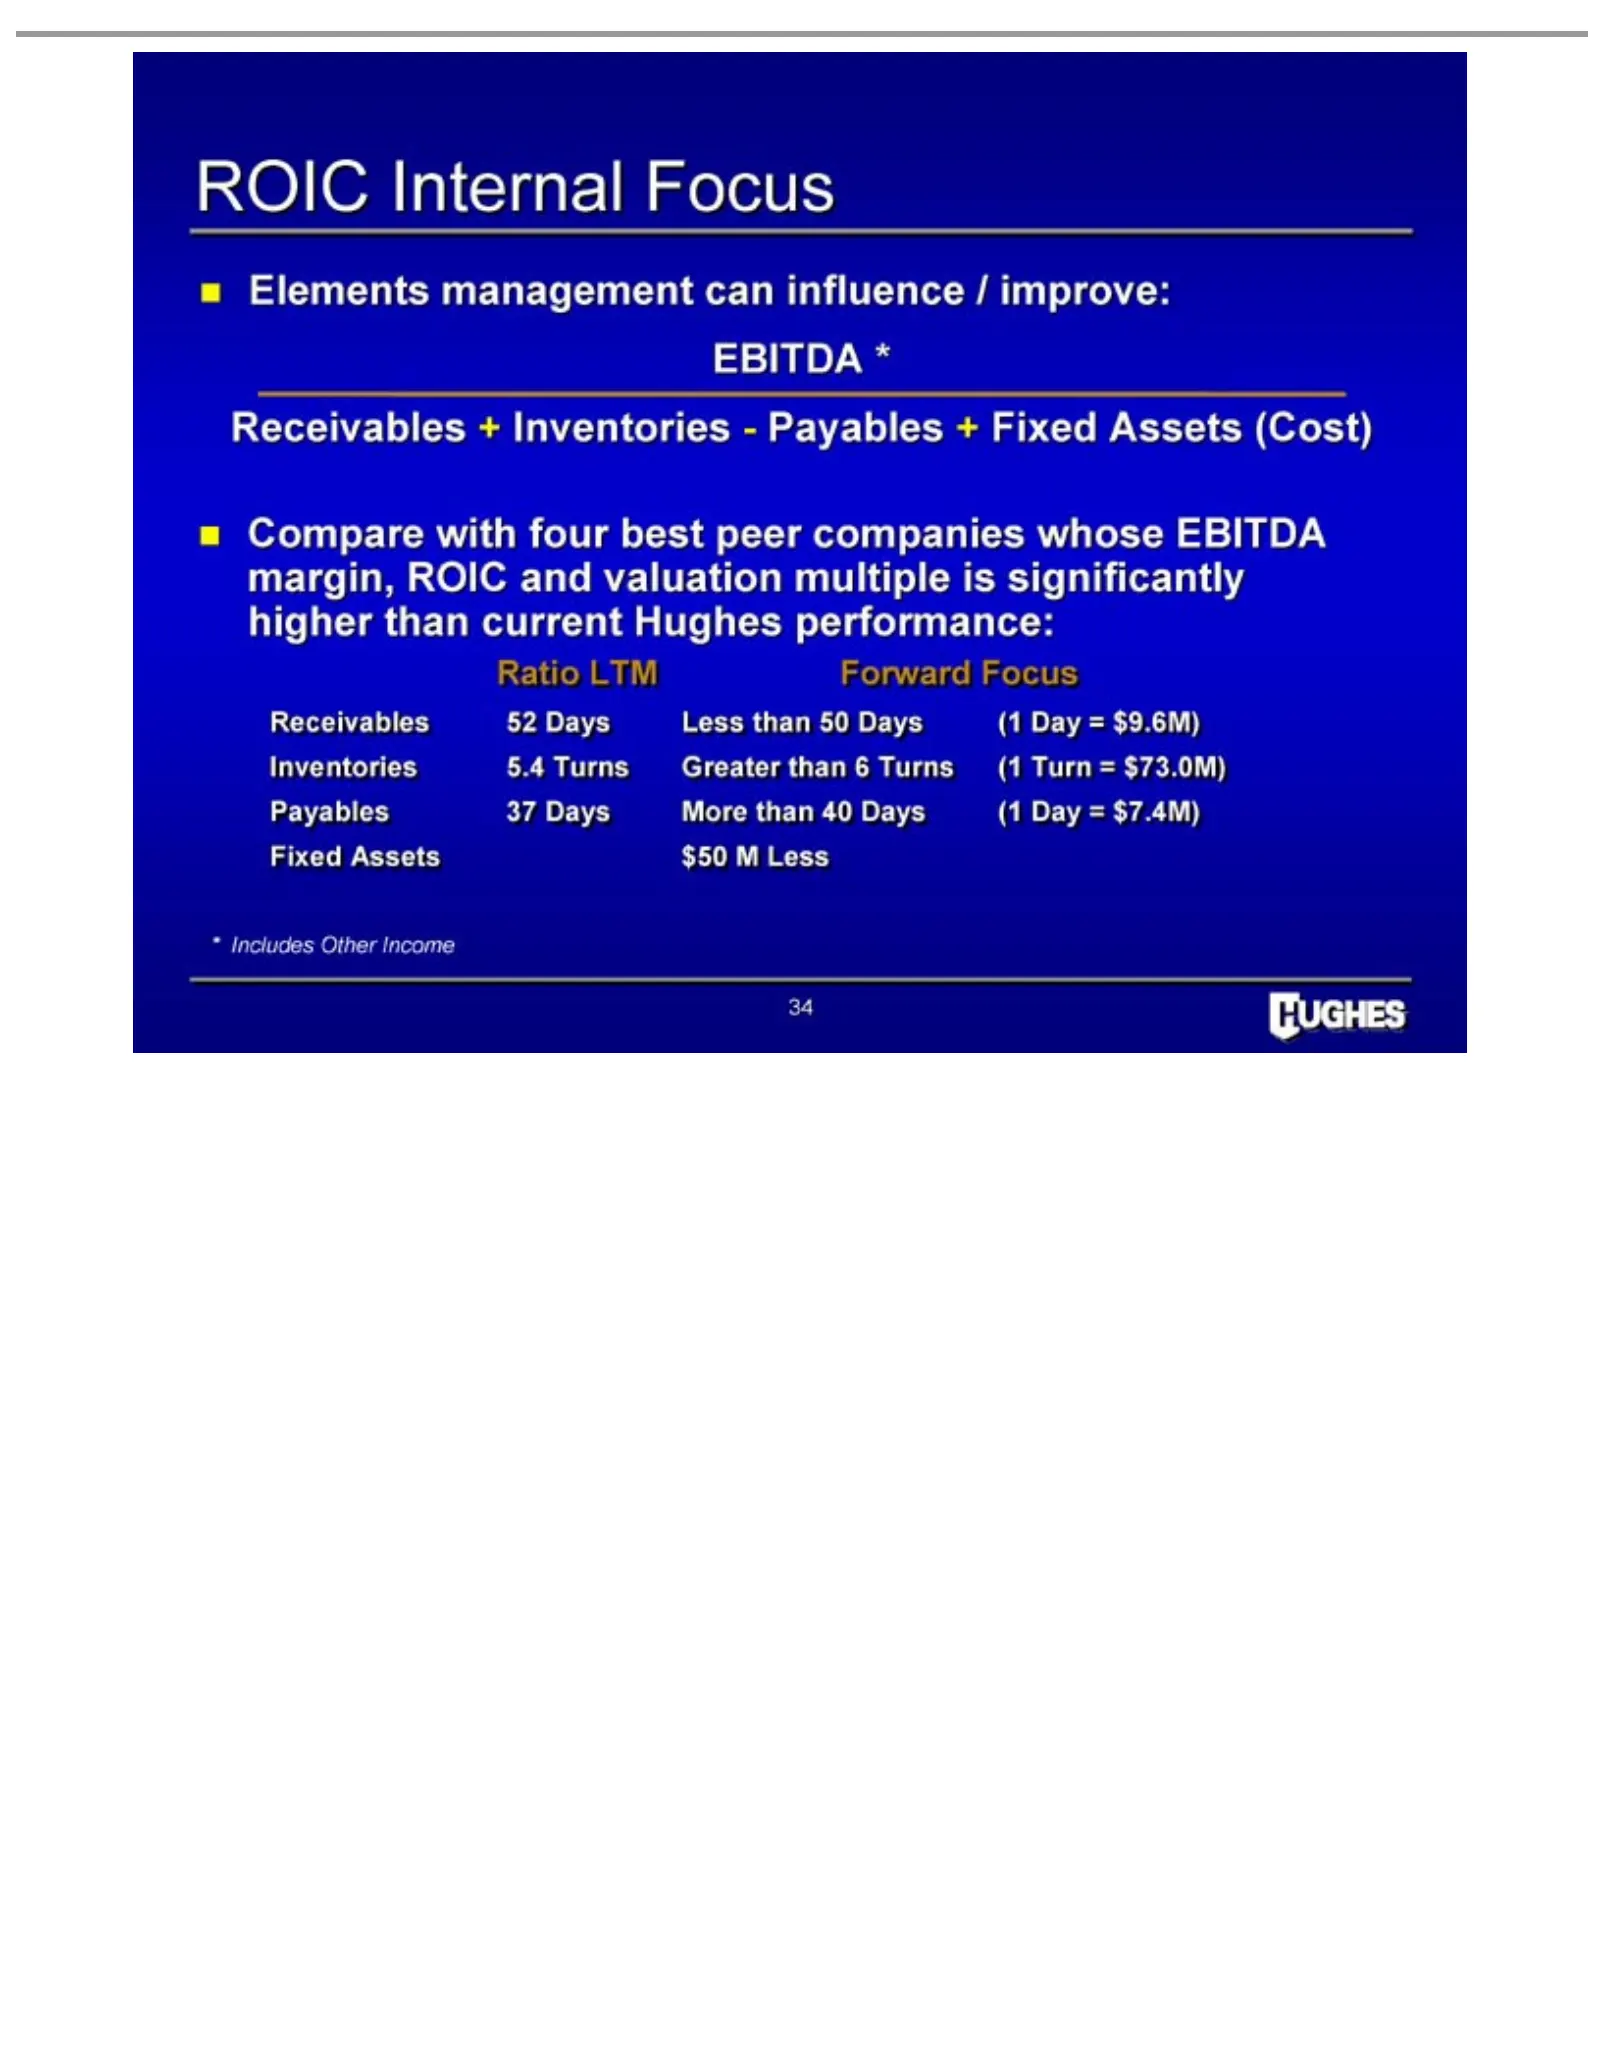
Slide 35: ROIC Elements
ROIC Elements Compare Ratio Receivables Inventories Payables Fixed * 34Includes LTM Assets Internal 37 with management Other Forward 5.4 Days +$ Inventories—Payables 52 four Focus $Turns Days 50 Income More best MFocus Less 5.4 Less can peer than Greater than influence companies 4050 Days than Days
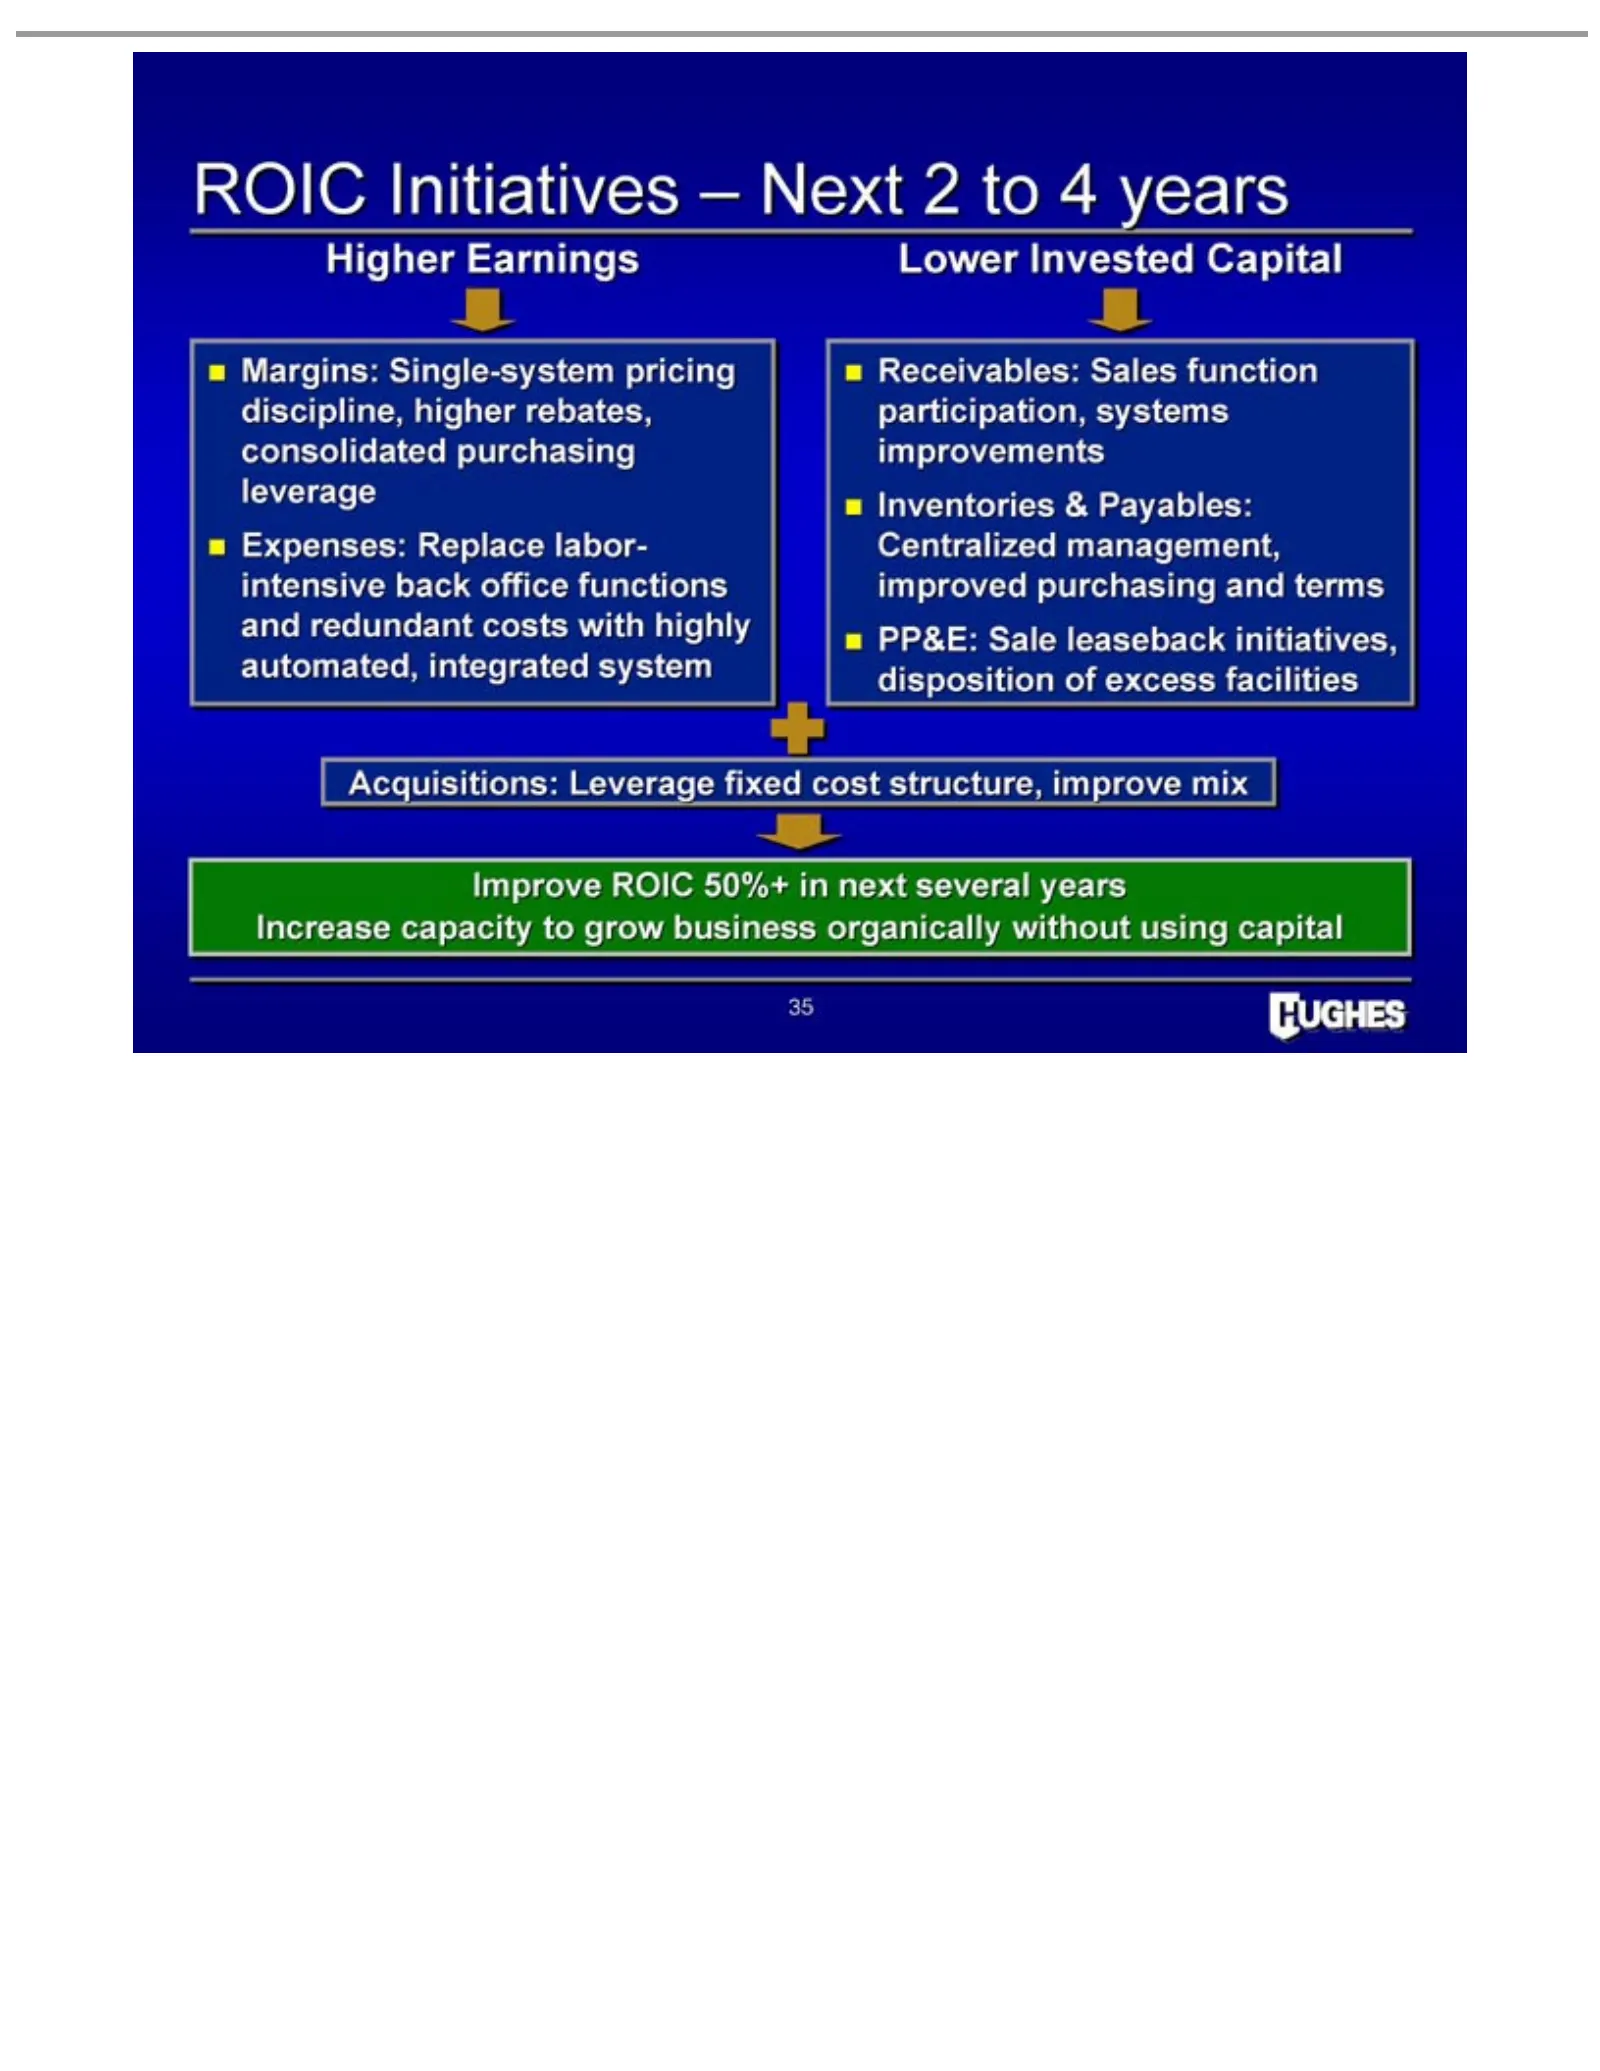
Slide 36: Initiatives to Improve ROIC
ROIC Higher Margins: discipline, consolidated Expenses: leverage intensive and automated, Lower Receivables: participation, Inventories improvements Centralized improved PP&E: disposition Acquisitions: Improve Increase 35 redundant Initiatives Invested Earnings Sale capacity ROIC Single-system back
Slide 37: Pro Forma Capitalization
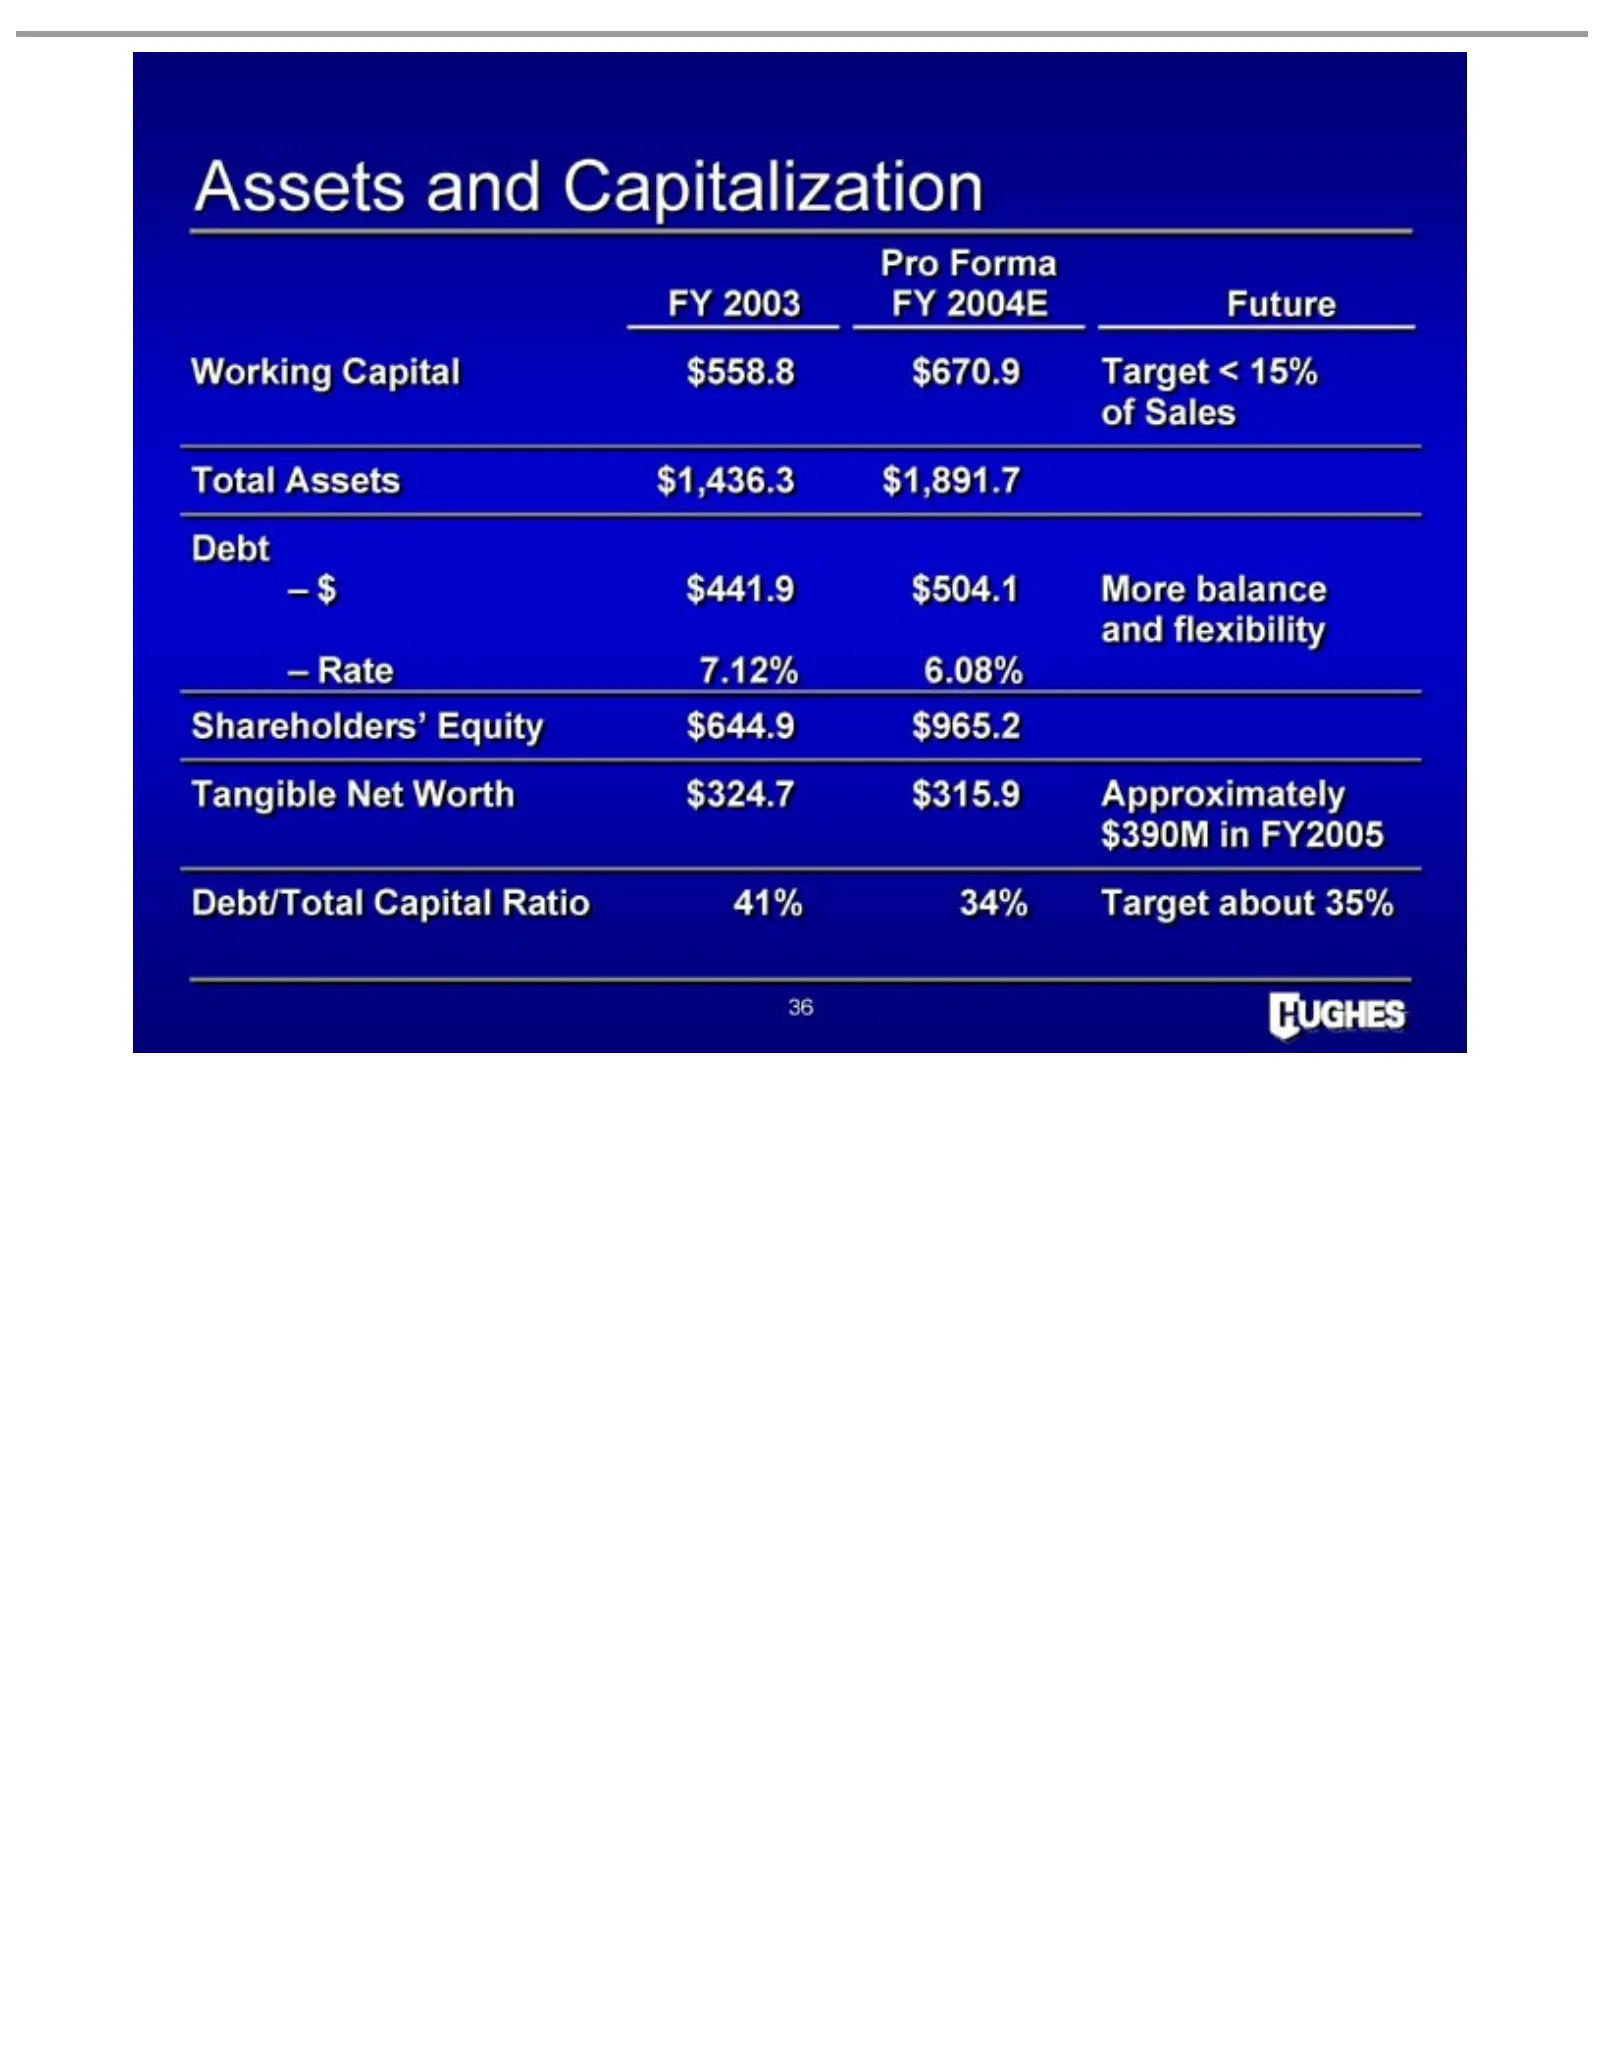
Assets Pro FY Working Total Debt – Shareholders’ Tangible Debt/Total 36$ 2003 Rate $441.9 Forma Assets 7.12% and Capital Net FY$504.1 Capital Capitalization $1,436.3 2004E Worth 6.08% Equity $558.8 More Ratio Future $324.7 $644.9 $1,891.7 $670.9 balance 41%$315.9 $965.2 34% Target and Approximately
Slide 38: Strategic Financial Goals
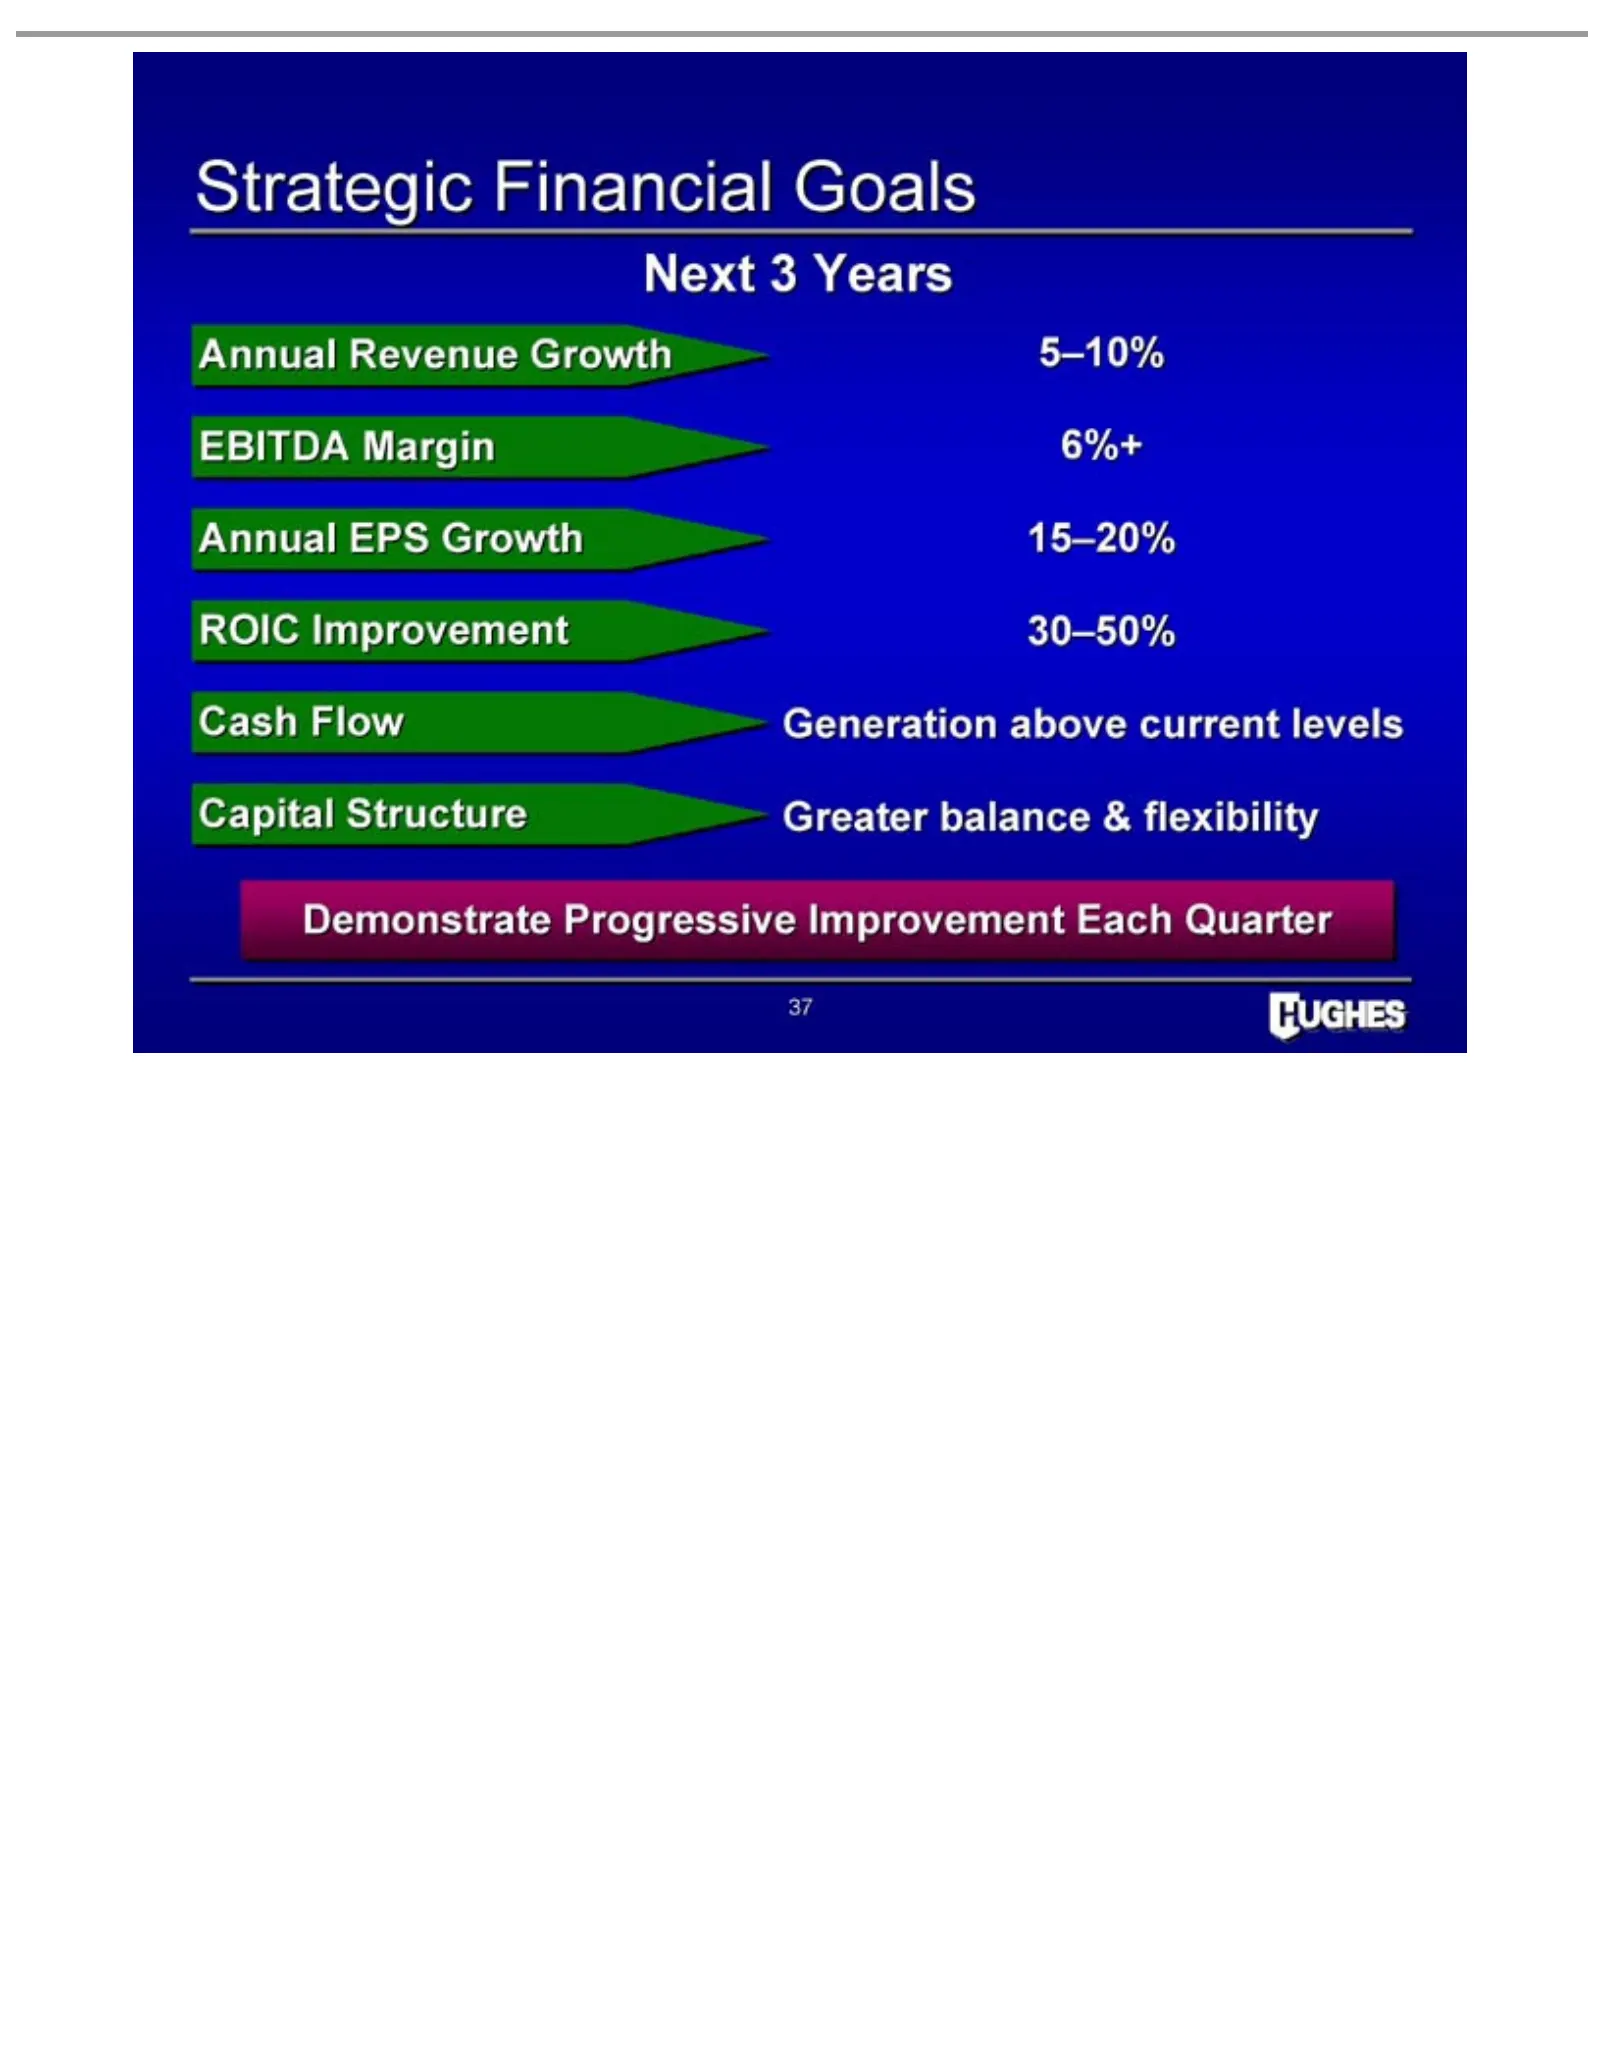
Strategic Next EBITDA Annual ROIC Cash Capital Demonstrate 37 3Flow Improvement Years Structure Revenue EPS Financial Margin Generation Growth Progressive Growth 6%+ Greater Goals 30–50% 15–20% above 5–10% Improvement balance current & flexibility levels Each Quarter
Slide 39: Key Investment Highlights
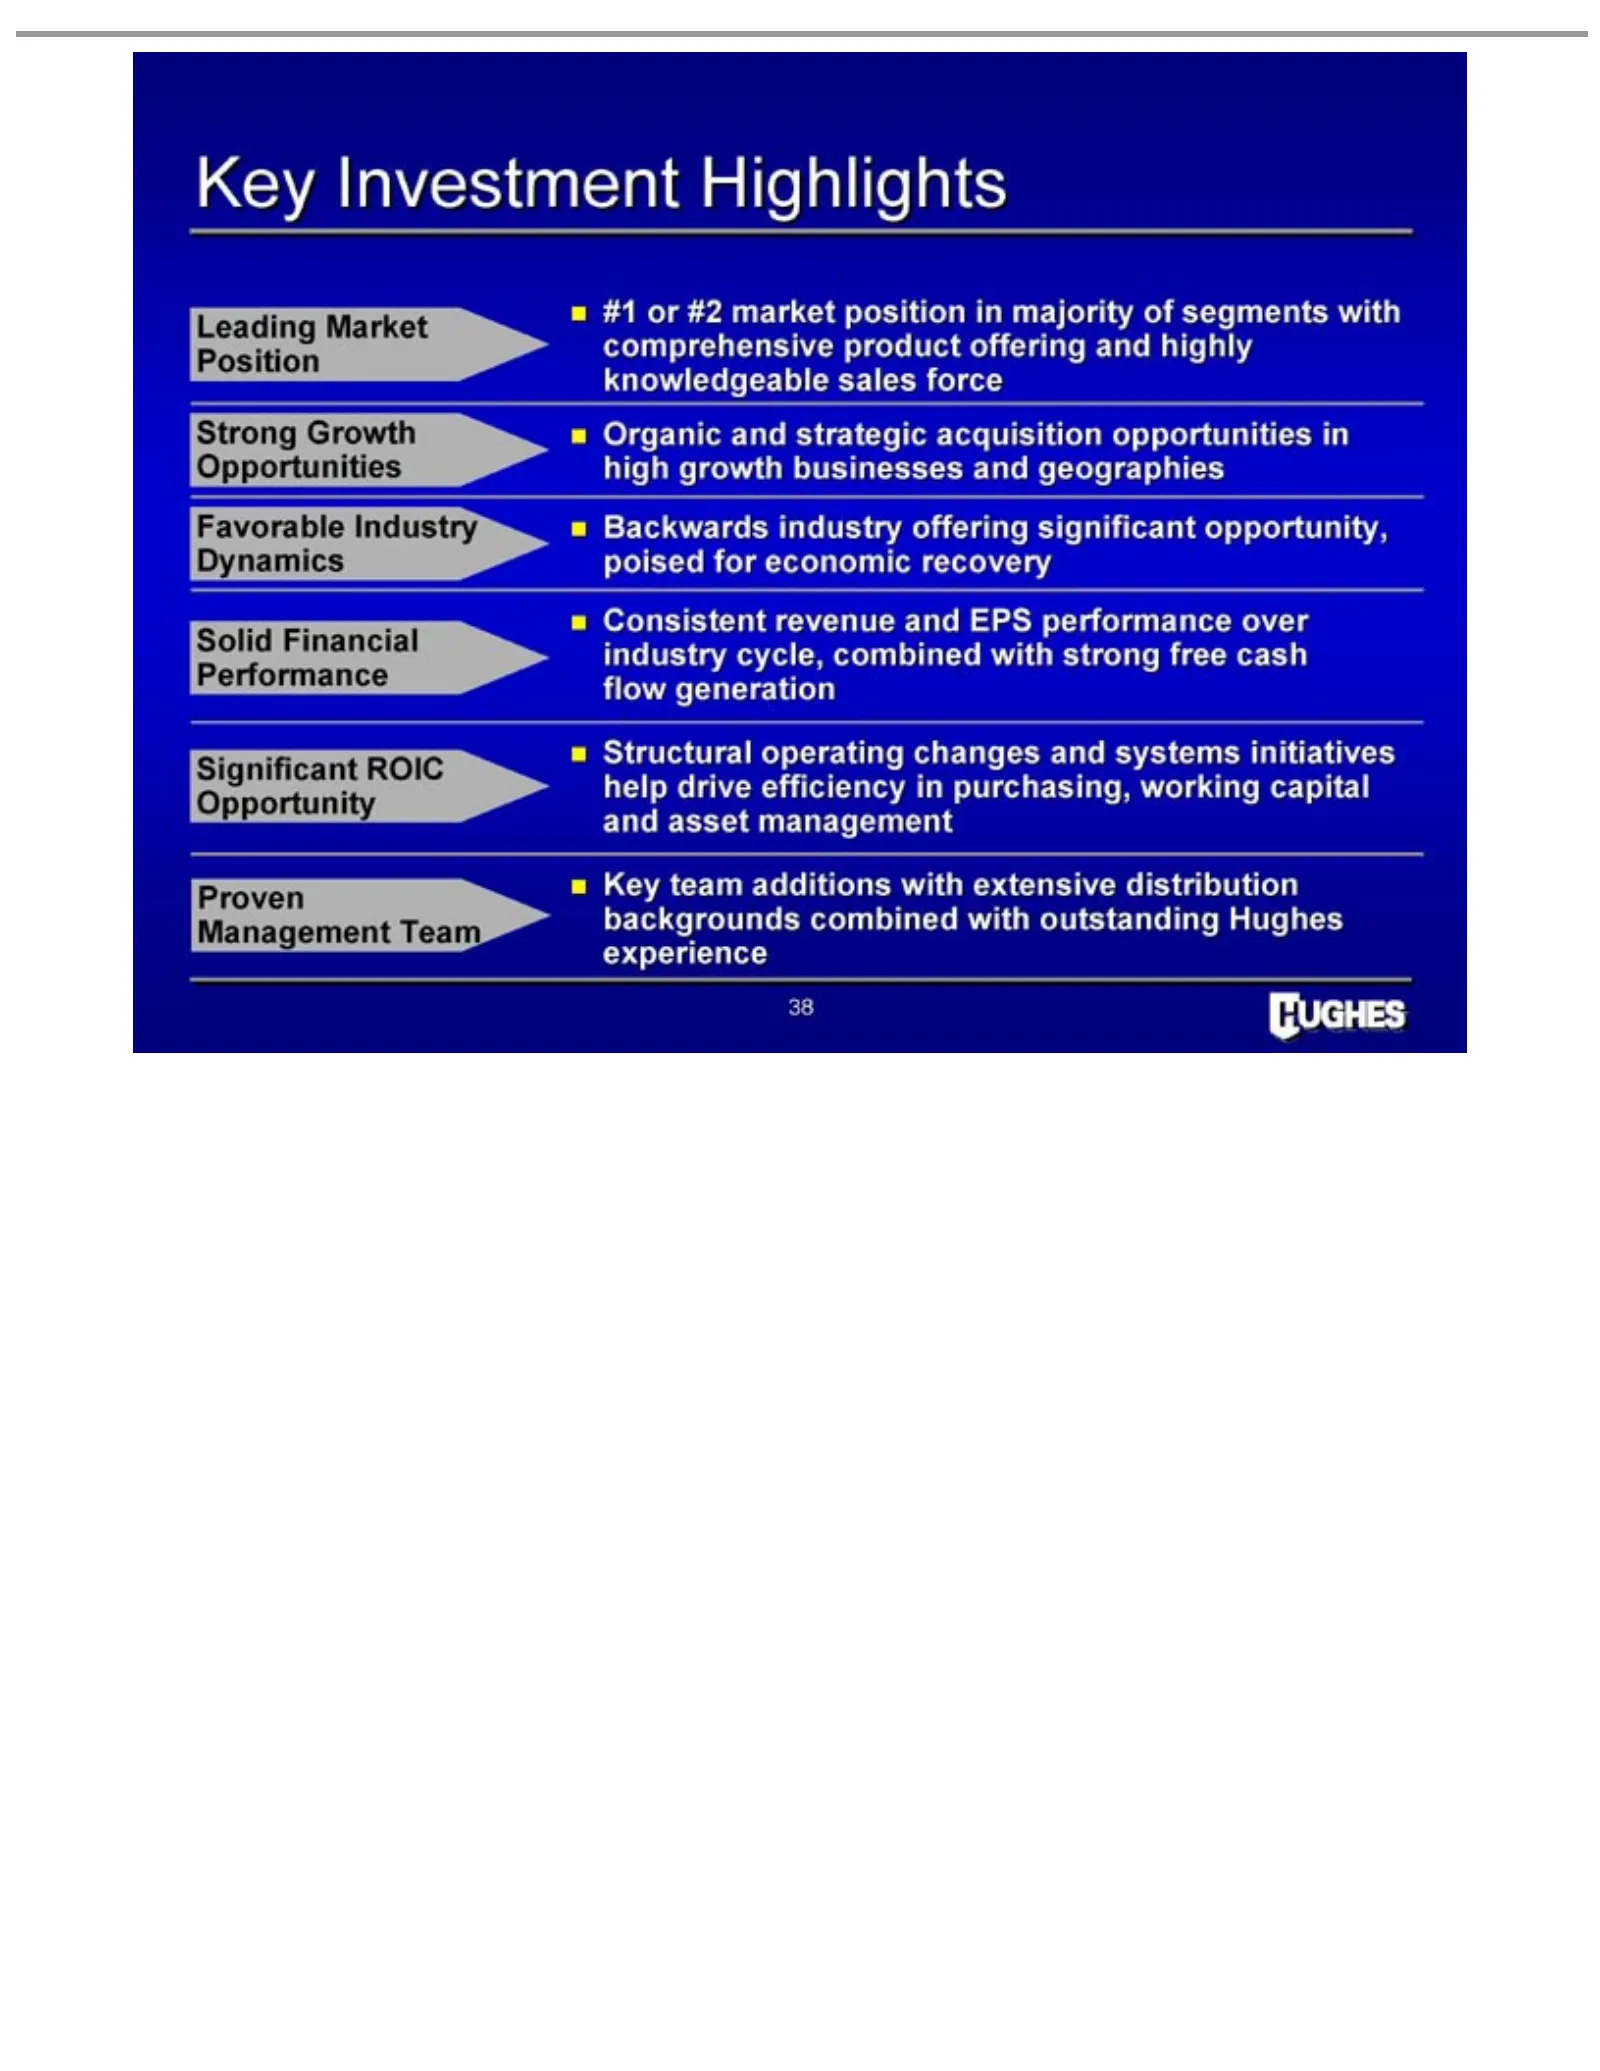
Keyorasset #1 Leading Position Strong Opportunities Favorable Dynamics Consistent Solid Performance Significant Opportunity and Proven Management 38 experience Investment #2 Financial Growth Key Market knowledgeable market management Industry poised revenue ROIC team help flow Team high Organic indu
Source: SEC EDGAR · 8-K filed Feb 2, 2004