Ascena Retail — Investor Day (October 2013)
150 slides from Ascena Retail's investor day presentation, Oct 9, 2013
Slide 1: Investor Conference October 9, 2013
Investor Conference October 9, 2013
Slide 2: Forward Looking Statements
Forward Looking Statements This presentation contains forward - looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 . Forward - looking statements involve known and unknown risks and uncertainties, which may cause our actual results in future periods to diff
Slide 3: Historical Financial Information / Non-GAAP Financial Measures
Historical Financial Information Non - GAAP Financial Measures Where indicated, certain financial information herein has been presented on a non - GAAP basis . This basis adjusts for items that management believes are not indicative of the Company’s underlying operating performance . Reference shoul
Slide 4: Introduction Video
INTRODUCTION VIDEO A _— — ascena retail group inc.
Slide 5: Investor Highlights
Investor Highlights David Jaffe President & CEO
Slide 6: Vision
Vision “Serve our shareholders and create value by becoming a family of leading retail concepts with $10 billion in sales and top tier profitability.” 6
Slide 7: Mission
Mission “Making people feel good about themselves.” 7
Slide 8: Ascena Retail Group brands
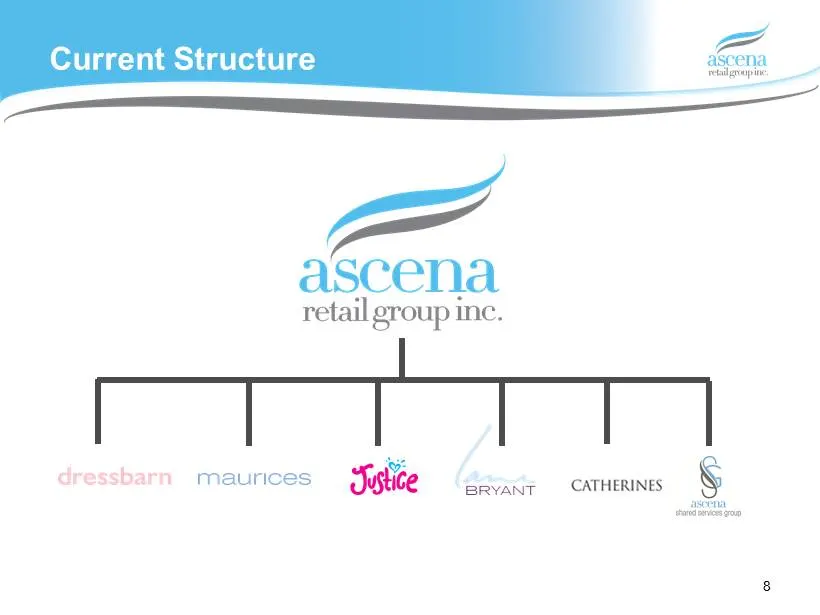
ascena retail group inc. [TIT dressbarn maurices Qfystice BRVANT CATHERINES
Slide 9: Unique Business Model
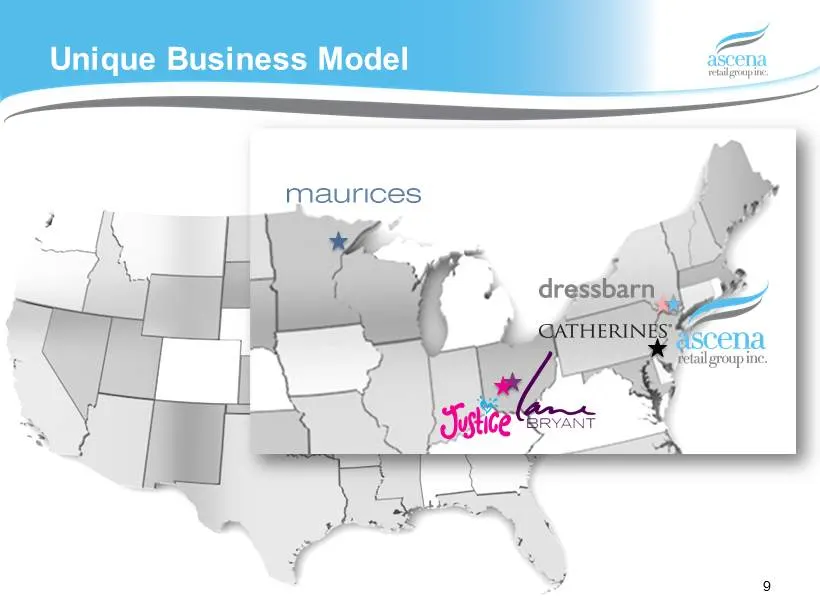
Unique Business Model maurices
Slide 10: Organization Structure
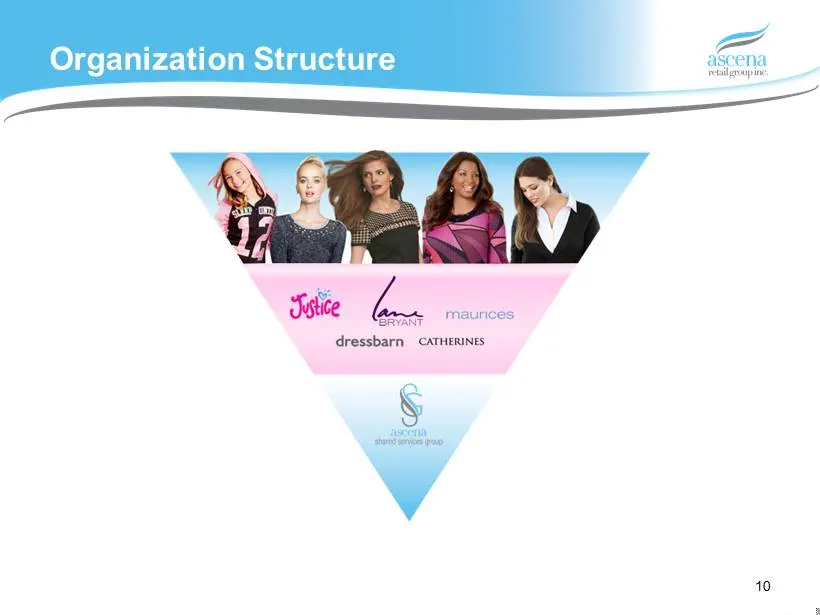
Organization Structure dressbarn CATHERINES sued sone pon 10
Slide 11: Diversification
Diversification 11
Slide 12: Ascena
= ascena renin 12
Slide 13: Investor Highlights
Investor Highlights • Diversified portfolio • Significant top line growth opportunities • Margin upside from shared services & synergies • Strong Balance Sheet & Cash Flow • Future opportunities 13
Slide 14: Justice
Tushice Michael Rayden CEO, Justice oy Justice Aa CATHERINES
Slide 15: Executives Present
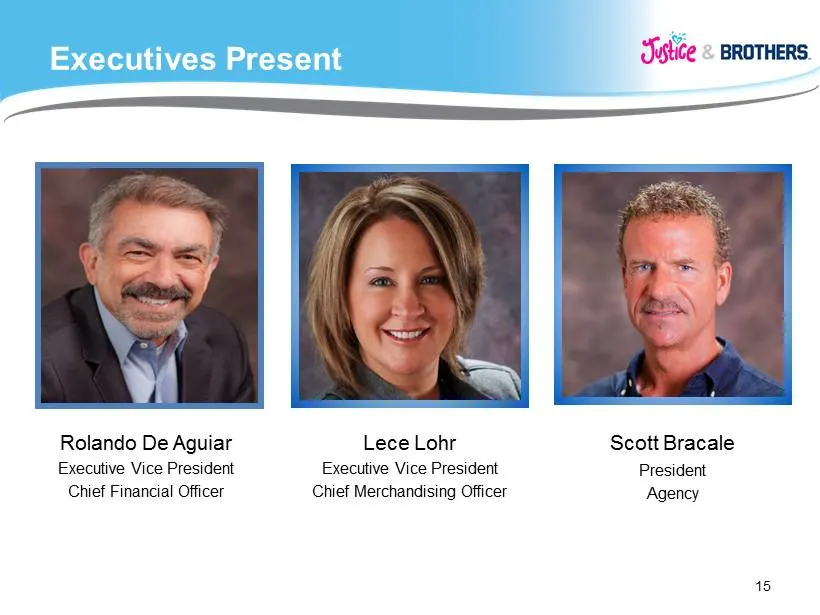
Executives Present 15 Lece Lohr Executive Vice President Chief Merchandising Officer Rolando De Aguiar Executive Vice President Chief Financial Officer Scott Bracale President Agency
Slide 16: Our Mission
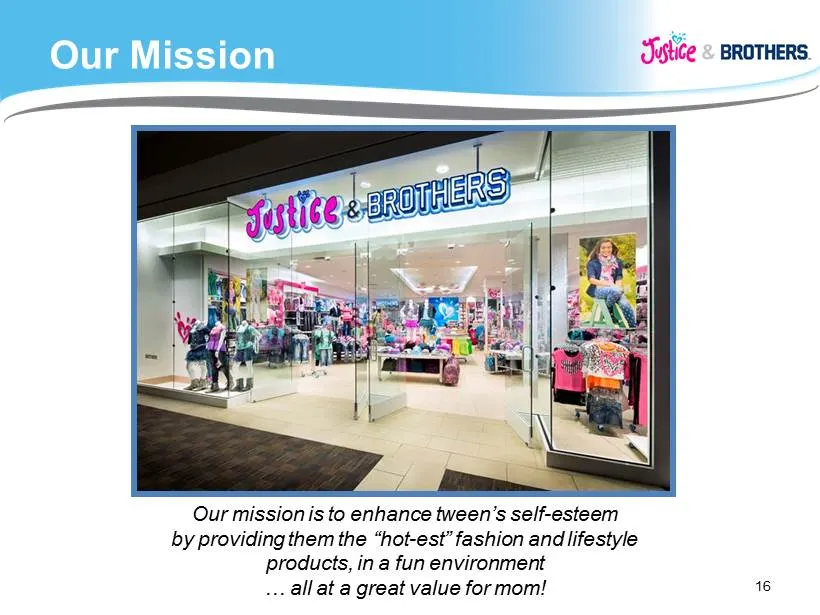
Our mission is to enhance tween’s self - esteem by providing them the “hot - est” fashion and lifestyle products, in a fun environment … all at a great value for mom! 16 Our Mission
Slide 17: Our Positioning
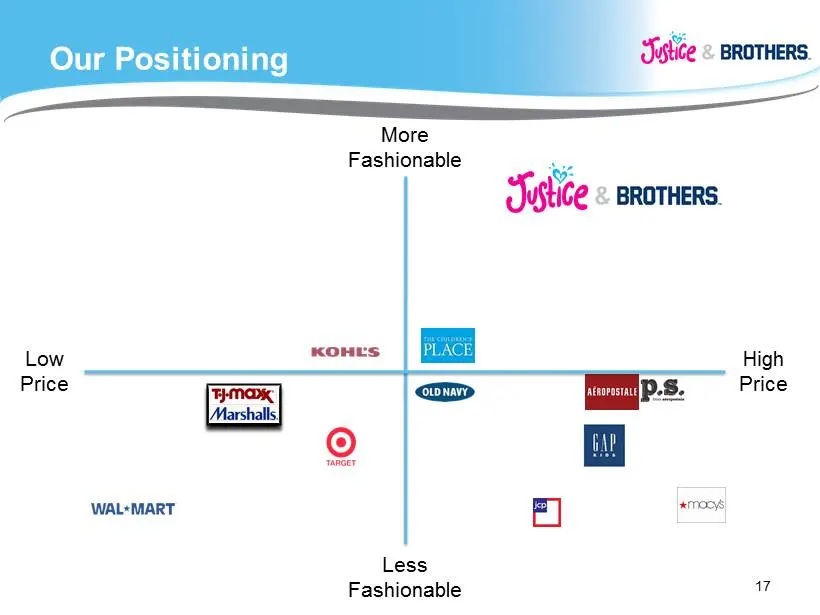
Our Positioning 17 More Fashionable Less Fashionable High Price Low Price
Slide 18: Our FY14 Strategic Initiatives
Our FY14 Strategic Initiatives 18
Slide 19: Our FY14 Strategic Initiatives
Our FY14 Strategic Initiatives • Brothers Brand Expansion • Ecommerce Sales Growth • Justice Sales Growth 19
Slide 20: Brothers
Brothers • Brothers Brand Expansion – Continue to add Brothers into Justice stores 20
Slide 21: Brothers
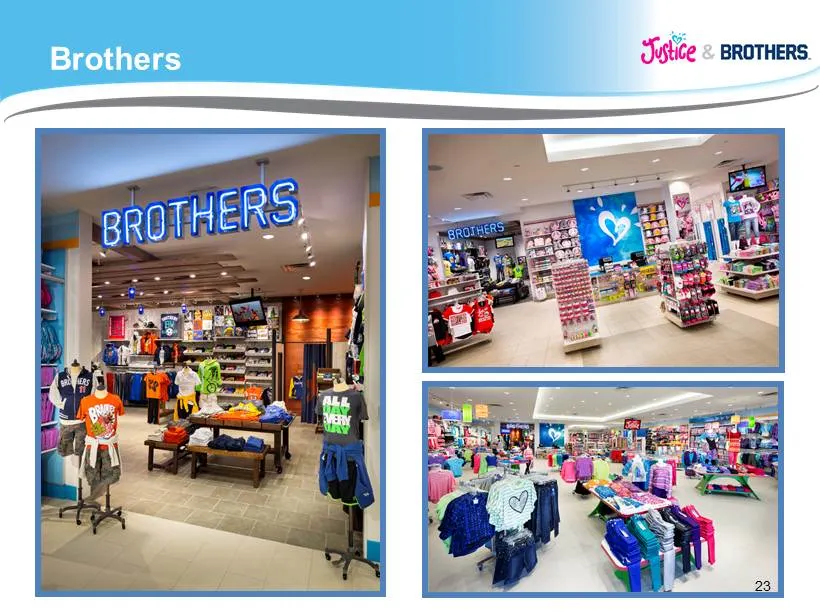
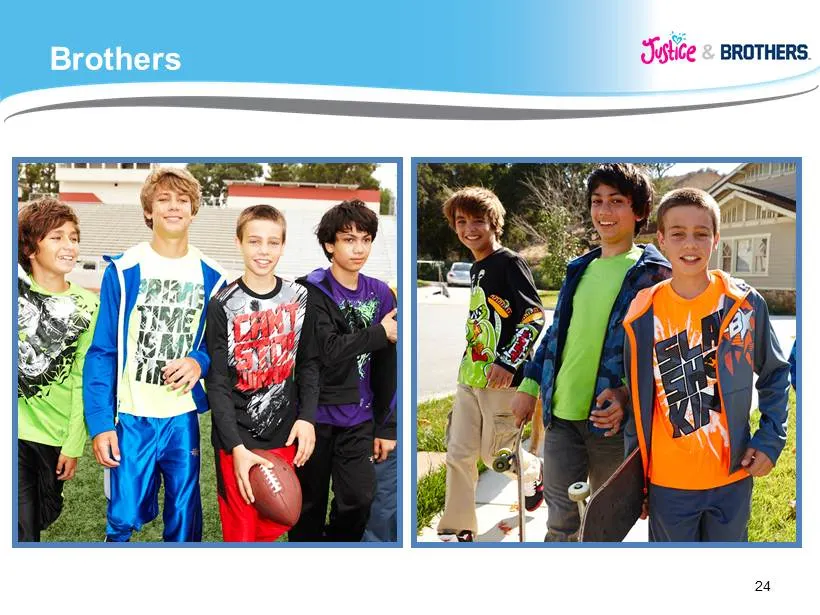
Brothers • Brothers Brand Expansion – Continue to add Brothers into Justice stores – Enhance Brothers apparel assortment and expand into accessories 21
Slide 22: Brothers
Brothers • Brothers Brand Expansion – Continue to add Brothers into Justice stores – Enhance Brothers apparel assortment and expand into accessories – Grow margin rates and dollars 22
Slide 23: Justice Brothers
Sushice © BROTHERS.
Slide 24: Justice Brothers
Suslice & BROTHERS 24
Slide 25: FY14 Strategic Initiatives: Ecommerce Sales Growth
FY14 Strategic Initiatives • Ecommerce Sales Growth 25
Slide 26: Ecommerce
Ecommerce • Ecommerce Sales Growth – Leverage New Platform 26
Slide 27: Ecommerce: Make Price Savings More Visible
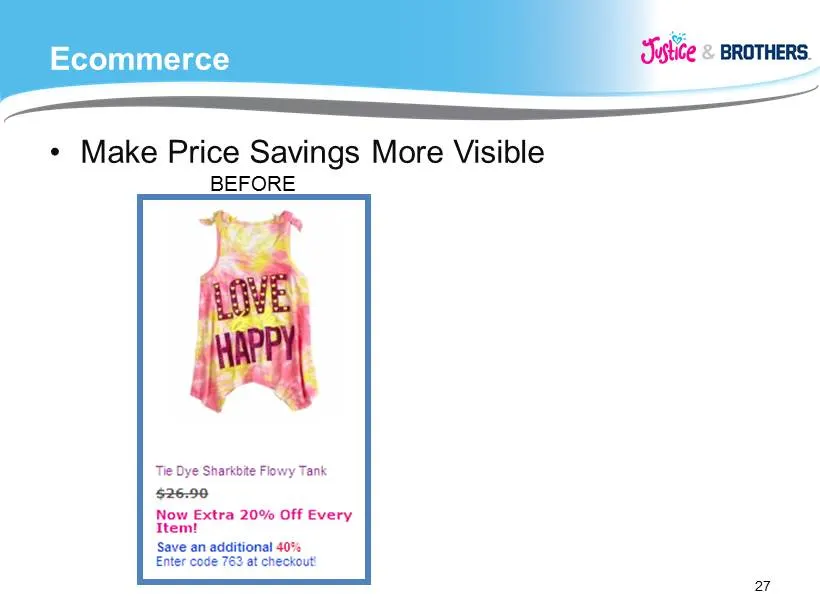
Ecommerce • Make Price Savings More Visible 27 BEFORE
Slide 28: Ecommerce: Make Price Savings More Visible
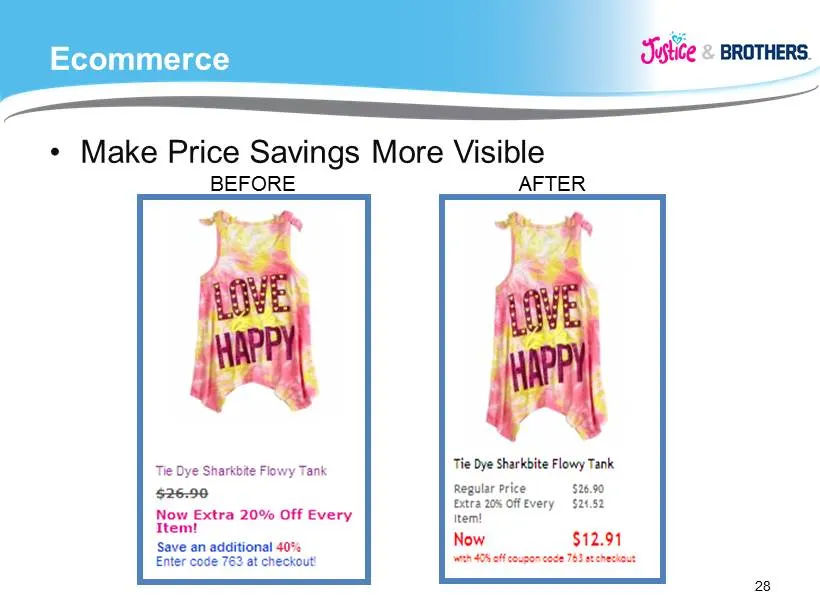
Ecommerce • Make Price Savings More Visible 28 BEFORE AFTER
Slide 29: Ecommerce
Ecommerce • Ecommerce Sales Growth – Leverage New Platform – Making Our Price Savings More Visible – Enhance Mobile Capabilities 29
Slide 30: FY14 Strategic Initiatives: Justice Sales Growth
FY14 Strategic Initiatives • Justice Sales Growth 30
Slide 31: Justice: Deliver Hottest Trends
Justice • Justice Sales Growth – Deliver Hottest Trends 31
Slide 32: Store Remodels and Openings
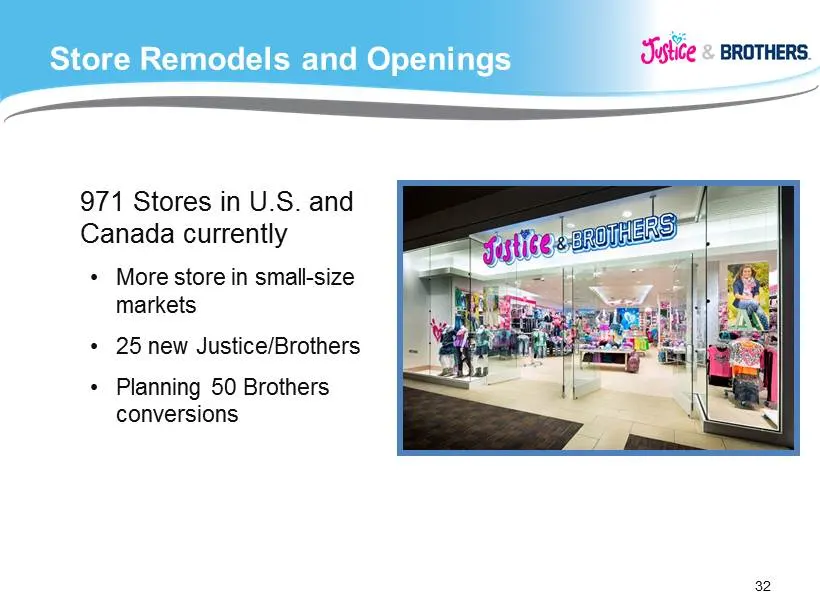
Store Remodels and Openings 971 Stores in U.S. and Canada currently • More store in small - size markets • 25 new Justice/Brothers • Planning 50 Brothers conversions 32
Slide 33: Justice: Evolve Compelling Value Message
Justice • Justice Sales Growth – Deliver Hottest Trends – New U.S. and Canadian Stores – Evolve Compelling Value Message 33
Slide 34: Compelling Value
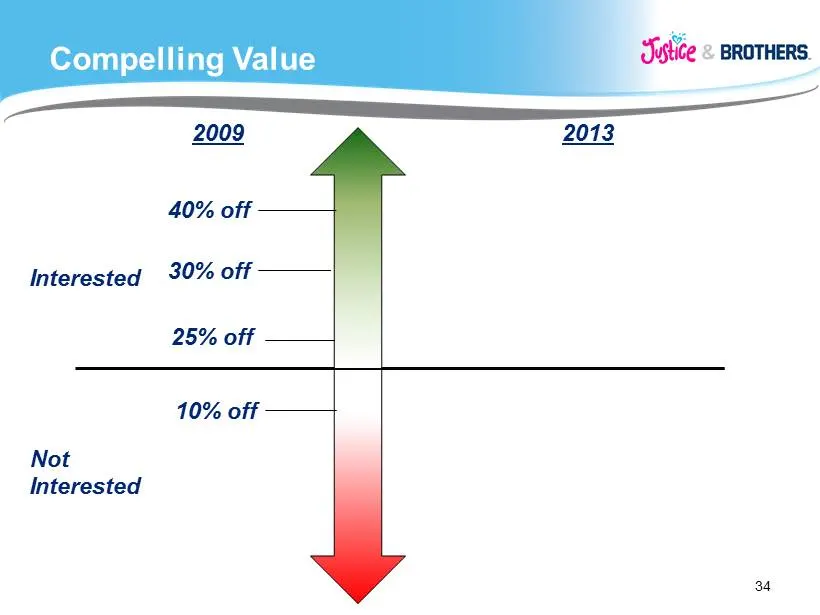
Compelling Value 34 Interested Not Interested 2013 2009 10% off 25% off 30% off 40% off
Slide 35: Compelling Value
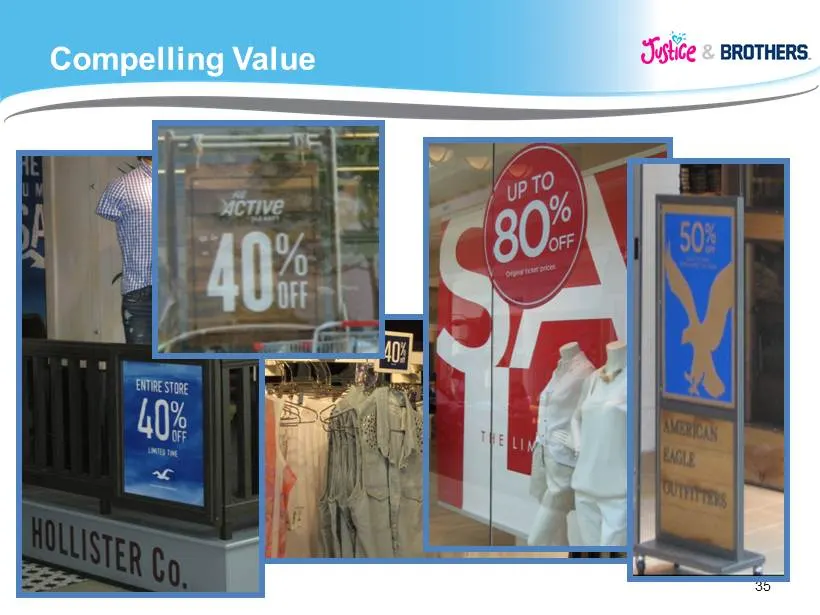
Compelling Value 35
Slide 36: Compelling Value
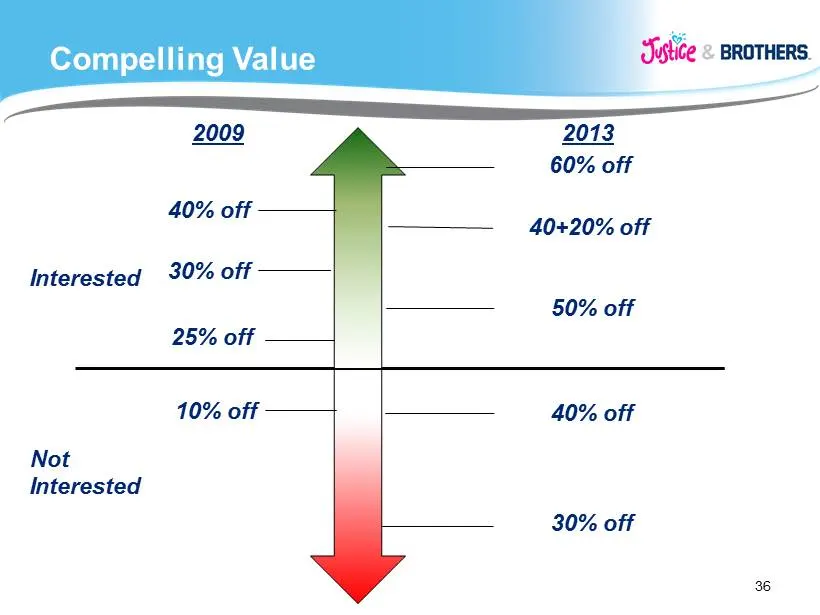
Compelling Value 36 Interested Not Interested 2013 60% off 50% off 40% off 30% off 2009 10% off 25% off 30% off 40% off 40+20% off
Slide 37: Compelling Value
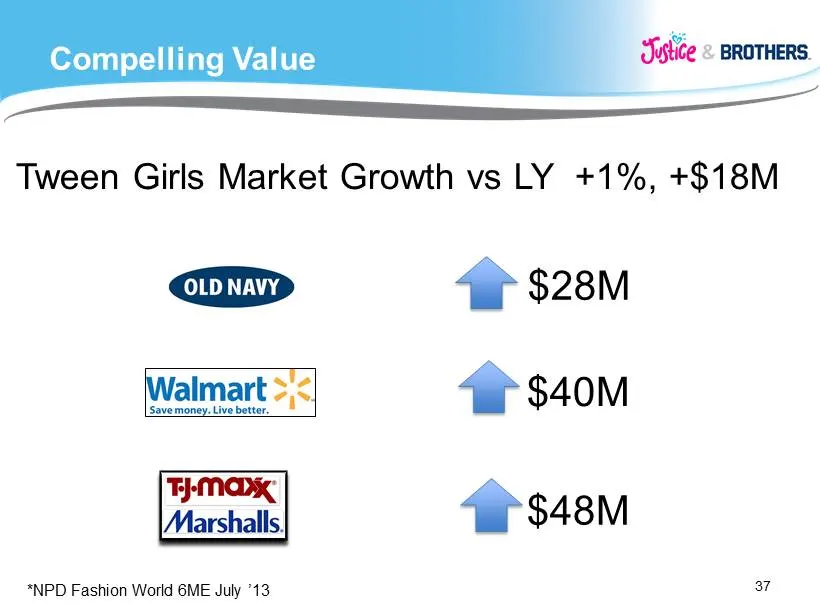
Compelling Value 37 $40M $28M $48M Tween Girls Market Growth vs LY +1%, +$18M *NPD Fashion World 6ME July ’13
Slide 38: Evolution: Test and Learn
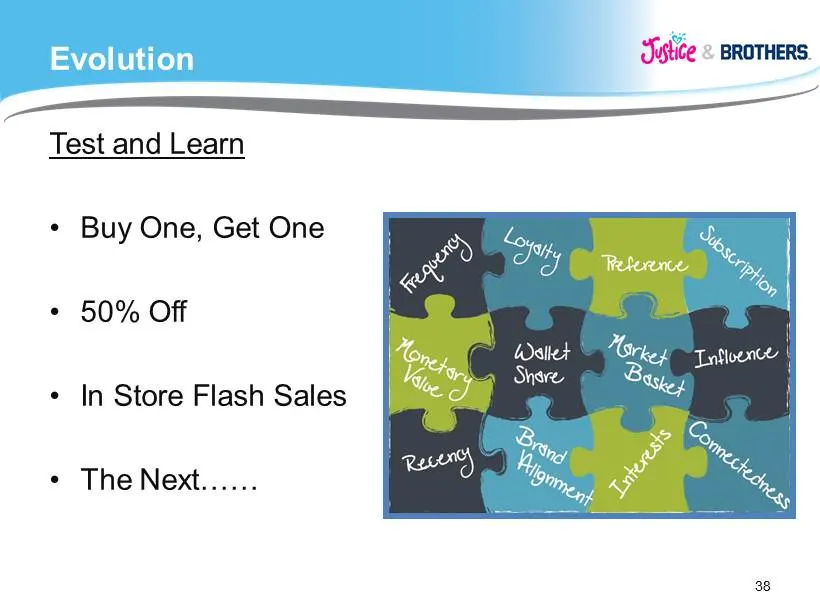
Evolution Test and Learn • Buy One, Get One • 50% Off • In Store Flash Sales • The Next…… 38
Slide 39: Opportunities: McDonald's Commercial
Opportunities 39 McDonald’s Commercial
Slide 40: Opportunities
Opportunities Sislce © BROTHERS.
Slide 41: Justice continues to dominate the EST Brand Equities
Justice continues to dominate the EST Brand Equities Brand Equity 41 Aug ‘13 FiSite Survey of Tween Girl Category Buyers
Slide 42: Justice continues to dominate the EST Brand Equities
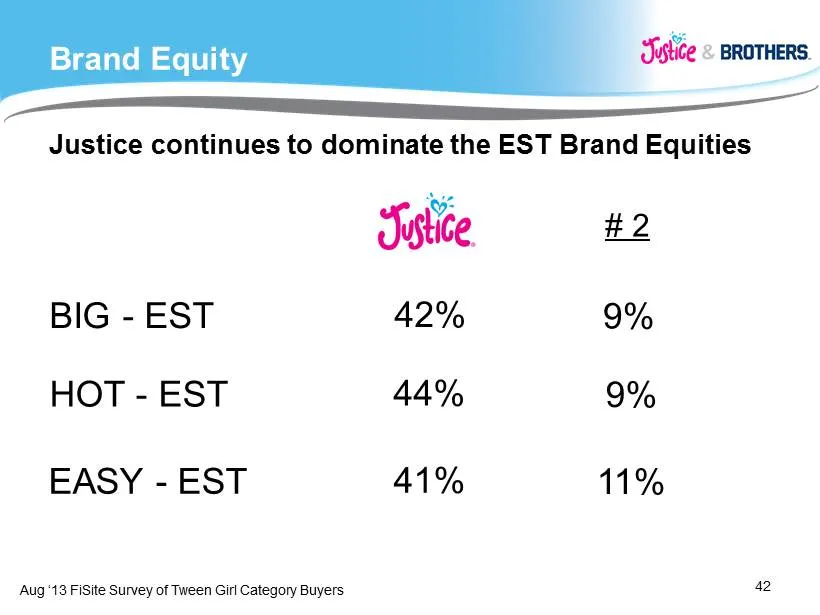
Justice continues to dominate the EST Brand Equities Brand Equity 42 Aug ‘13 FiSite Survey of Tween Girl Category Buyers # 2 BIG - EST HOT - EST EASY - EST 42% 9% 44% 9% 41% 11%
Slide 43: Brand Equity Still the Cool-EST
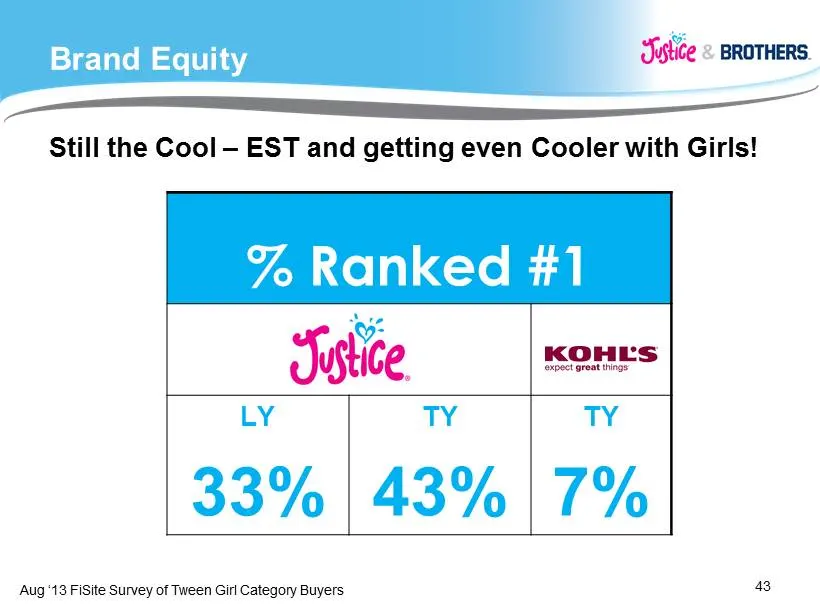
% Ranked #1 LY 33% TY 43% TY 7% Brand Equity 43 Still the Cool – EST and getting even Cooler with Girls! Aug ‘13 FiSite Survey of Tween Girl Category Buyers
Slide 44: Justice Letter
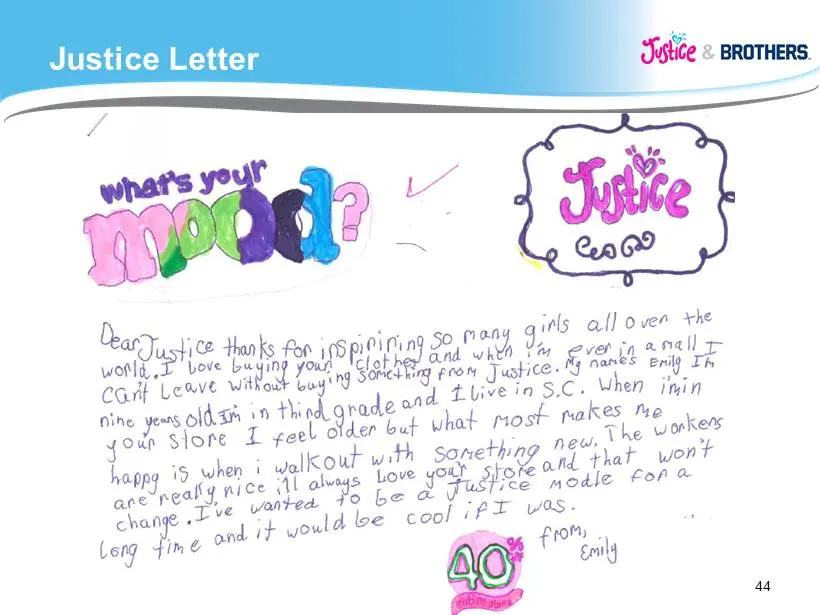
Justice Letter whats gitls all oven he a Sst Hie Hanks For ic6 pein) 5 DEY day woven (4 anal on love buy ing y' nt Tustice- Ay panes Pail Cart Lewe wit ay boy ria litres Taso when jinin ; rade fine yesoldish pitas den but hot post wa 8 eke gene : twth ees nee won't io ‘aly nice ee
Slide 45: Linda I. Heasley, President & CEO
Linda I. Heasley President & CEO
Slide 46: Executives Present
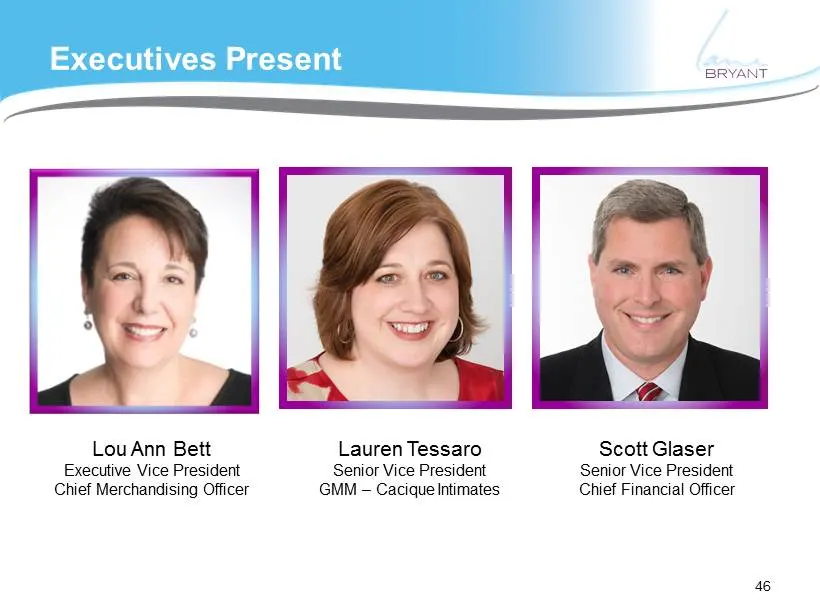
Executives Present Scott Glaser Senior Vice President Chief Financial Officer Lou Ann Bett Executive Vice President Chief Merchandising Officer Lauren Tessaro Senior Vice President GMM – Cacique Intimates 46
Slide 47: Our Vision
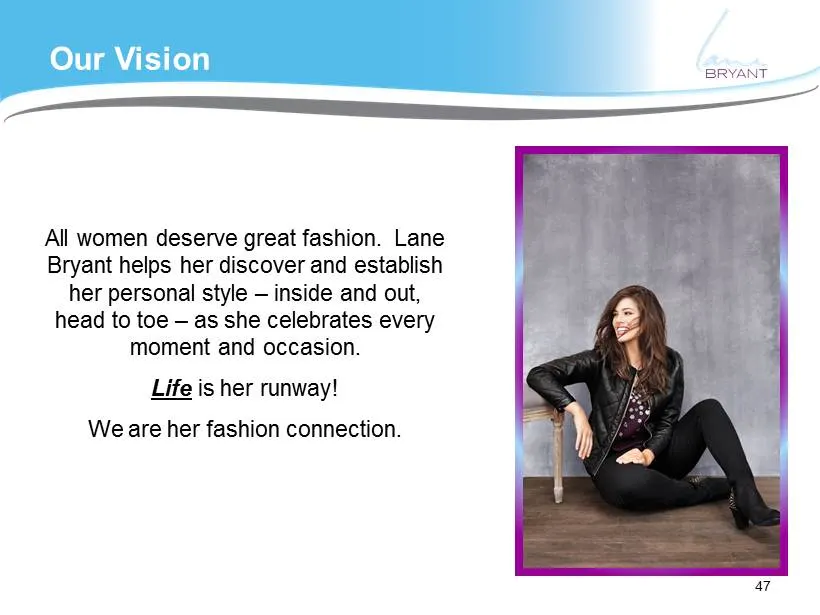
Our Vision 47 All women deserve great fashion. Lane Bryant helps her discover and establish her personal style – inside and out, head to toe – as she celebrates every moment and occasion. Life is her runway! We are her fashion connection.
Slide 48: Initial Observations
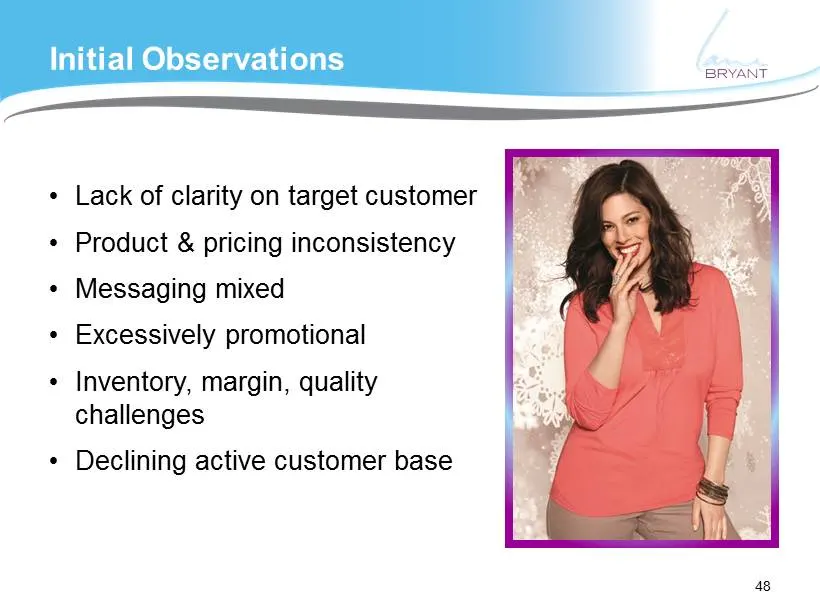
Initial Observations • Lack of clarity on target customer • Product & pricing inconsistency • Messaging mixed • Excessively promotional • Inventory, margin, quality challenges • Declining active customer base 48
Slide 49: Actions Taken
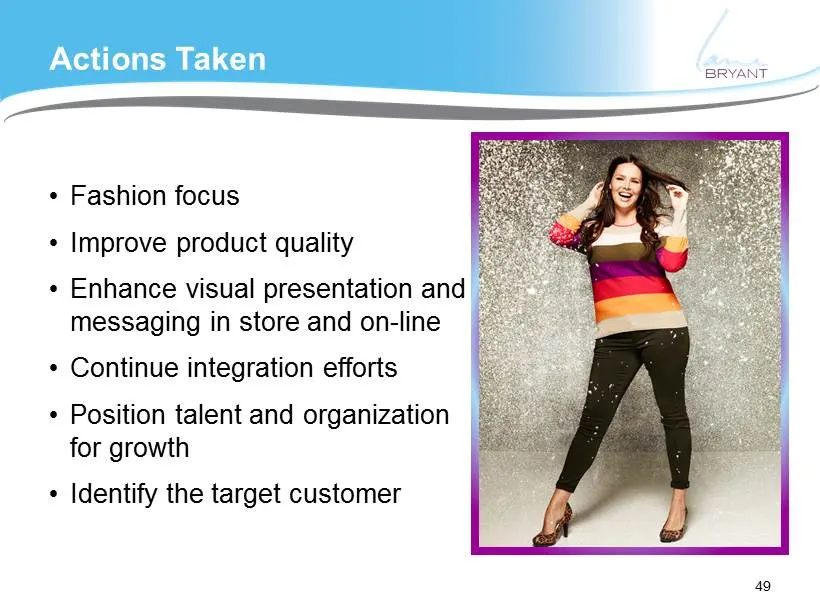
Actions Taken • Fashion focus • Improve product quality • Enhance visual presentation and messaging in store and on - line • Continue integration efforts • Position talent and organization for growth • Identify the target customer 49
Slide 50: Our Customer - Who She Was
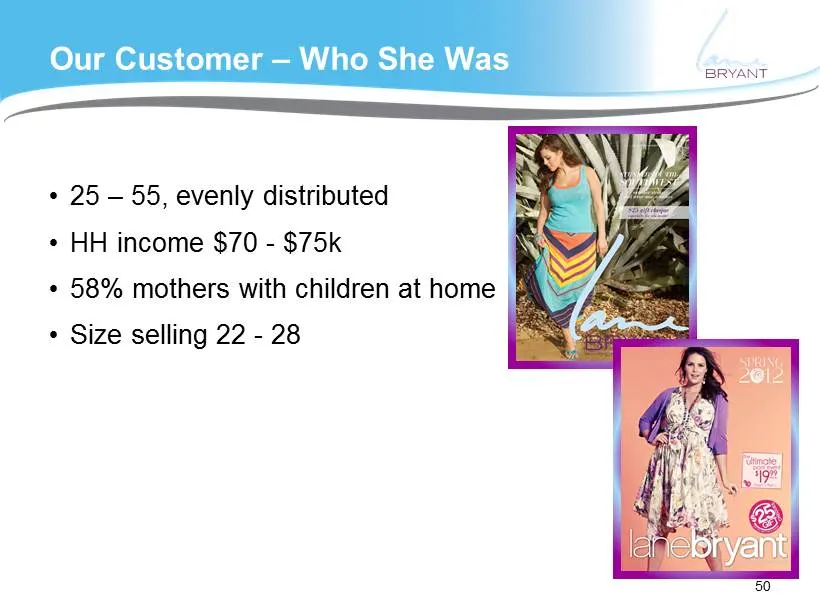
Our Customer – Who She Was • 25 – 55, evenly distributed • HH income $70 - $75k • 58% mothers with children at home • Size selling 22 - 28 50
Slide 51: Our Customer - Today
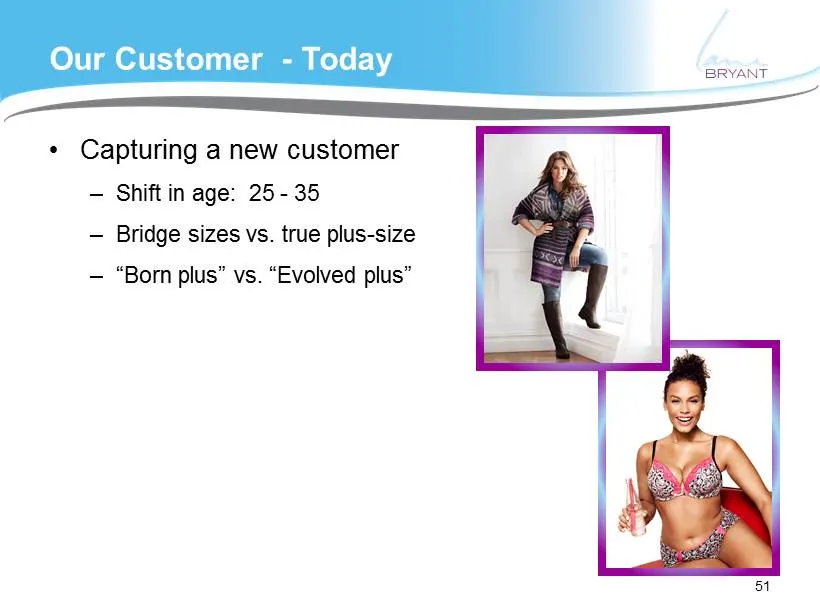
Our Customer - Today • Capturing a new customer – Shift in age: 25 - 35 – Bridge sizes vs. true plus - size – “Born plus” vs. “Evolved plus” 51
Slide 52: Competitive Market
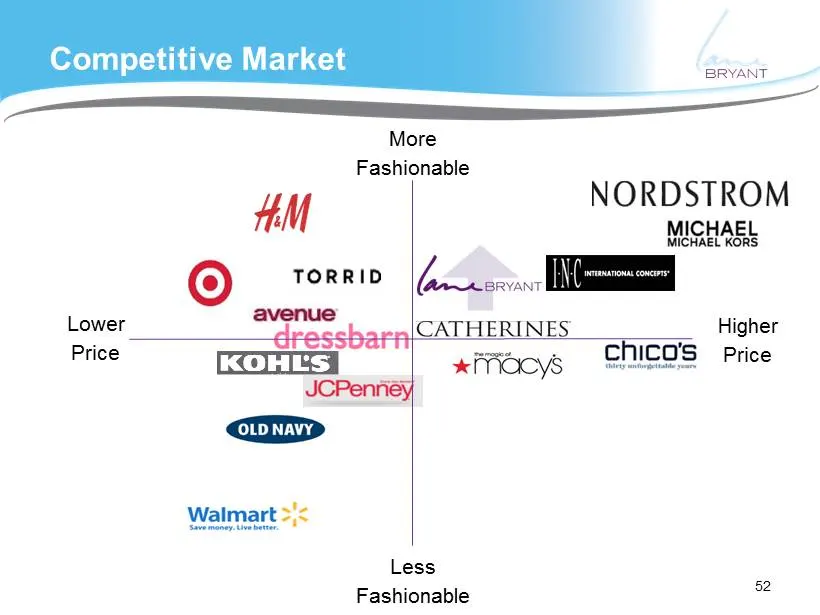
Lower Price Higher Price More Fashionable Less Fashionable Competitive Market 52
Slide 53: Brand Positioning
Brand Positioning • Lifestyle Driven Assortments • Fashion Relevance • Strategic Collaborations • Marketing Mix • Store Design 53
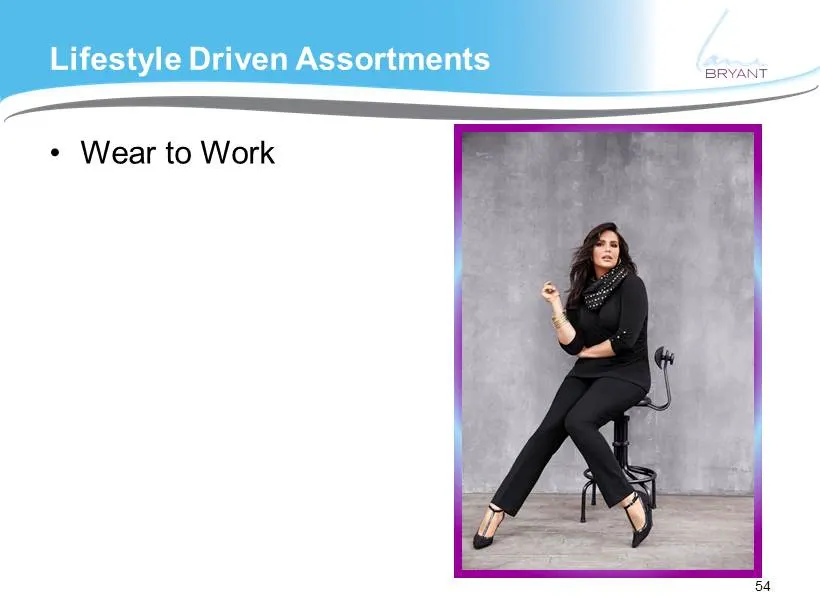
Slide 54: Lifestyle Driven Assortments: Wear to Work
Lifestyle Driven Assortments • Wear to Work 54
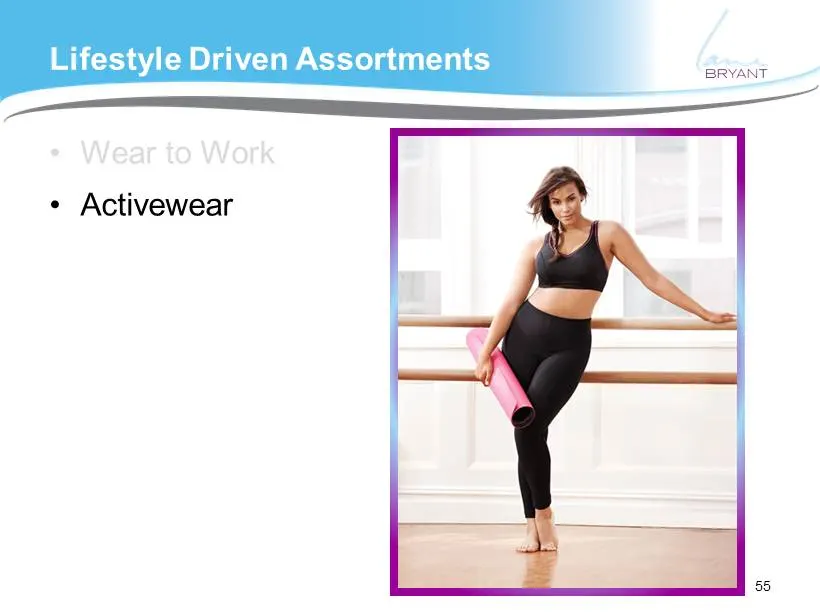
Slide 55: Lifestyle Driven Assortments: Activewear
Lifestyle Driven Assortments • Wear to Work • Activewear 55
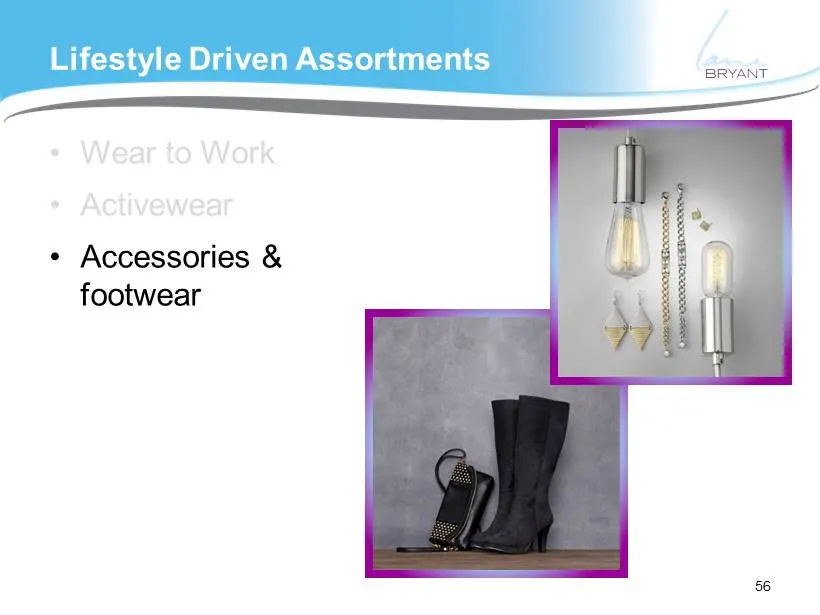
Slide 56: Lifestyle Driven Assortments: Accessories & Footwear
Lifestyle Driven Assortments • Wear to Work • Activewear • Accessories & footwear 56
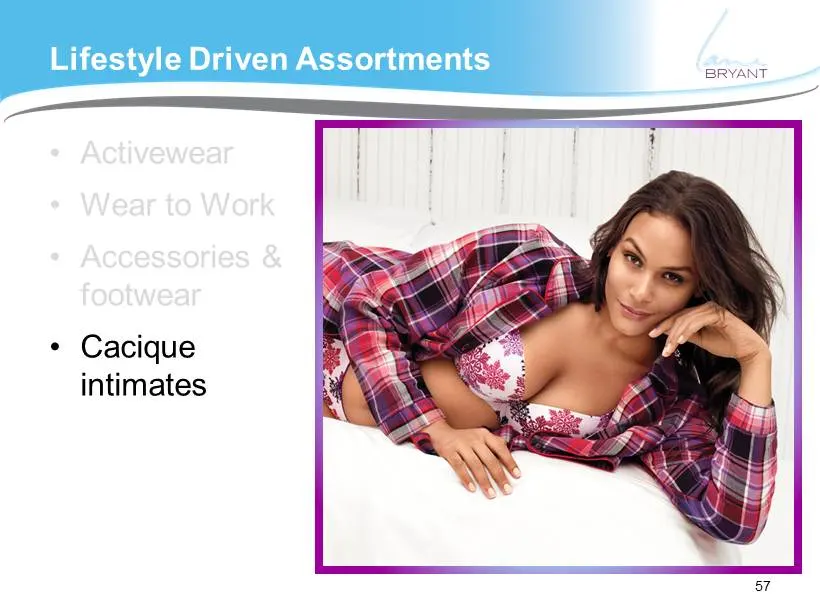
Slide 57: Lifestyle Driven Assortments: Cacique Intimates
Lifestyle Driven Assortments • Activewear • Wear to Work • Accessories & footwear • Cacique intimates 57
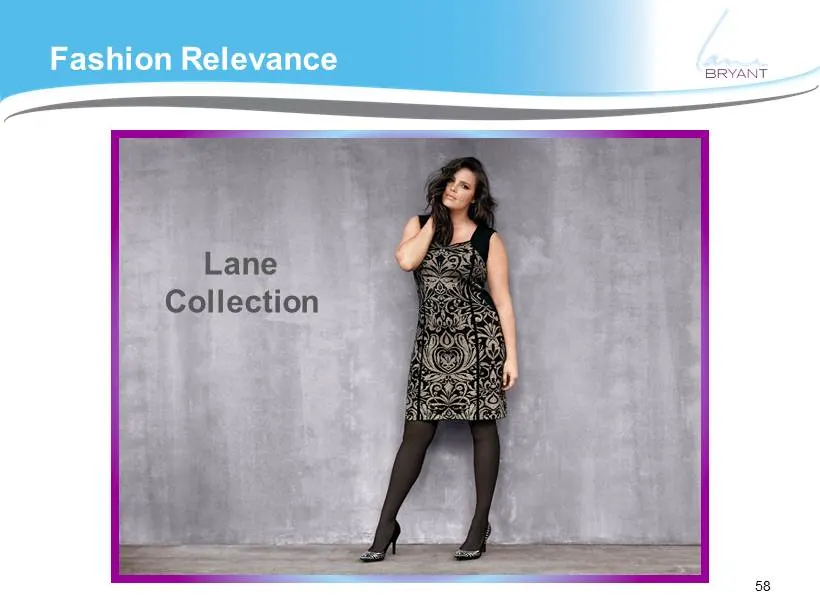
Slide 58: Fashion Relevance: Lane Collection
Fashion Relevance Lane Collection 58
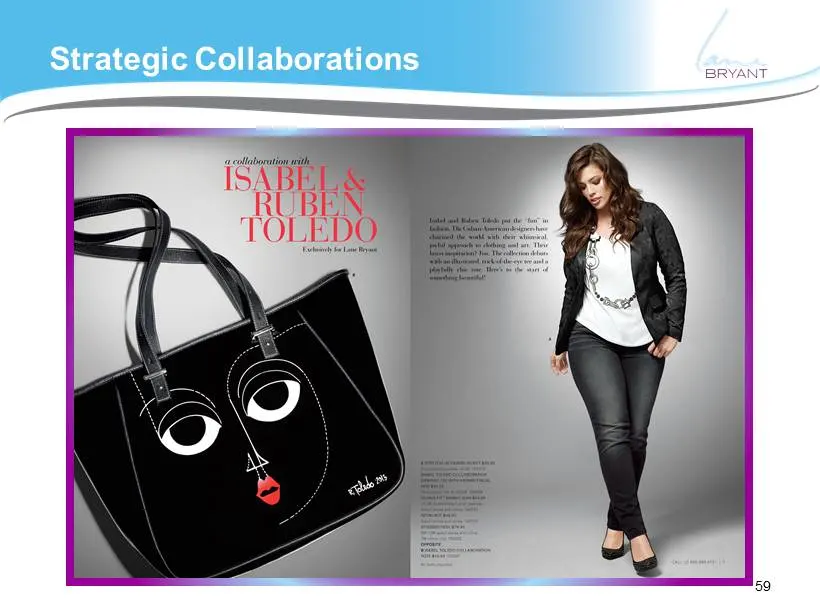
Slide 59: Strategic Collaborations
Strategic Collaborations 59
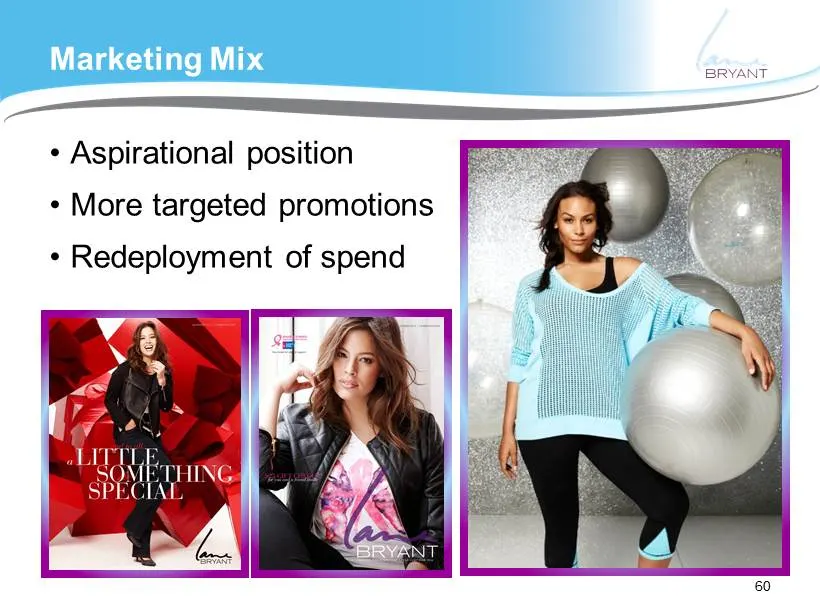
Slide 60: Marketing Mix
Marketing Mix • Aspirational position • More targeted promotions • Redeployment of spend 60
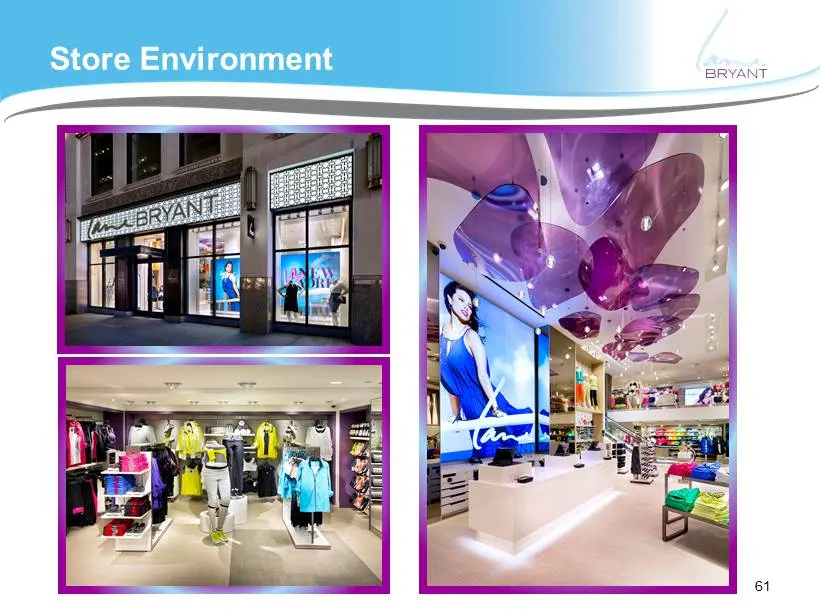
Slide 61: Store Environment
Store Environment 61
Slide 62: Evolving Business Model
Evolving Business Model 62 • Mid - single digit comps • Ecommerce growth • Expanding customer base and increasing share of wallet
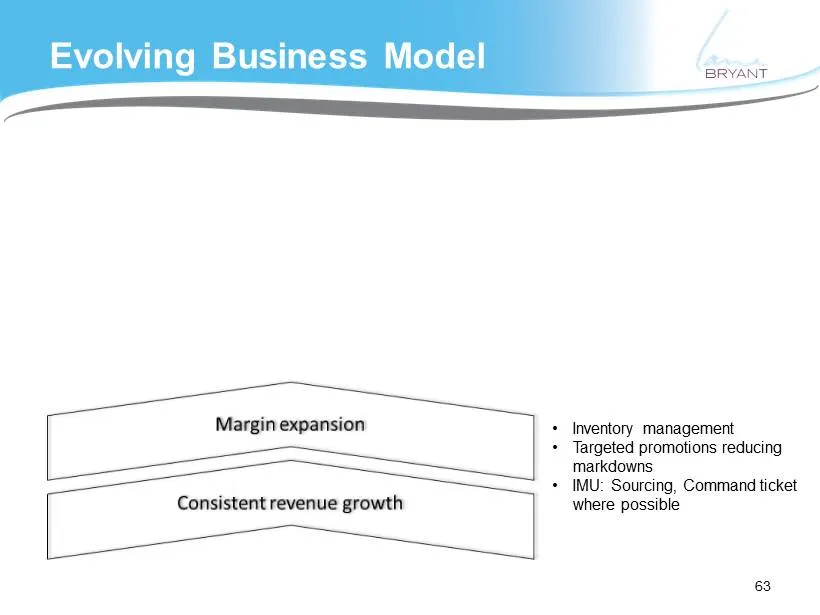
Slide 63: Evolving Business Model: Inventory Management
Evolving Business Model 63 • Inventory management • Targeted promotions reducing markdowns • IMU: Sourcing, Command ticket where possible
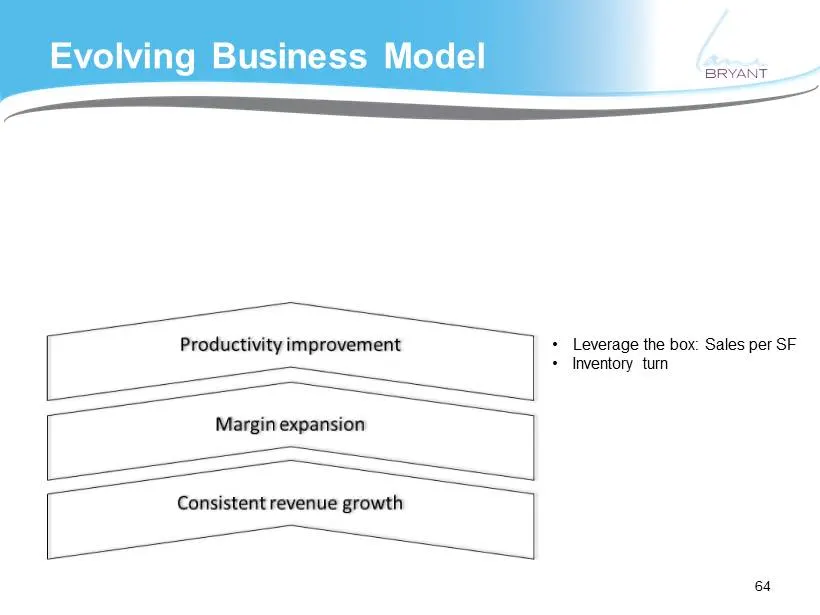
Slide 64: Evolving Business Model: Leverage the Box
Evolving Business Model 64 • Leverage the box: Sales per SF • Inventory turn
Slide 65: Evolving Business Model: Operating Expenses
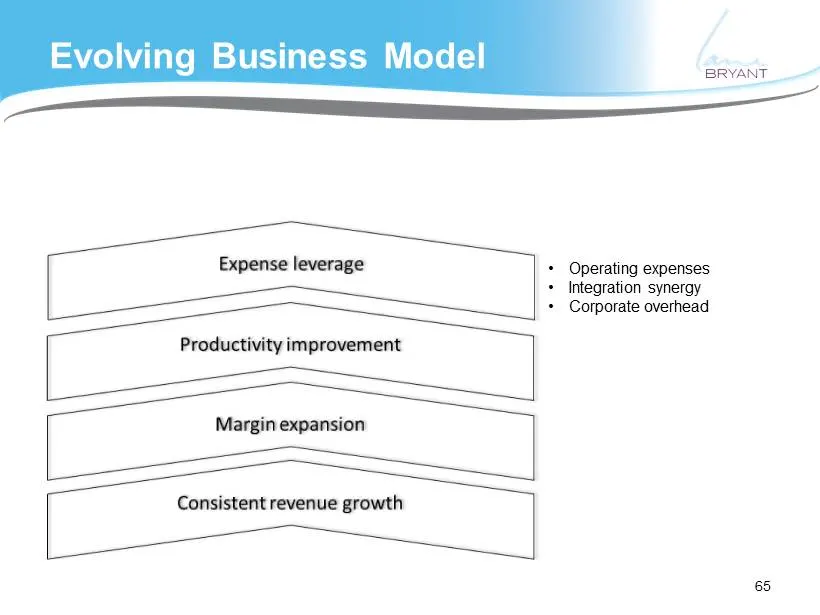
Evolving Business Model 65 • Operating expenses • Integration synergy • Corporate overhead
Slide 66: Evolving Business Model: Real Estate
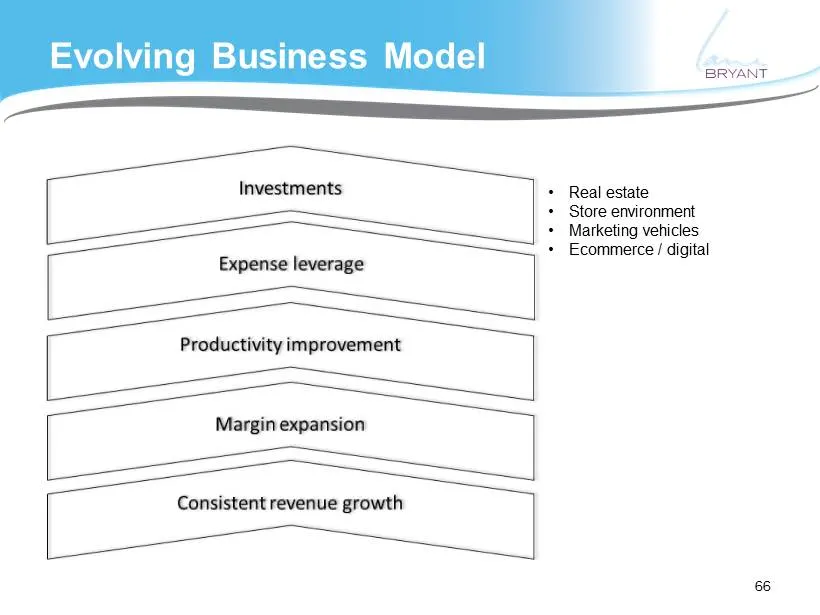
Evolving Business Model 66 • Real estate • Store environment • Marketing vehicles • Ecommerce / digital
Slide 67: Evolving Business Model
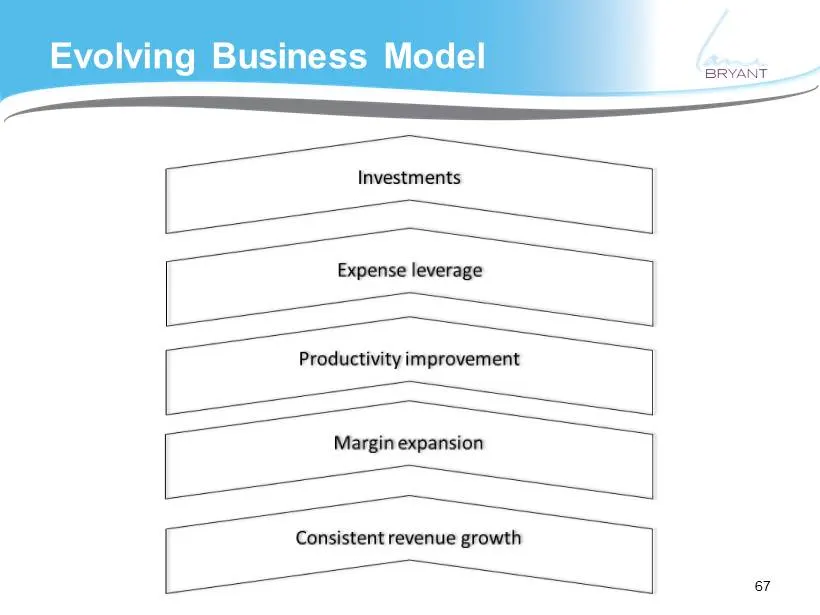
Evolving Business Model oot Le 67
Slide 68: Lane Bryant / Cacique
BRYANT BRYANT CACIQUE
Slide 69: George Goldfarb, President
George Goldfarb President oy OustiGe Aa. CATHERINES
Slide 70: Executives Present
Executives Present Erin Stern Executive Vice President Chief Merchandising Officer Brian Thun Senior Vice President Chief Financial Officer 70
Slide 71: Our Vision
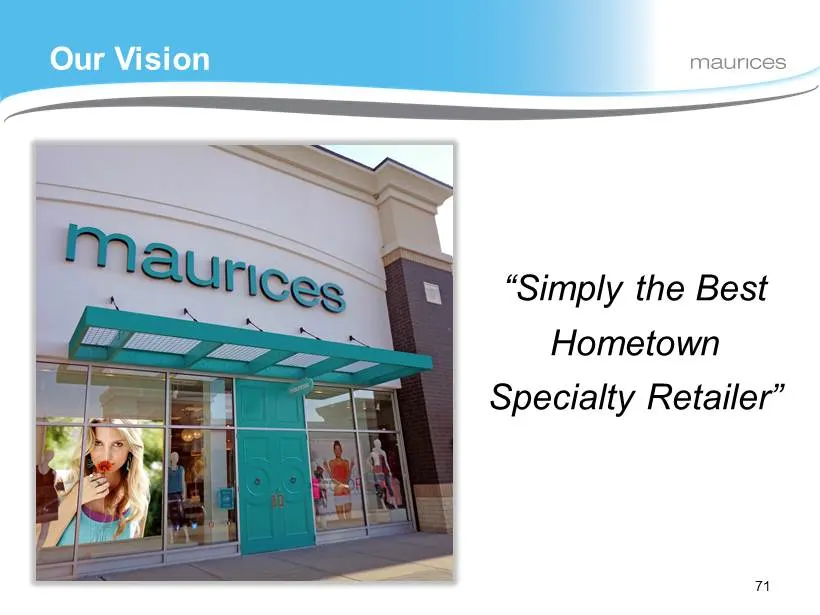
Our Vision “Simply the Best Hometown Specialty Retailer” 71
Slide 72: National Market Positioning
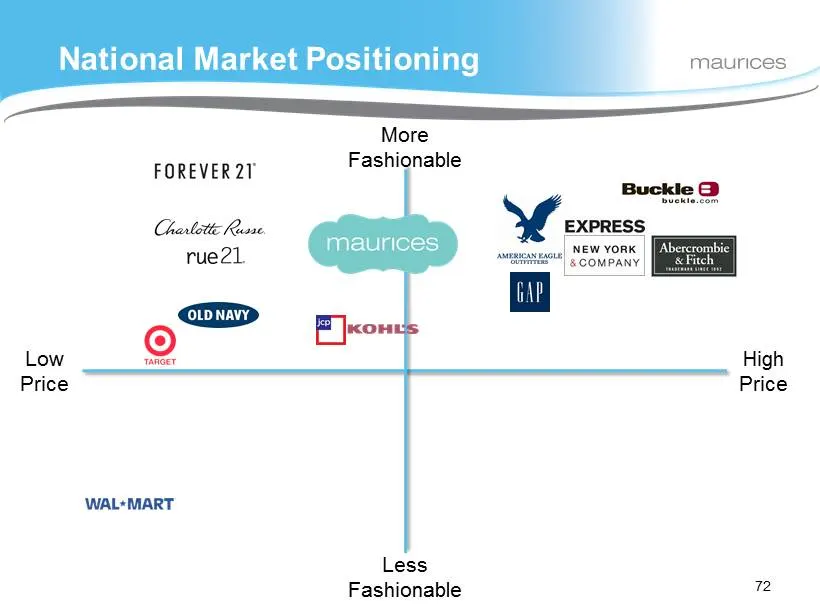
National Market Positioning More Fashionable Less Fashionable High Price Low Price 72
Slide 73: Small Market Positioning
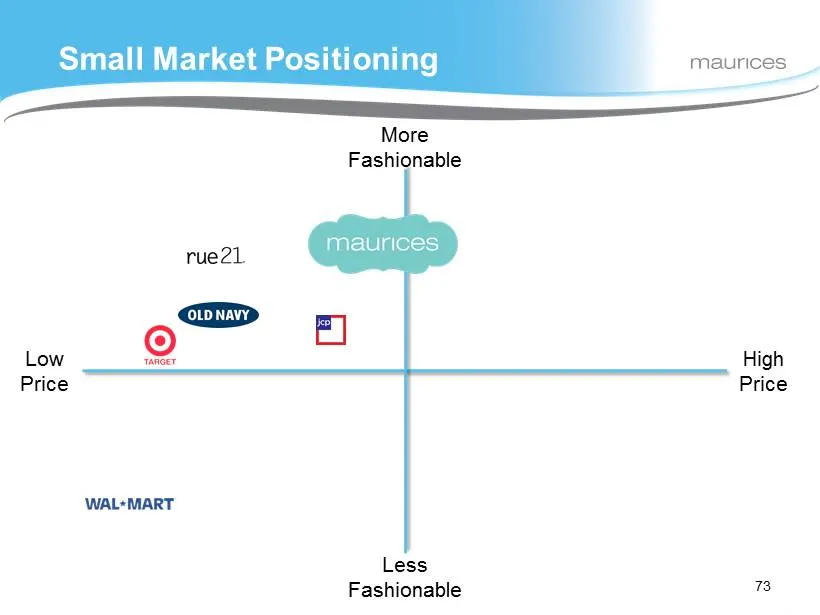
Small Market Positioning More Fashionable Less Fashionable High Price Low Price 73
Slide 74: Our Customer
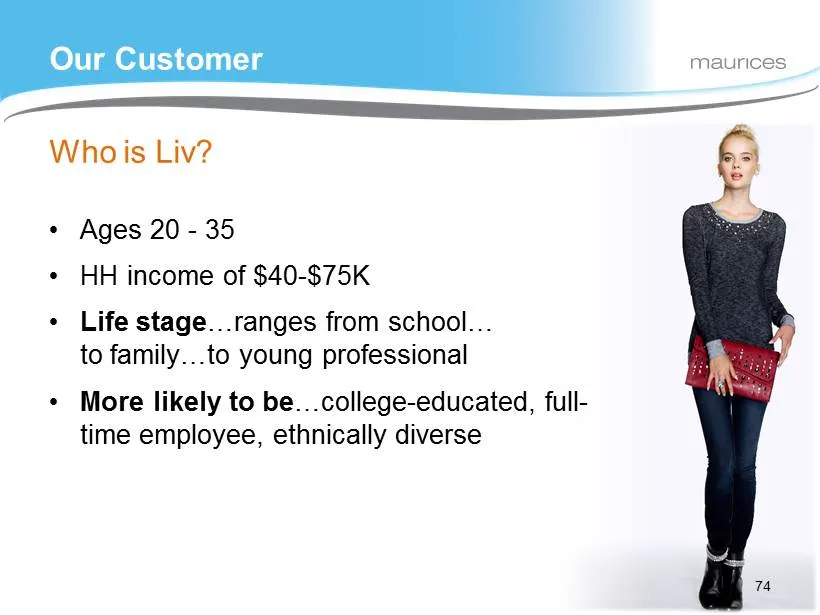
Our Customer Who is Liv? • Ages 20 - 35 • HH income of $40 - $75K • Life stage …ranges from school… to family…to young professional • More likely to be …college - educated, full - time employee, ethnically diverse 74
Slide 75: Strategic Initiatives
Strategic Initiatives • Merchandising transformation • Growing the top line profitably 75
Slide 76: Merchandising Transformation
Merchandising Transformation • Hybrid sourcing model • Develop design capability 76
Slide 77: Merchandising Transformation
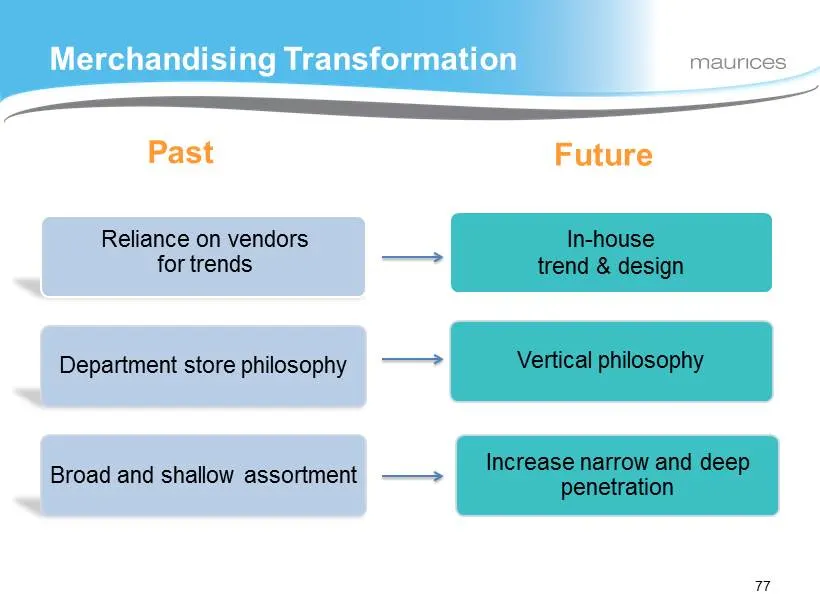
Merchandising Transformation Past Future Reliance on vendors for trends Department store philosophy Broad and shallow assortment In - house trend & design Vertical philosophy Increase narrow and deep penetration 77
Slide 78: Merchandising Transformation: Marketing Strategy
Merchandising Transformation Marketing Strategy • Aspirational story • Support key seasonal drivers • Strengthened analytics • Omni - Channel 78
Slide 79: Growing the Top Line Profitably
Growing the Top Line Profitably • New store expansion • New décor rollout • Ecommerce growth • Expansion categories 79
Slide 80: New Store Expansion
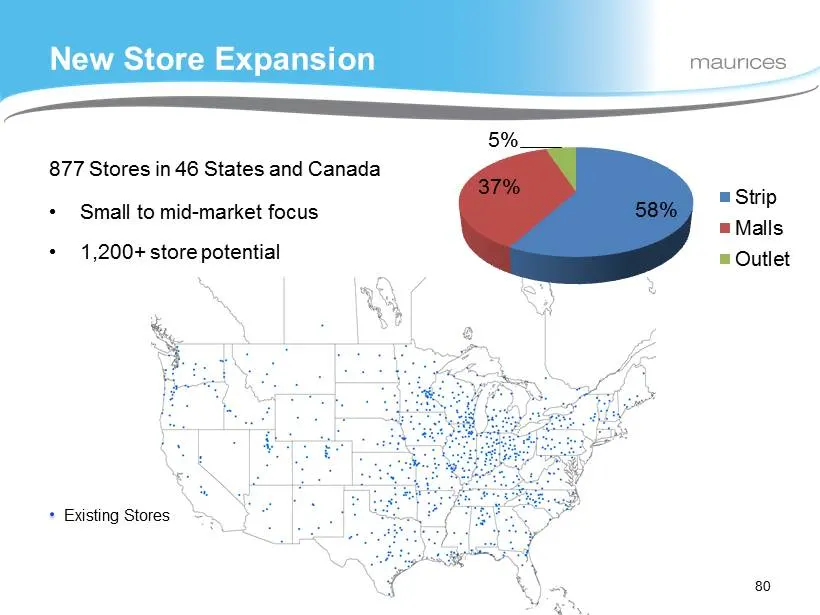
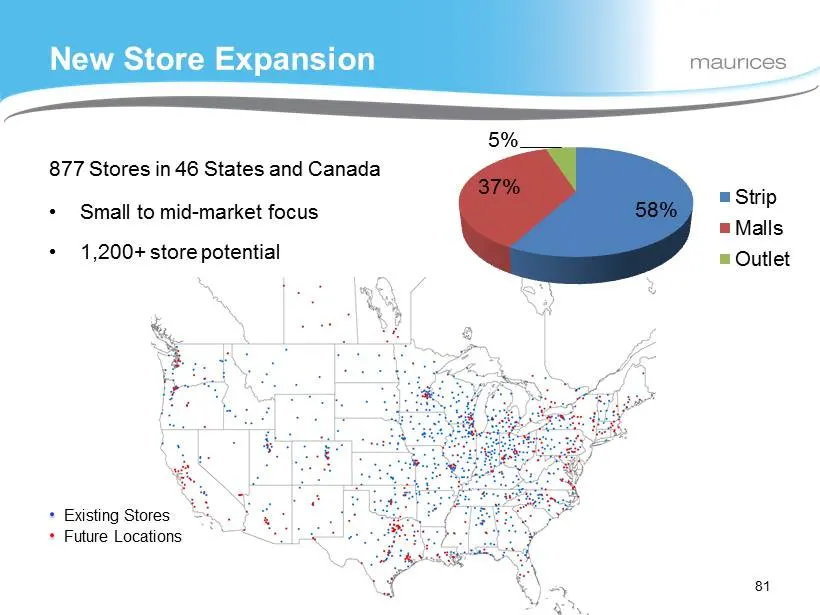
New Store Expansion 877 Stores in 46 States and Canada • Small to mid - market focus • 1,200+ store potential Existing Stores 58% 37% 5% Strip Malls Outlet 80
Slide 81: New Store Expansion
New Store Expansion 81 Existing Stores Future Locations 877 Stores in 46 States and Canada • Small to mid - market focus • 1,200+ store potential 58% 37% 5% Strip Malls Outlet
Slide 82: New Décor Rollout
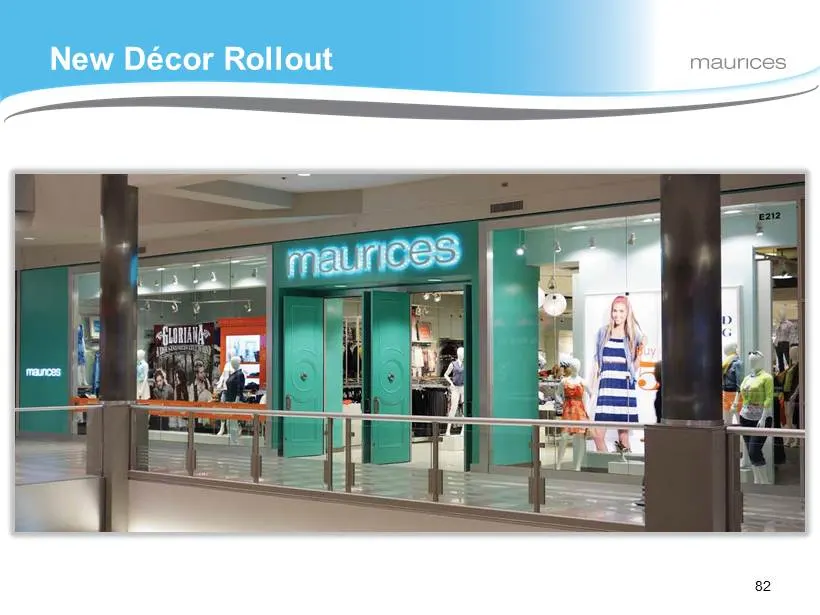
New Décor Rollout co)
Slide 83: New Décor Rollout
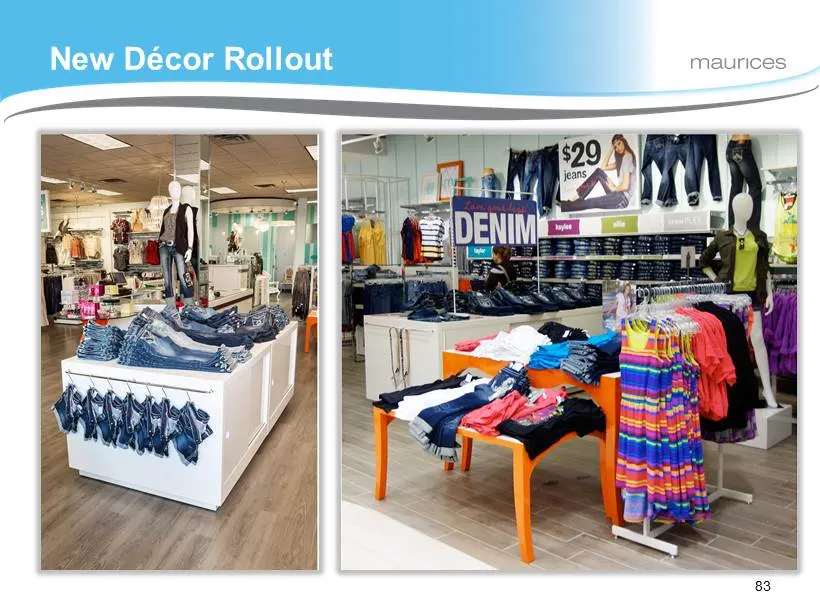
New Décor Rollout 83
Slide 84: New Décor Rollout
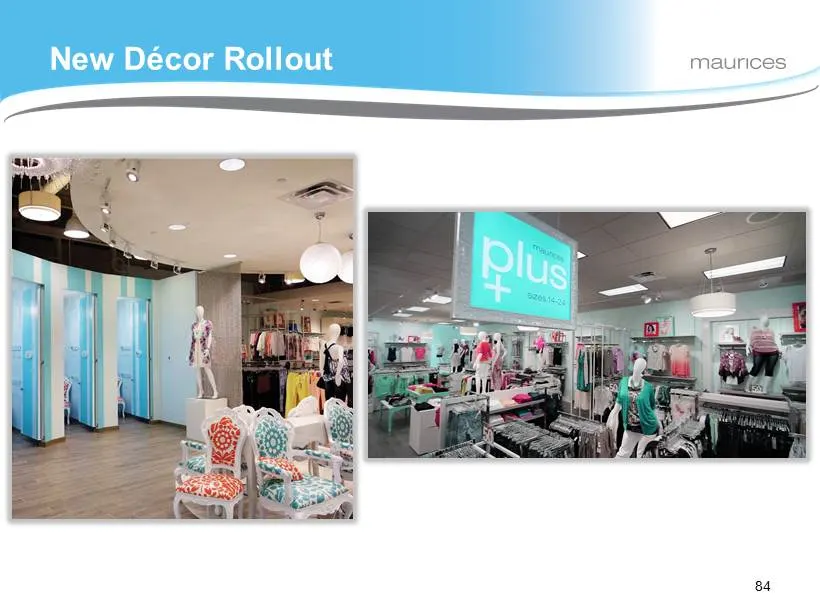
New Décor Rollout 84
Slide 85: Ecommerce Growth
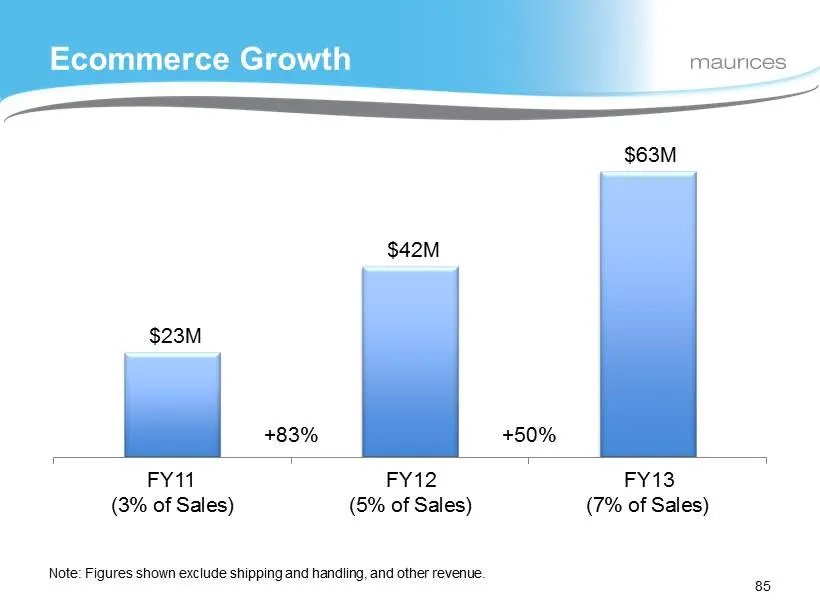
Ecommerce Growth 85 $23M $ 42M $ 63M 2011 (3% of Sales) 2012 (5% of Sales) 2013 (7% of Sales) +83% +50% Note: Figures shown exclude shipping and handling, and other revenue. FY11 FY12 FY13
Slide 86: Expansion Categories
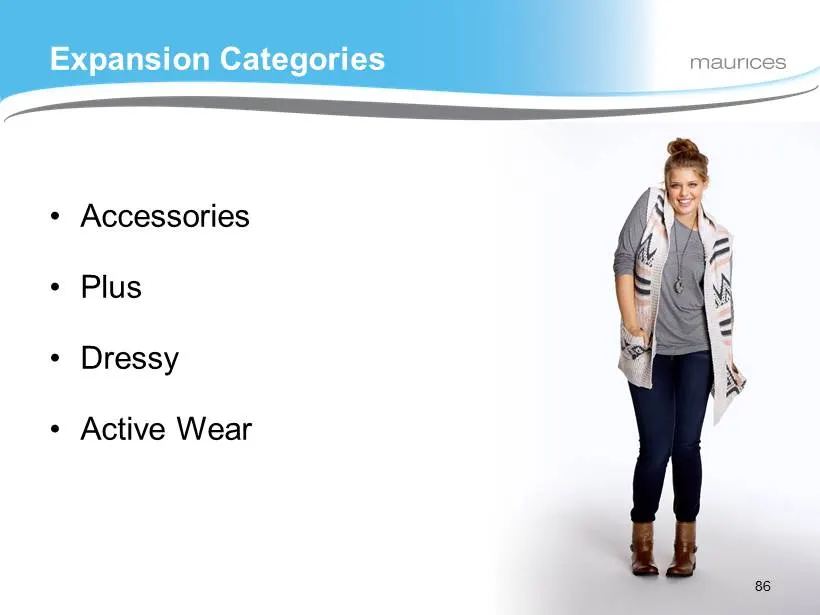
Expansion Categories • Accessories • Plus • Dressy • Active Wear 86
Slide 87: Simply the Best Hometown Specialty Retailer
“Simply the Best Hometown Specialty Retailer” 87
Slide 88: Jeff Gerstel, President
Jeff Gerstel President oy: custice BRYANT CATHERINES
Slide 89: Executives Present
Executives Present 89 Lori Wagner Executive Vice President Ecommerce Chief Marketing Officer John Pershing Executive Vice President Human Resources Raana Zia Senior Vice President Chief Financial Officer
Slide 90: Purpose: Inspiring Women to Look & Feel Beautiful
Purpose Inspiring Women to Look & Feel Beautiful 90
Slide 91: Inspiring women to look and feel beautiful
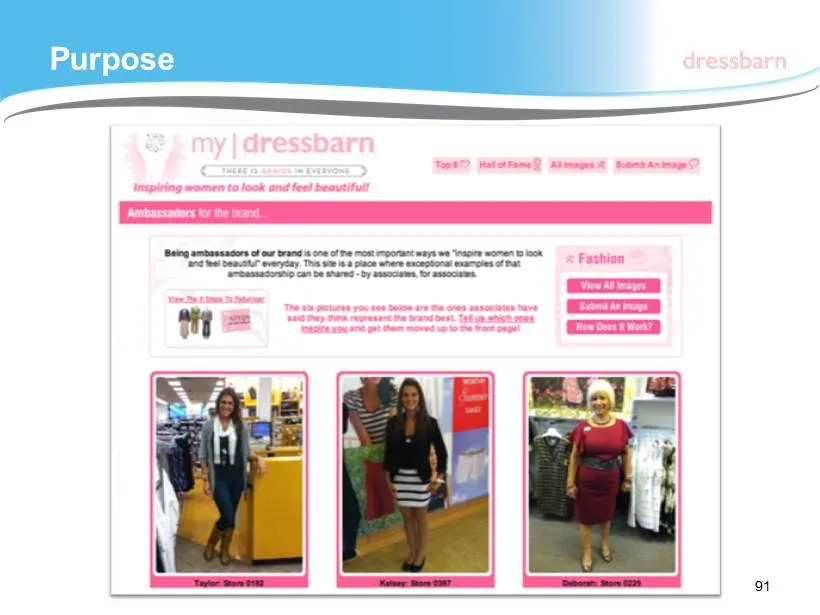
Tap8 HatetFame® Atmagee ® Sete An image © Inspiring women to look ond feel beoutiful! (eng ambassadors of cu brand sone of te Mout nooraet maya we Yosory women Bot "rien beasts” veryany Ths tn na pace amare excapnora! exries fat Fashion PERI a SR cae acne ethan neue Tne su pictures you ee betow are
Slide 92: Reinvigorating a Brand
Reinvigorating a Brand • Talent • Brand • Product • Growth • Culture 92
Slide 93: Talent
Talent • People who believe what we believe • Blend t enure / new blood • Vision and d rive 93
Slide 94: Brand
Brand • Clarify our customer • Position ourselves competitively 94
Slide 95: Clarify our Customer: Segmentation
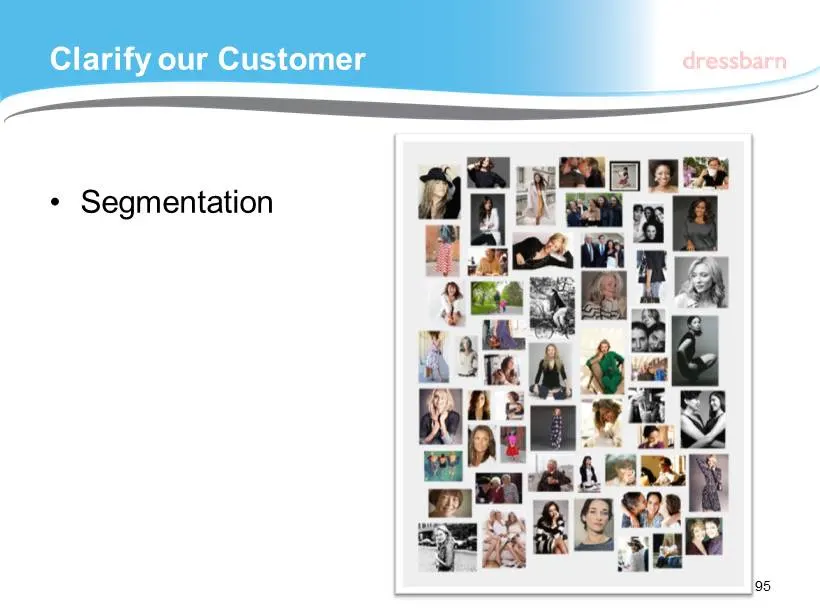
Clarify our Customer • Segmentation 95
Slide 96: Clarify our Customer
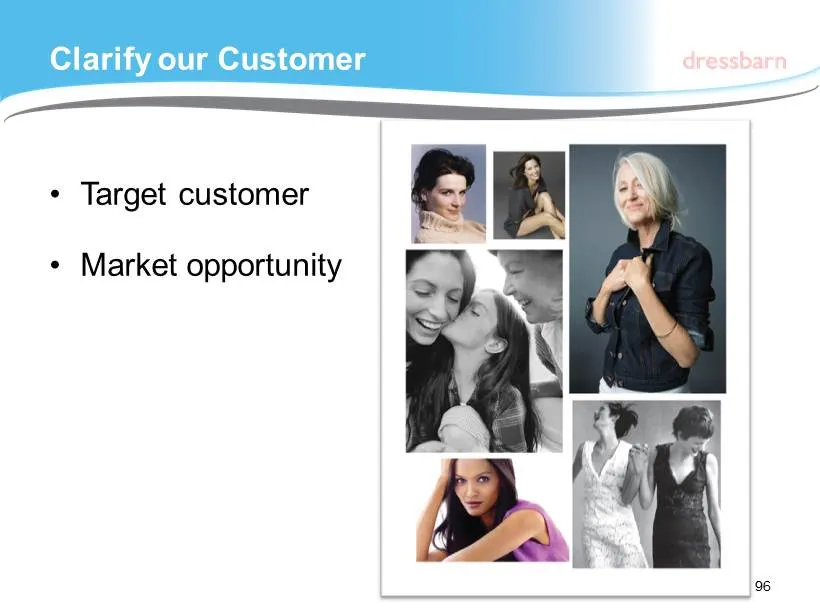
Clarify our Customer • Target customer • Market opportunity 96
Slide 97: Position Ourselves
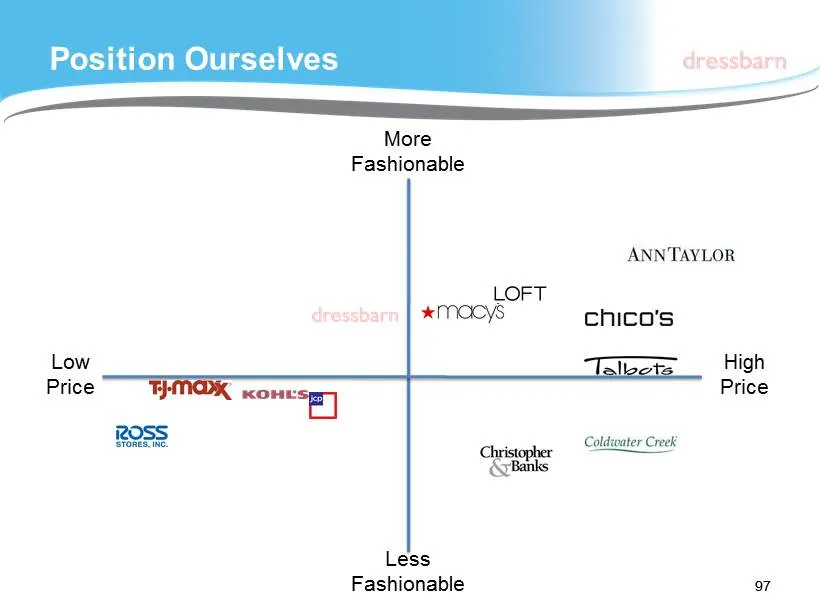
Position Ourselves 97 More Fashionable Less Fashionable High Price Low Price 97
Slide 98: Product
Product • Brand right merchandise • Hybrid model • Inventory management • Telling our story 98
Slide 99: Product: Brand Right Merchandise
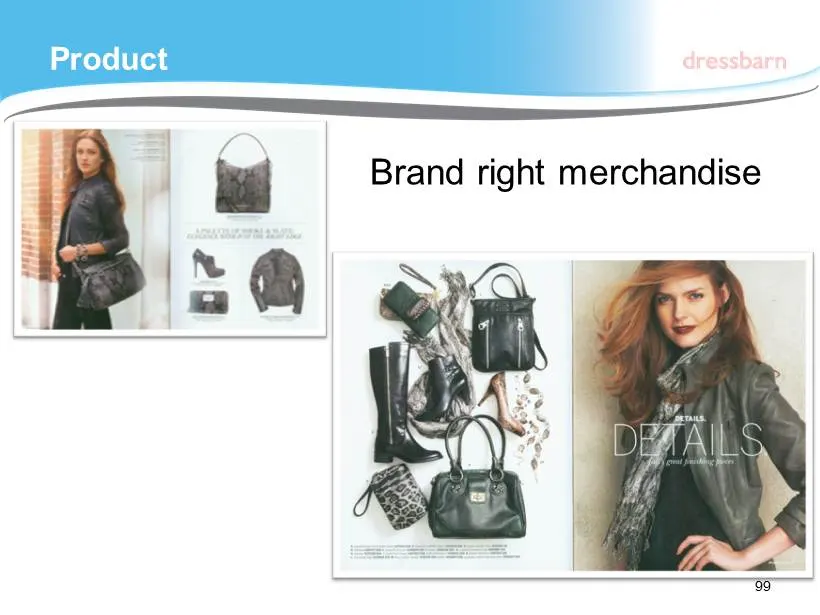
Product 99 Brand right merchandise
Slide 100: Hybrid Model
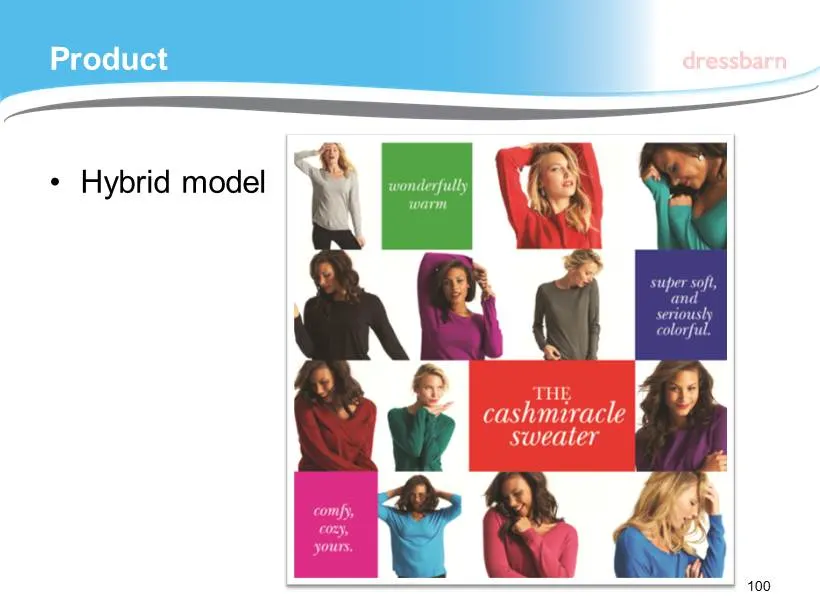
* Hybrid model“ THE cashmiracle sweater 400
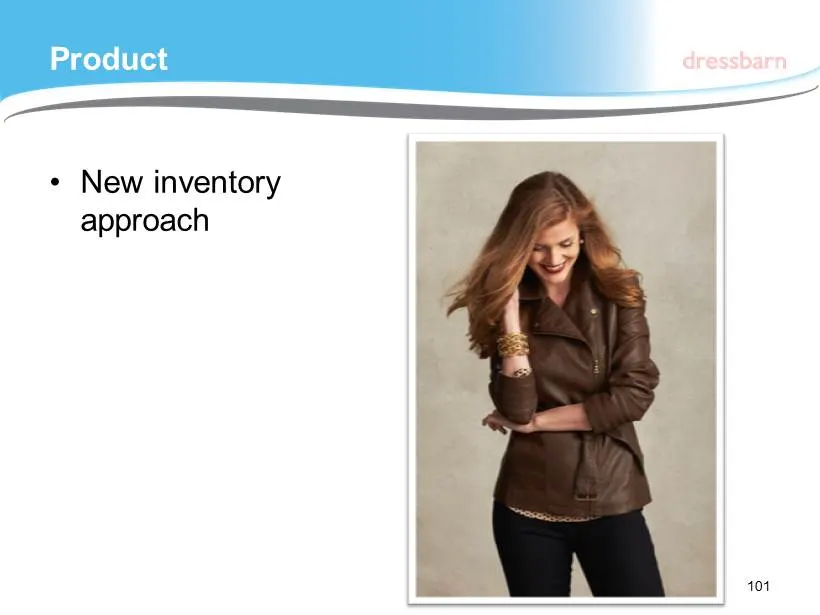
Slide 101: New Inventory Approach
• New inventory approach Product 101
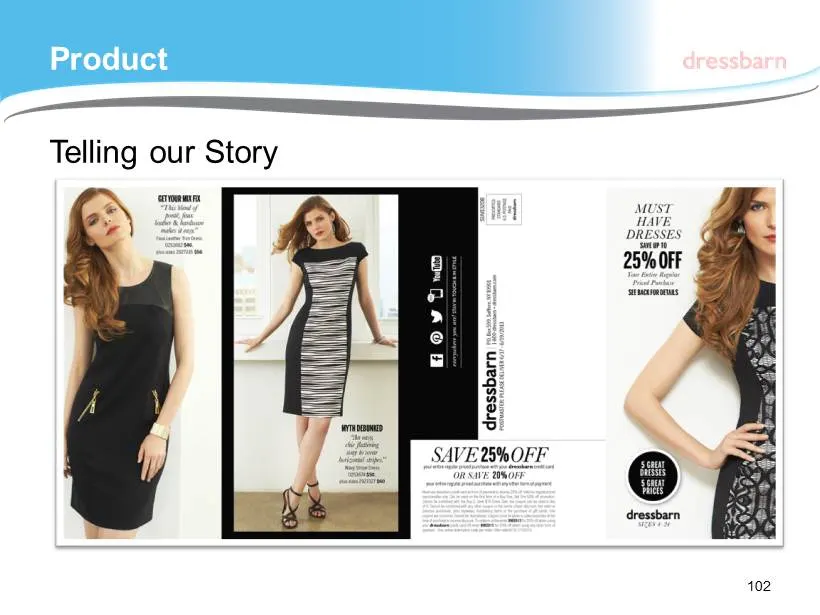
Slide 102: Product: Telling our Story
Product Telling our Story 102
Slide 103: Growth
Growth • Brand / Product • Real estate • Store productivity • Ecommerce 103
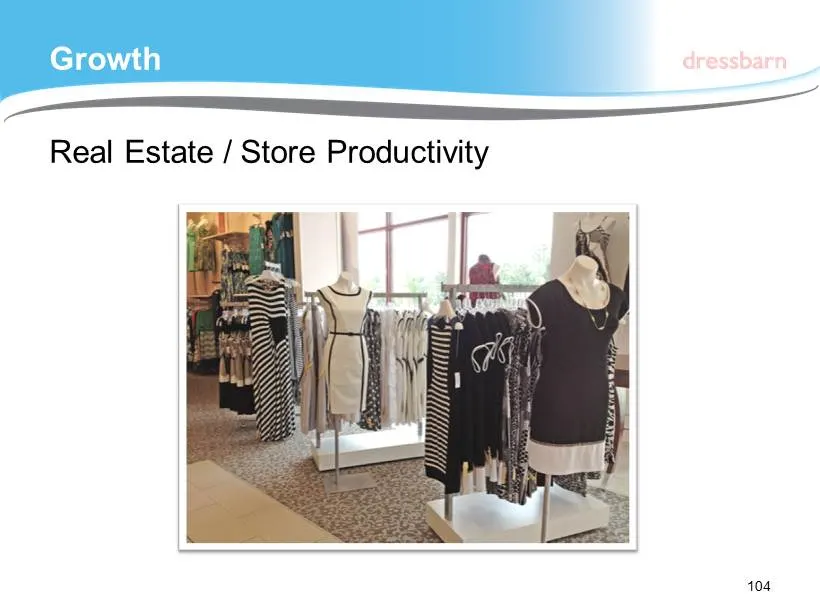
Slide 104: Growth: Real Estate / Store Productivity
Growth Real Estate / Store Productivity 104
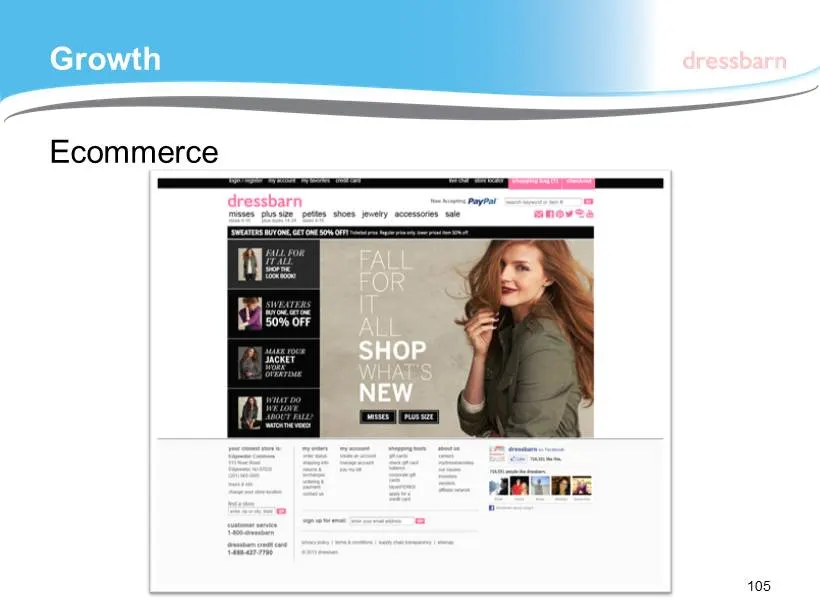
Slide 105: Growth: Ecommerce
Growth Ecommerce 105
Slide 106: Inspiring women to look & feel beautiful
Inspiring women to look & feel beautiful
Slide 107: Eric Specter, Acting President
Eric Specter Acting President
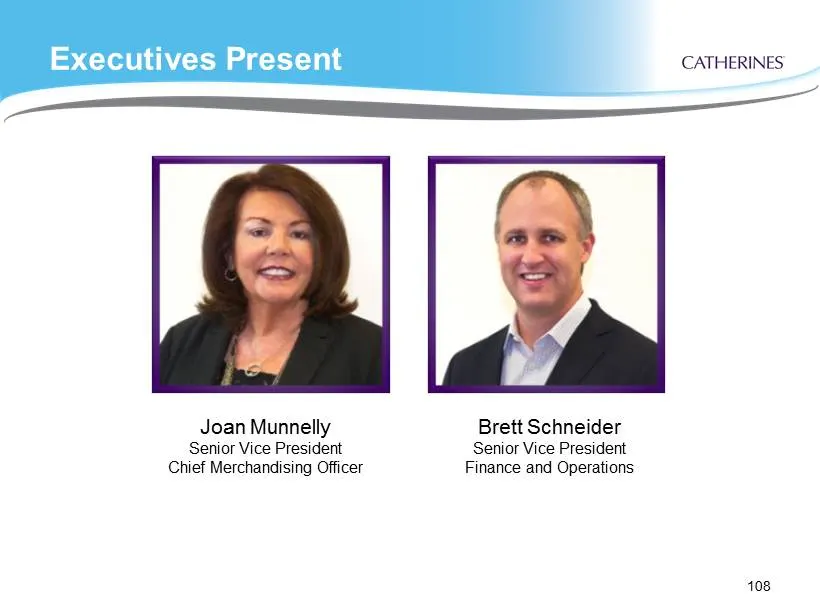
Slide 108: Executives Present
Executives Present 108 Joan Munnelly Senior Vice President Chief Merchandising Officer Brett Schneider Senior Vice President Finance and Operations
Slide 109: Our Mission
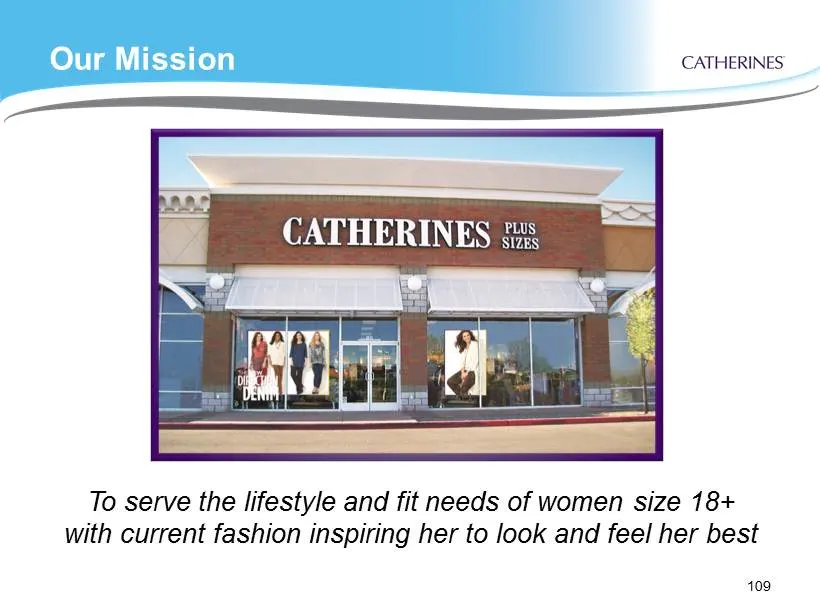
Our Mission 109 To serve the lifestyle and fit needs of women size 18+ with current fashion inspiring her to look and feel her best
Slide 110: Competitive Market
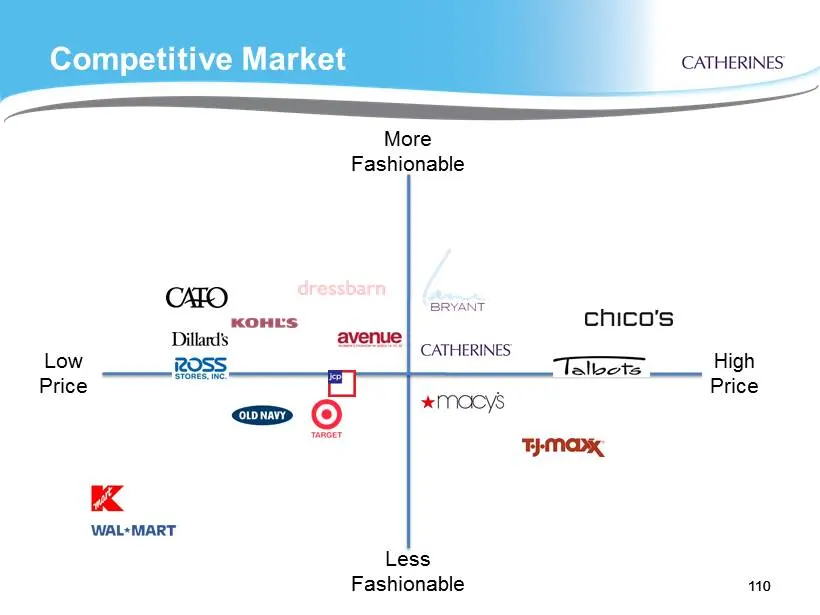
More Fashionable Less Fashionable High Price Low Price Competitive Market 110 110 110
Slide 111: Extended Size Competition
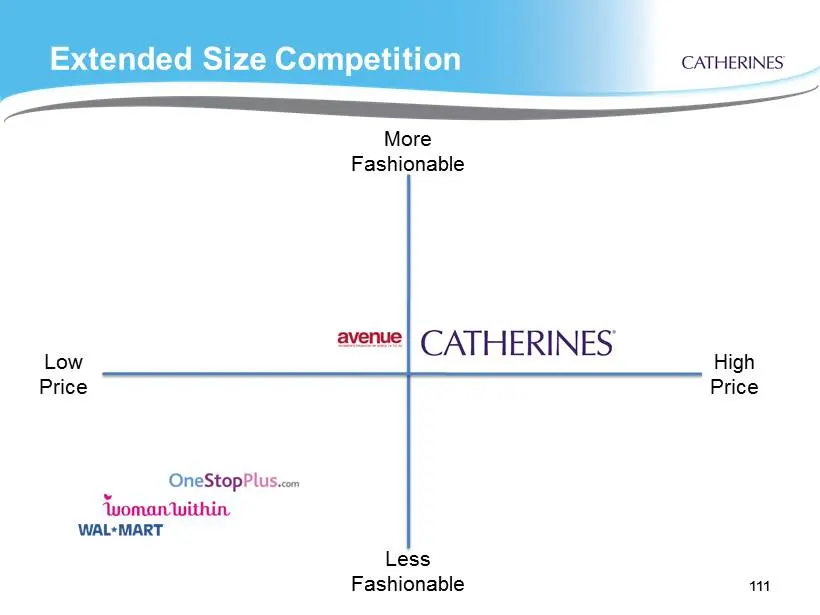
Extended Size Competition 111 111 111 More Fashionable Less Fashionable High Price Low Price
Slide 112: Sales by Size
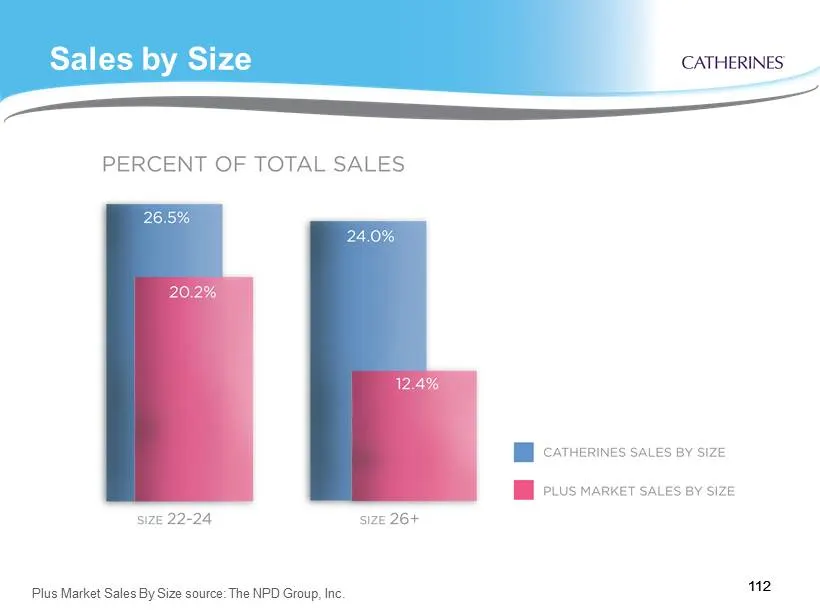
Sales by Size 112 112 112 Plus Market Sales By Size source: The NPD Group, Inc.
Slide 113: Transforming the Business
Transforming the Business • Merchandising Transformation • Sales Productivity 113
Slide 114: Merchandising Transformation: Product
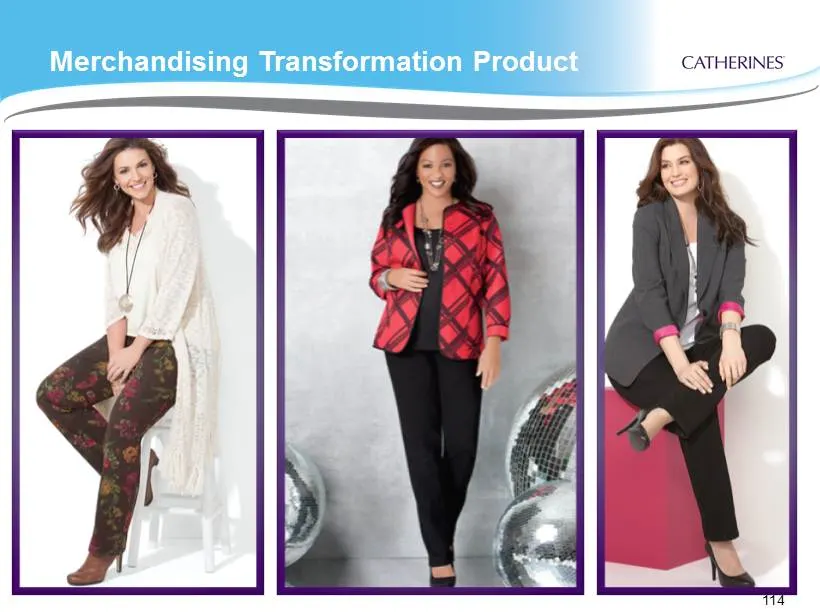
Merchandising Transformation Product 114 114
Slide 115: Merchandising Transformation: Product
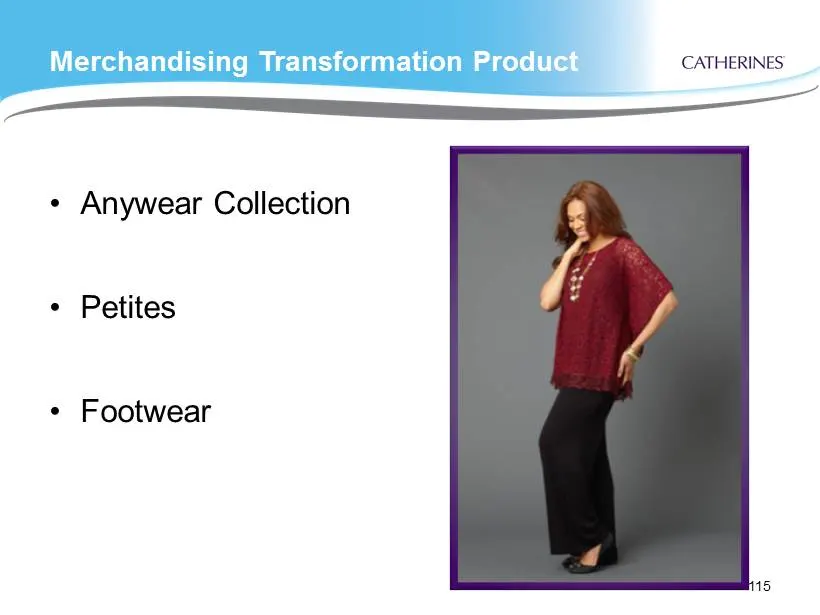
Merchandising Transformation Product • Anywear Collection • Petites • Footwear 115
Slide 116: Merchandising Transformation: Sourcing
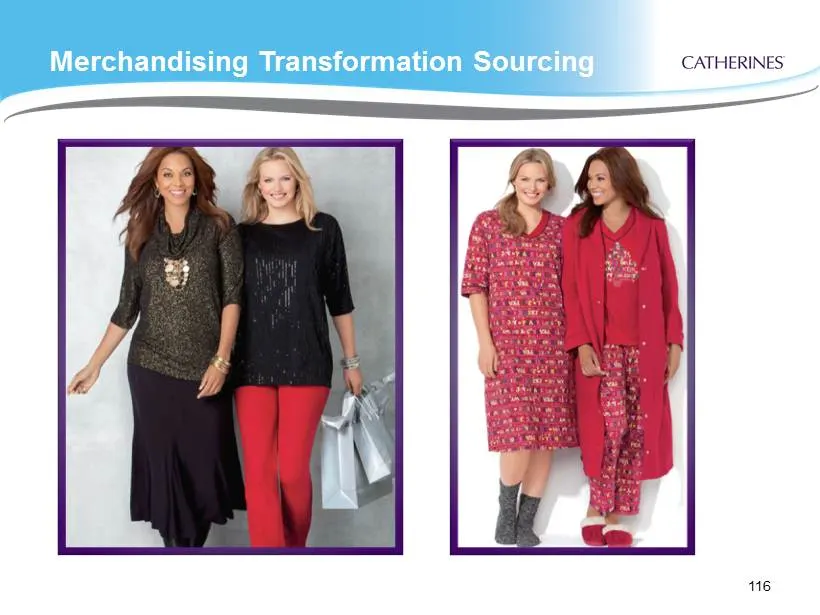
Merchandising Transformation Sourcing 116
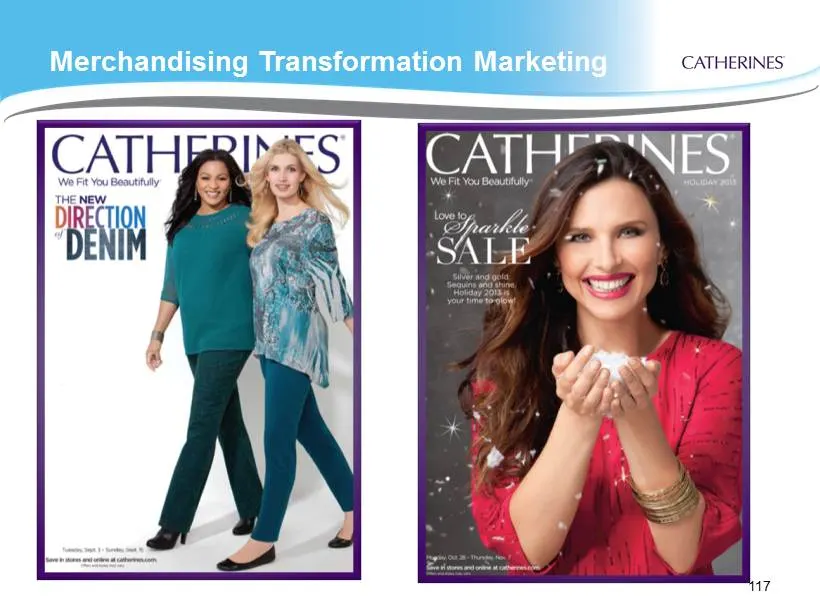
Slide 117: Merchandising Transformation: Marketing
Merchandising Transformation Marketing 117
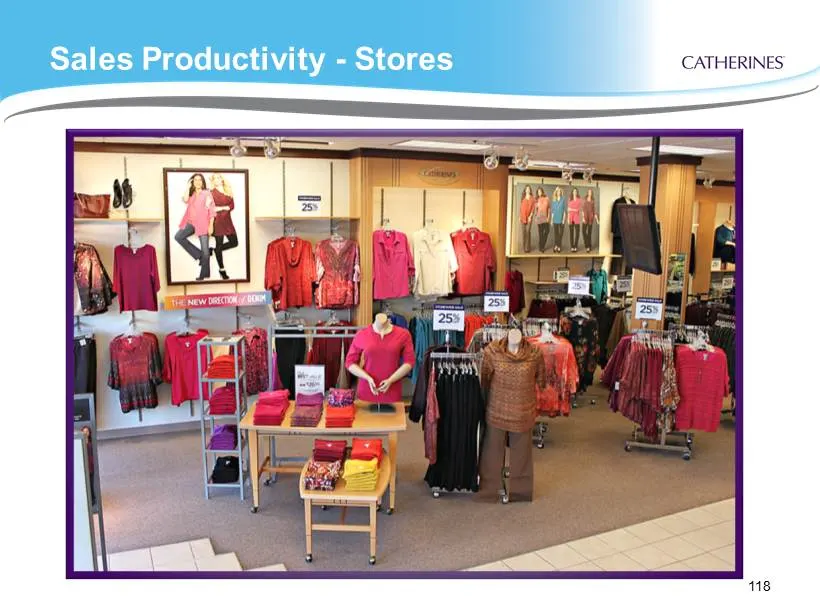
Slide 118: Sales Productivity - Stores
Sales Productivity - Stores 118
Slide 119: Sales Productivity: EXP Stores
Sales Productivity 750 EXP Stores • 40 stores • Innovation lab • Develop best in class business practices • Learnings to be rolled to chain 119
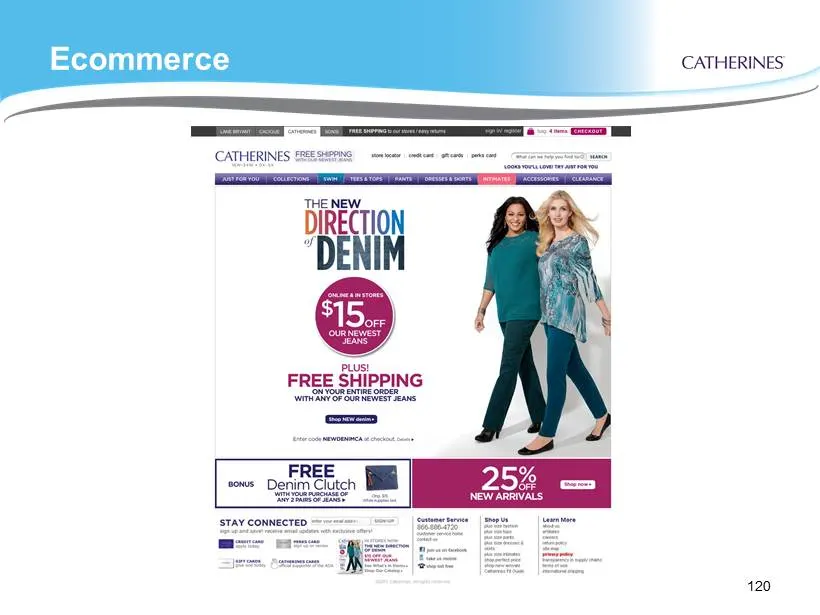
Slide 120: Catherines
CATHERINES ne FREE SHIPPING FREE Y) sows Peerem | Io 120
Slide 121: Catherines
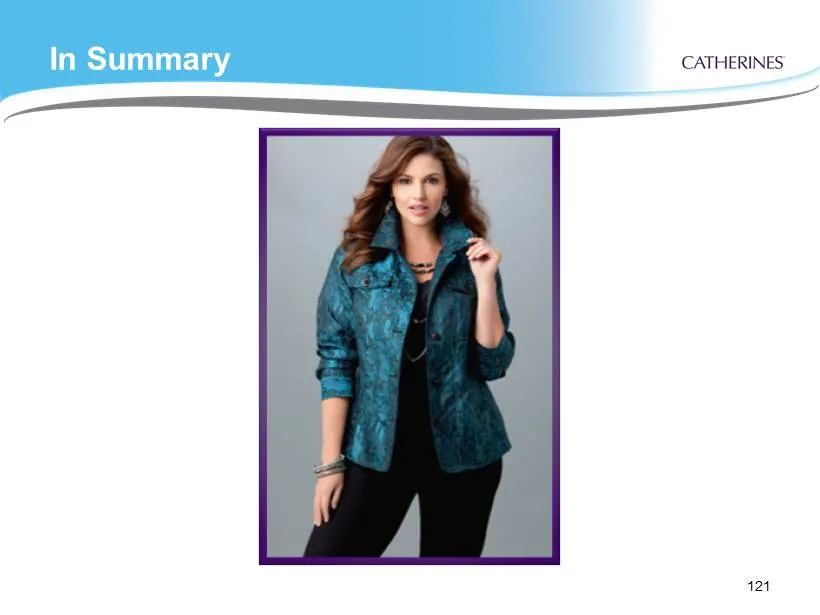
CATHERINES 121
Slide 122: Shared Services, John Sullivan
Shared Services John Sullivan Chief Operating Officer
Slide 123: Executives Present
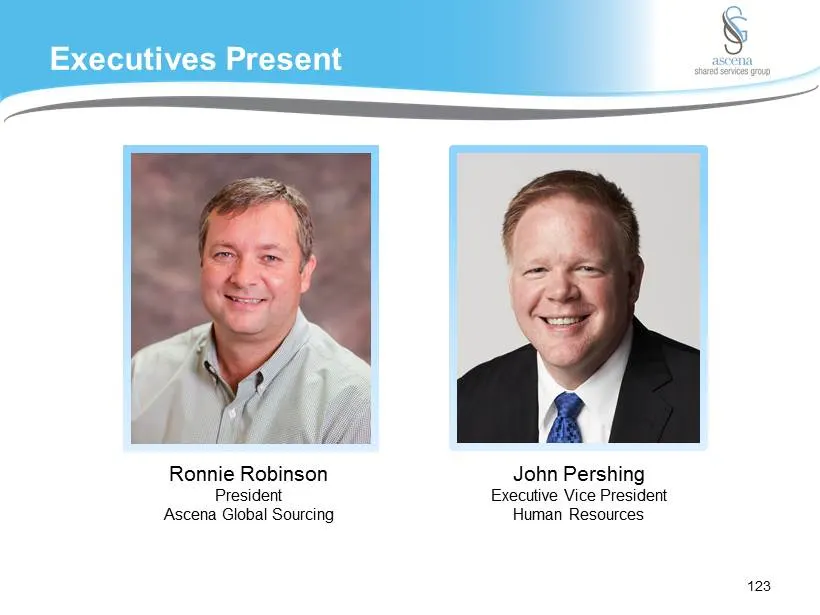
Executives Present 123 Ronnie Robinson President Ascena Global Sourcing John Pershing Executive Vice President Human Resources
Slide 124: Our Mission
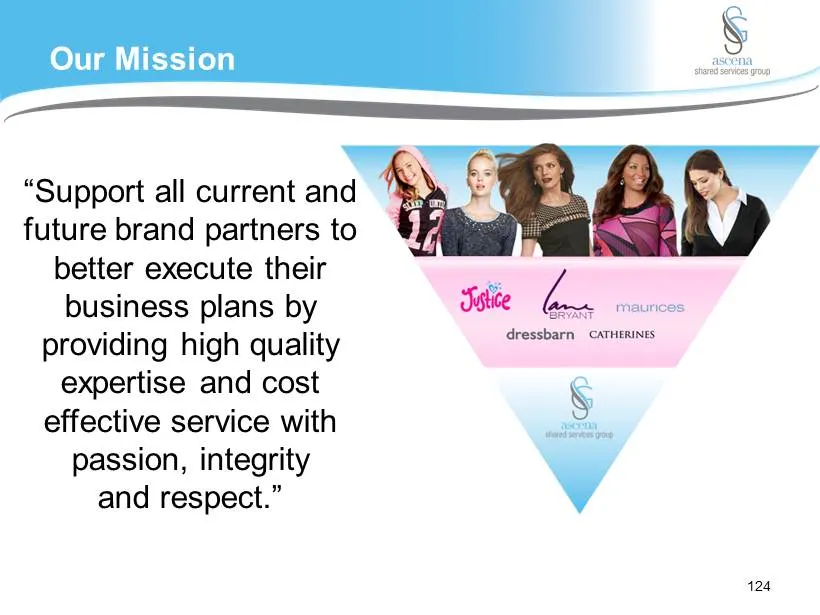
Our Mission “Support all current and future brand partners to better execute their business plans by providing high quality expertise and cost effective service with passion, integrity and respect.” 124
Slide 125: Integration Strategies
Integration Strategies • Transform distribution centers • Redesign transportation network • Unify technology platforms • Expand product sourcing • Optimize business processing 125
Slide 126: Transform Distribution Centers: National Retail Distribution Center
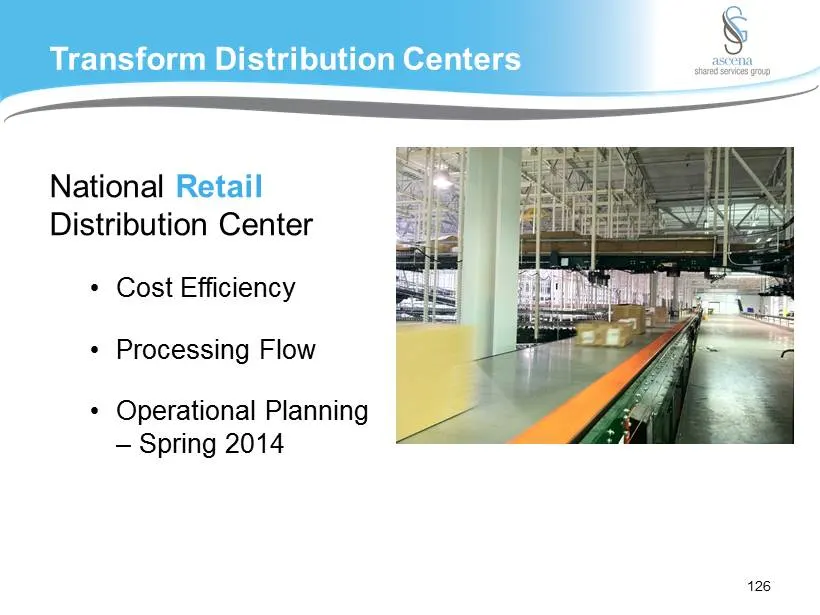
Transform Distribution Centers National Retail Distribution Center • Cost Efficiency • Processing Flow • Operational Planning – Spring 2014 126
Slide 127: Transform Distribution Centers Progress
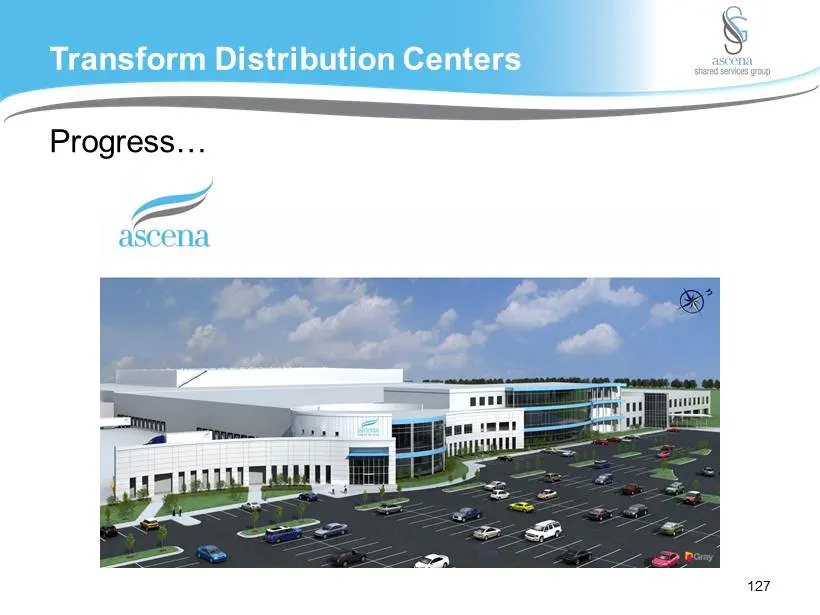
Transform Distribution Centers Progress… 127
Slide 128: Transform Distribution Centers: National Ecommerce Fulfillment Center
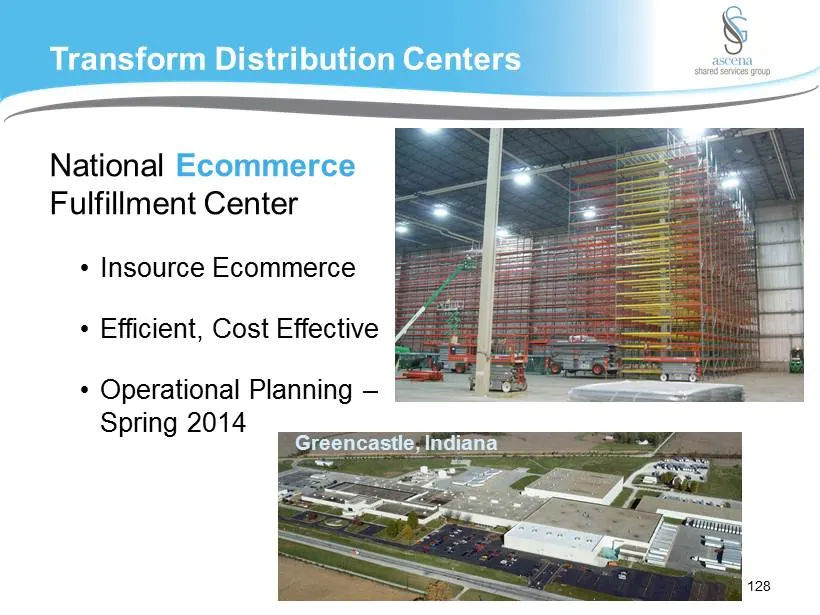
Transform Distribution Centers National Ecommerce Fulfillment Center • Insource Ecommerce • Efficient, Cost Effective • Operational Planning – Spring 2014 Greencastle, Indiana 128
Slide 129: Redesign Transportation Network
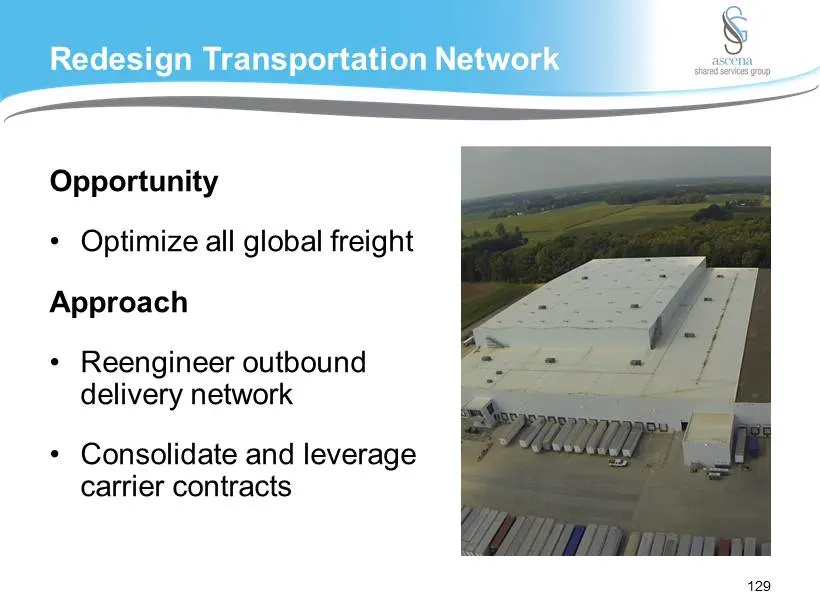
Redesign Transportation Network Opportunity • Optimize all global freight Approach • Reengineer outbound delivery network • Consolidate and leverage carrier contracts 129
Slide 130: Expand Direct Sourcing
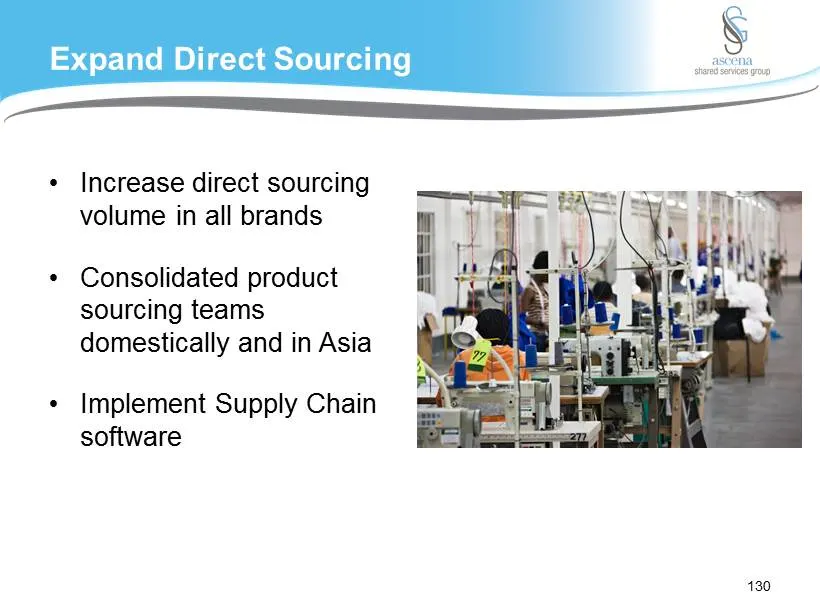
Expand Direct Sourcing • Increase direct sourcing volume in all brands • Consolidated product sourcing teams domestically and in Asia • Implement Supply Chain software 130
Slide 131: Transform Technology Platforms
Transform Technology Platforms • Consolidate data centers • Standardize core processing systems across all brands – Point of Sale – Financial – Warehouse Management – Merchandising • Unify technology teams 131
Slide 132: Shared Service Capabilities
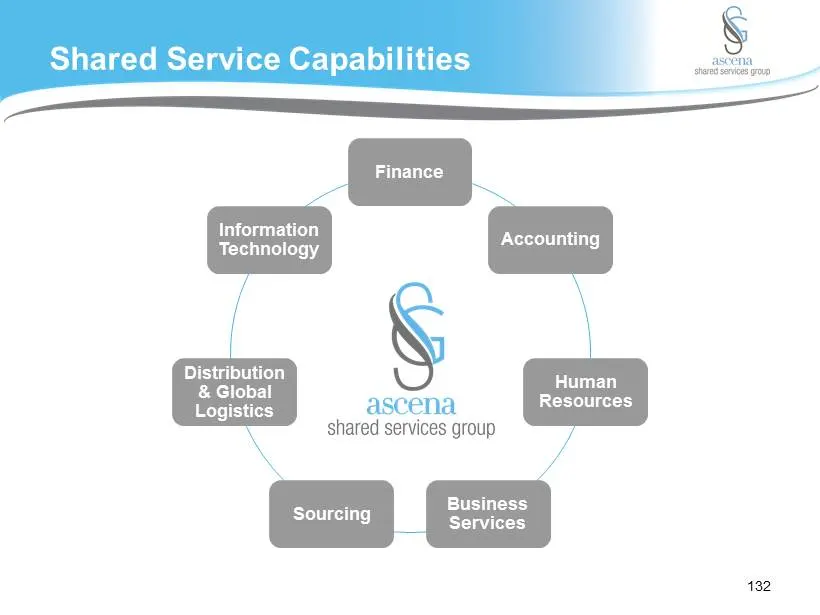
Shared Service Capabilities Finance Accounting Human Resources Business Services Sourcing Distribution & Global Logistics Information Technology 132
Slide 133: Closing Thoughts: Transformation Progress
Closing Thoughts….. Transformation progress…. Plan Execute Innovate 133
Slide 134: Financial Highlights, Dirk Montgomery
Financial Highlights Dirk Montgomery Chief Financial Officer
Slide 135: Executives Present
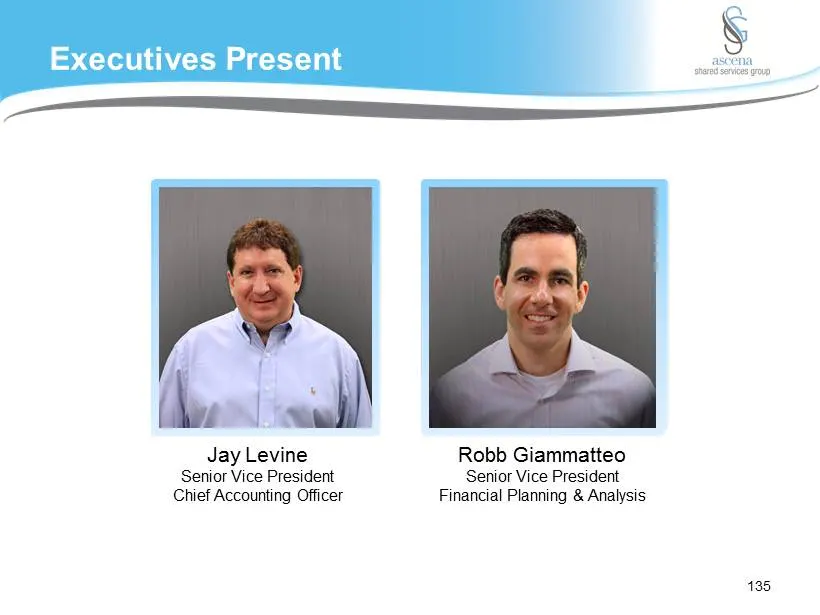
Executives Present Jay Levine Senior Vice President Chief Accounting Officer Robb Giammatteo Senior Vice President Financial Planning & Analysis 135
Slide 136: Attractive Investment Considerations
Attractive Investment Considerations • Diversified portfolio • Significant top line growth opportunities • Margin upside from shared services & synergies • Strong Balance Sheet & Cash Flow • Future opportunities 136
Slide 137: Diversified Portfolio
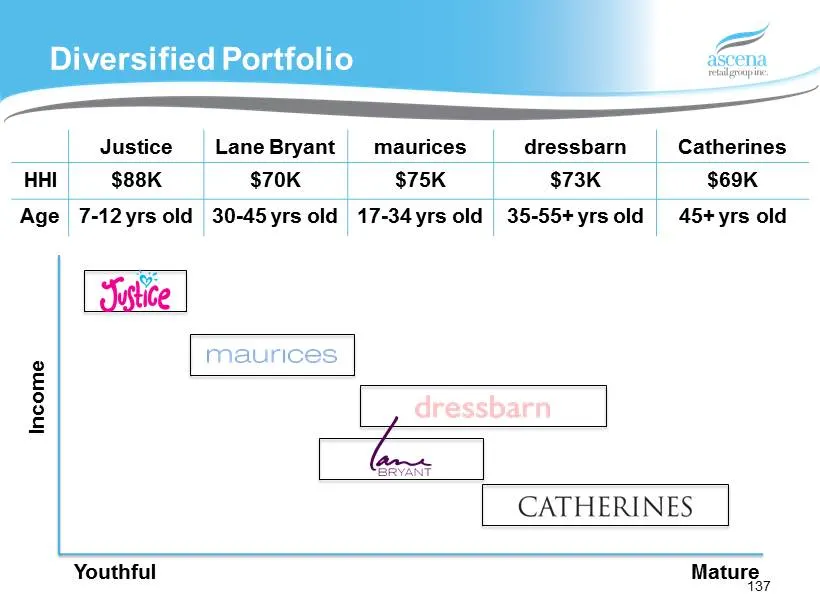
Youthful Mature Income Diversified Portfolio Justice Lane Bryant maurices dressbarn Catherines HHI $88K $70K $75K $73K $69K Age 7 - 12 yrs old 30 - 45 yrs old 17 - 34 yrs old 35 - 55+ yrs old 45+ yrs old 137
Slide 138: Annual New Store Growth: 1% to 2%
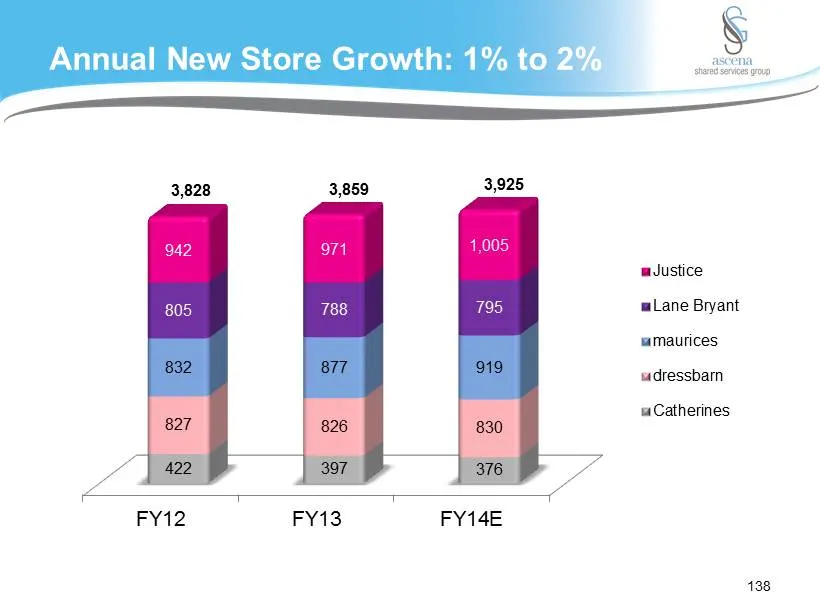
Annual New Store Growth: 1% to 2% FY12 FY13 FY14E 422 397 376 827 826 830 832 877 919 805 788 795 942 971 1,005 Justice Lane Bryant maurices dressbarn Catherines 3,828 3,859 3,925 138
Slide 139: Strong Ecommerce Growth
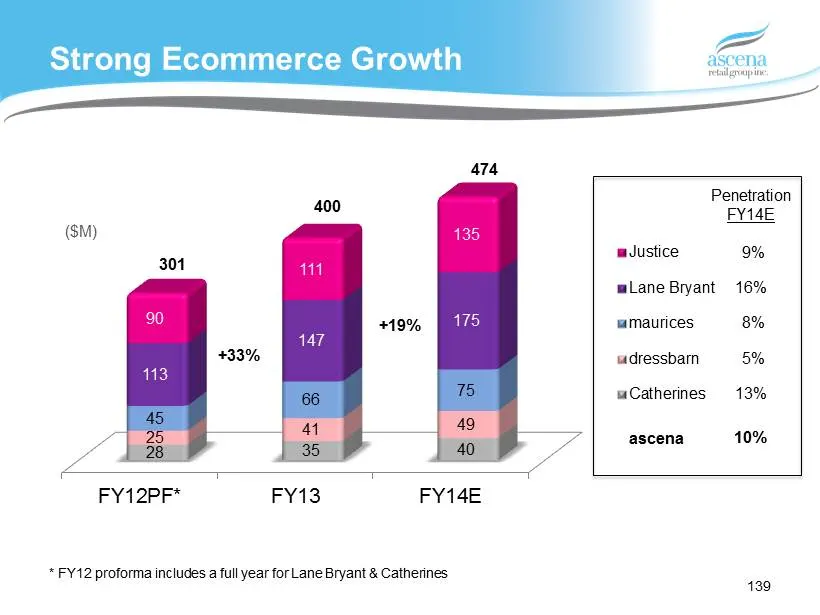
Strong Ecommerce Growth FY12PF* FY13 FY14E 28 35 40 25 41 49 45 66 75 113 147 175 90 111 135 Justice Lane Bryant maurices dressbarn Catherines 135/9% ($M) 301 474 400 Penetration FY14E 9% 16% 8% 5% 13% 10% ascena +33% +19% * FY12 proforma includes a full year for Lane Bryant & Catherines 139
Slide 140: Annual Revenue Growth: 4% to 7%+
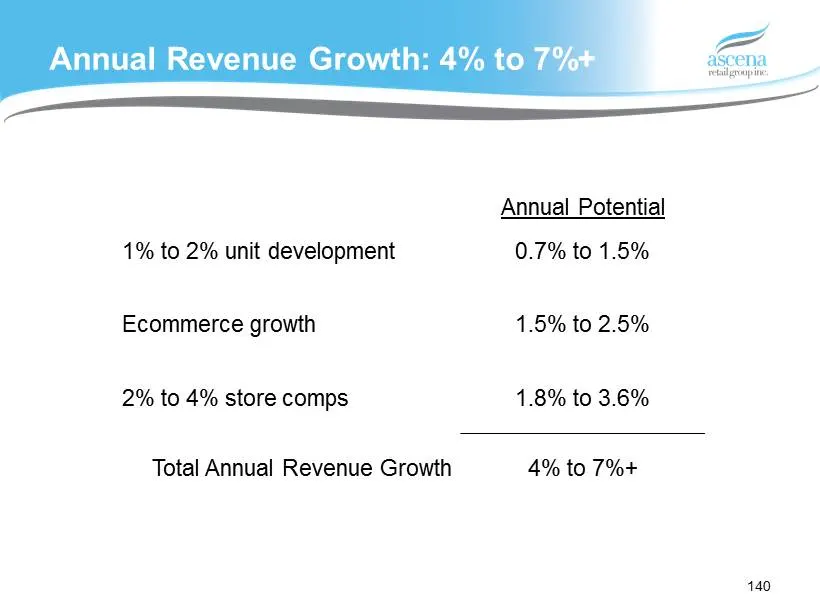
Annual Revenue Growth: 4% to 7%+ Annual Potential 1% to 2% unit development 0.7% to 1.5% Ecommerce growth 1.5% to 2.5% 2% to 4% store comps 1.8% to 3.6% Total Annual Revenue Growth 4% to 7%+ 140
Slide 141: Key Initiatives Drive Margin Upside
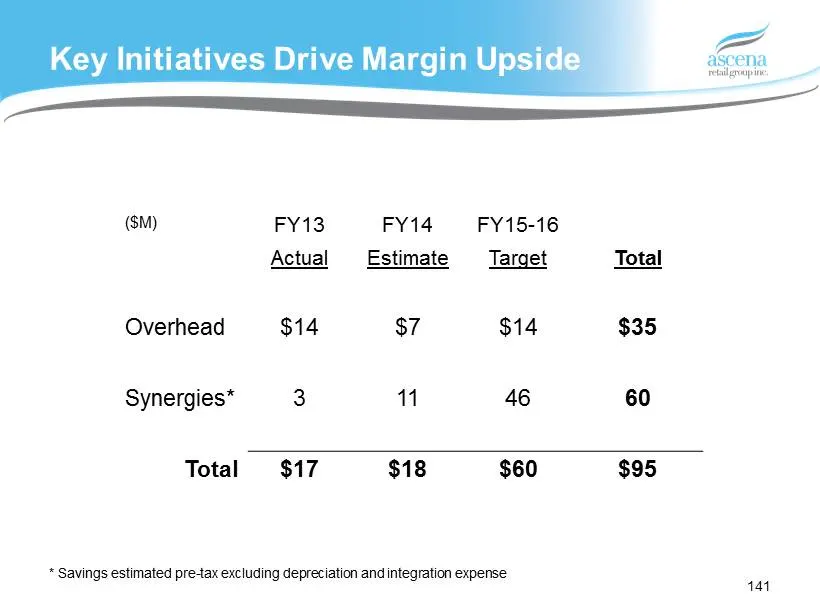
Key Initiatives Drive Margin Upside ($M) FY13 FY14 FY15 - 16 Actual Estimate Target Total Overhead $14 $7 $14 $35 Synergies* 3 11 46 60 Total $17 $18 $60 $95 * Savings estimated pre - tax excluding depreciation and integration expense 141
Slide 142: Synergy Initiatives On Track
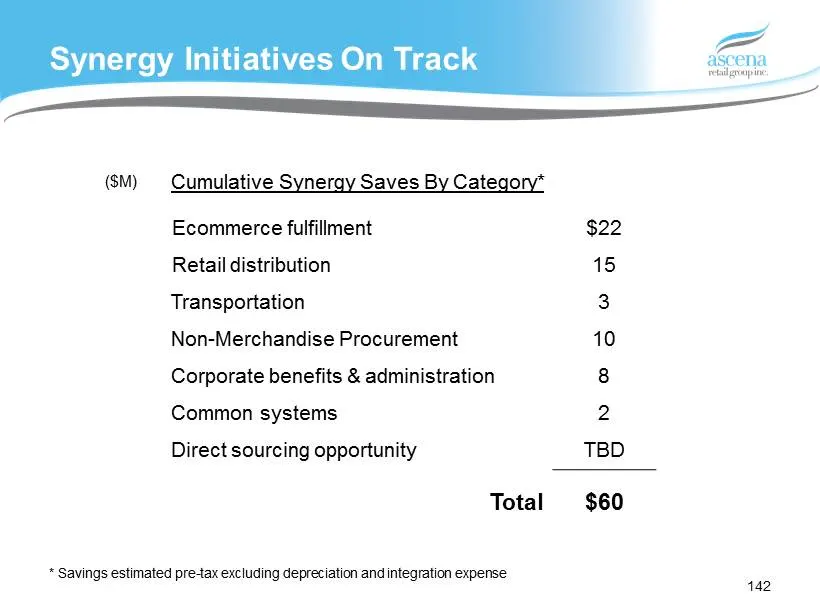
Synergy Initiatives On Track Cumulative Synergy Saves By Category* Ecommerce fulfillment $22 Retail distribution 15 Transportation 3 Non - Merchandise Procurement 10 Corporate benefits & administration 8 Common systems 2 Direct sourcing opportunity TBD Total $60 * Savings estimated pre - tax excludi
Slide 143: 10%+ Long Range Operating Margin
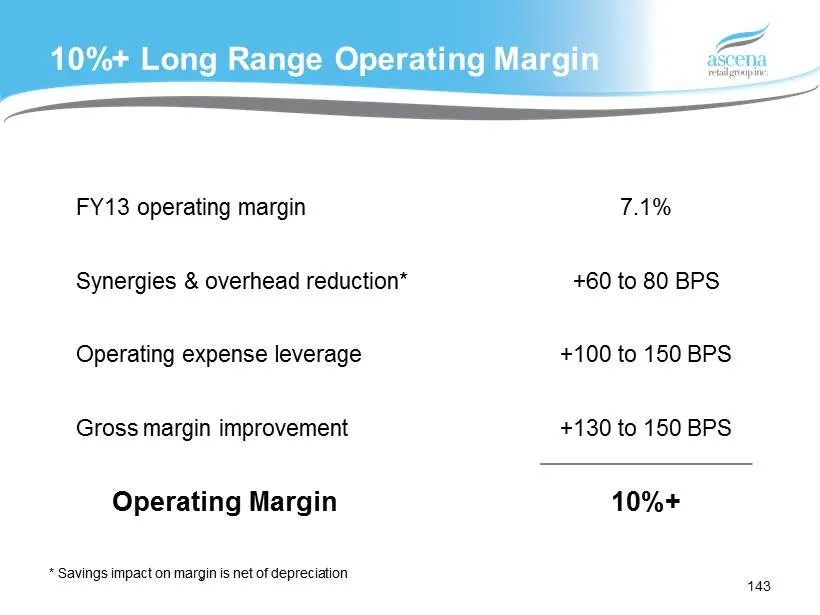
10%+ Long Range Operating Margin FY13 operating margin 7.1% Synergies & overhead reduction* +60 to 80 BPS Operating expense leverage +100 to 150 BPS Gross margin improvement +130 to 150 BPS Operating Margin 10%+ * * Savings impact on margin is net of depreciation 143
Slide 144: FY14 Is Peak Year For CapEx
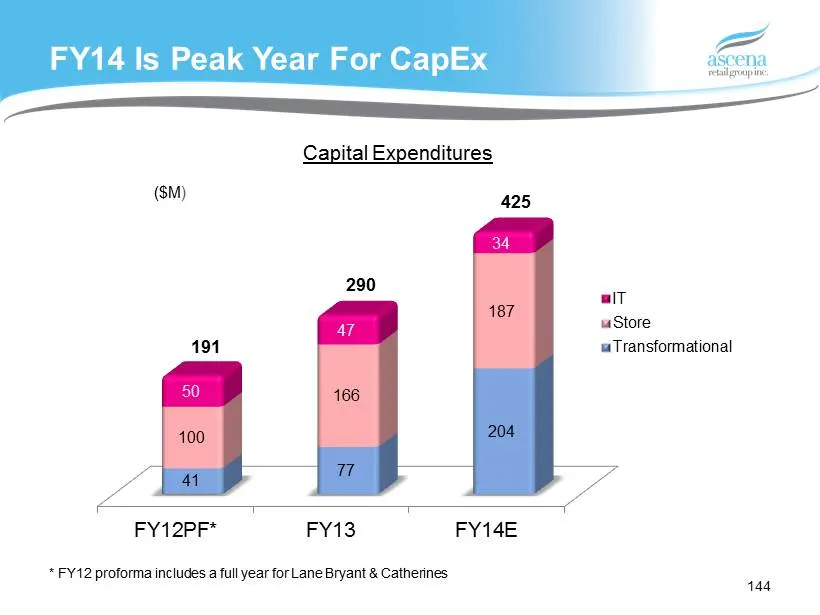
FY14 Is Peak Year For CapEx FY12PF* FY13 FY14E 41 77 204 100 166 187 50 47 34 IT Store Transformational ($M ) 425 290 191 Capital Expenditures * FY12 proforma includes a full year for Lane Bryant & Catherines 144
Slide 145: Strong Excess Cash Flow
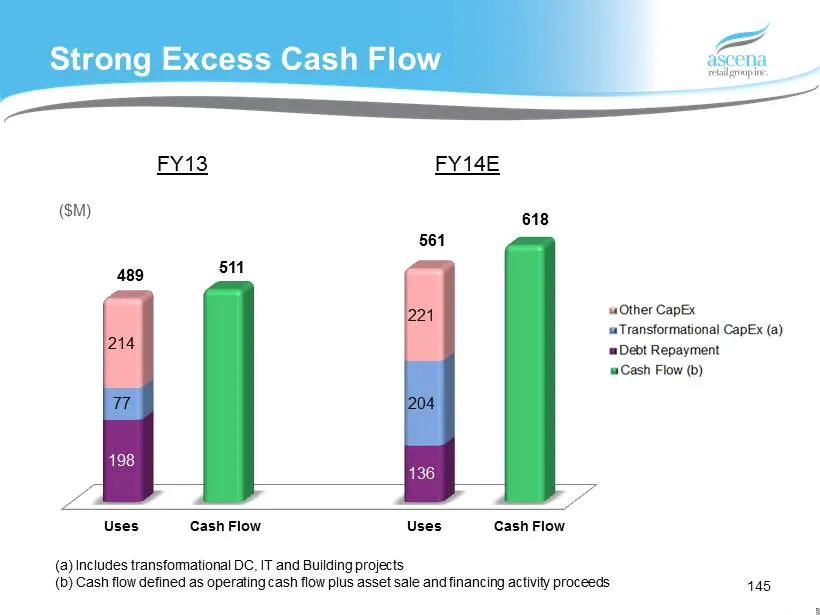
Strong Excess Cash Flow 198 136 77 204 214 221 511 618 Cash Flow (b) Other CapEx Transformational CapEx (a) Debt Repayment FY13 ($M) (a) Includes transformational DC, IT and Building projects (b) Cash flow defined as operating cash flow plus asset sale and financing activity proceeds 489 561 Cash Fl
Slide 146: Strong Balance Sheet: Zero Net Debt
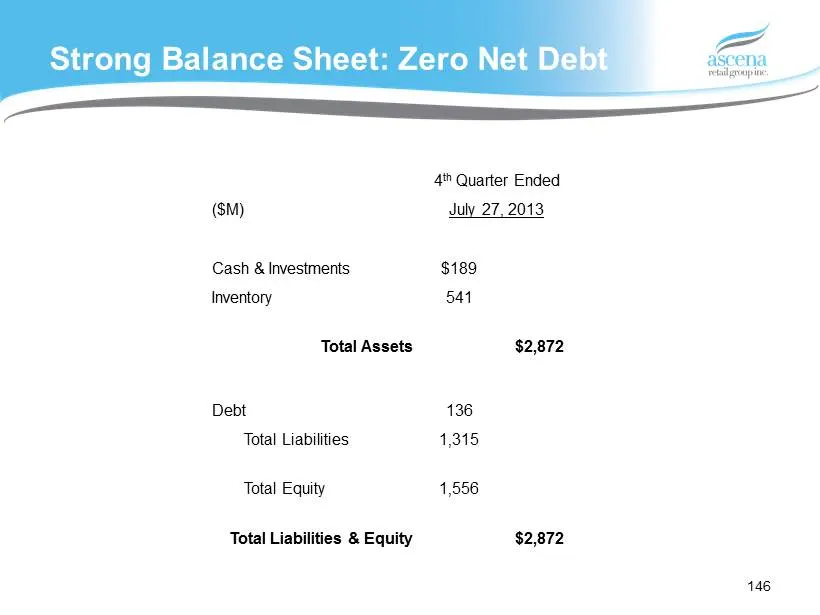
Strong Balance Sheet: Zero Net Debt 4 th Quarter Ended ($M) July 27, 2013 Cash & Investments $189 Inventory 541 Total Assets $2,872 Debt 136 Total Liabilities 1,315 Total Equity 1,556 Total Liabilities & Equity $2,872 Strong Balance Sheet and Cash Flow 146
Slide 147: Long-Term Economic Model
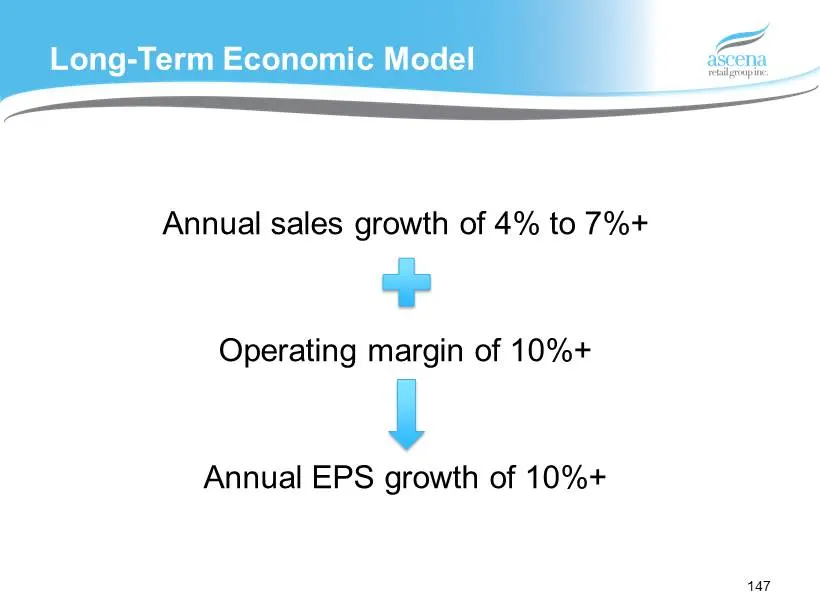
Long - Term Economic Model Annual sales growth of 4% to 7%+ Operating margin of 10%+ Annual EPS growth of 10%+ 147
Slide 148: Our Vision
Our Vision “Serve our shareholders and create value by becoming a family of leading retail concepts with $10 billion in sales and top tier profitability.” 148
Slide 149: Attractive Investment Considerations
Attractive Investment Considerations • Diversified portfolio • Significant top line growth opportunities • Margin upside from shared services & synergies • Strong Balance Sheet & Cash Flow • Future opportunities 149
Slide 150: Investor Conference October 9, 2013
Investor Conference October 9, 2013
Source: SEC EDGAR · 8-K filed Oct 9, 2013
More decks from Ascena Retail Group Inc
 Q2 FY2020 Earnings Presentation9 slides · Mar 9, 2020
 Q1 FY2020 Earnings Presentation9 slides · Dec 9, 2019
 Q4 FY2019 Earnings Presentation9 slides · Oct 3, 2019
 Earnings Presentation (June 2019)5 slides · Jun 10, 2019
 Q3 2019 Earnings Presentation11 slides · Jun 10, 2019
 Q2 FY2019 Earnings Presentation12 slides · Mar 14, 2019