Airtran — Investor Presentation (March 2005)
16 slides from Airtran's investor presentation, Mar 24, 2005
Slide 1: Investor Update — March 2005
Investor Update — March 2005
Slide 2: Forward-looking statements
Please note that the discussion today may contain forward looking statements that involve risks and uncertainties including those relating to the company’s ability to develop new markets, its fleet and growth plans, its low cost advantage vs. competitors, its ability to obtain financing, and its abi
Slide 3: AirTran Airways Today
AirTran Airways Today Low-cost, low-fare airline serving 43 cities One of youngest all-Boeing fleets in the world Fleet of 92 aircraft (81 717’s/11 737’s) Six consecutive years of profitability One of three consistently profitable airlines Well positioned for growth
Slide 4: 2004 Highlights — Continued Strong Cost Performance
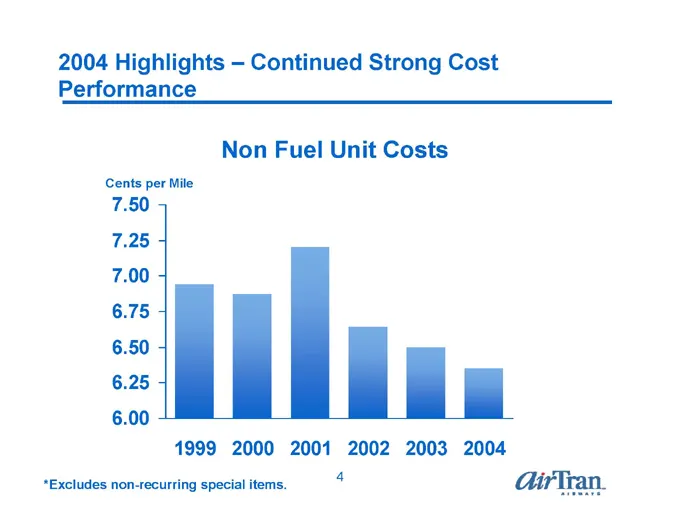
2004 Highlights — Continued Strong Cost Performance Non Fuel Unit Costs Cents per Mile 7.50 7.25 7.00 6.75 6.50 6.25 6.00 1999 2000 2001 2002 2003 2004 *Excludes non-recurring special items.
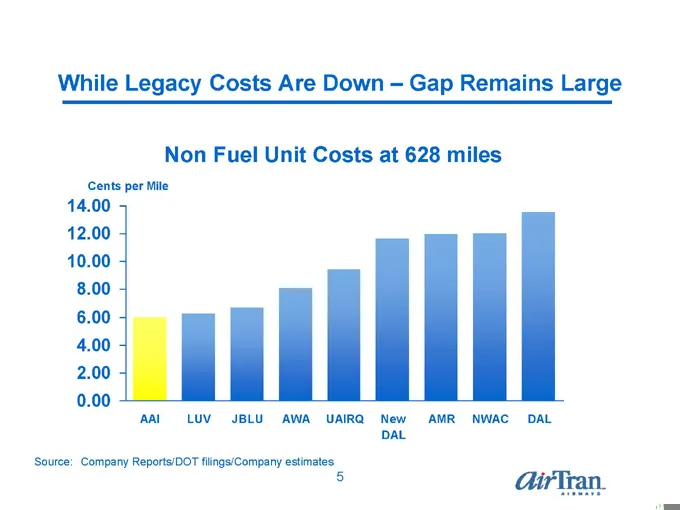
Slide 5: While Legacy Costs Are Down — Gap Remains Large
While Legacy Costs Are Down — Gap Remains Large Non Fuel Unit Costs at 628 miles Cents per Mile 14.00 12.00 10.00 8.00 6.00 4.00 2.00 0.00 AAI LUV JBLU AWA UAIRQ New DAL AMR NWAC DAL Source: Company Reports/DOT filings/Company estimates
Slide 6: What Creates AirTran's Cost Advantage?
What Creates AirTran’s Cost Advantage? Productive workforce at all levels Young, simplified fleet Fuel efficient Attractive ownership costs Efficient use of facilities Competition for heavy maintenance contracts Low cost distribution 74% of sales are directly with AirTran
Slide 7: New Aircraft Will Continue To Drive Down Costs
New 737 Aircraft Will Continue To Drive Down Costs Increases crew productivity No additional staffing required, same rates as 717 crews 17% increase in seats Transcontinental range increases productivity Daily utilization now 12-13 hrs/day vs. 11 hrs/day on 717’s Even better fuel economy than the 71
Slide 8: Low Costs Does Not Mean Budget Service
Low Costs Does Not Mean Budget Service Assigned seating Business class Only airline with business class on every flight Convenient distribution Internet/Kiosks No fee telephone reservations and airport sales Travel agencies XM Radio and oversized luggage bins Friendly crewmembers
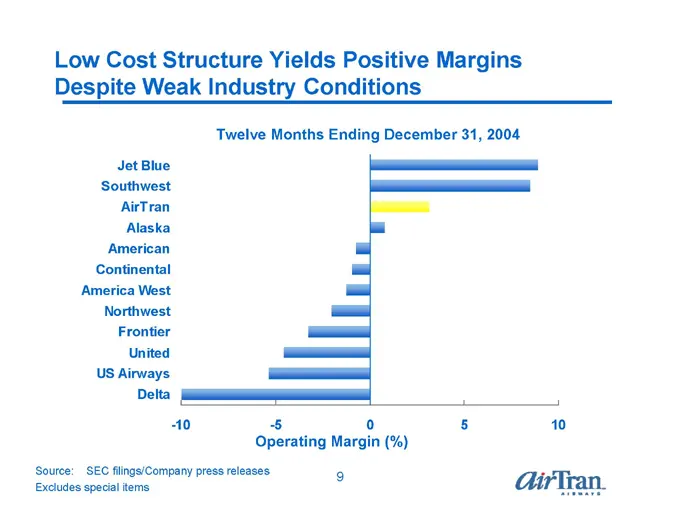
Slide 9: Low Cost Structure Yields Positive Margins Despite Weak Industry Conditions
Low Cost Structure Yields Positive Margins Despite Weak Industry Conditions Twelve Months Ending December 31, 2004 Jet Blue Southwest AirTran Alaska American Continental America West Northwest Frontier United US Airways Delta -10 -5 0 5 10 Operating Margin (%) Source: SEC filings/Company press relea
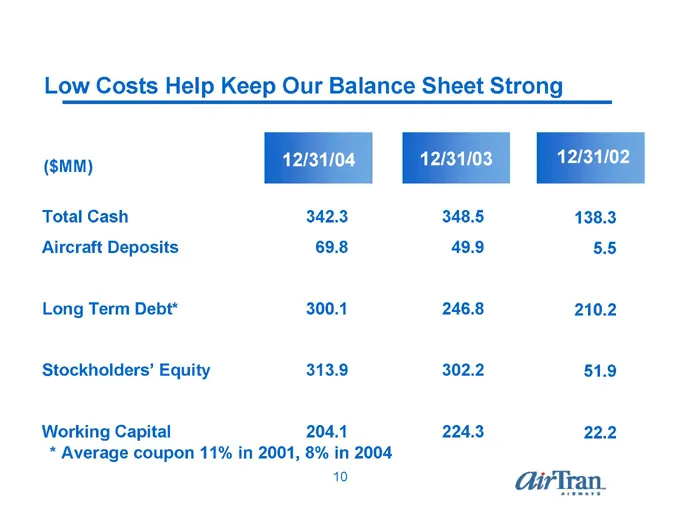
Slide 10: Low Costs Help Keep Our Balance Sheet Strong
Low Costs Help Keep Our Balance Sheet Strong 12/31/04 12/31/03 12/31/02 ($MM) Total Cash 342.3 348.5 138.3 Aircraft Deposits 69.8 49.9 5.5 Long Term Debt* 300.1 246.8 210.2 Stockholders’ Equity 313.9 302.2 51.9 Working Capital 204.1 224.3 22.2 * Average coupon 11% in 2001, 8% in 2004
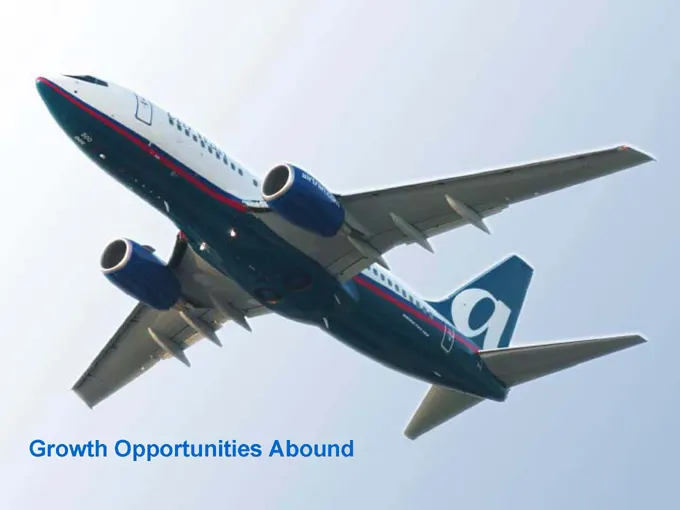
Slide 11: Growth Opportunities Abound
Growth Opportunities Abound
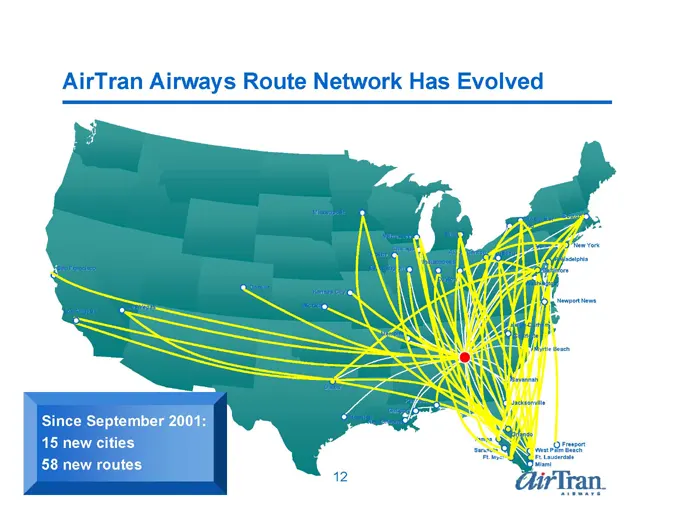
Slide 12: Route Network Has Evolved
AirTran Airways Route Network Has Evolved Since September 2001: 15 new cities 58 new routes Savannah Jacksonville Orlando San Francisco Los Angeles Las Vegas Minneapolis Milwaukee Chicago Moline Bloomington Denver Kansas City Wichita Flint Boston Buffalo Rochester Indianapolis Akron/Canton Dayton Pi
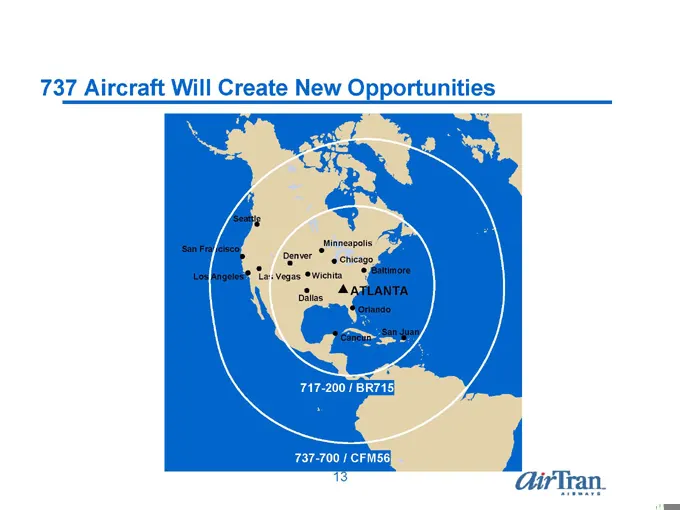
Slide 13: Aircraft Will Create New Opportunities
737 Aircraft Will Create New Opportunities Seattle San Francisco Los Angeles Minneapolis Denver Chicago Baltimore Las Vegas Wichita Dallas ATLANTA Orlando Cancun San Juan 717-200 / BR715 737-700 / CFM56
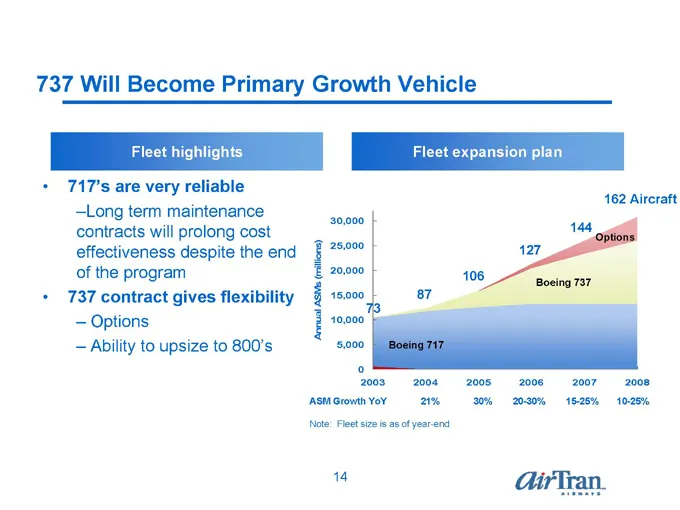
Slide 14: Will Become Primary Growth Vehicle
737 Will Become Primary Growth Vehicle Fleet highlights 717’s are very reliable Long term maintenance contracts will prolong cost effectiveness despite the end of the program 737 contract gives flexibility Options Ability to upsize to 800’s Fleet expansion plan Annual ASMs (millions) 30,000 25,000 2
Slide 15: Significant Growth Opportunities Exist
Significant Growth Opportunities Exist Delta has abandoned Dallas/Fort Worth The Northeast remains wide open AirTran is well positioned Florida remains a perfect fit for AirTran’s network 717 size also opens up routes from secondary cities Atlanta growth opportunities are still abundant We are Atlan
Slide 16: Summary
Summary Solid results despite challenging environment Industry shakeout is occurring Opportunities still abound without immediate failures Fundamentals are in place to capitalize on opportunities Aircraft on order at low ownership costs Small aircraft with very low costs and going lower Financial st
Source: SEC EDGAR · 8-K filed Mar 24, 2005
More decks from Airtran Holdings Inc
 Merger or Acquisition (September 2010)21 slides · Sep 27, 2010
 Bank of America - Merrill Lynch Global Transportation Conference 201025 slides · Jun 15, 2010
 Shareholder Meeting (May 2010)33 slides · May 18, 2010
 Investor Presentation (May 2010)26 slides · May 13, 2010
 JP Morgan Aviation, Transportation and Defense Conference 201025 slides · Mar 9, 2010
 Raymond James 2010 Growth Airline Conference25 slides · Feb 4, 2010