HCC Insurance — Investor Presentation (September 2009)
37 slides from HCC Insurance's investor presentation, Sep 29, 2009
Slide 1: Second Quarter 2009 Investor Presentation
Second Quarter 2009 Investor Presentation
Slide 2: Notice About This Presentation
Notice About This Presentation ABOUT FORWARD-LOOKING STATEMENTS: This presentation contains certain "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934, which are intended to be covered by the safe harbor
Slide 3: HCC Overview
HCC Overview Specialty insurer since 1974 (NYSE: HCC) Diversified operations headquartered in Houston, Texas include: P&C, Surety, Aviation and Life, Accident & Health Domestic and International Rated AA (Very Strong) by Standard & Poor's, AA (Very Strong) by Fitch Ratings and A+ (Superior) by A.M.
Slide 4: Lines of Business
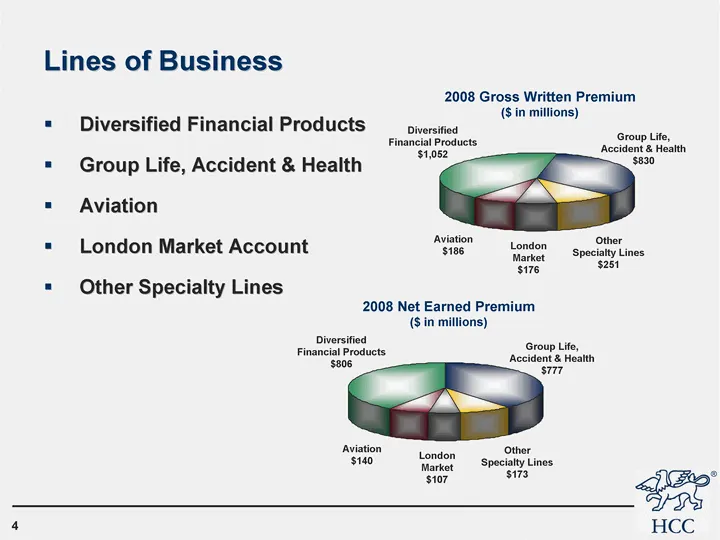
DFP Life A&H Other Spec Lon. Market Aviation 12/31/2008 806 777 173 107 140 Lines of Business Diversified Financial Products Group Life, Accident & Health Aviation London Market Account Other Specialty Lines DFP Life A&H Other Spec Lon. Market Aviation 12/31/2008 1052 830 251 176 186 Group Life, Acc
Slide 5: Lines of Business Comparison
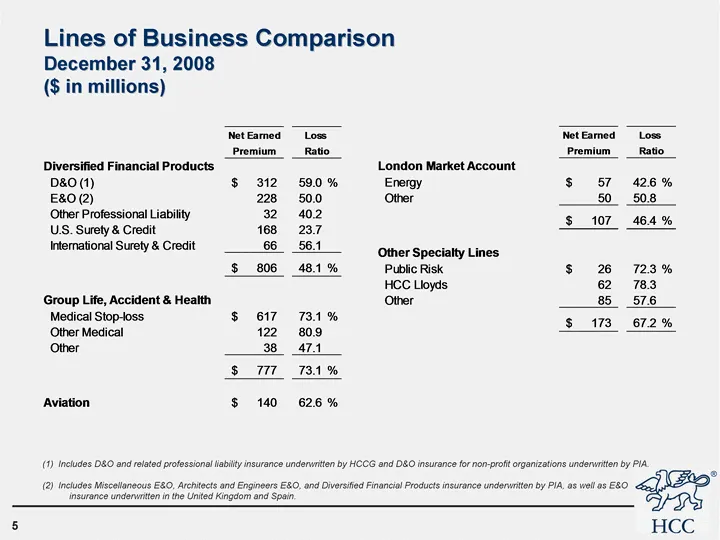
Lines of Business Comparison December 31, 2008 ($ in millions) (1) Includes D&O and related professional liability insurance underwritten by HCCG and D&O insurance for non-profit organizations underwritten by PIA. (2) Includes Miscellaneous E&O, Architects and Engineers E&O, and Diversified Financia
Slide 6: Historical Performance
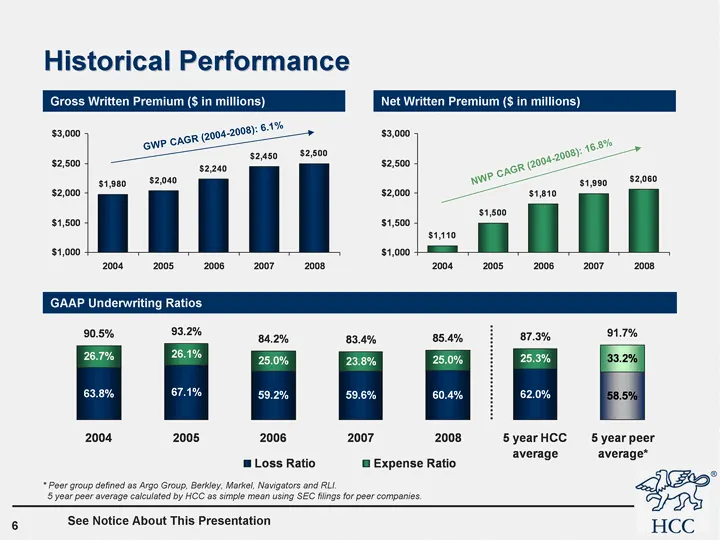
2003 2004 2005 2006 2007 2008 1Q09 Net Written Premium 870 1110 1500 1810 1990 2060 490 2003 2004 2005 2006 2007 2008 1Q09 Gross Written Premium 1620 1980 2040 2240 2450 2500 600 Historical Performance See Notice About This Presentation Gross Written Premium ($ in millions) 2004 2005 2006 2007 2008
Slide 7: 2009 Underwriting Performance: Peer Group Comparison YTD
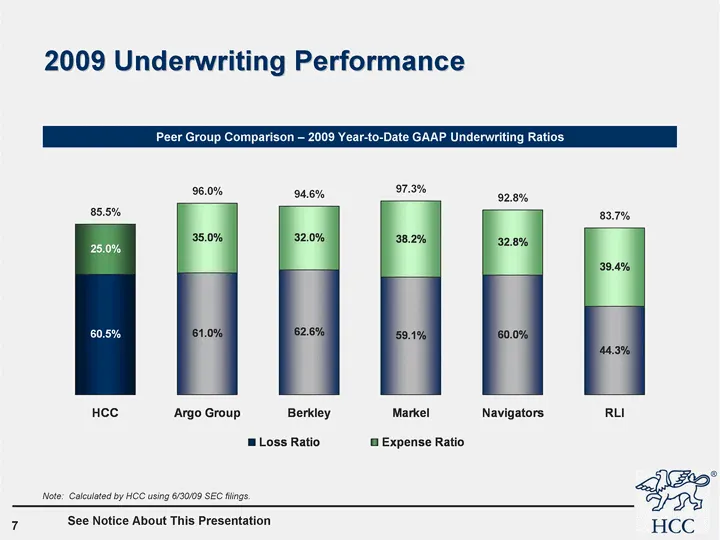
2009 Underwriting Performance HCC Argo Group Berkley Markel Navigators RLI Loss Ratio 0.605 0.61 0.626 0.591 0.6 0.443 Expense Ratio 0.25 0.35 0.32 0.382 0.328 0.394 0.855 0.96 0.946 0.973 0.928 0.837 Peer Group Comparison - 2009 Year-to-Date GAAP Underwriting Ratios See Notice About This Presentati
Slide 8: 2009 Underwriting Performance: Accident Year Ratios
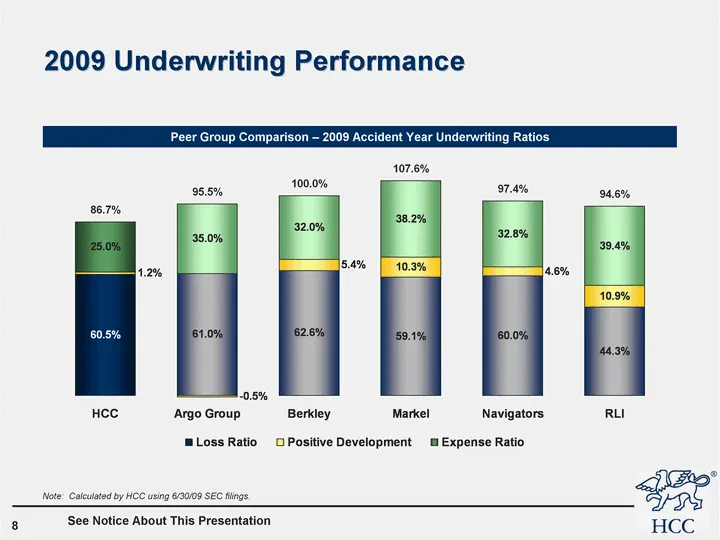
2009 Underwriting Performance HCC Argo Group Berkley Markel Navigators RLI Loss Ratio 0.605 0.61 0.626 0.591 0.6 0.443 Positive Development 0.012 -0.005 0.054 0.103 0.046 0.109 Expense Ratio 0.25 0.35 0.32 0.382 0.328 0.394 0.867 0.955 1 1.076 0.974 0.946 Peer Group Comparison - 2009 Accident Year U
Slide 9: 2009 Underwriting Performance: Loss Ratios
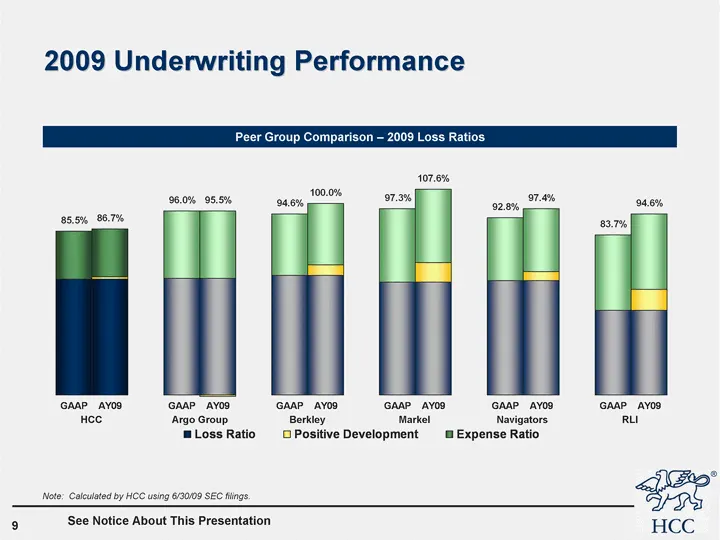
2009 Underwriting Performance GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 GAAP AY09 Loss Ratio 0.605 0.605 0.61 0.61 0.626 0.626 0.591 0.591 0.6 0.6 0.443 0.443 Positive Development 0.012 -0.005 0.054 0.103 0.046 0.109 Expense Ratio 0.25 0.25 0 0.35 0.35 0 0.32 0.32 0 0.382 0.382 0 0.328 0.328
Slide 10: A Culture Focused on Underwriting Profitability
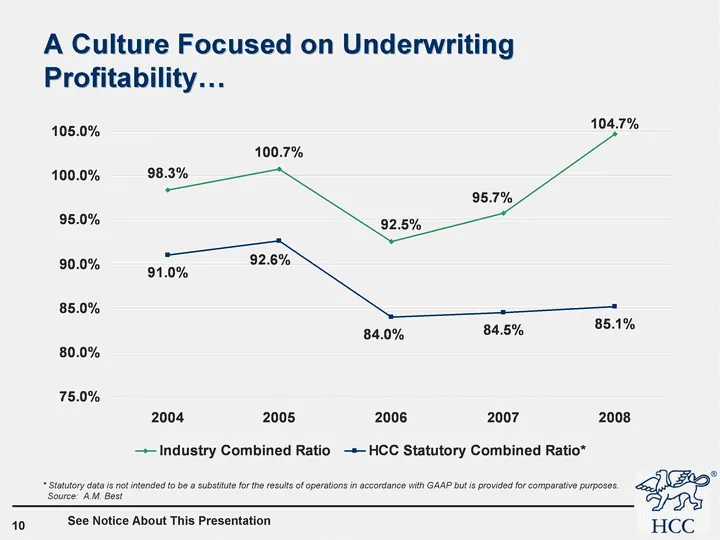
A Culture Focused on Underwriting Profitability... See Notice About This Presentation * Statutory data is not intended to be a substitute for the results of operations in accordance with GAAP but is provided for comparative purposes. Source: A.M. Best 2003 2004 2005 2006 2007 2008 Peer Group Average
Slide 11: Strong, Predictable Return on Equity
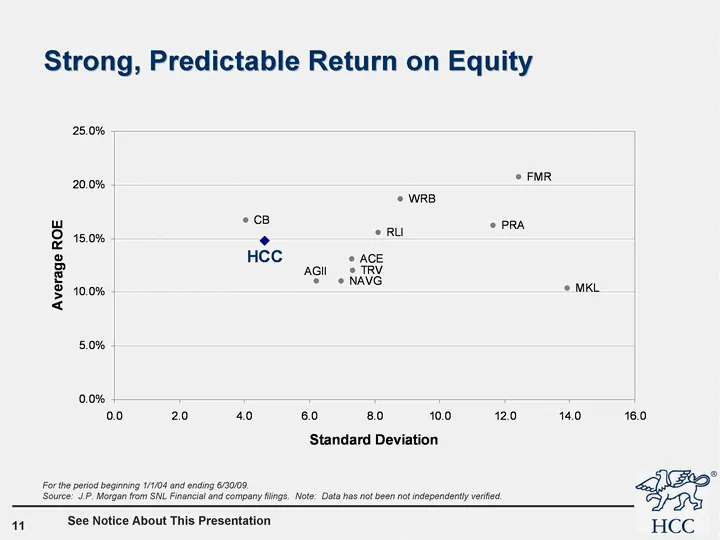
Strong, Predictable Return on Equity For the period beginning 1/1/04 and ending 6/30/09. Source: J.P. Morgan from SNL Financial and company filings. Note: Data has not been not independently verified. See Notice About This Presentation
Slide 12: Consistent Return on Equity
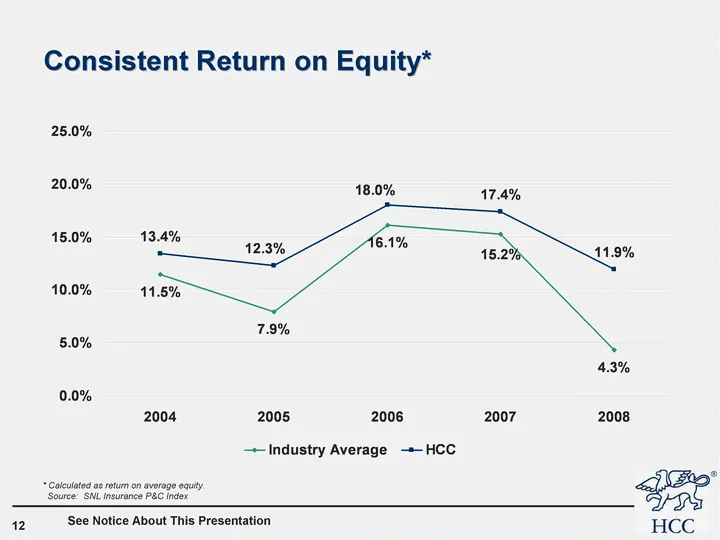
Consistent Return on Equity* See Notice About This Presentation * Calculated as return on average equity. Source: SNL Insurance P&C Index 2003 2004 2005 2006 2007 2008 Industry Average 0.113 0.1146 0.0789 0.1607 0.1524 0.0433 HCC Average 0.171 0.171 0.171 0.171 0.171 0.171 HCC 0.147 0.134 0.123 0.18
Slide 13: Strong BVPS Growth
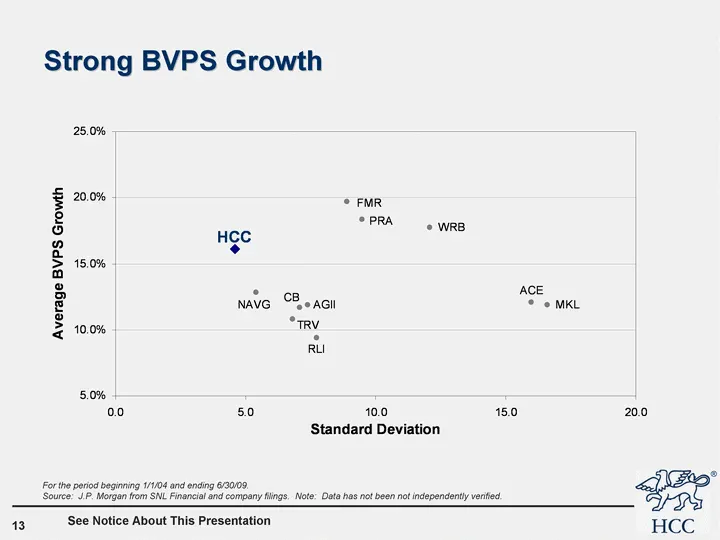
Strong BVPS Growth See Notice About This Presentation For the period beginning 1/1/04 and ending 6/30/09. Source: J.P. Morgan from SNL Financial and company filings. Note: Data has not been not independently verified.
Slide 14: Growth in Shareholders' Equity and BVPS
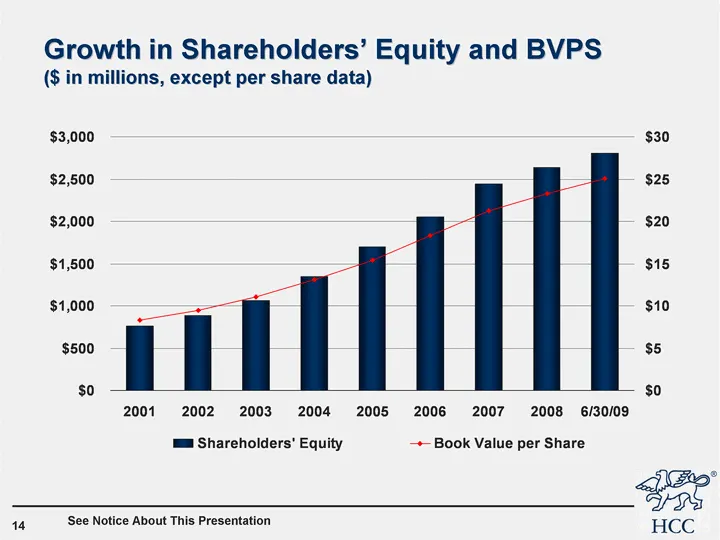
Growth in Shareholders' Equity and BVPS ($ in millions, except per share data) See Notice About This Presentation 1998 1999 2000 2001 2002 2003 2004 2005 2006 2007 2008 6/30/2009 Shareholders' Equity 440430000 458439000 530930000 765.347 884.671 1059.135 1341.274 1702.015 2050.009 2443.695 2640.023
Slide 15: Characteristics That Make HCC Unique
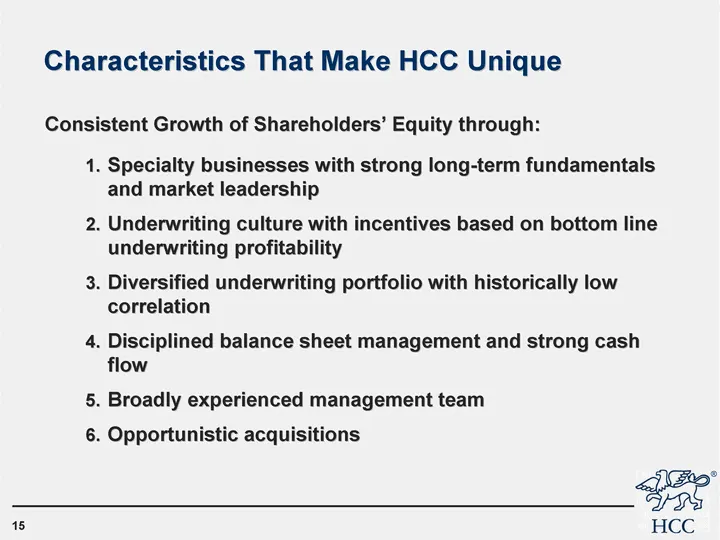
Characteristics That Make HCC Unique Consistent Growth of Shareholders' Equity through: Specialty businesses with strong long-term fundamentals and market leadership Underwriting culture with incentives based on bottom line underwriting profitability Diversified underwriting portfolio with historica
Slide 16: HCC Underwriters Compensation Example
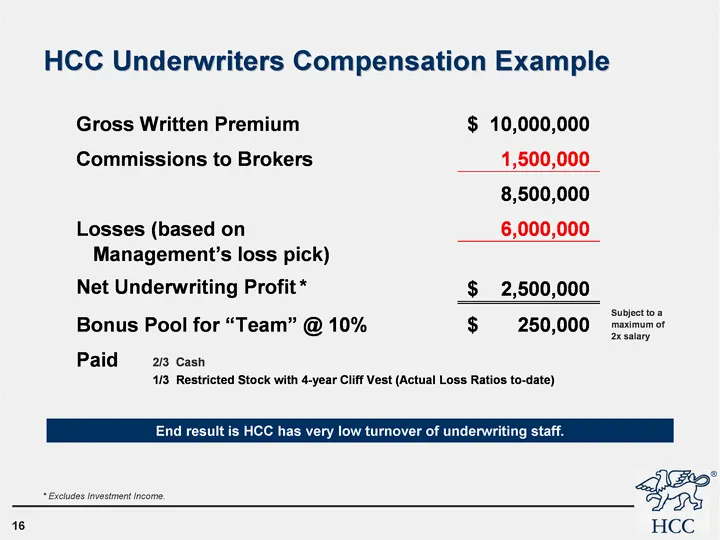
HCC Underwriters Compensation Example * Excludes Investment Income. * Excludes Investment Income. End result is HCC has very low turnover of underwriting staff.
Slide 17: A Diverse Collection of Profitable Businesses
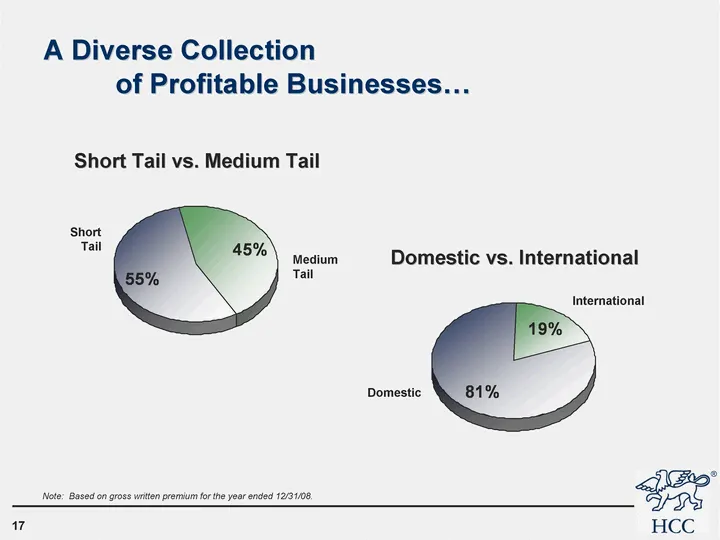
A Diverse Collection of Profitable Businesses... Short Medium 4th Qtr East 0.55 0.45 20.4 Short Tail vs. Medium Tail Short Tail Medium Tail Domestgic International East 0.81 0.19 Domestic vs. International International Domestic Note: Based on gross written premium for the year ended 12/31/08.
Slide 18: Select Product Characteristics
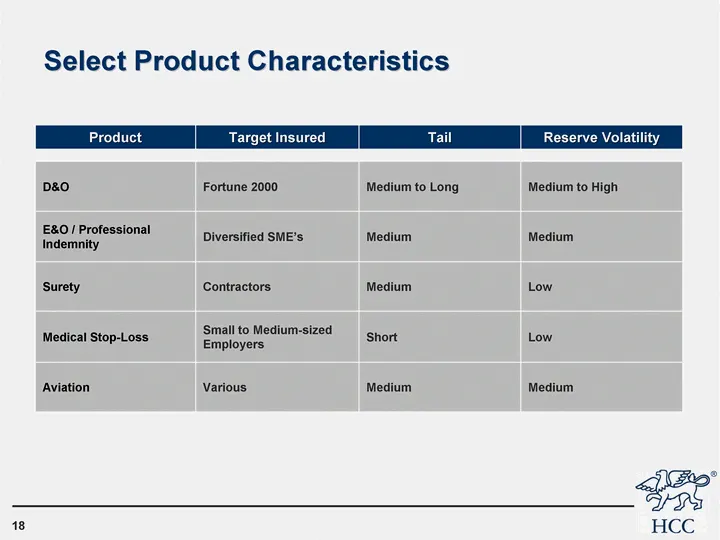
Select Product Characteristics Product Target Insured Tail Reserve Volatility D&O Fortune 2000 Medium to Long Medium to High E&O / Professional Indemnity Diversified SME's Medium Medium Surety Contractors Medium Low Medical Stop-Loss Small to Medium-sized Employers Short Low Aviation Various Medium
Slide 19: Effective Catastrophe Management
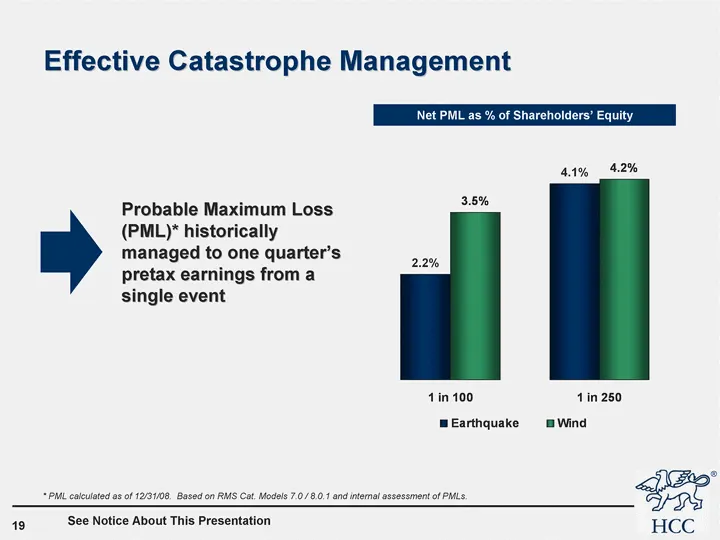
Effective Catastrophe Management 1 in 100 1 in 250 Earthquake 0.022 0.041 Wind 0.035 0.042 Probable Maximum Loss (PML)* historically managed to one quarter's pretax earnings from a single event See Notice About This Presentation * PML calculated as of 12/31/08. Based on RMS Cat. Models 7.0 / 8.0.1 a
Slide 20: Investment Portfolio June 30, 2009
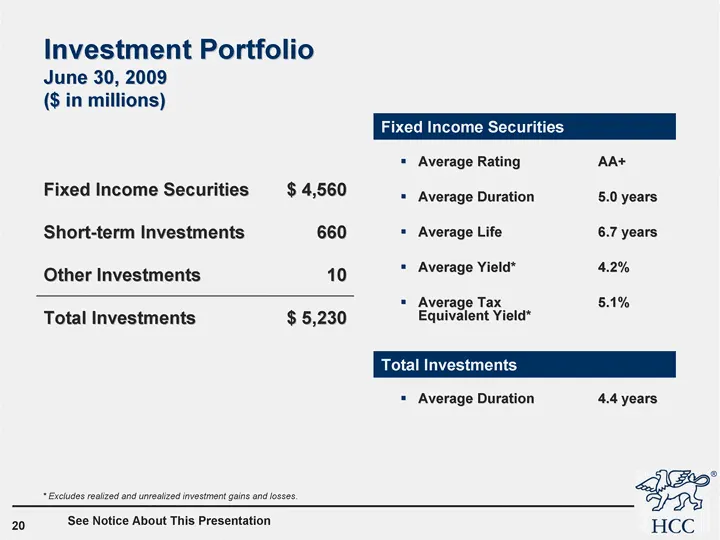
Average Rating AA+ Average Duration 5.0 years Average Life 6.7 years Average Yield* 4.2% Average Tax 5.1% Equivalent Yield* Average Duration 4.4 years Fixed Income Securities $ 4,560 Short-term Investments 660 Other Investments 10 Total Investments $ 5,230 Investment Portfolio June 30, 2009 ($ in mi
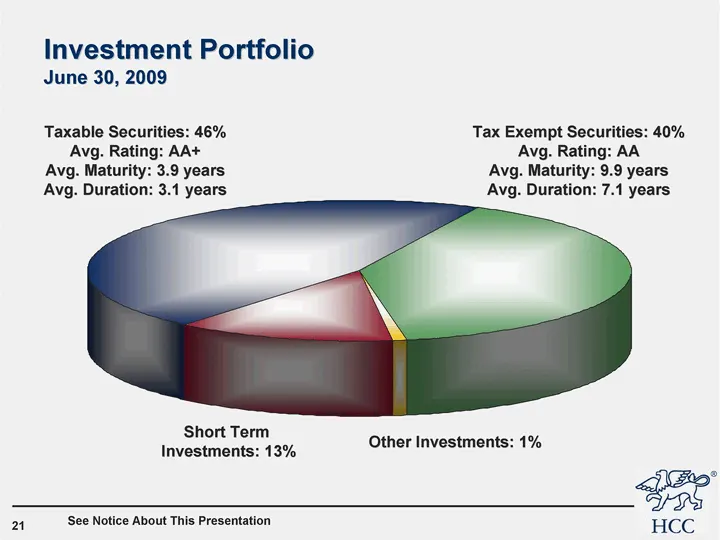
Slide 21: Investment Portfolio June 30, 2009
Taxable Securities Tax Exempt Securities Other Cash Short Term Investments 6/30/2007 46 40 1 1.1 13 See Notice About This Presentation Short Term Investments: 13% Tax Exempt Securities: 40% Avg. Rating: AA Avg. Maturity: 9.9 years Avg. Duration: 7.1 years Taxable Securities: 46% Avg. Rating: AA+ Avg
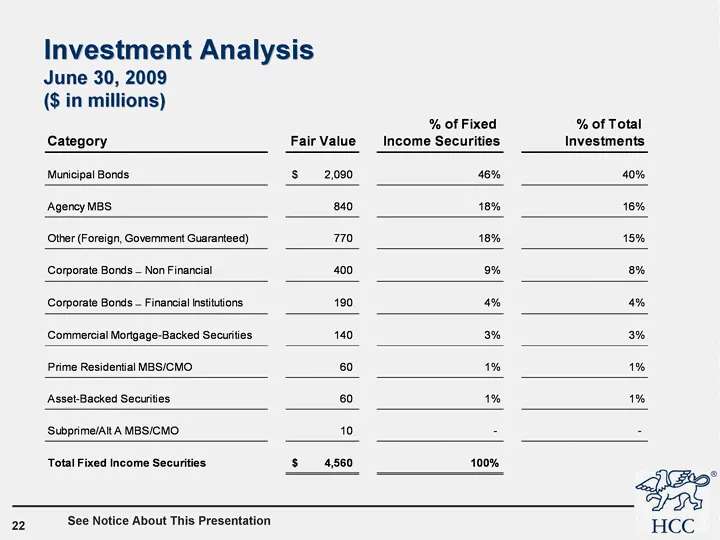
Slide 22: Investment Analysis
Investment Analysis June 30, 2009 ($ in millions) See Notice About This Presentation
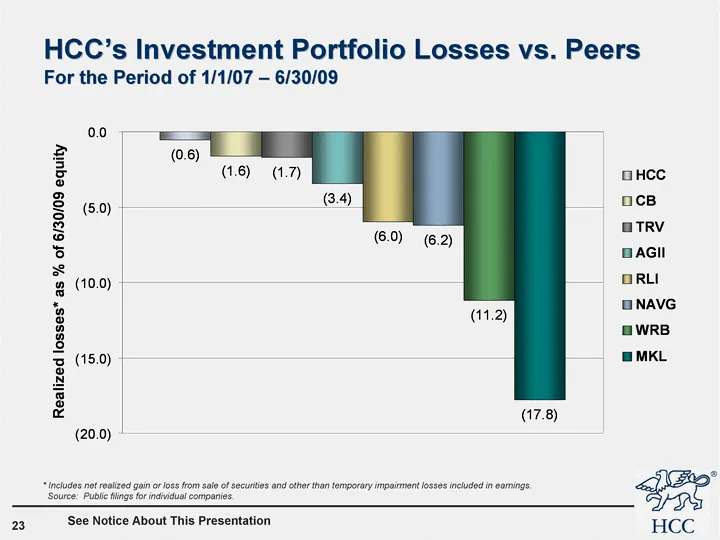
Slide 23: HCC's Investment Portfolio Losses vs. Peers
* Includes net realized gain or loss from sale of securities and other than temporary impairment losses included in earnings. Source: Public filings for individual companies. HCC's Investment Portfolio Losses vs. Peers For the Period of 1/1/07 - 6/30/09 See Notice About This Presentation
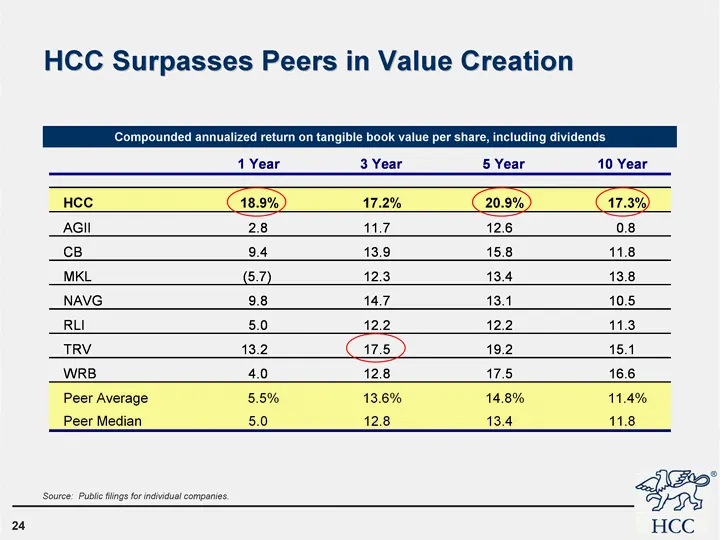
Slide 24: HCC Surpasses Peers in Value Creation
HCC Surpasses Peers in Value Creation Source: Public filings for individual companies. Compounded annualized return on tangible book value per share, including dividends Compounded annualized return on tangible book value per share, including dividends
Slide 25: HCC is Well Positioned to Pursue New Opportunities
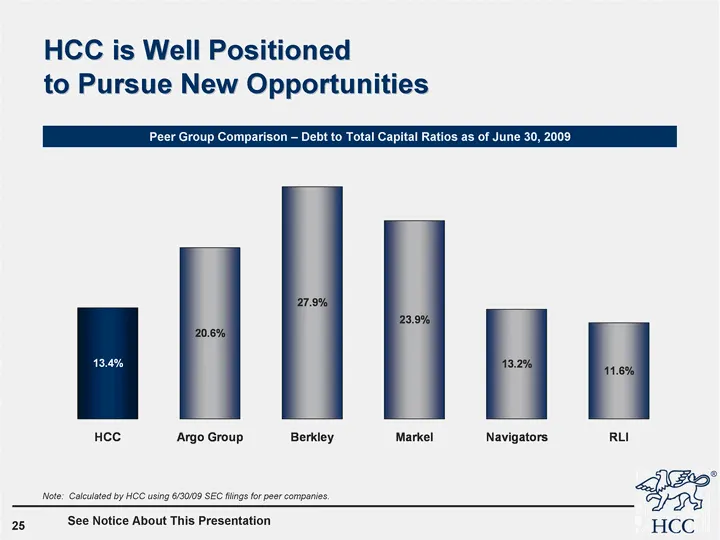
HCC Argo Group Berkley Markel Navigators RLI Debt to Equity 0.134 0.206 0.279 0.239 0.132 0.116 HCC is Well Positioned to Pursue New Opportunities Peer Group Comparison - Debt to Total Capital Ratios as of June 30, 2009 See Notice About This Presentation Note: Calculated by HCC using 6/30/09 SEC fil
Slide 26: Summary of Strengths
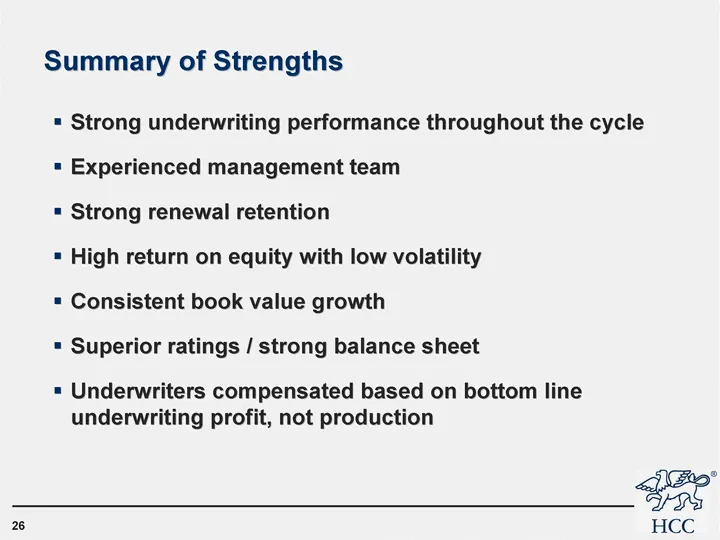
Summary of Strengths Strong underwriting performance throughout the cycle Experienced management team Strong renewal retention High return on equity with low volatility Consistent book value growth Superior ratings / strong balance sheet Underwriters compensated based on bottom line underwriting pro
Slide 27: Appendix
Appendix HCC
Slide 28: Financial Highlights
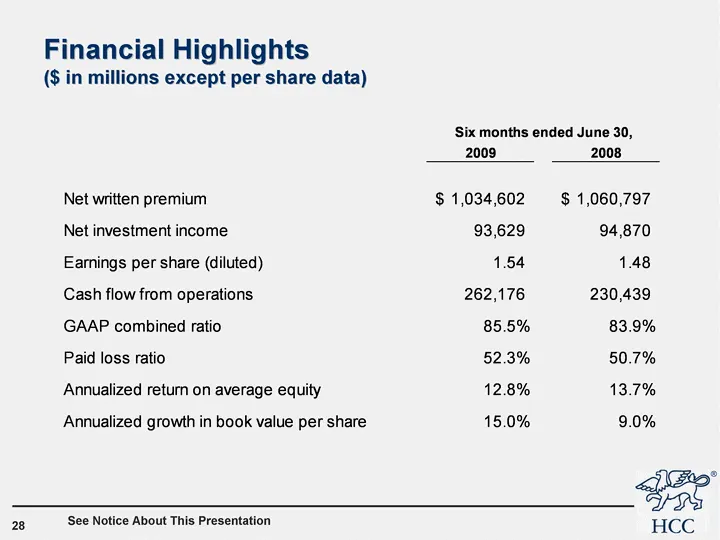
Financial Highlights ($ in millions except per share data) See Notice About This Presentation
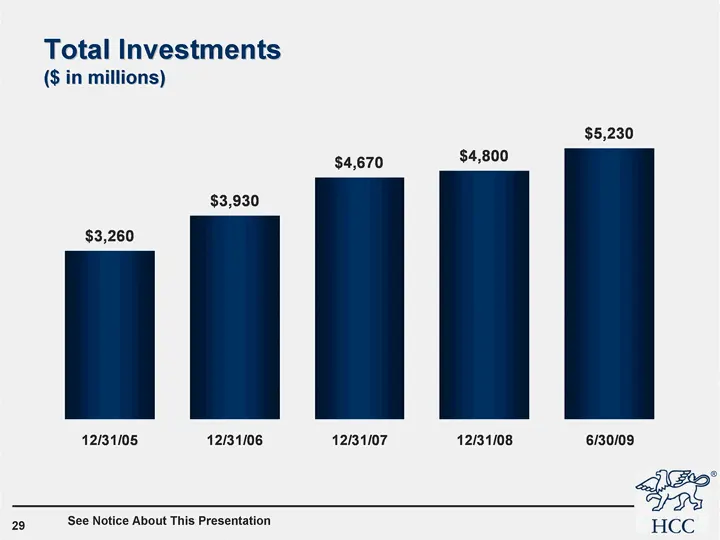
Slide 29: Total Investments
Total Investments ($ in millions) 2003 2004 38717 12/31/2006 12/31/2007 12/31/2008 6/30/2009 Investment Assets 1710 2470 3260 3930 4670 4800 5230 See Notice About This Presentation
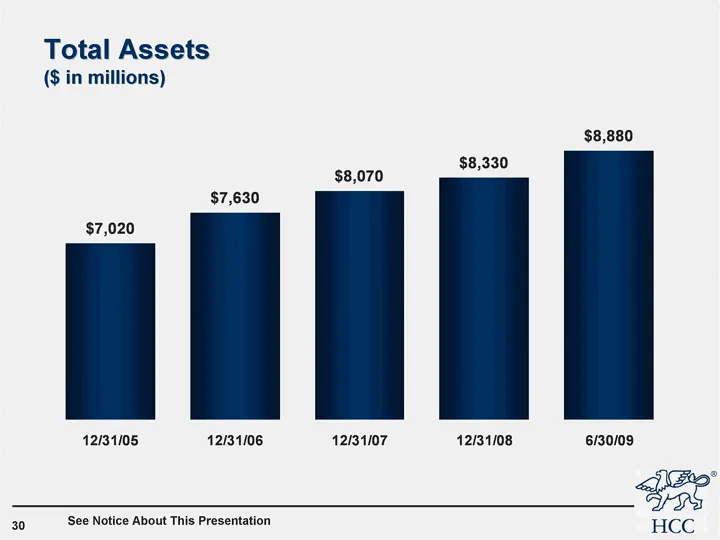
Slide 30: Total Assets
Total Assets ($ in millions) 2003 2004 38717 12/31/2006 12/31/2007 12/31/2008 6/30/2009 Total Assets 4900 5900 7020 7630 8070 8330 8880 See Notice About This Presentation
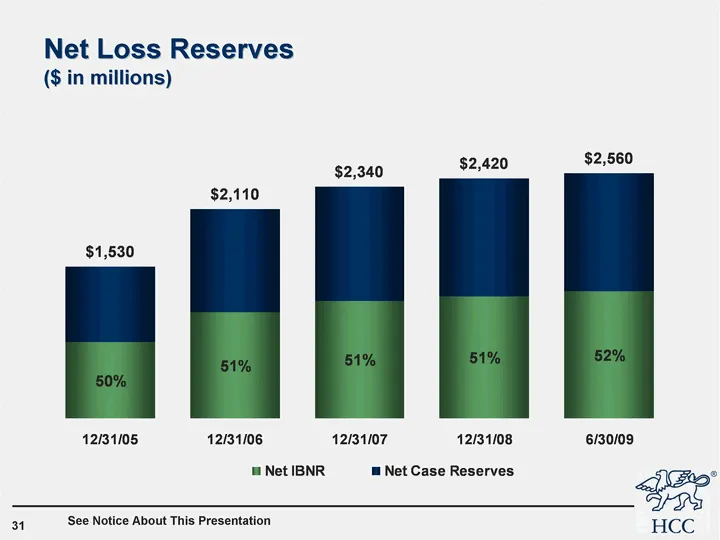
Slide 31: Net Loss Reserves
Net Loss Reserves ($ in millions) 2003 2004 12/31/05 12/31/2006 12/31/2007 12/31/2008 6/30/2009 Net IBNR 516 768 1073 1187 1230 1284 See Notice About This Presentation
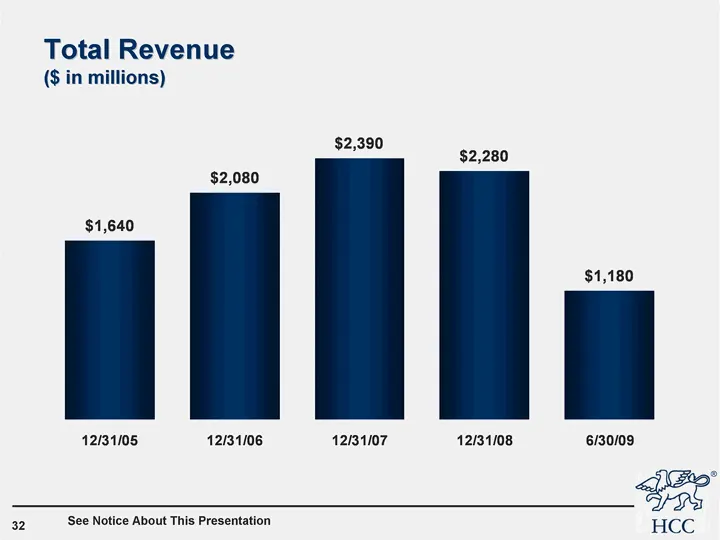
Slide 32: Total Revenue
Total Revenue ($ in millions) 2003 2004 12/31/05 12/31/2006 12/31/2007 12/31/2008 6/30/2009 Total Revenur 940 1280 1640 2080 2390 2280 1180 See Notice About This Presentation
Slide 33: Net Earnings
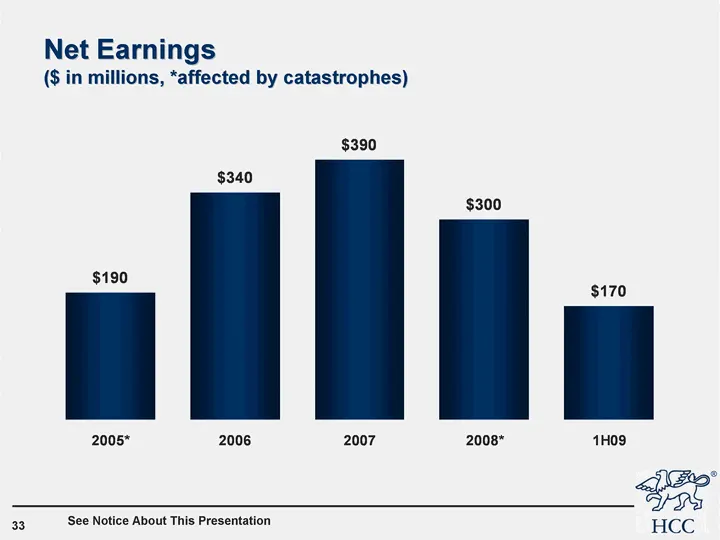
Net Earnings ($ in millions, *affected by catastrophes) 2003 2004* 2005* 2006 2007 2008* 1H09 Net Earnings 142 163 190 340 390 300 170 See Notice About This Presentation
Slide 34: Operating Cash Flow
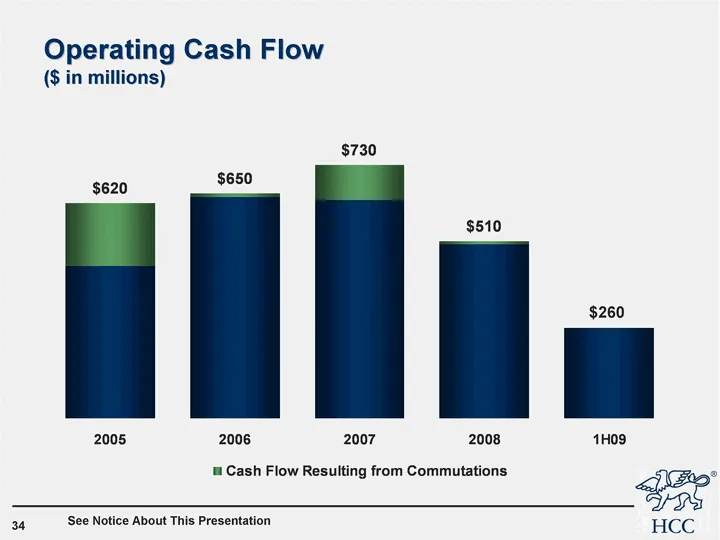
Operating Cash Flow ($ in millions) 2003 2004 2005 2006 2007 2008 1H09 $260 See Notice About This Presentation
Slide 35: Subprime Liability Exposure
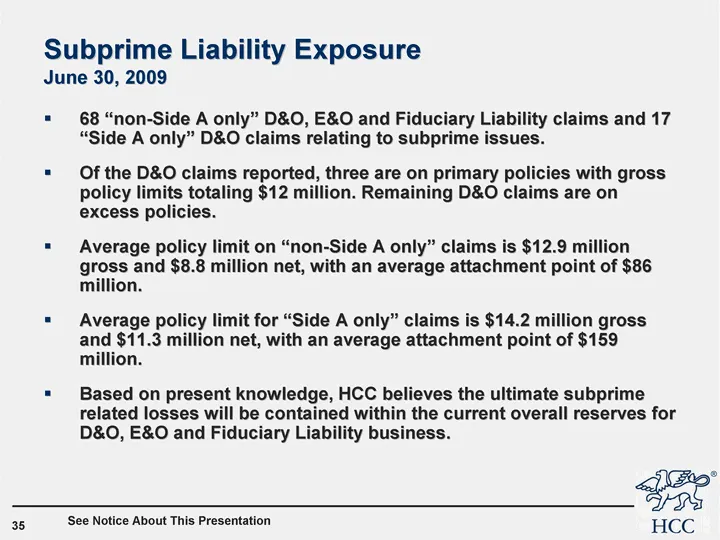
Subprime Liability Exposure June 30, 2009 68 "non-Side A only" D&O, E&O and Fiduciary Liability claims and 17 "Side A only" D&O claims relating to subprime issues. Of the D&O claims reported, three are on primary policies with gross policy limits totaling $12 million. Remaining D&O claims are on exc
Slide 36: Experienced Management Team
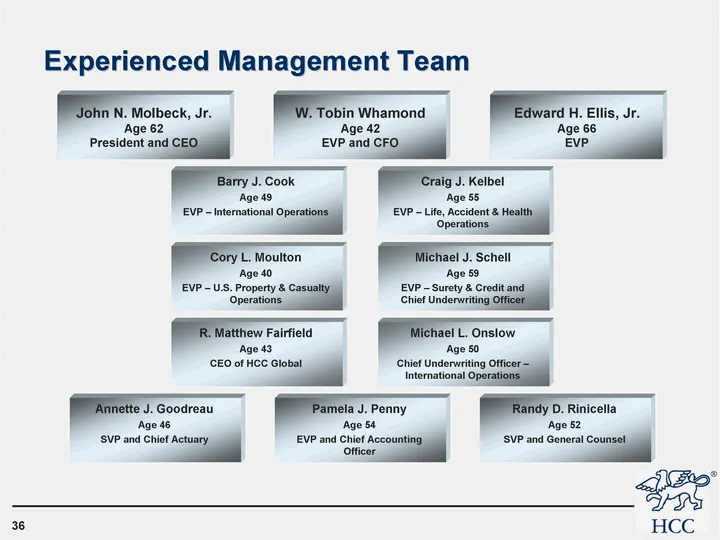
Experienced Management Team Pamela J. Penny Age 54 EVP and Chief Accounting Officer Randy D. Rinicella Age 52 SVP and General Counsel Barry J. Cook Age 49 EVP - International Operations Michael J. Schell Age 59 EVP - Surety & Credit and Chief Underwriting Officer Cory L. Moulton Age 40 EVP - U.S. Pr
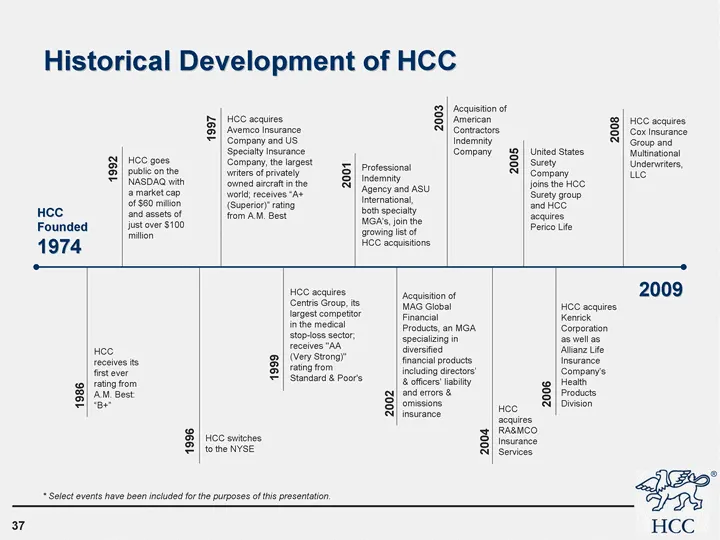
Slide 37: Historical Development of HCC
Historical Development of HCC HCC Founded 1974 2009 HCC receives its first ever rating from A.M. Best: "B+" HCC goes public on the NASDAQ with a market cap of $60 million and assets of just over $100 million HCC switches to the NYSE HCC acquires Avemco Insurance Company and US Specialty Insurance Co
Source: SEC EDGAR · 8-K filed Sep 29, 2009
More decks from HCC Insurance Holdings Inc
 Q2 2015 Earnings Presentation31 slides · Aug 14, 2015
 Merger or Acquisition (June 2015)22 slides · Jun 23, 2015
 Merger or Acquisition (June 2015)10 slides · Jun 10, 2015
 Merger or Acquisition (June 2015)30 slides · Jun 10, 2015
 Q1 2015 Earnings Presentation35 slides · May 21, 2015
 36th Annual Raymond James Institutional Investors Conference (February 2015)36 slides · Feb 27, 2015