Palmetto Bancshares — Shareholder Meeting (May 2012)
35 slides from Palmetto Bancshares's shareholder meeting presentation, May 18, 2012
Slide 1: Annual Meeting of Shareholders
Annual Meeting of Shareholders May 17, 2012 Exhibit 99.1

Slide 2: Informational Update to Shareholders: Mike Glenn, Chairman
Informational Update to Shareholders: Mike Glenn, Chairman of the Board
Slide 3: Trait #1: Leadership
Trait #1: Leadership • CEOs are highly skilled managers – Who are backed by knowledgeable and engaged boards • These CEOs are leaders – Who understand their markets, their strategies and what it takes to be successful – Are strategists who can execute
Slide 4: Trait #2: Sustainable Strategies
Trait #2: Sustainable Strategies • The banks employ strategies that: – Avoid activities that entail excessive risk: for example, commercial real estate concentrations or high-risk residential mortgages (sub-prime) – Escape the wasting effects of commoditization: low-margin and plain vanilla products
Slide 5: Trait #3: Organizational Clarity
Trait #3: Organizational Clarity • From the Board flowing through the bank, all have a shared sense of what it takes to be successful • The Board and senior management are fully aligned on strategy – And management understands what levers to pull to deliver optimal performance
Slide 6: Informational Update to Shareholders: Sam Erwin, CEO
Informational Update to Shareholders: Sam Erwin, Chief Executive Officer Lee Dixon, Chief Operating and Chief Risk Officer
Slide 7: Industry, Economic and Market Context
Industry, Economic and Market Context
Slide 8: The Palmetto Bank: 2011 in Review and 2012 Outlook
The Palmetto Bank: 2011 in Review and 2012 Outlook
Slide 9: 2011 in Review: Retail
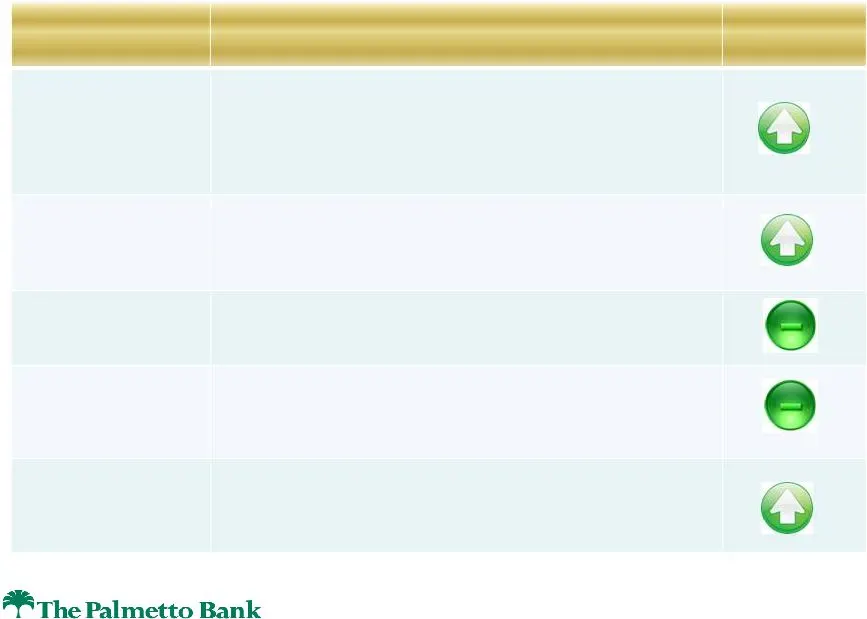
Strategic Initiative Results (2011 vs. 2010) Change from 2010 Branch Loan Growth Production up 66% over 2010 ($24.5 million vs. $14.8 million) Began to outpace runoff Core Deposit Growth Grew core deposits over $37 million ($666 million vs. $629 million) Fee Income Growth Flat growth ($16.8 million
Slide 10: 2011 in Review: Commercial
Strategic Initiative Results (2011 vs. 2010) Change from 2010 Commercial Loan Portfolio 6% decrease ($549 million vs. $583 million) New Loan Production Documented Calls 395% increase ($109 million vs. $22 million) Intentional effort to grow business (2,949 vs. 0 in 2010) Treasury Deposits 1.8% incre
Slide 11: 2011 in Review: Wealth Management
Strategic Initiative Results (2011 vs. 2010) Change from 2010 Trust Asset Growth Assets up $18 million (7% increase) Trust Account Growth Grew number of accounts 39 (5% increase) Trust Net Income Growth Net income increase (22.8% increase) Brokerage Asset Growth Assets down $851 thousand (5% decreas
Slide 12: AB the Palmetto Bank
AB the Palmetto Bank
Slide 13: Evolution of Big Picture Strategic Focus
Evolution of Big Picture Strategic Focus • – Quantify depth of credit loss hole – Strategic Project Plan to survive and thrive – Prepare for regulatory agreement • – Raise capital – Process improvement – Change management • – Performance culture and talent management – Operating earnings – Client fo
Slide 14: 2012 Strategic Priorities
2012 Strategic Priorities
Slide 15: 2012 Strategic Priorities
2012 Strategic Priorities 1. Return to profitability 2. Improve asset quality 3. Exit regulatory agreement 4. Execute on client service and support through Palmetto Partnership 5. Develop a high performing culture and winning team Control our own destiny and earn the right to keep doing it our way!
Slide 16: 1. Return to Profitability
1. Return to Profitability
Slide 17: ‘0% 3.0% 3.0% 29% 20% 150% 100% 050% 0% 36% raza ram 302m) ra200
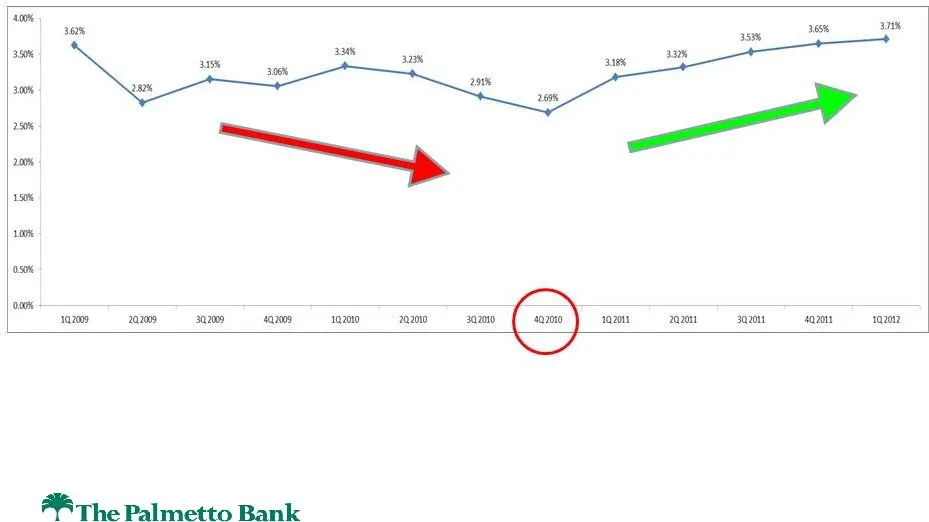
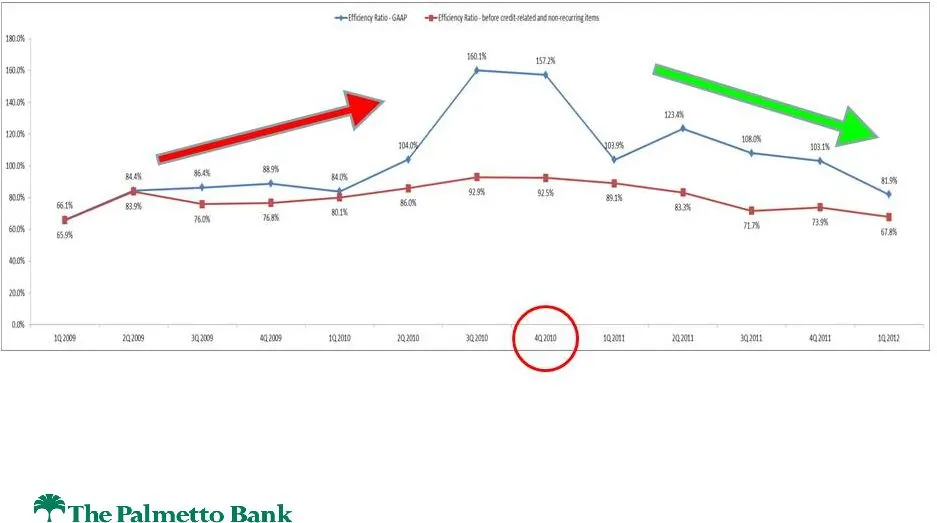
‘0% 3.0% 3.0% 29% 20% 150% 100% 050% 0% 36% raza ram 302m) ra200 2a200 sa200 sa20 raz saz 365% az unk 020% AB The Palmetto Bank
Slide 18: am a aaa ams
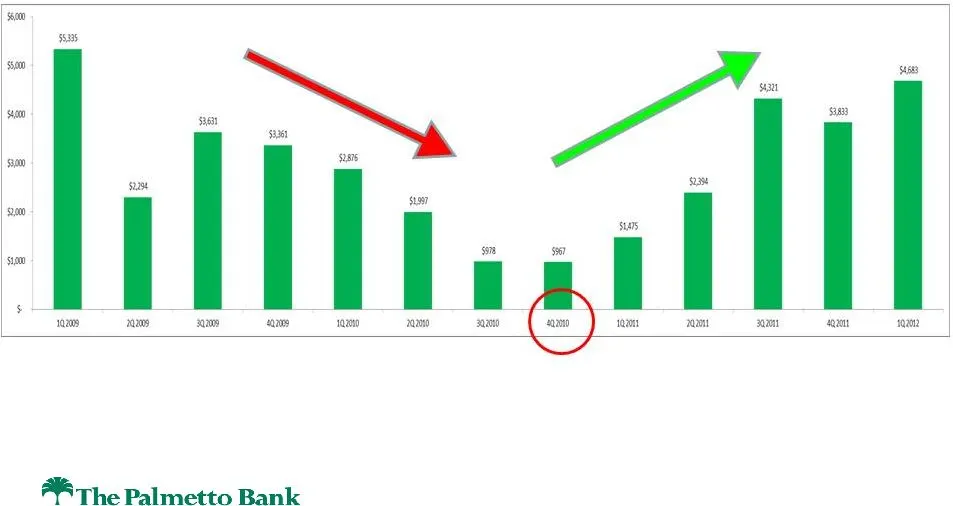
3% ow on am a aaa ams ito GP eben te bee cnt ies was 19% aan nao sox om em m1 sum om ox vem AB The Palmetto Bank
Slide 19: ea sm
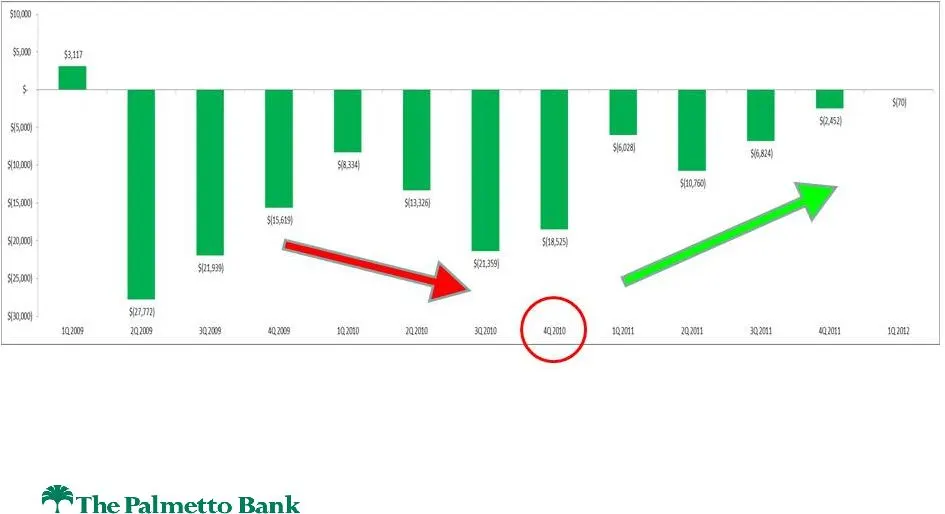
8 | | ea sm ry j | om nem sa Bod se [ j am 10m am xm 2m bod 5 ‘0 AB The Palmetto Bank xm am am
Slide 20: sui
sui seam susan spa pod som am om rom am om sea om xem am som ‘om AB The Palmetto Bank
Slide 21: Return to Profitability
Return to Profitability • $6.2 million of annual expense Savings through Automation, Vendor management and Efficiency • Asset-liability management and Internal Audit co- sourcing began January 1 • Branches: – Two consolidations completed on March 30 – Two sales targeted to close in the second quarte
Slide 22: 2. Improve Asset Quality
2. Improve Asset Quality
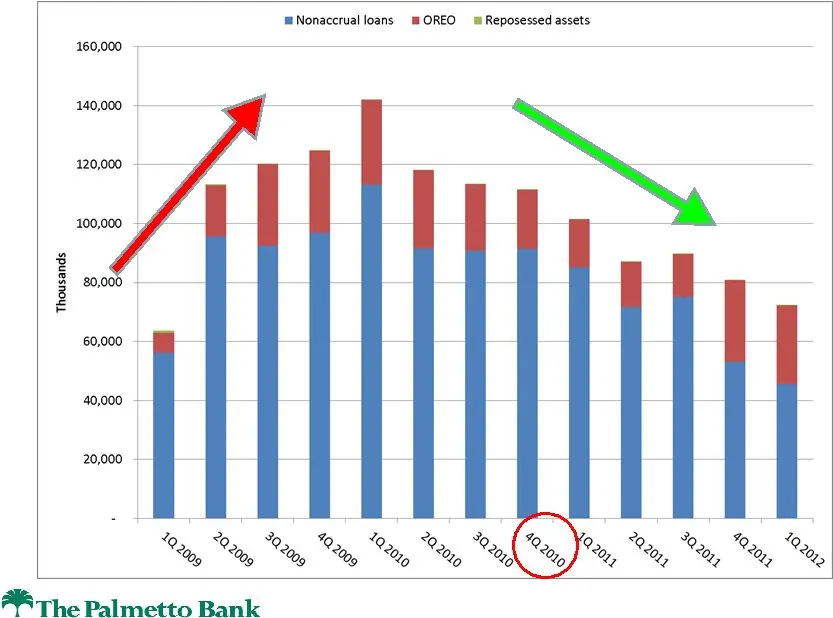
Slide 23: Nonaccrual loans and repossessed assets
m= Nonaccrual loans: MOREO m Reposessed assets 160,000 ‘Thousands 60,000 40,000 20,000 7 - - %, eo °e, i %, ‘Xe %> % x i, 2. Q. "2. ey my "eg AB The Palmetto Bank
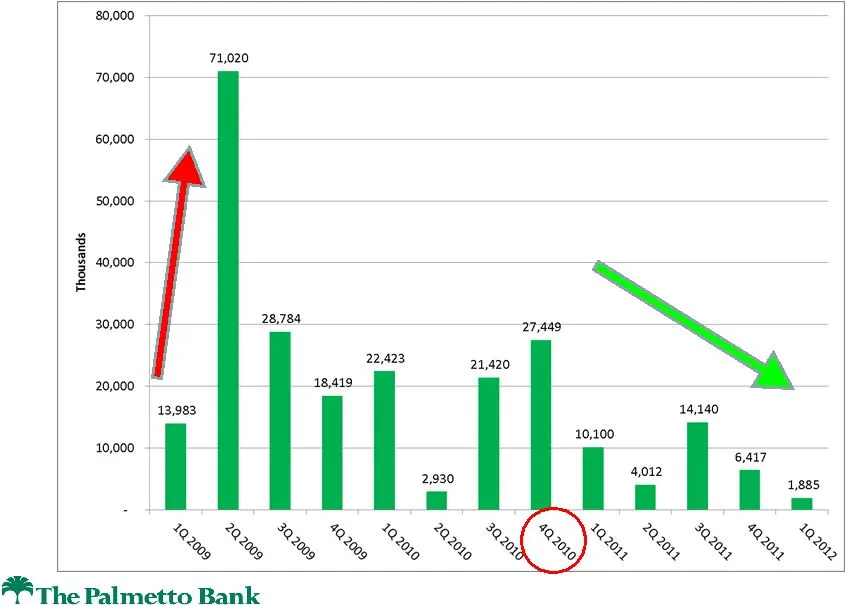
Slide 24: Nonaccrual Loans - Gross Additions
Nonaccrual Loans - Gross Additions
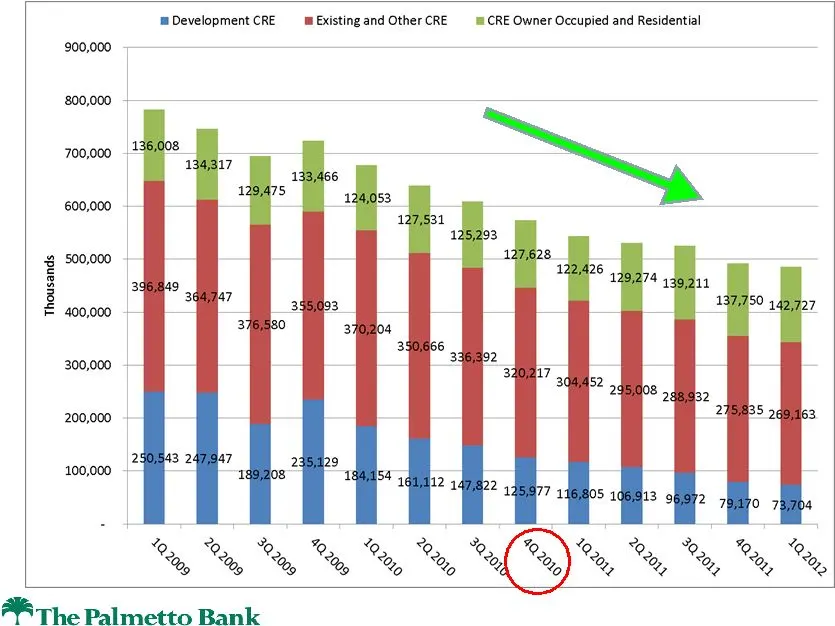
Slide 25: Commercial Real Estate Loans
Commercial Real Estate Loans
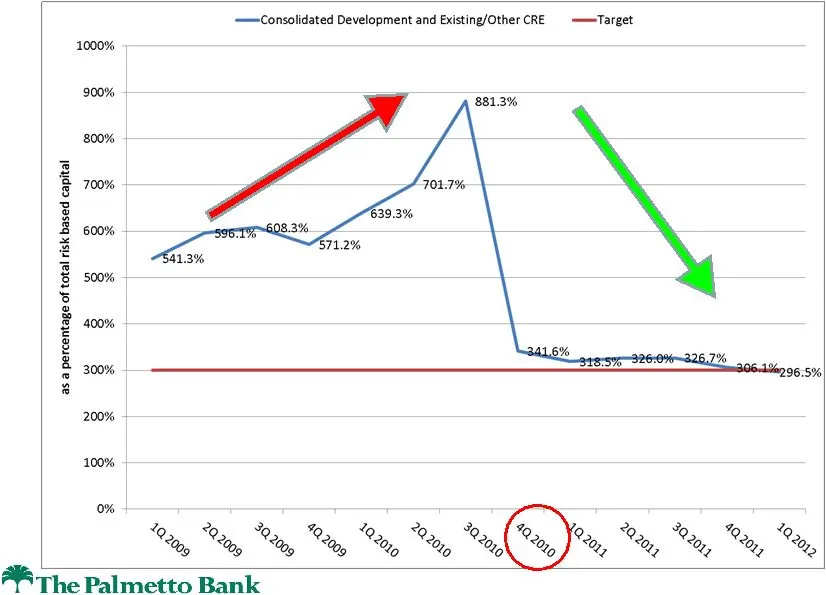
Slide 26: Commercial Real Estate Loans as a Percentage of Total Risk Based Capital
Commercial Real Estate Loans as a Percentage of Total Risk Based Capital
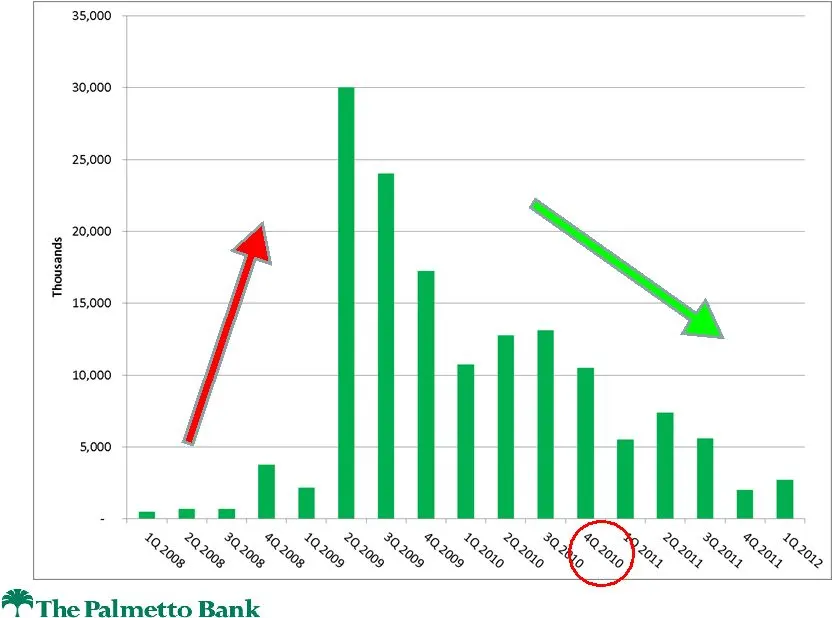
Slide 27: ‘Thousands
35,000 30,000 25,000 20,000 ‘Thousands 15,000 10,000 5,000 / | %, aaah ay ay ay Q. ay Me, AB The Palmetto Bank

Slide 28: 3. Exit Regulatory Agreement
3. Exit Regulatory Agreement

Slide 29: 4. Execute on Client Service and Support through Palmetto Partnership
4. Execute on Client Service and Support through Palmetto Partnership
Slide 30: The Path To Profitability!
The Path To Profitability! Project SAVE The Palmetto Partnership Profitability Driven by... Executing Clients
Slide 31: Technology Upgrades to Meet Client Expectations: Second Quarter
Technology Upgrades to Meet Client Expectations: Second Quarter Upgraded ATM fleet, locations and capability March Upgraded Telephone Automatic Voice Response Unit May Upgraded Remote Deposit Capture May Upgraded Real Time Internet Banking May Upgraded E-Statement System May New Mobile Friendly Web
Slide 32: Technology Upgrades to Meet Client Expectations: Third Quarter
Technology Upgrades to Meet Client Expectations: Third Quarter New Lockbox System July New Person to Person Payments July New Online Personal Finance System July Upgraded Web Site July New Commercial Positive Pay September New ACH Fraud Control September New Electronic Check Recovery September

Slide 33: 5. Develop a High Performing Culture and Winning Team
5. Develop a High Performing Culture and Winning Team
Slide 34: Critical Elements of Our Evolving Culture
Critical Elements of Our Evolving Culture 1. Continuous improvement culture (including possibility thinking “out of the red box”, automation, and expense consciousness) 2. Client service and support culture Palmetto Partnership 3. Performance culture (personally and corporately) 4. Winning culture!

Slide 35: AB the Palmetto Bank
AB the Palmetto Bank
Source: SEC EDGAR · 8-K filed May 18, 2012
More decks from Palmetto Bancshares Inc
 Merger or Acquisition (August 2015)17 slides · Aug 12, 2015
 Shareholder Meeting (May 2015)28 slides · May 21, 2015
 Merger or Acquisition (April 2015)15 slides · Apr 22, 2015
 Investor Presentation (September 2014)25 slides · Sep 15, 2014
 Investor Presentation (June 2014)24 slides · Jun 24, 2014
 Shareholder Meeting (May 2014)26 slides · May 15, 2014