Whitney — Gulf South Bank Conference 2008
30 slides from Whitney's conference presentation, May 1, 2008
Slide 1: Gulf South Bank Conference
John M. Turner, Jr. President Thomas L. Callicutt, Jr. EVP & CFO Lewis P. Rogers EVP Credit Administration Gulf South Bank Conference May 1, 2008 New Orleans, LA
Slide 2: Thomas L. Callicutt, Jr., Chief Financial Officer
Thomas L. Callicutt, Jr. Chief Financial Officer
Slide 3: Forward-Looking Statements
Forward-Looking Statements This presentation may include forward-looking statements containing expectations about future conditions and descriptions of future plans and strategies. Whitney's ability to accurately predict the effects of future plans or strategies is inherently limited such that actua
Slide 4: Whitney Today
Whitney Today § Whitney today is a very good, sound bank § Difficult operating environment § Credit § NIM § Strong balance sheet and solid capital position § Cost control programs that are part of our strategic review process are expected to benefit expense levels § Geographic diversification has he
Slide 5: 1Q08 Earnings
1Q08 Earnings 1Q08 4Q07 (Period-end) Total Assets $10.8B $11.0B Total Loans $7.7B $7.6B Total Deposits $8.3B $8.6B Net Income $29.9MM $30.2MM E.P.S. (diluted) $.45 $.45 • Net income $30 million • Earnings per share (diluted) $.45 • Results include: – A $2.3 million gain from the VISA IPO – A $1.4 mi
Slide 6: Net Interest Margin - Asset Sensitive
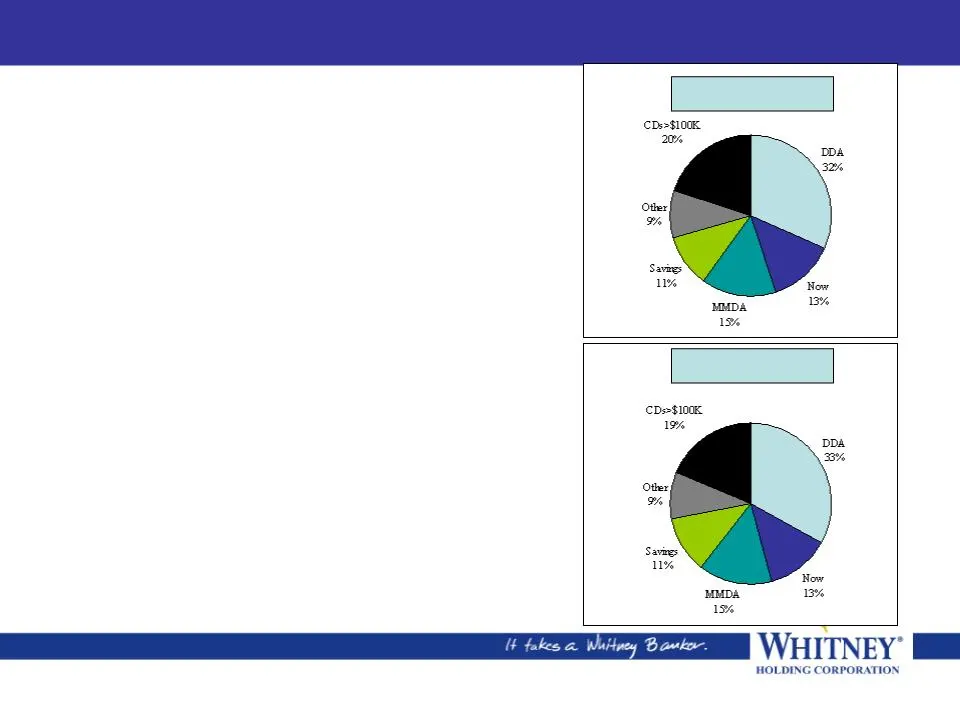
Net Interest Margin - Asset Sensitive * NIM remains near the top of the peer group * Active management of loan and deposit pricing * Liquidity in the deposit base * Moderately asset-sensitive * Loan portfolio - 54% variable rate – (29% tied to Libor; 25% tied to Prime) * Benefiting from wider Prime/
Slide 7: Diversified By Geography
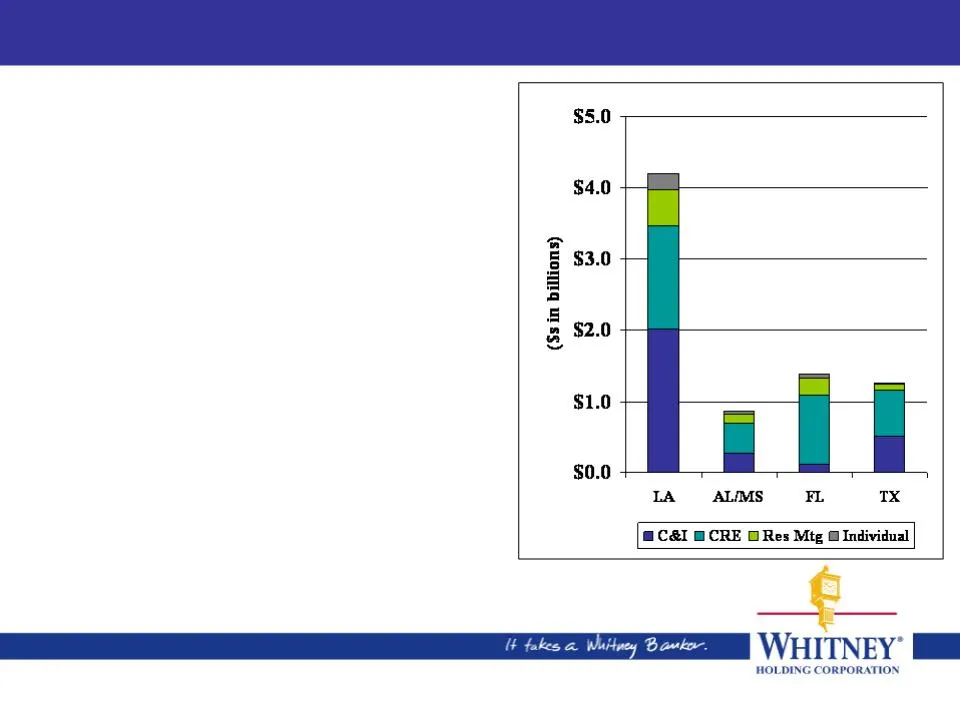
Diversified By Geography Total Loans $7.7 billion – 37% serviced in metro New Orleans – 18% serviced in southwest LA – 18% serviced in Florida • 7% serviced from the panhandle • 11% serviced from the Tampa Bay metro area – 16% serviced in Houston – 11% serviced in Alabama/Mississippi – Loan growth s
Slide 8: Cost Control and Efficiencies
Cost Control and Efficiencies Total Noninterest Expense $83.9 $85.8 $86.4 § Whitney’s strategic focus requires that we address process inefficiencies and improve automation in priority areas § Normalized expenses down 2% from 1Q07 § Strategic investments § Opened new offices § Offered additional pro
Slide 9: Sound Capital Levels
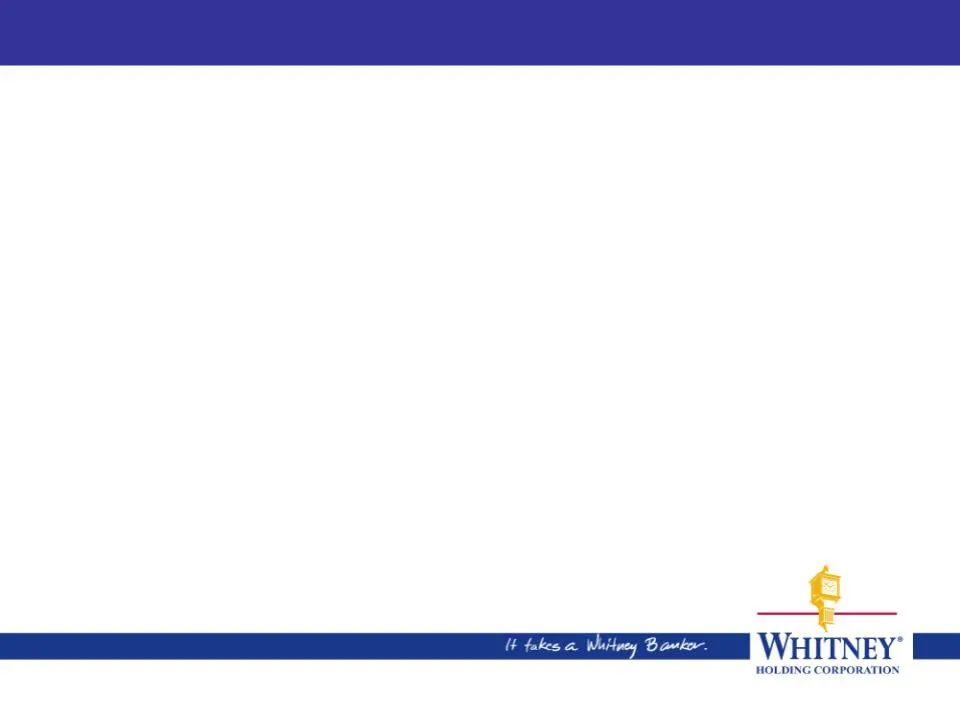
Sound Capital Levels 3/31/08 12/31/07 3/31/07 Equity to Assets 11.39% 11.73% 11.30% Tangible Equity to Assets 8.32% 8.24% 8.22% Tier I Leverage 8.45% 8.79% 9.02%
Slide 10: A Strong Monitoring Process Is Key
A Strong Monitoring Process Is Key One of our core strengths is understanding and managing credit risk – Seasoned, well understood credit culture – Consistent application and monitoring of standards throughout the Company – Multiple controls within our credit culture – An independent credit review f
Slide 11: Adequately Reserved For Inherent Loss
Adequately Reserved For Inherent Loss • Methodology for determining the allowance is a consistent process – Important factors are re-evaluated quarterly to respond to changing conditions • Allowance encompasses three elements – Allowances established for losses on criticized loans – Allowances based
Slide 12: Lewis P. Rogers, EVP, Credit Administration
Lewis P. Rogers EVP, Credit Administration
Slide 13: Commercial and Business Banking Focus
Commercial and Business Banking Focus • Commercial portfolio 83% – 46% CRE – 37.5% C&I • Consumer portfolio 17% – 12% Residential RE – 4% Individual • No Indirect portfolio • No meaningful exposure to subprime home mortgage loans • Minimal Credit Card portfolio – $44 million • Oil & gas approximatel
Slide 14: Commercial Real Estate Diversified
Commercial Real Estate Diversified Total CRE $1,437.6 $441.9 $991.1 $662.3 $3,533.0 ($s in millions) LA AL/MS FL TX Total Residential Construction 81.8 42.4 69.9 85.1 $279.2 Commercial construction, land & land development 419.3 224.9 426.9 355.3 $1,426.5 Owner- occupied CRE 459.1 70.6 176.4 87.1 $7
Slide 15: Florida Loan Portfolio Facts
Florida Loan Portfolio Facts • Total portfolio approximately $1.4 billion – Approximately $540 million in panhandle – Approximately $850 million in Tampa Bay area • CRE portfolio totals $991 million – Residential construction $70 million • Lot loans = 12% of total FL portfolio • Undeveloped land loa
Slide 16: Prompt Identification of Problem Loans
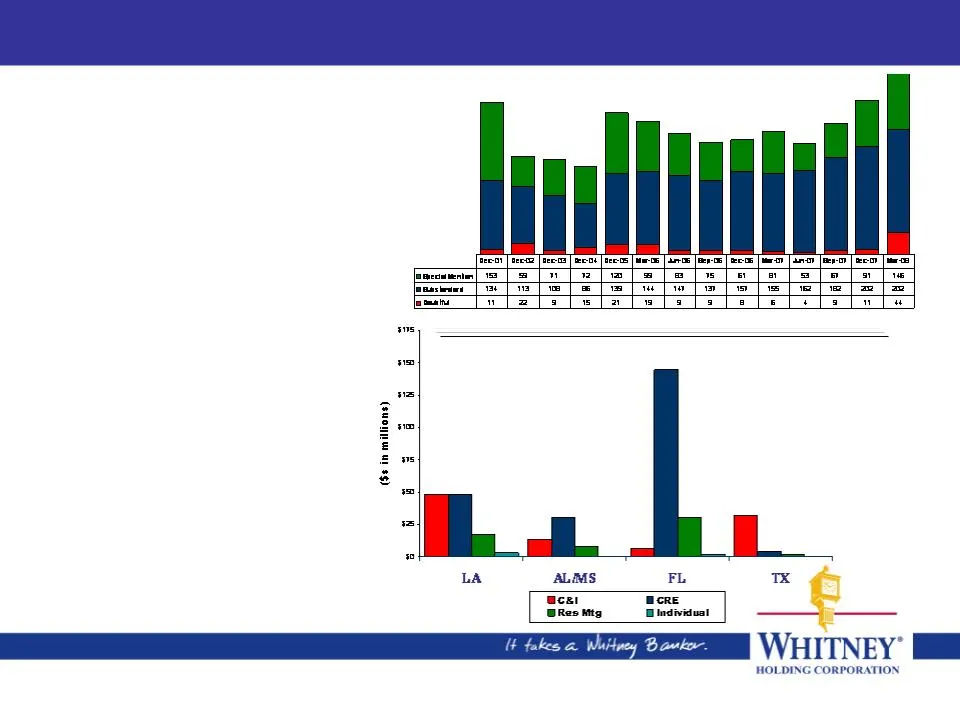
Prompt Identification of Problem Loans • Prompt identification of problem loans leads to increased level of downgrades, criticized and nonperforming loans • 5% of total loans are criticized – 13% of FL loans are criticized • Approximately 1/3 rd of the criticized are lots and undeveloped land – 6% A
Slide 17: Thorough Workout Process
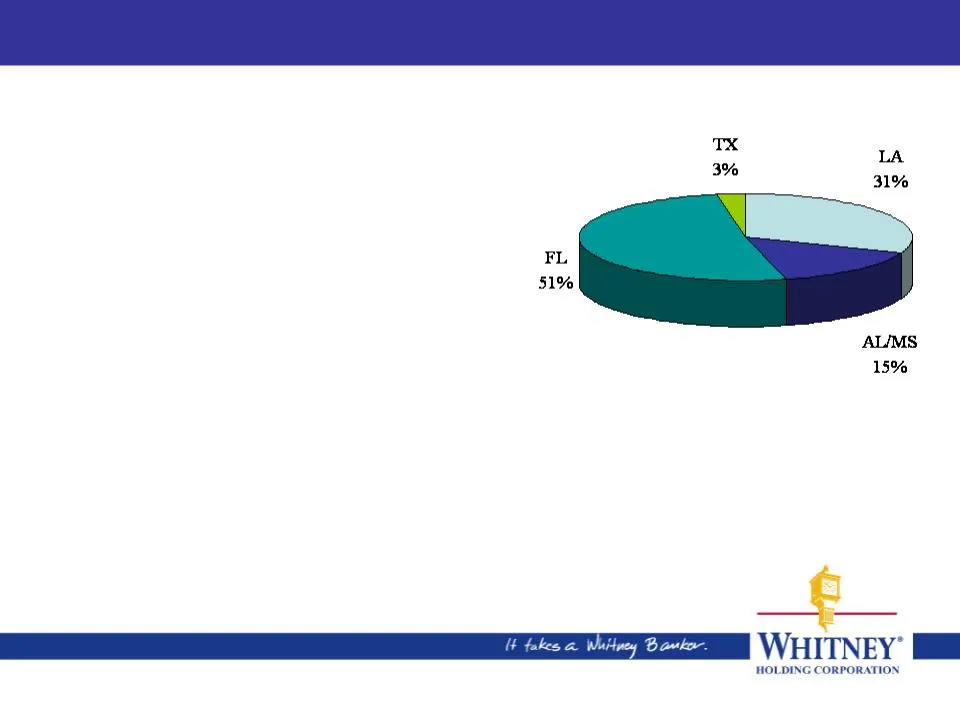
Thorough Workout Process • NPAs = $151 million at 3/31/08 – NPLs = $139 million – ORE = $12 million • Handful of larger loans can significantly impact our ratios – NPA ratio 1.96% – Reserve coverage ratio .66% • Approximately half of NPLs from Florida • 4 larger credits have impacted NPLs since 6/30
Slide 18: All Florida Portfolios Are Not The Same
All Florida Portfolios Are Not The Same • All Florida portfolios are not the same – Underwriting standards vary – Relationship banking is our focus • All Florida loans are not troubled – 87% of our Florida portfolio is not criticized • All loans in Florida were not made at 100% LTV • All Florida loa
Slide 19: Historical Trend: Healthy Level of Recoveries
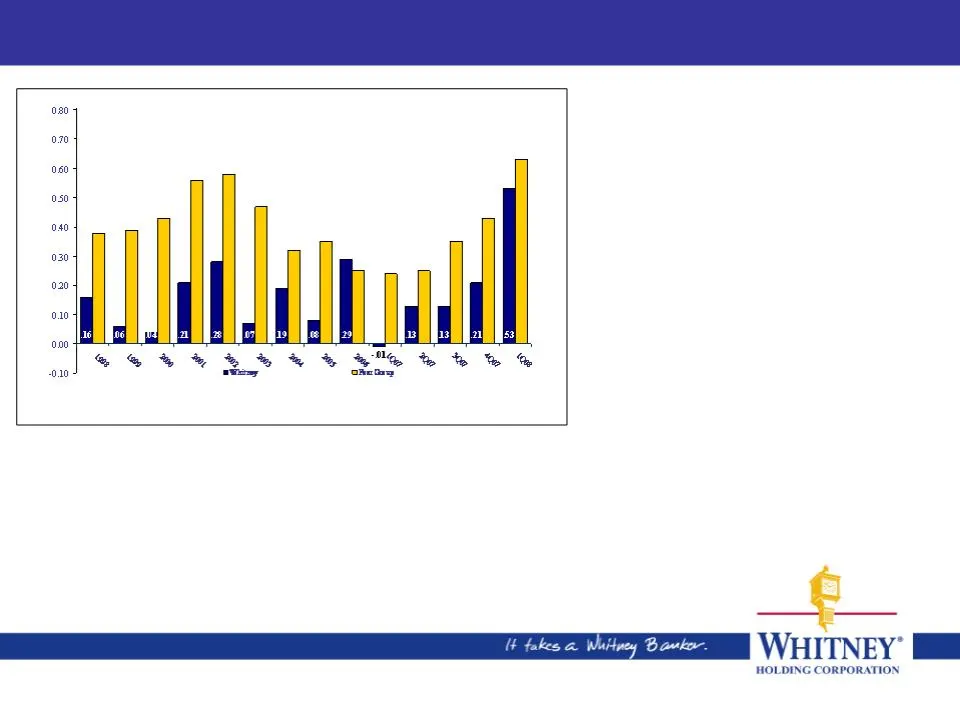
Historical Trend: Healthy Level of Recoveries Percent Net Charge-offs to Average Loans • Higher level in 1Q08 as we took charge- offs for some of the inherent losses we reserved for in earlier periods • Net charge-offs historically at or below peer levels given a higher level of recoveries
Slide 20: John M. Turner, Jr., President
John M. Turner, Jr. President
Slide 21: A Renewed Strategic Vision
A Renewed Strategic Vision Updated our Strategic Plan Reviewed and challenged: Where we’ve been Where we are today Where we believe Whitney should go Mission Statement Guiding Principles
Slide 22: Whitney's Mission Will Not Change
Whitney’s Mission Will Not Change OUR MISSION IS TO DELIVER EXTRAORDINARY VALUE AND SERVICE , ALONG WITH SUPERIOR RESULTS, TO OUR CUSTOMERS AND SHAREHOLDERS WHILE PROVIDING LEADERSHIP TO OUR LOCAL COMMUNITIES AND OUTSTANDING CAREER OPPORTUNITIES TO OUR VALUED EMPLOYEES.
Slide 23: Whitney's Guiding Principles Will Not Change
Whitney’s Guiding Principles Will Not Change • Soundness - This ensures our continuity and promotes the trust of our customers, shareholders and communities. • Profitability - We focus on profitability, since it is not only a gauge of our success, but ensures that we will have the capital we need to
Slide 24: Acquisitions Are Important To Our Growth
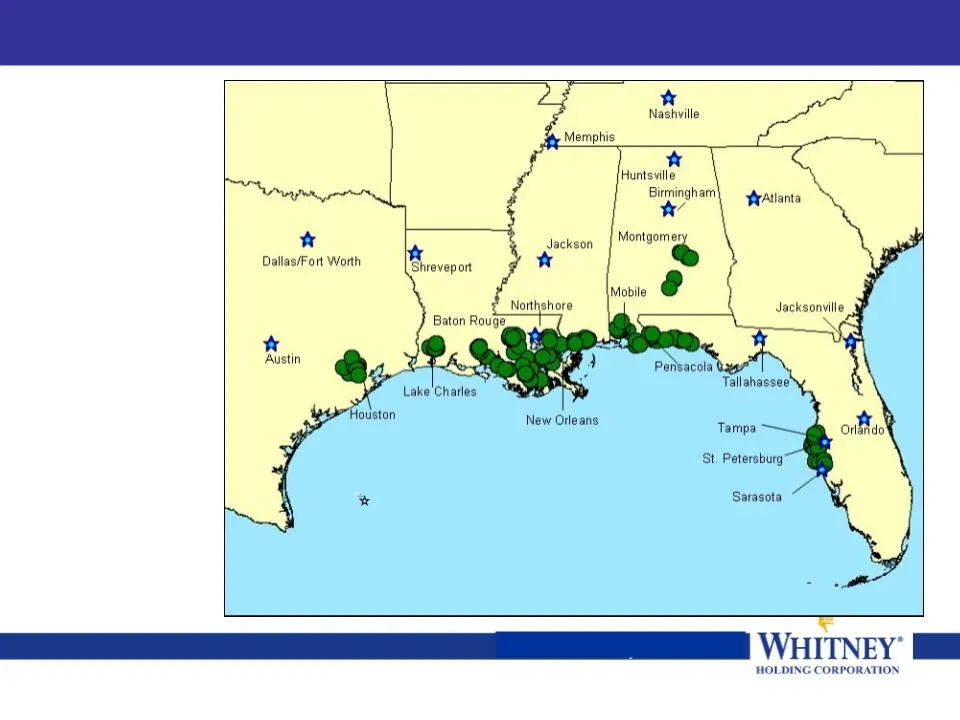
Acquisitions Are Important To Our Growth § I-10/Gulf Coast Strategy has served Whitney well § It is now time to move on to the next phase of our acquisition strategy § We will emphasize markets in larger cities from Texas throughout the southeast Represent possible future Whitney expansion
Slide 25: Benefits Of Our Expansion Efforts
Benefits Of Our Expansion Efforts • Growth markets in Houston and southwest Louisiana “offset” stressed markets in Florida • Growth in 1Q08 came mainly from Houston, however all pipelines look good • Outlook for Houston, southwest Louisiana and south Alabama is positive • Greater New Orleans economy
Slide 26: Leveraging Hometown Opportunities
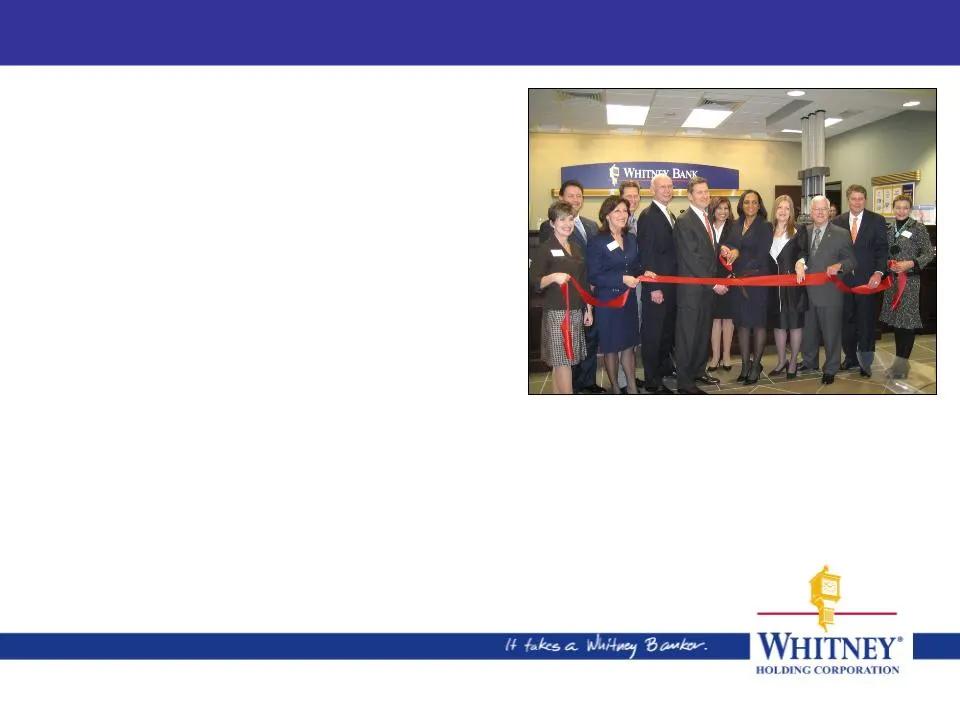
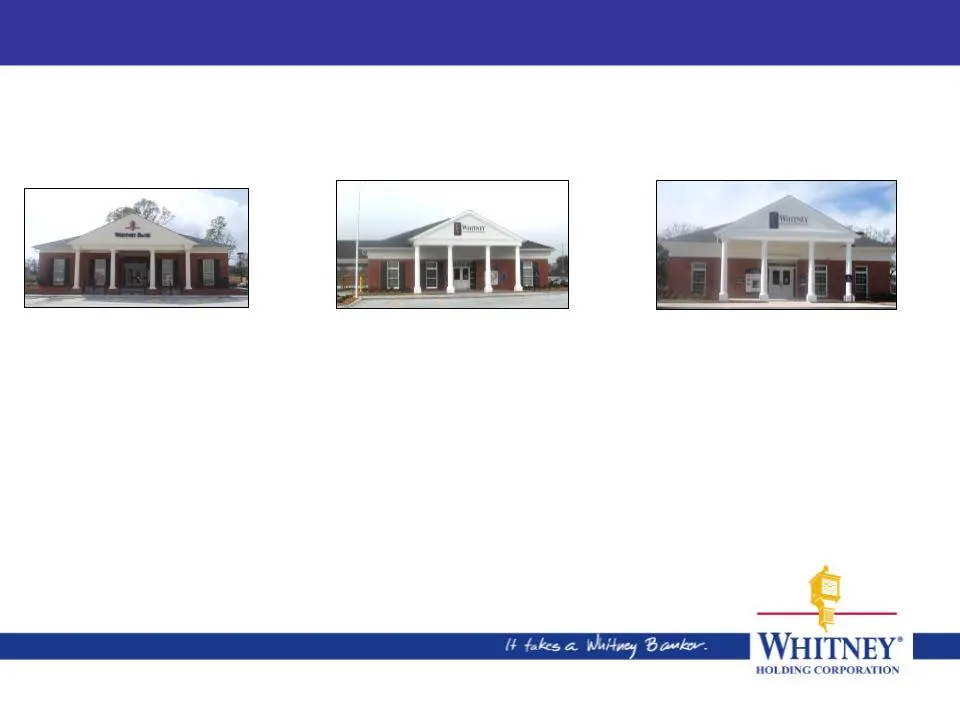
Leveraging Hometown Opportunities • Opened 3 new offices • Striving for increased market share • Refocusing on our roots Marrero Hammond LaPlace
Slide 27: Focus & Discipline: A Key To Continued Success
Focus & Discipline: A Key To Continued Success • Focus on segmentation – Commercial & Business Banking • Continued geographic diversification • Balance sheet management • Focus on growing fee income • Credit remains a core strength • Capital management • Reduction of expenses
Slide 28: Whitney Is A Very Good, Very Strong Bank
Whitney Is A Very Good, Very Strong Bank • Strong credit culture • Strong NIM • Strong balance sheet and solid capital position • Operational resiliency • Geographic diversification
Slide 29: Service, Knowledge, Relationship-focus
• Service • Knowledge • Relationship-focus • Friendly • Community-conscious
Slide 30: Gulf South Bank Conference
John M. Turner, Jr. President Thomas L. Callicutt, Jr. EVP & CFO Lewis P. Rogers EVP Credit Administration Gulf South Bank Conference May 1, 2008 New Orleans, LA
Source: SEC EDGAR · 8-K filed May 1, 2008
More decks from Whitney Holding Corp
 Q4 2010 Earnings Presentation15 slides · Jan 27, 2011
 Merger or Acquisition (December 2010)18 slides · Dec 23, 2010
 Merger or Acquisition (December 2010)18 slides · Dec 22, 2010
 Stifel Nicolaus Bank & Thrift Conference 201030 slides · Nov 2, 2010
 Q3 2010 Earnings Presentation16 slides · Oct 26, 2010
 Q2 2010 Earnings Presentation18 slides · Jul 27, 2010