Pioneer Natural Resources — Hart Energy's Developing Unconventional Gas Conference 2010
39 slides from Pioneer Natural Resources's conference presentation, Oct 4, 2010
Slide 1: Hart Energy's Developing Unconventional Gas Conference
Hart Energy’s Developing Unconventional Gas Conference October 5, 2010 EXHIBIT 99.1
Slide 2: Forward-Looking Statements
Forward-Looking Statements Except for historical information contained herein, the statements, charts and graphs in this presentation are forward-looking statements that are made pursuant to the Safe Harbor Provisions of the Private Securities Litigation Reform Act of 1995. Forward- looking statemen
Slide 3: Returning to Our Texas Roots
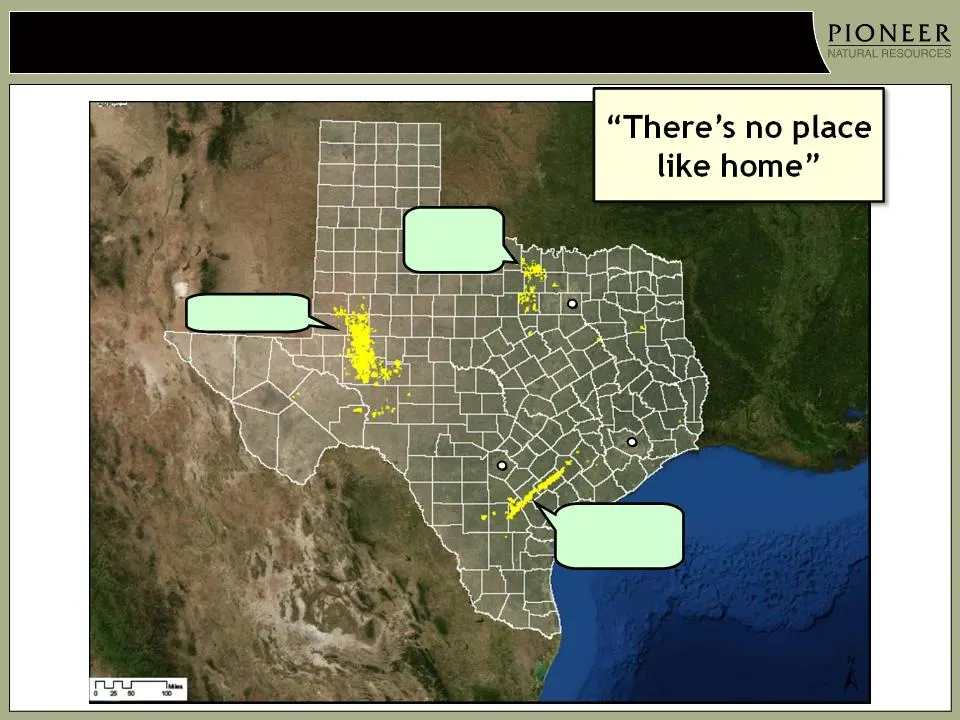
Returning to Our Texas Roots Dallas San Antonio Houston Barnett Combo Spraberry Eagle Ford Shale
Slide 4: PXD - Largest Spraberry Acreage Holder and Producer
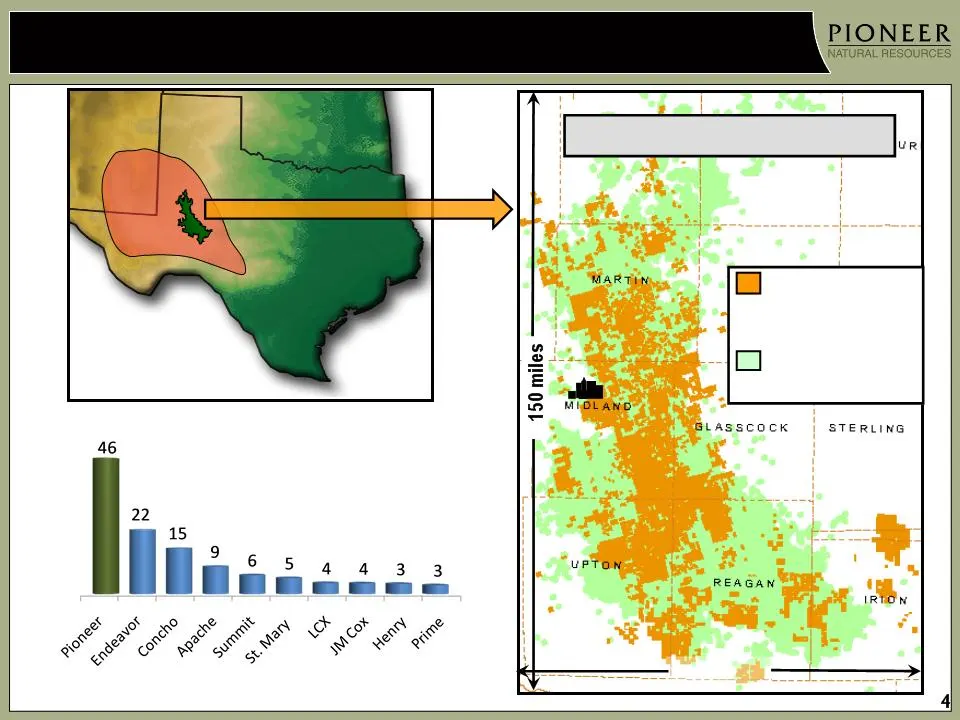
PXD - Largest Spraberry Acreage Holder and Producer PXD Acreage (~900,000 Acres; ~75% HBP) All Others (~800,000 Acres) 75 miles PERMIAN BASIN 24 MM acres 20,000+ Drilling Locations Spraberry Field Gross Production by Operator (MBOED) 1 1) Based on 2009 data from Railroad Commission of Texas
Slide 5: History of Spraberry Trend Completions
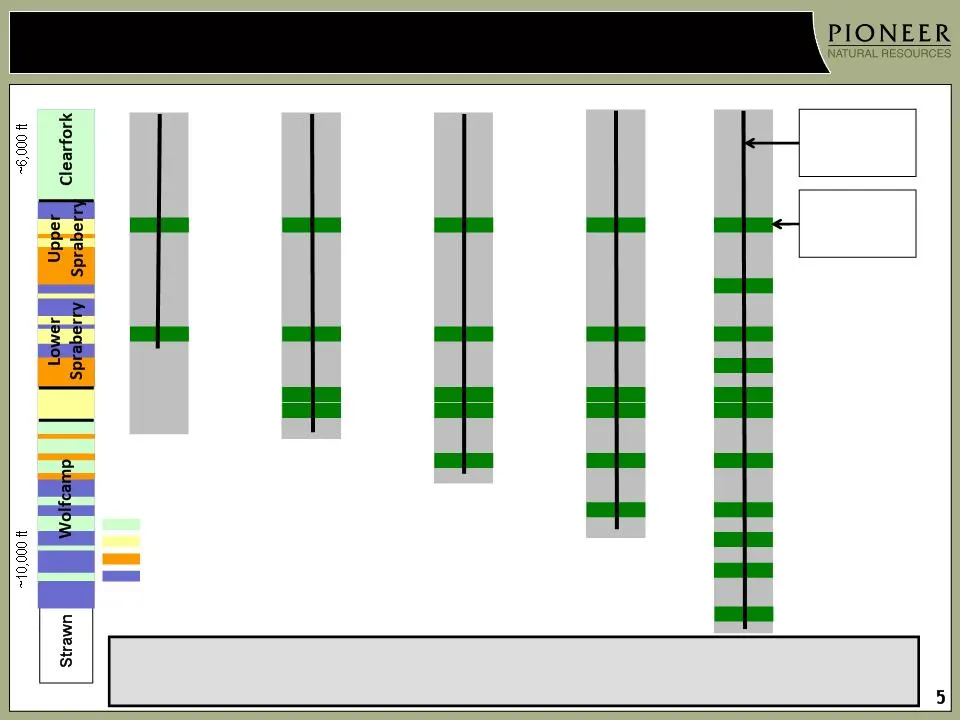
History of Spraberry Trend Completions 2010+ 2008 - 09 2000s 1980 - 90s 1950 - 70s Drilling deeper and adding fracture stimulation stages have added production and improved recoveries Average Cased Depth of Wellbore Fracture Stimulation Stages Dean Limestone Pay Sandstone Pay Non-Organic Shale Non-P
Slide 6: Increasing Rigs by 2012 - Accelerating Spraberry Development
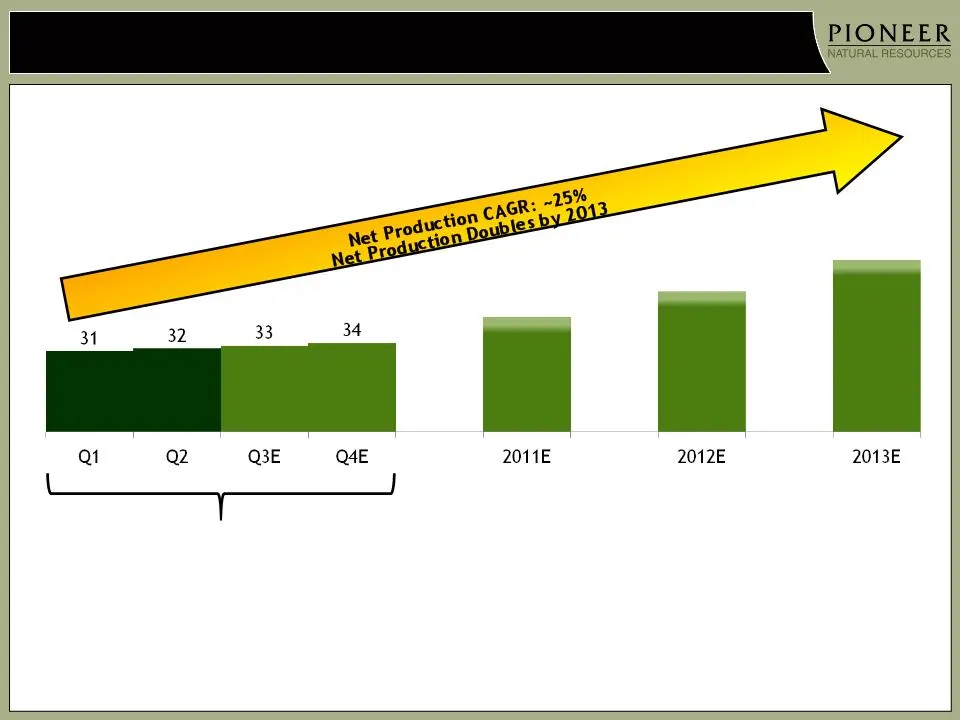
Increasing to 40 Rigs by 2012 - Accelerating Spraberry Development Wells ~440 ~700 ~1,000 ~1,000 +2% vs. Q4 2009 +4% vs. Q1 2010 Spraberry Net Production 1 (MBOED) 38 - 44 48 - 54 60 - 66 1) Reflects planned drilling program and expiration of VPP commitments
Slide 7: Eagle Ford Shale: Largest U.S. Oil Discovery Since Prudhoe Bay
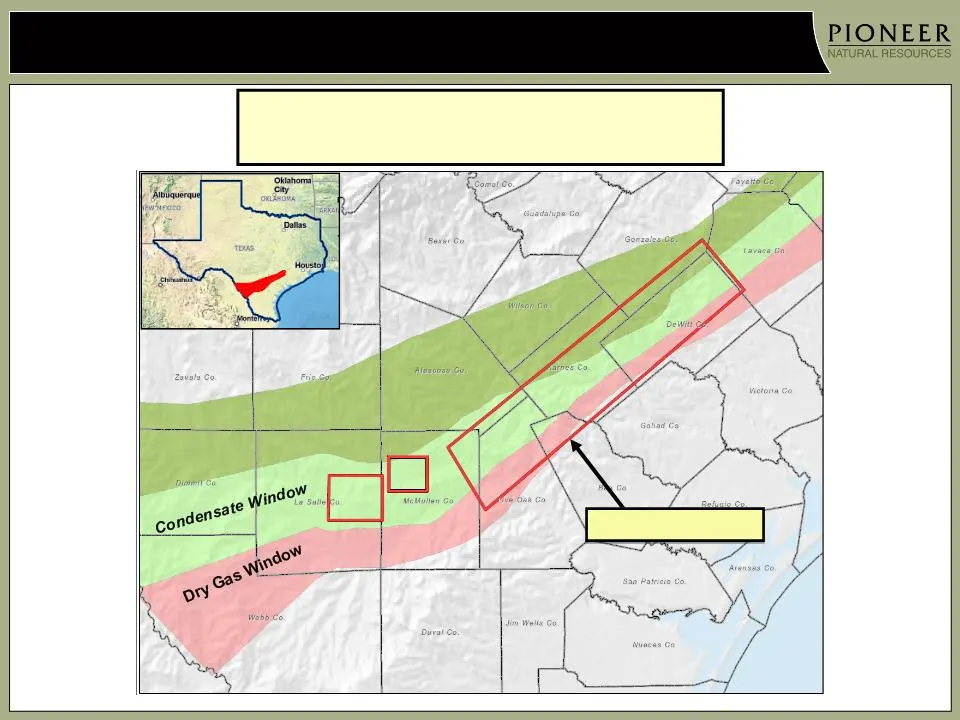
Eagle Ford Shale: Largest U.S. Oil Discovery Since Prudhoe Bay § Gross resource potential of play: ~150 TCF 1 § >100 rigs currently running in the play Oil Window Map source: PXD 1) Source: Tudor, Pickering, Holt & Co. PXD Acreage Area
Slide 8: Pioneer's History in the Eagle Ford Shale
Pioneer’s History in the Eagle Ford Shale § Re-completed several vertical wells in late 2006 in the Eagle Ford zone of interest § Play “exploded” with several key horizontal wells tested at high rates in 2008/2009 § Drilled 20 wells (15 with pilots & full suite of logs) § Cut over 1,000 feet of core
Slide 9: Early Vertical Recompletions Encouraging
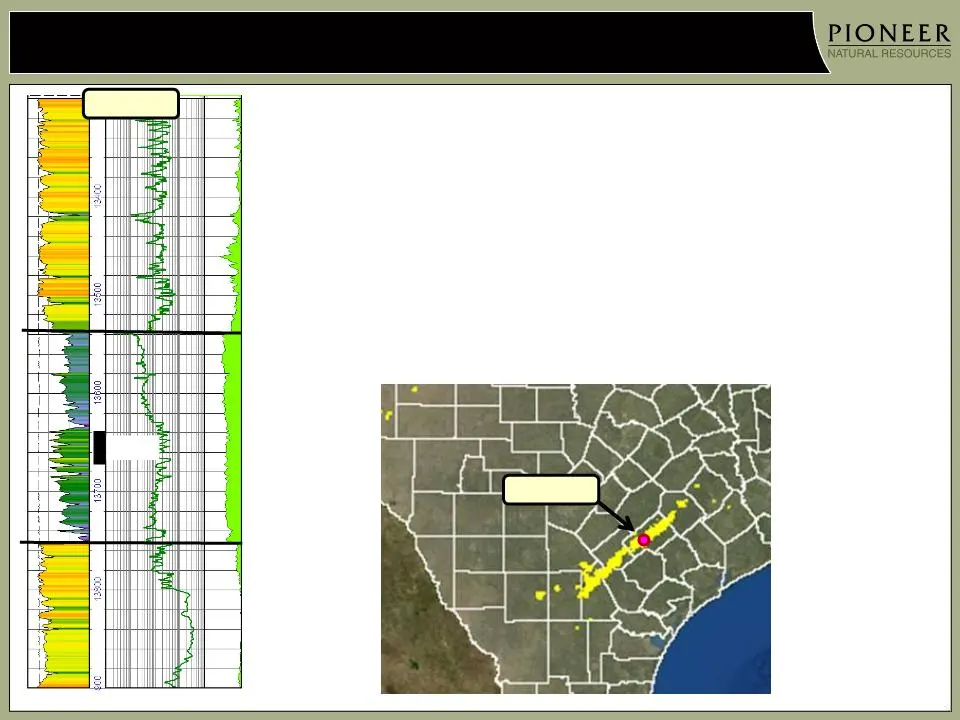
Early Vertical Recompletions Encouraging Perfs § 2006 Re-Completion Program – Rolf 2-6: 2,500 lbs proppant à 50 MCFPD (dry gas) – Wernli 1-4: 45,000 lbs proppant à 200 MCFPD (dry gas) – Menn 1: 190,000 lbs proppant à 550 MCFPD (wet gas) § Results – Larger frac was more productive – Liquids are prese
Slide 10: Horizontal Wells Deliver True Potential
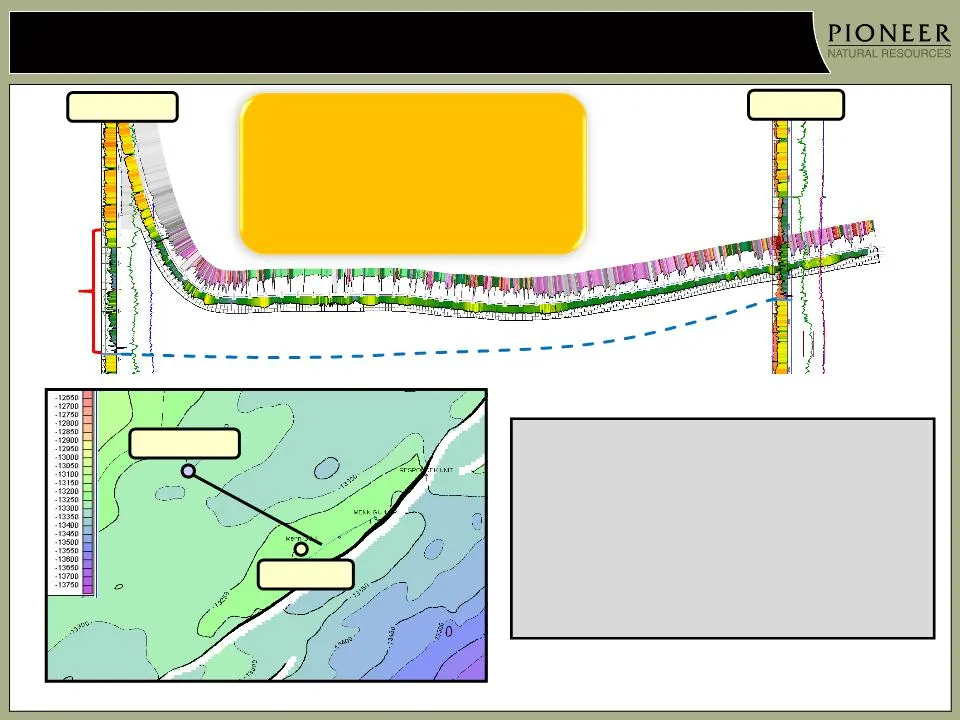
Horizontal Wells Deliver True Potential Charles Riedesel 4,500 ft lateral 4 MM lbs proppant in 14 stages IP: 15.7 MMCFEPD w/ 680 BBL condensate Riedesel Base Eagle Ford From 3D Seismic Top Eagle Ford Menn 1 Riedesel Menn 1 Eagle Ford Shale § IP of 15.7 MMCFEPD was ~30x more productive than vertical
Slide 11: Drilling Results Leader in Eagle Ford Shale Play
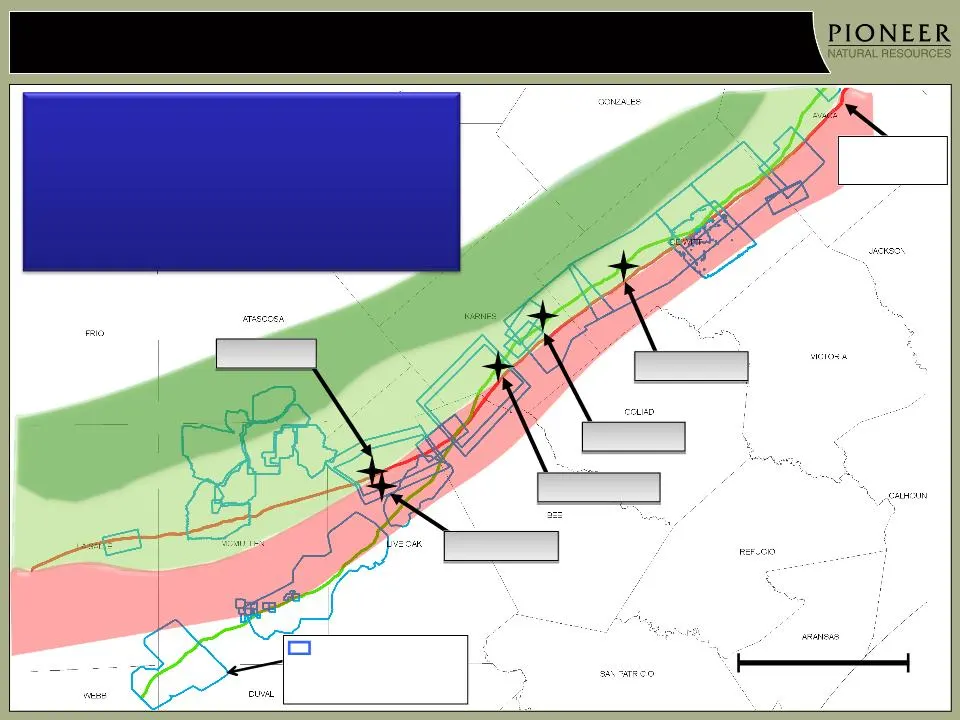
Drilling Results Leader in Eagle Ford Shale Play Leading IP’s: Handy #1 19.9 MMCFEPD (75% Liquids) Crawley #1 17.0 MMCFPD (Dry Gas) Riedesel #1 15.7 MMCFEPD (55% Liquids) Chestnutt #1 15.6 MMCFEPD (45% Liquids) Sinor #5 11.3 MMCFEPD (55% Liquids) PXD 3-D Seismic Coverage : >2,000 sq. miles Dry Gas W
Slide 12: 80% of Pioneer's Acreage in Condensate Window
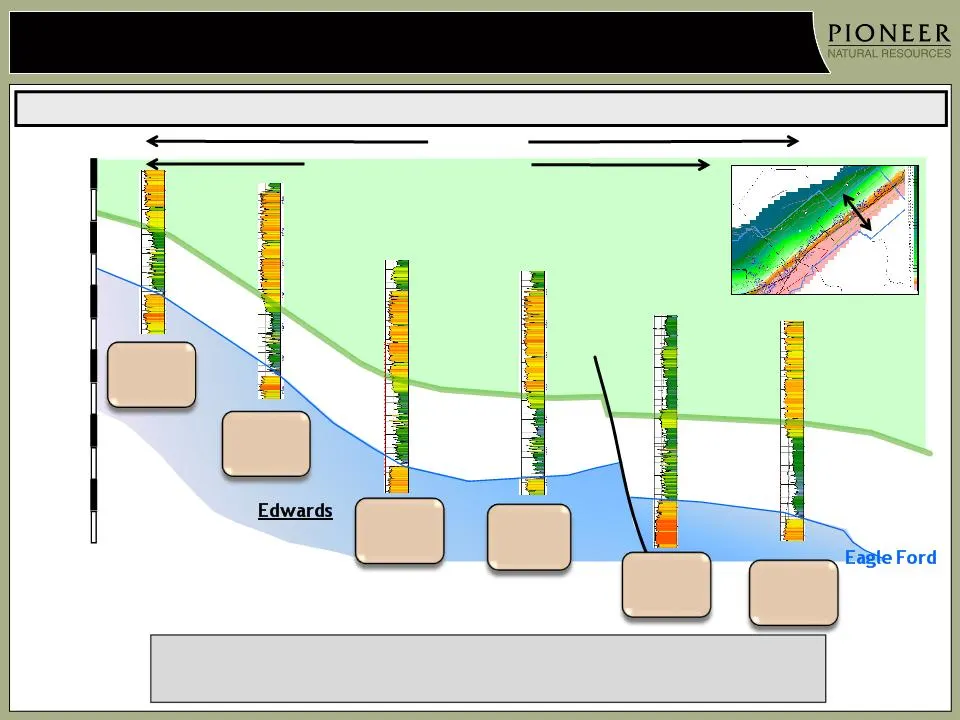
80% of Pioneer’s Acreage in Condensate Window 80% of Pioneer’s Acreage in Condensate Window 6 miles NW Handy Riedesel Chesnutt SE 13,400 ft 13,200 ft 13,000 ft Top Eagle Ford Base Sligo Margin 14,000 ft 13,800 ft 13,600 ft Yield BBL/MM Eagle Ford Yield BBL/MM Yield BBL/MM Yield BBL/MM Pioneer Well P
Slide 13: Eagle Ford Shale Joint Venture Highlights
Eagle Ford Shale Joint Venture Highlights § Sold 45% of PXD’s interest in ~212 M net acres in the Eagle Ford Shale to Reliance Industries Ltd. (RIL) for ~$1.15 B – Effective June 1, 2010 – $266 MM in cash received upfront – $879 MM in drilling carry; RIL funding 75% of PXD’s share of well costs unti
Slide 14: Pioneer Has Received Highest Acreage Value
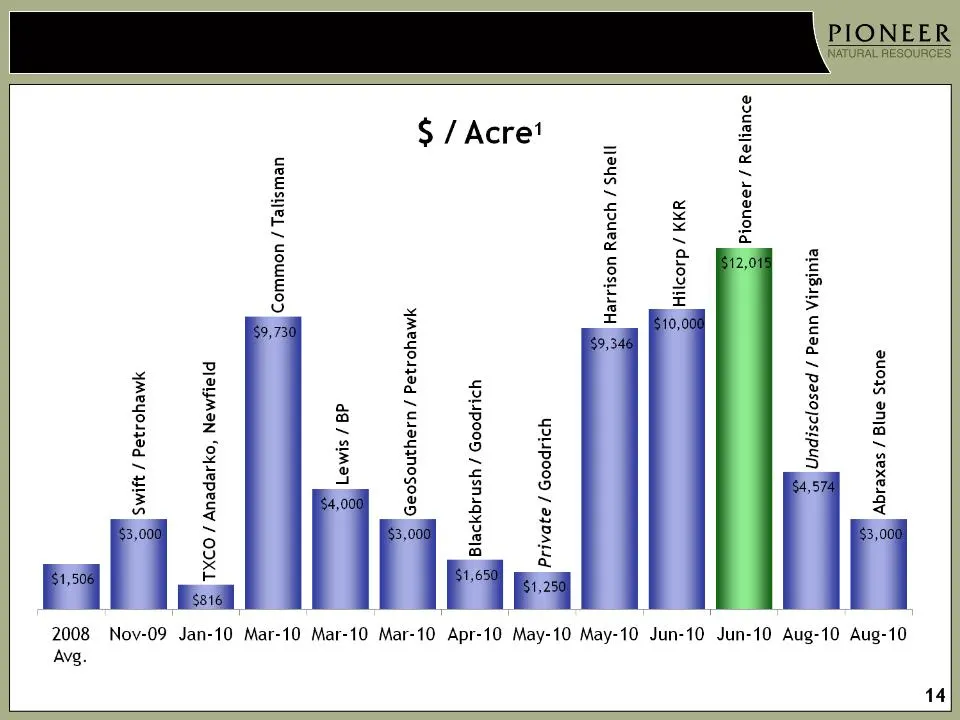
Pioneer Has Received Highest Acreage Value 1) Source: Raymond James 2) Source: Madison Williams
Slide 15: Eagle Ford Shale Joint Venture Development Plan
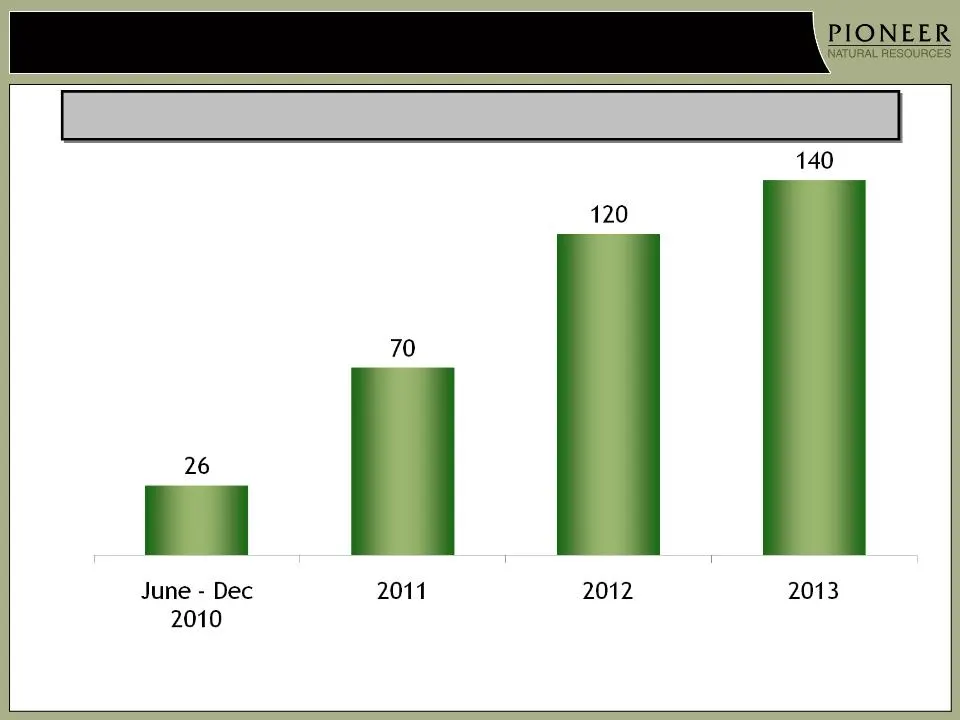
Eagle Ford Shale Joint Venture Development Plan Year-end Rig Count 7 10 14 14 Gross Wells Over 700 MMBOE Net Resource Potential from ~2,000 drilling locations
Slide 16: Significant Eagle Ford Shale Production Ramp-up
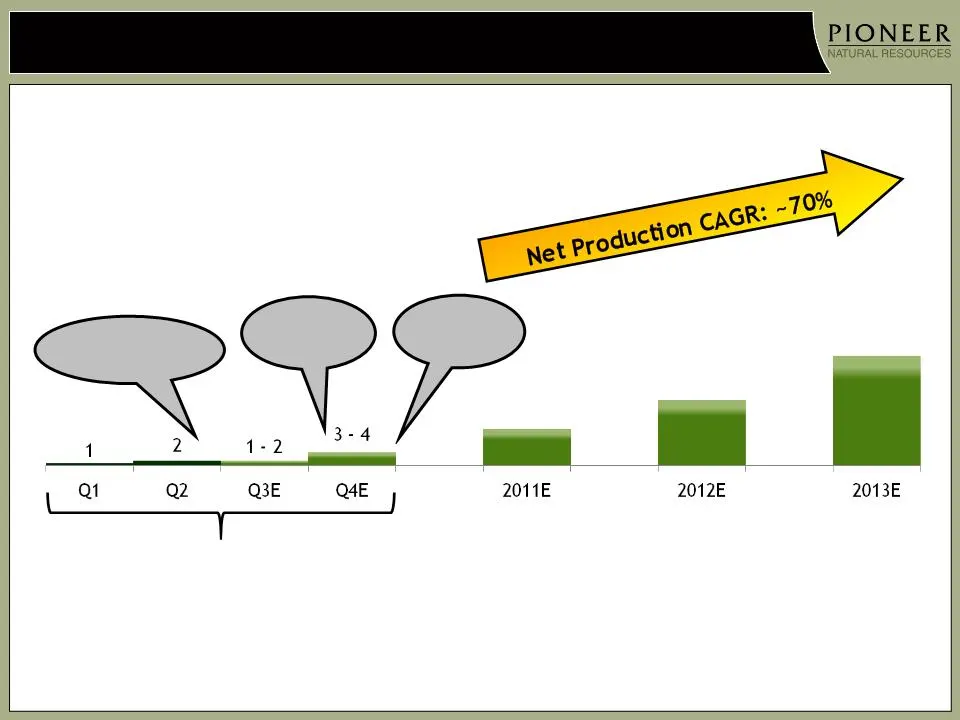
Significant Eagle Ford Shale Production Ramp-up Gross Wells 26 (June - Dec) 70 120 140 Eagle Ford Net Production 1 (MBOEPD) 10 - 13 19 - 24 32 - 41 1) Reflects planned drilling program and working interest of 42% Midstream connections begin RIL JV effective June 1 st YE exit rate ~5 MBOEPD
Slide 17: Eagle Ford Shale Production Breakdown
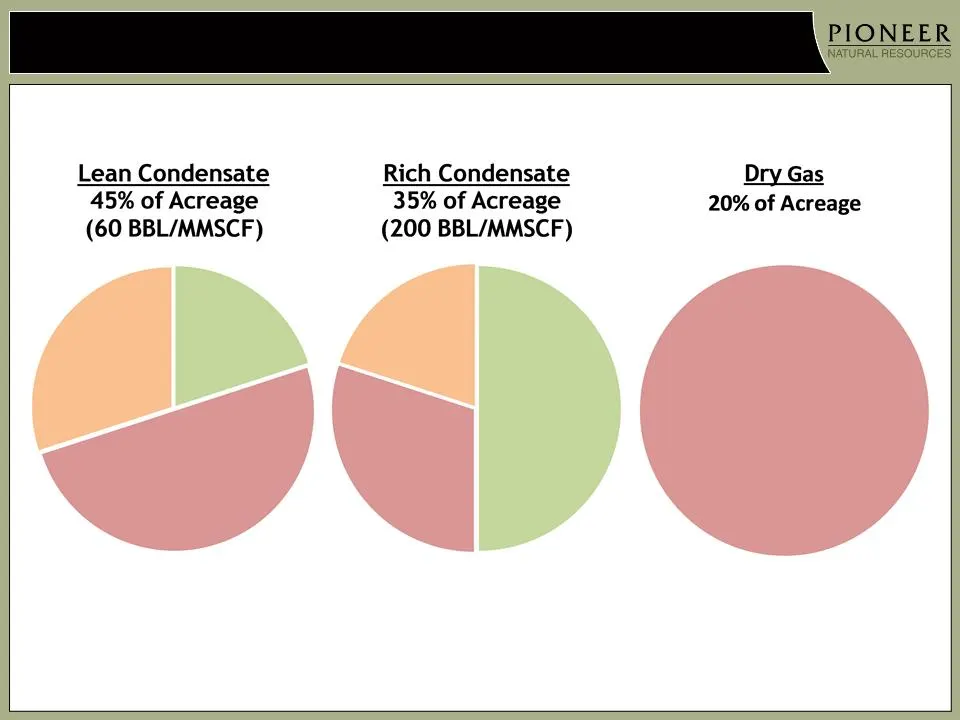
Eagle Ford Shale Production Breakdown 30% NGL* 50% Gas 20% Condensate 20% NGL* 30% Gas 100% Gas 50% Condensate *NGLs are 50% ethane, 25% propane, 15% butanes and 10% heavier liquids
Slide 18: Higher Condensate / NGL Yields Result in Low Breakeven Gas Price
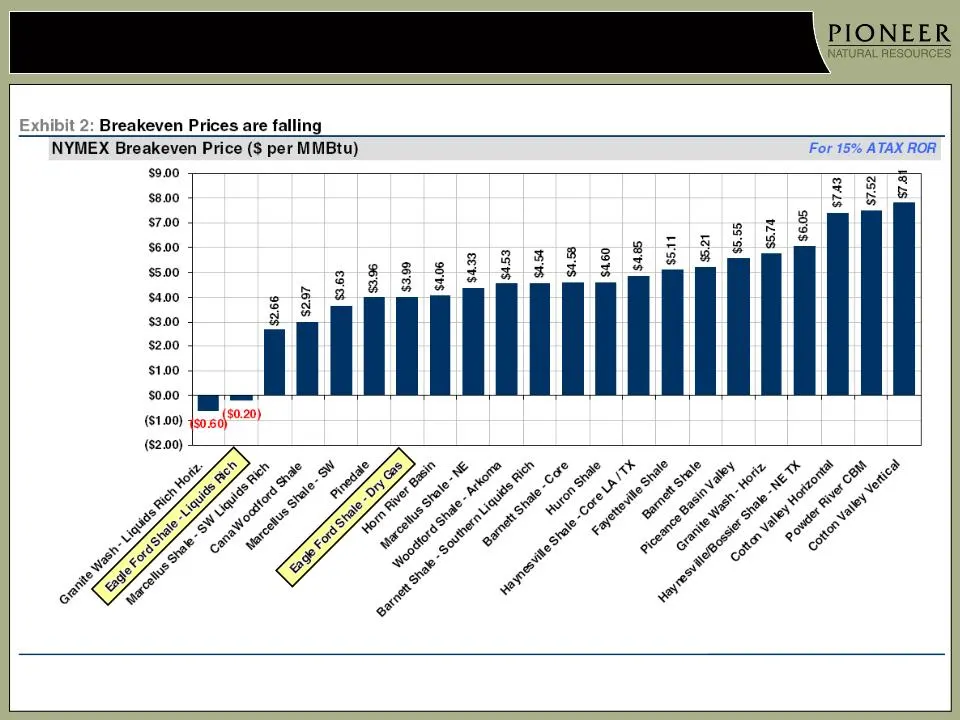
Higher Condensate / NGL Yields Result in Low Breakeven Gas Price for Eagle Ford Shale Assumes condensate yield of 25%, NGL yield of ~85 BBL/MM, $80/BBL oil price and NGL price 45% of oil Source: Credit Suisse
Slide 19: Eagle Ford Shale IRR Sensitivity to Condensate Yield and NGL Prices
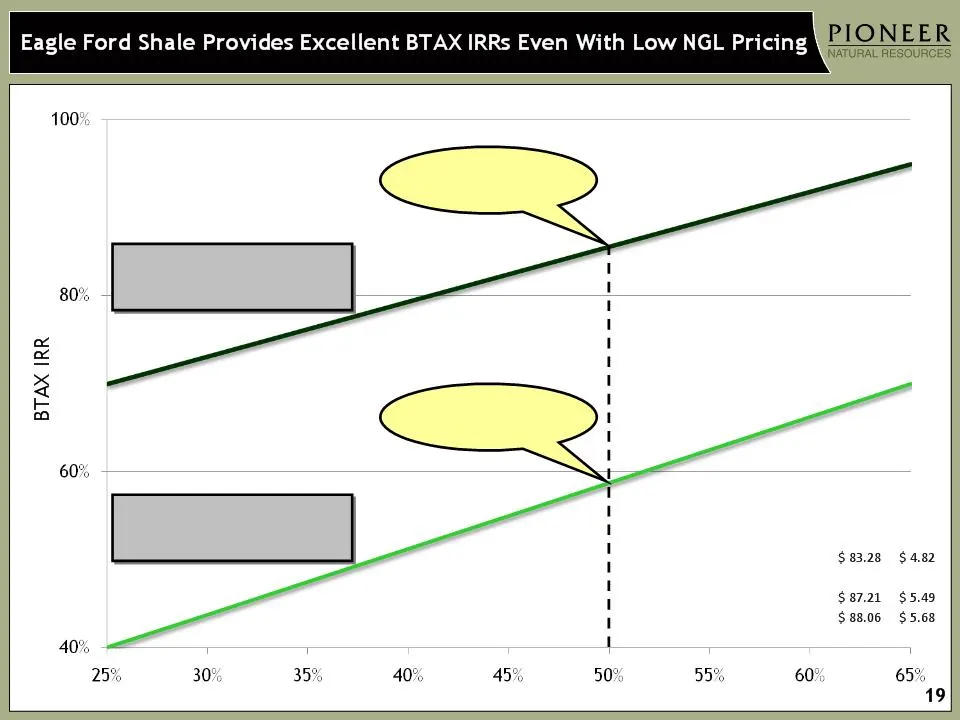
Strip Case (August) Oil Gas 2010 (August-Dec) 2011 $ 86.24 $ 5.17 2012 . 2013 2014+ $ 88.77 $ 5.82 NGL % of WTI ~60% IRR at NGL Prices 50% of WTI High Condensate Yield 200 BBL / MMCF Low Condensate Yield 60 BBL / MMCF ~85% IRR at NGL Prices 50% of WTI
Slide 20: Eagle Ford Shale Operational Update
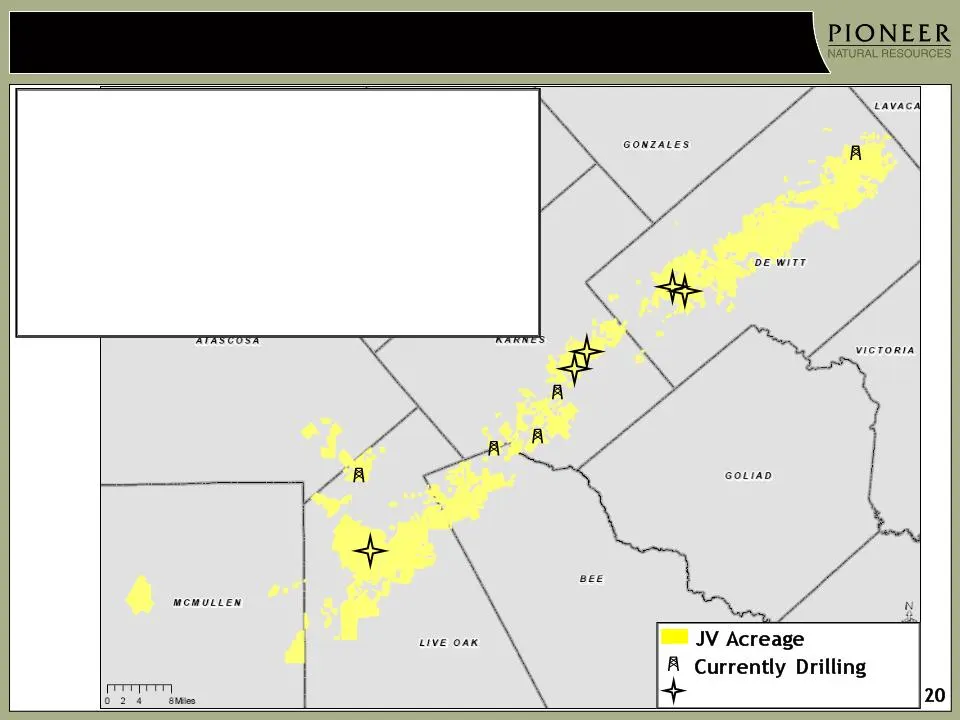
Eagle Ford Shale Operational Update § 5 wells currently producing § 5 wells completed and awaiting central gathering facility construction; expect to be online during Q4 § 5 wells awaiting completion; expect to be online during Q4 following completion of gathering facilities § Running 5 rigs; will i
Slide 21: Eagle Ford Shale Joint Venture Midstream Plan
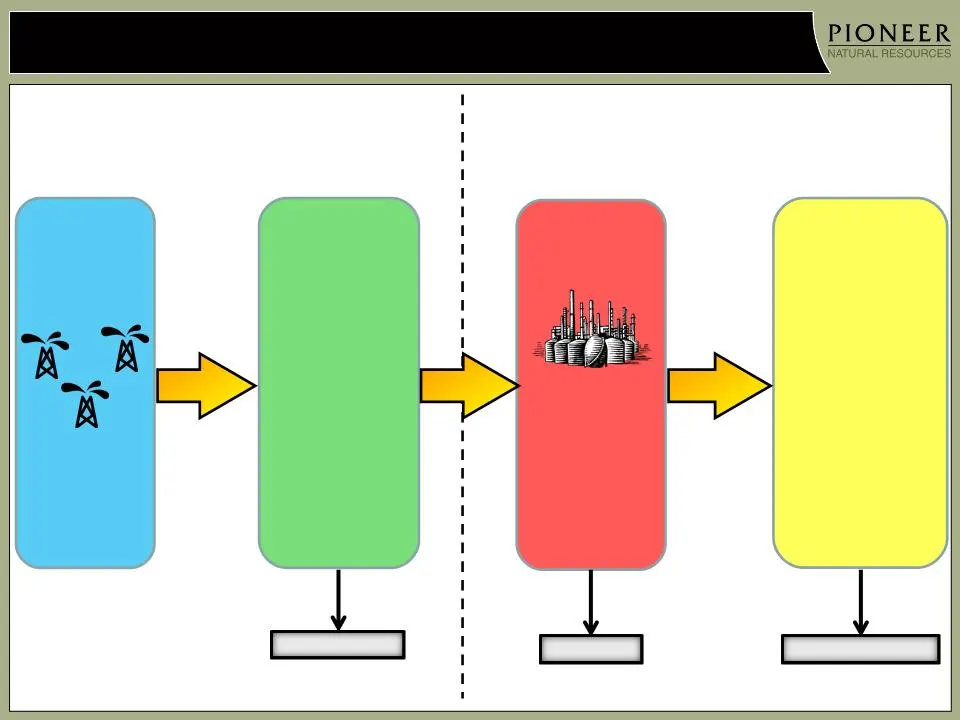
Eagle Ford Shale Joint Venture Midstream Plan Eagle Ford Shale Upstream • Production from Drilling – Rich or Dry Gas – Condensate PXD/RIL Joint Venture Fractionation • NGLs separated into ethane, propane, butanes and pentanes+ Midstream Central Gathering Facilities • Gather gas and condensate • Sepa
Slide 22: Eagle Ford Shale Midstream Development Plan
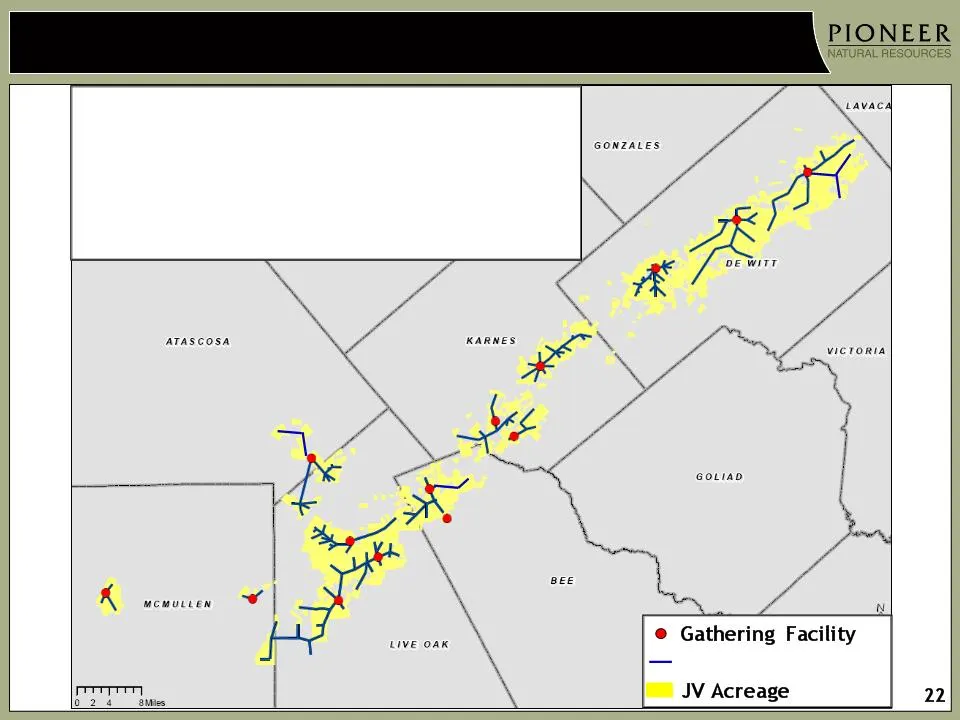
Eagle Ford Shale Midstream Development Plan § 14 Central Gathering Facilities § 250 miles of pipeline § Cost: ~$300 MM through 2013 (PXD’s share) § Provides enhanced control and efficiencies for marketing of upstream production § Potential for 3 rd party business Gathering Pipeline
Slide 23: Significant Surplus Capacity to Process PXD's Eagle Ford Shale Production
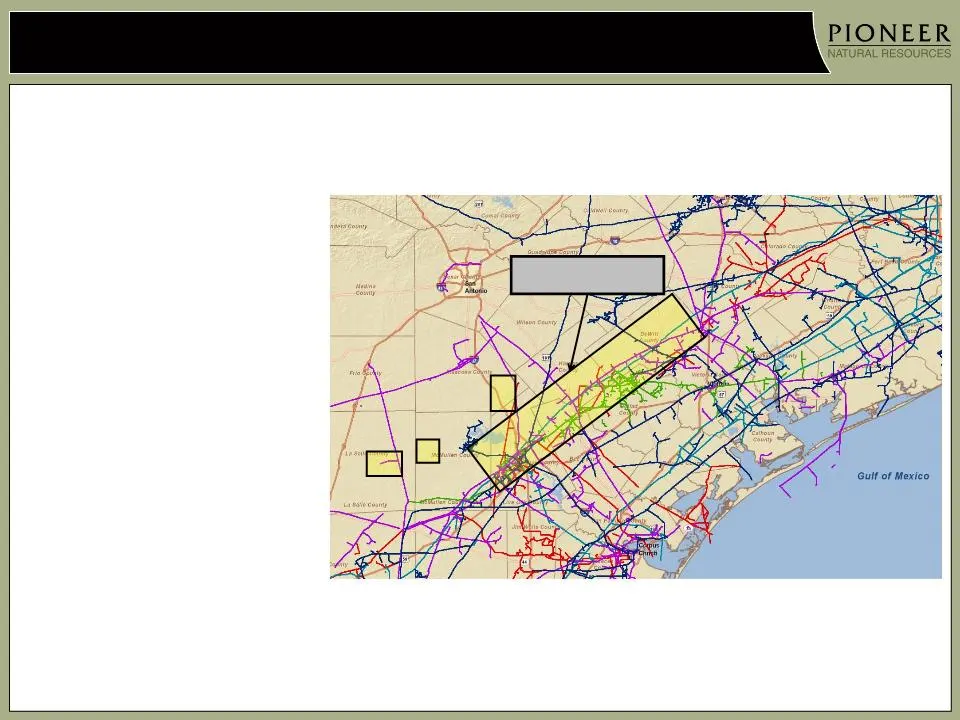
Significant Surplus Capacity to Process PXD’s Eagle Ford Shale Production Pioneer Acreage Midstream - To Transport and Process Wet Gas 1 Existing Processing Capacity: ~3 BCF/D Surplus Processing Capacity: 0.75 - 1.0 BCF/D Fractionation - To Process NGLs 2 Mont Belvieu Existing Capacity: ~700 MBPD Pr
Slide 24: Operating Cash Flow Expected to Double by 2013
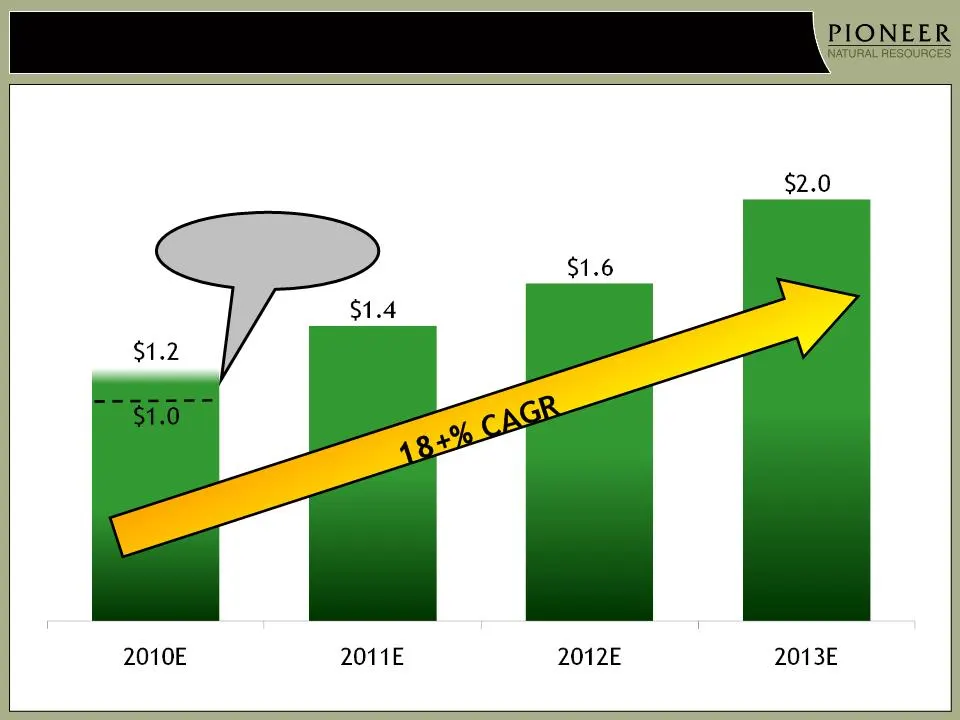
Operating Cash Flow Expected to Double by 2013 Billions 1 1) Based on August strip pricing and includes derivative positions as of July 20, 2010 Additional Cash Flow From Deepwater GOM Refund
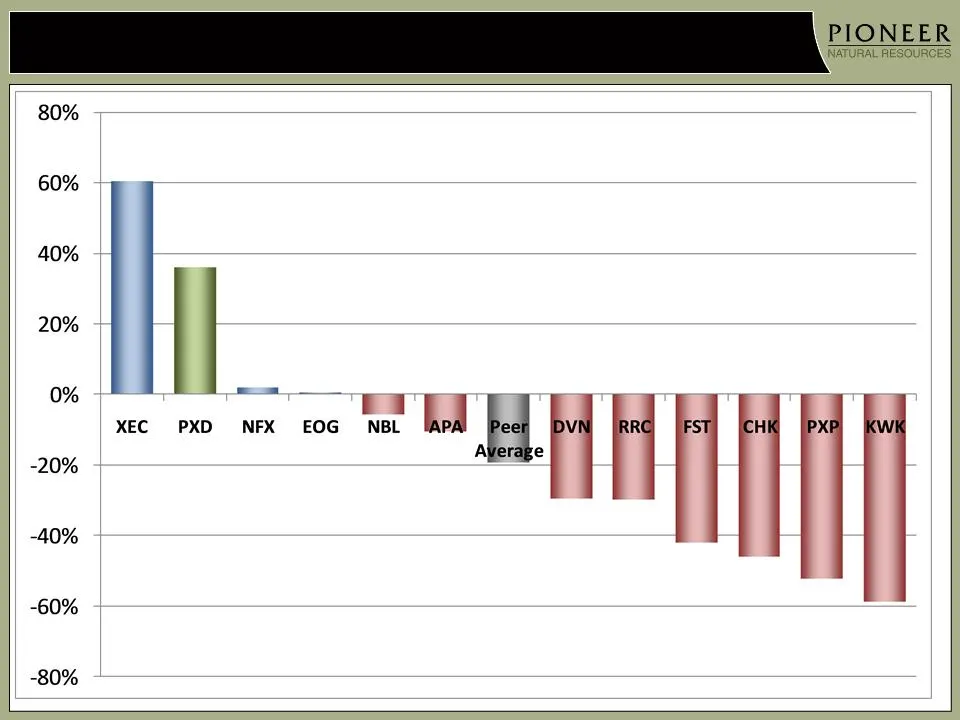
Slide 25: PXD Stock Price Performance vs. Peers Since 12/31/07
PXD Stock Price Performance vs. Peers Since 12/31/07
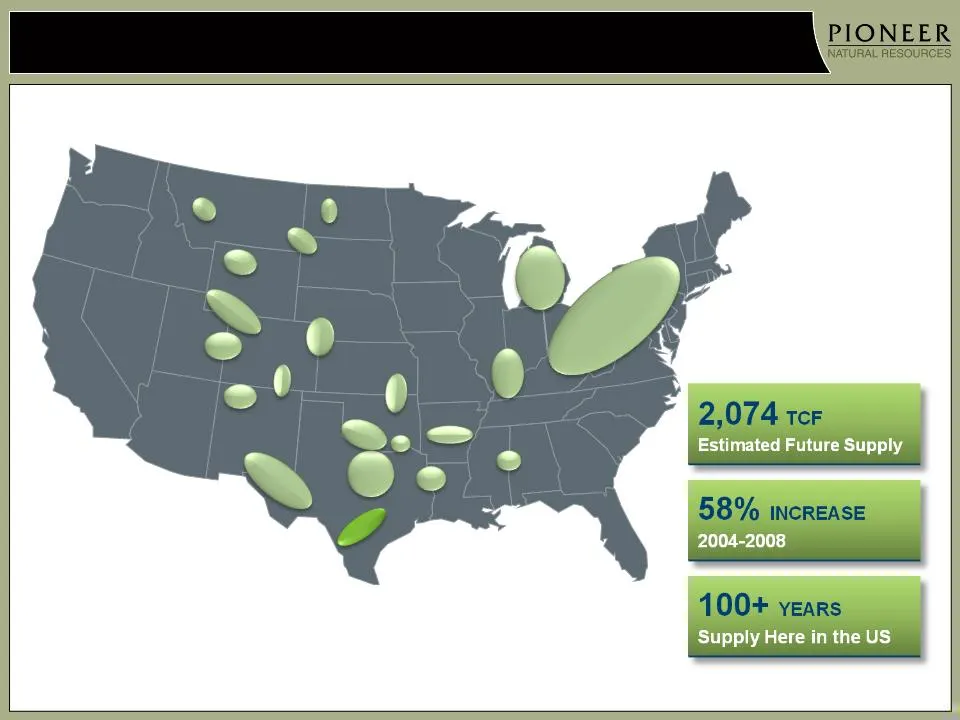
Slide 26: The Shale Gas Revolution
The Shale Gas Revolution Haynesville Fayetteville New Albany Floyd-Neal Marcellus/ Devonian/Utica Woodford Barnett- Woodford Eagle Ford Barnett Lewis Cody Niobrara Mulky Bakken Antrim Baxter-Mancos Mowry Gammon Mancos Pierre Total Potential Natural Gas Resources: Source: Potential Gas Committee Repo
Slide 27: Promote Using More Natural Gas
Promote Using More Natural Gas ABUNDANT DOMESTIC CLEAN JOBS And Natural Gas is Available Now!
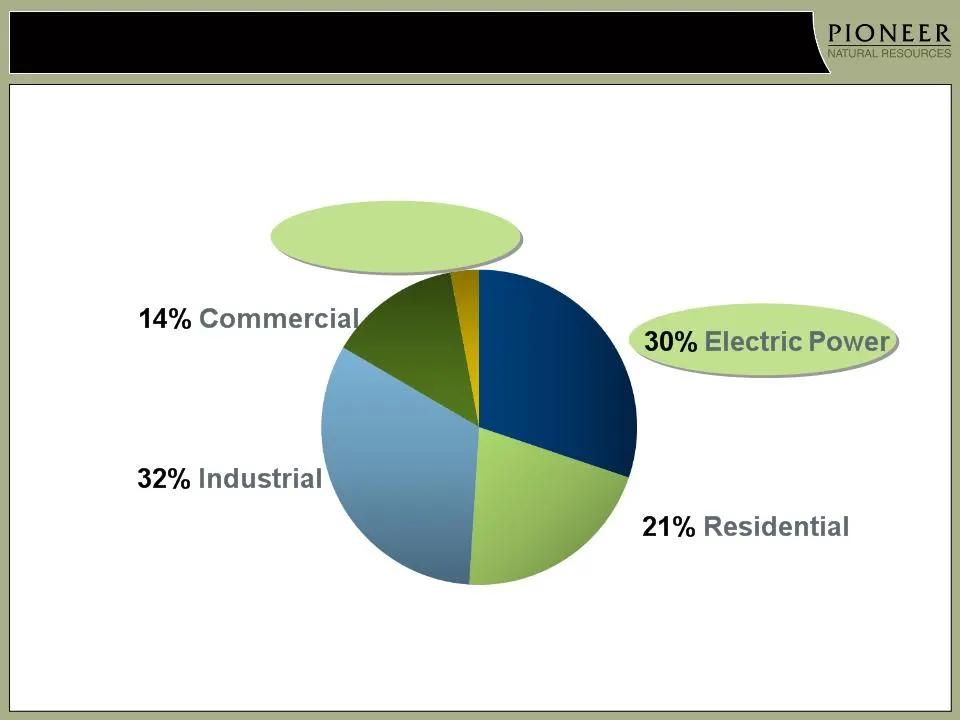
Slide 28: How We Use Natural Gas
How We Use Natural Gas Source: EIA, Natural Gas Year In Rev iew, 2009 How Natural Gas is Used Today 3% Transportation
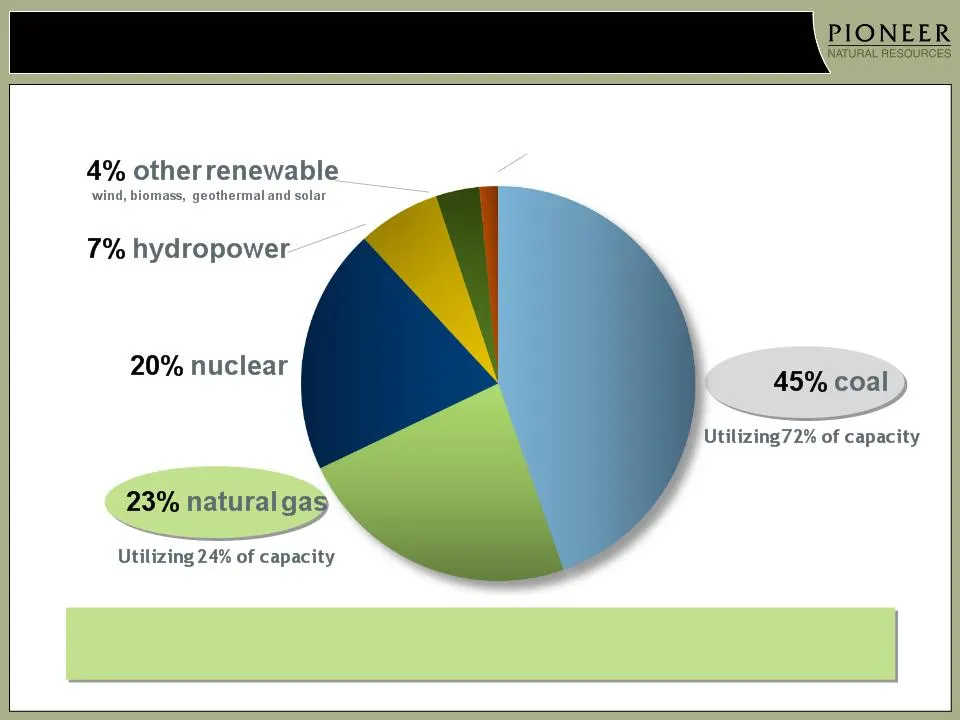
Slide 29: Today's Electricity Mix
Today’s Electricity Mix Source: EIA, 2009 Annual Energy Review 1% other non-renewable EIA expects demand for electricity to grow ~1% per year and that 250 gigawatts of new generating capacity will be needed by 2035.
Slide 30: Natural Gas is Cleaner for Power Generation
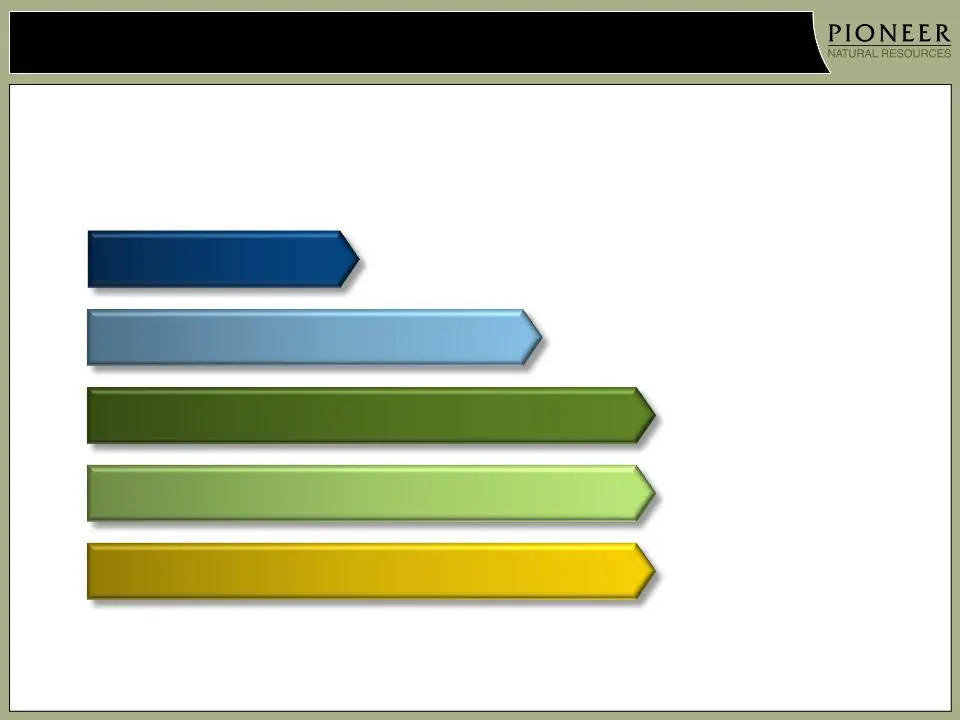
Natural Gas is Cleaner for Power Generation Reduces CO 2 emissions Reduces NOx emissions Virtually Eliminates SO2 Emissions Virtually Eliminates Particulate Emissions Completely Eliminates Mercury Emissions Compared to coal, natural gas… 50% 80% 99.96% 99.74% 100%
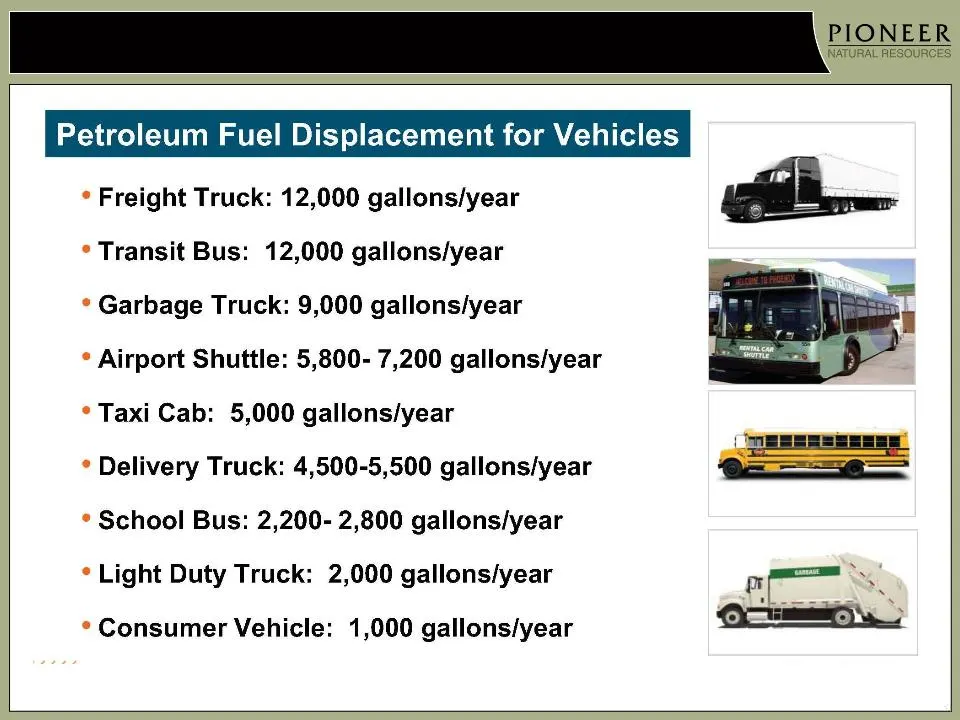
Slide 31: Natural Gas for Transportation
Natural Gas for Transportation Source: NGVAmerica
Slide 32: Our Dependence on Foreign Oil
Our Dependence on Foreign Oil $208,894,495,000 § We imported 3,540,500,000 barrels in 2009 • That’s 9,700,000 barrels per day § We paid out $208,894,495,000 for imported oil in 2009 • That’s $572,000,000 per day • Or $680 for each person in America § Among the top countries we import from: Venezuela
Slide 33: Natural Gas is Cleaner for Vehicles
Natural Gas is Cleaner for Vehicles Reduce CO 2 emissions Reduce CO emissions Reduce NOx emissions Reduce Particulate Matter emissions Reduce VOC emissions § Compared to gasoline or diesel, NGVs: 20-30% 70-90% 75-95% 90% 89%
Slide 34: Infrastructure: Refueling Stations
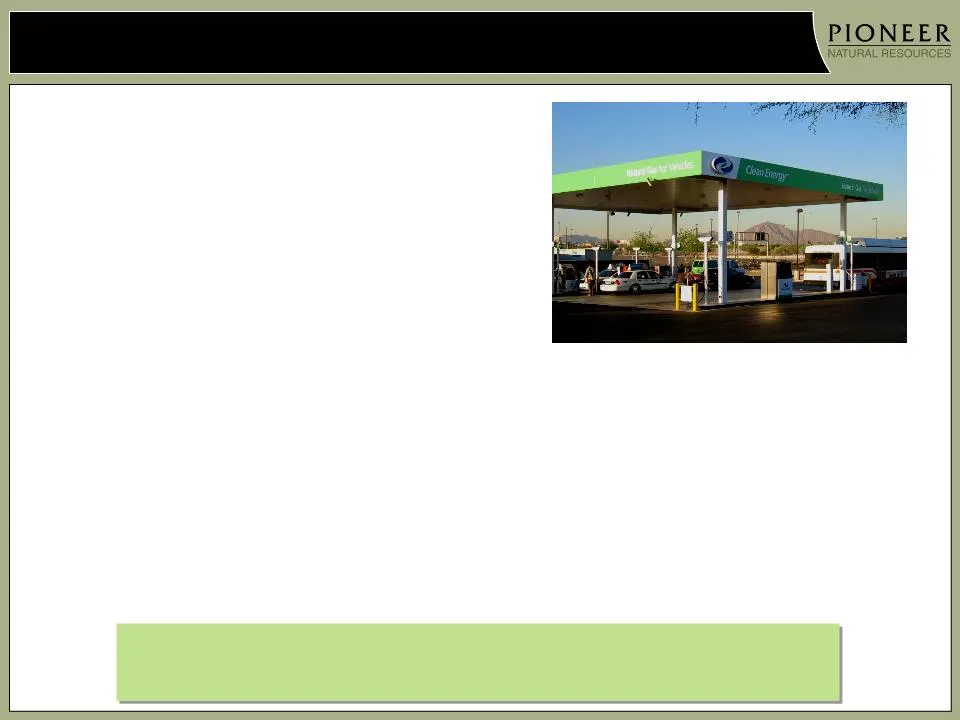
Infrastructure: Refueling Stations • ~ 10,000 natural gas vehicles in U.S. today • ~ 1,600 natural gas fueling stations • NGV fueling infrastructure is growing: ‒ cleaner, more affordable fleets ‒ governments concerned about air quality ‒ more commitment to reduce reliance on foreign oil • Public ac
Slide 35: Jobs Across the Country
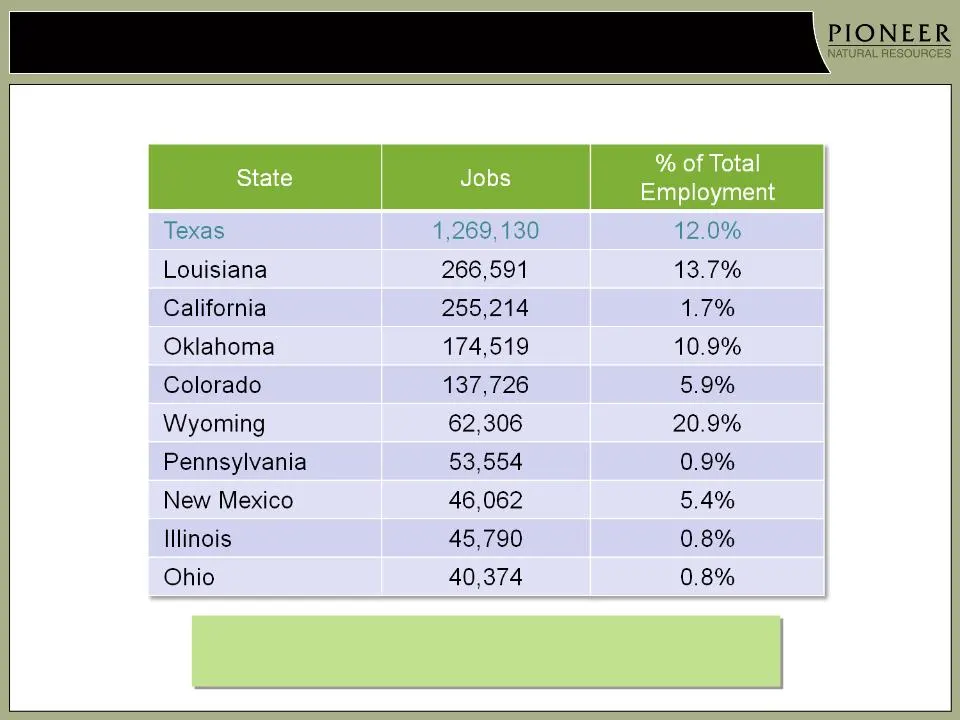
Jobs Across the Country Top 10 States for Natural Gas Jobs Source: IHS Global Insight, 2009 31 states have more than 10,000 jobs tied to natural gas More jobs being added every year
Slide 36: Protecting Natural Gas Operations
Protecting Natural Gas Operations
Slide 37: @ (J @u Barrett Corporation BG GROUP B
@ (J @u Barrett Corporation BG GROUP B bhpbilliton = aw € Cabot Oil & Gas Corporation E devon el paso Exes 5 ENERG=N. Gise resources EQT (HichMount ‘nergy for poople + (LAREDO jMumataehe. NEWBIELD 1. note VME Nees. >> ry) e revronawke = PIONEER PXP_ aur QUICKSILVER NATURAL RESOURCES SandRidge SENECA
Slide 38: Natural Gas - The Natural Choice Now
Natural Gas The Natural Choice Now. www.anga.us twitter @ANGAus
Slide 39: Certain Reserve Information
Certain Reserve Information Cautionary Note to U.S. Investors --The U.S. Securities and Exchange Commission (the "SEC") prohibits oil and gas companies, in their filings with the SEC, from disclosing estimates of oil or gas resources other than “reserves,” as that term is defined by the SEC. In this
Source: SEC EDGAR · 8-K filed Oct 4, 2010
More decks from Pioneer Natural Resources Co
 Merger or Acquisition (October 2023)15 slides · Oct 11, 2023
 Q3 2020 Earnings Presentation30 slides · Nov 4, 2020
 Merger or Acquisition (October 2020)18 slides · Oct 20, 2020
 IPAA Oil & Gas Investment Symposium 201846 slides · Apr 9, 2018
 Investor Presentation (January 2014)80 slides · Jan 6, 2014
 Q4 2012 Earnings Presentation48 slides · Feb 13, 2013