Front Yard Residential — Proxy Contest (May 2019)
27 slides from Front Yard Residential's proxy contest presentation, May 7, 2019
Slide 1: Renew RESI: Response to Front Yard's Misleading Presentation
Renew RESI Response to Front Yard’s Misleading Presentation May 2019
Slide 2: Disclaimer
DISCLAIMER This presentation is for discussion and general informational purposes only. It does not have regard to the specific investment objective, financial situation, suitability, or the particular need of any specific person who may receive this presentation, and should not be taken as advice o
Slide 3: Overview: Front Yard's Misleading Presentation
Overview: Front Yard’s Misleading Presentation
Slide 4: Front Yard's Troubling Misrepresentations and Omissions
FRONT YARD’S TROUBLING MISREPRESENTATIONS AND OMISSIONS ▪ Snow Park Capital Partners, LP (“Snow Park”) is a long-term stockholder of Front Yard Residential Corporation (NYSE: RESI)(“Front Yard” or the “Company”) with deep knowledge of its business, portfolio and governance ▪ All three of Snow Park’s
Slide 5: Front Yard's Refusal to Address or Acknowledge Failures
FRONT YARD’S REFUSAL TO ADDRESS OR ACKNOWLEDGE FAILURES In its recent presentation, Front Yard once again opted to completely ignore the litany of issues that continue to drive the Company’s underperformance, strategic missteps and poor governance ▪ Miserable Total Shareholder Returns – Despite oper
Slide 6: The Status Quo Needs to Change in Front Yard's Boardroom
THE STATUS QUO NEEDS TO CHANGE IN FRONT YARD’S BOARDROOM Without changing the composition of Front Yard’s Board, the Company appears destined to continue doubling down on a flawed business plan that has already destroyed significant value and left stockholders in a perilous position If elected to th
Slide 7: Front Yard's Unaddressed Failures and Misrepresentations
Front Yard’s Unaddressed Failures and Misrepresentations
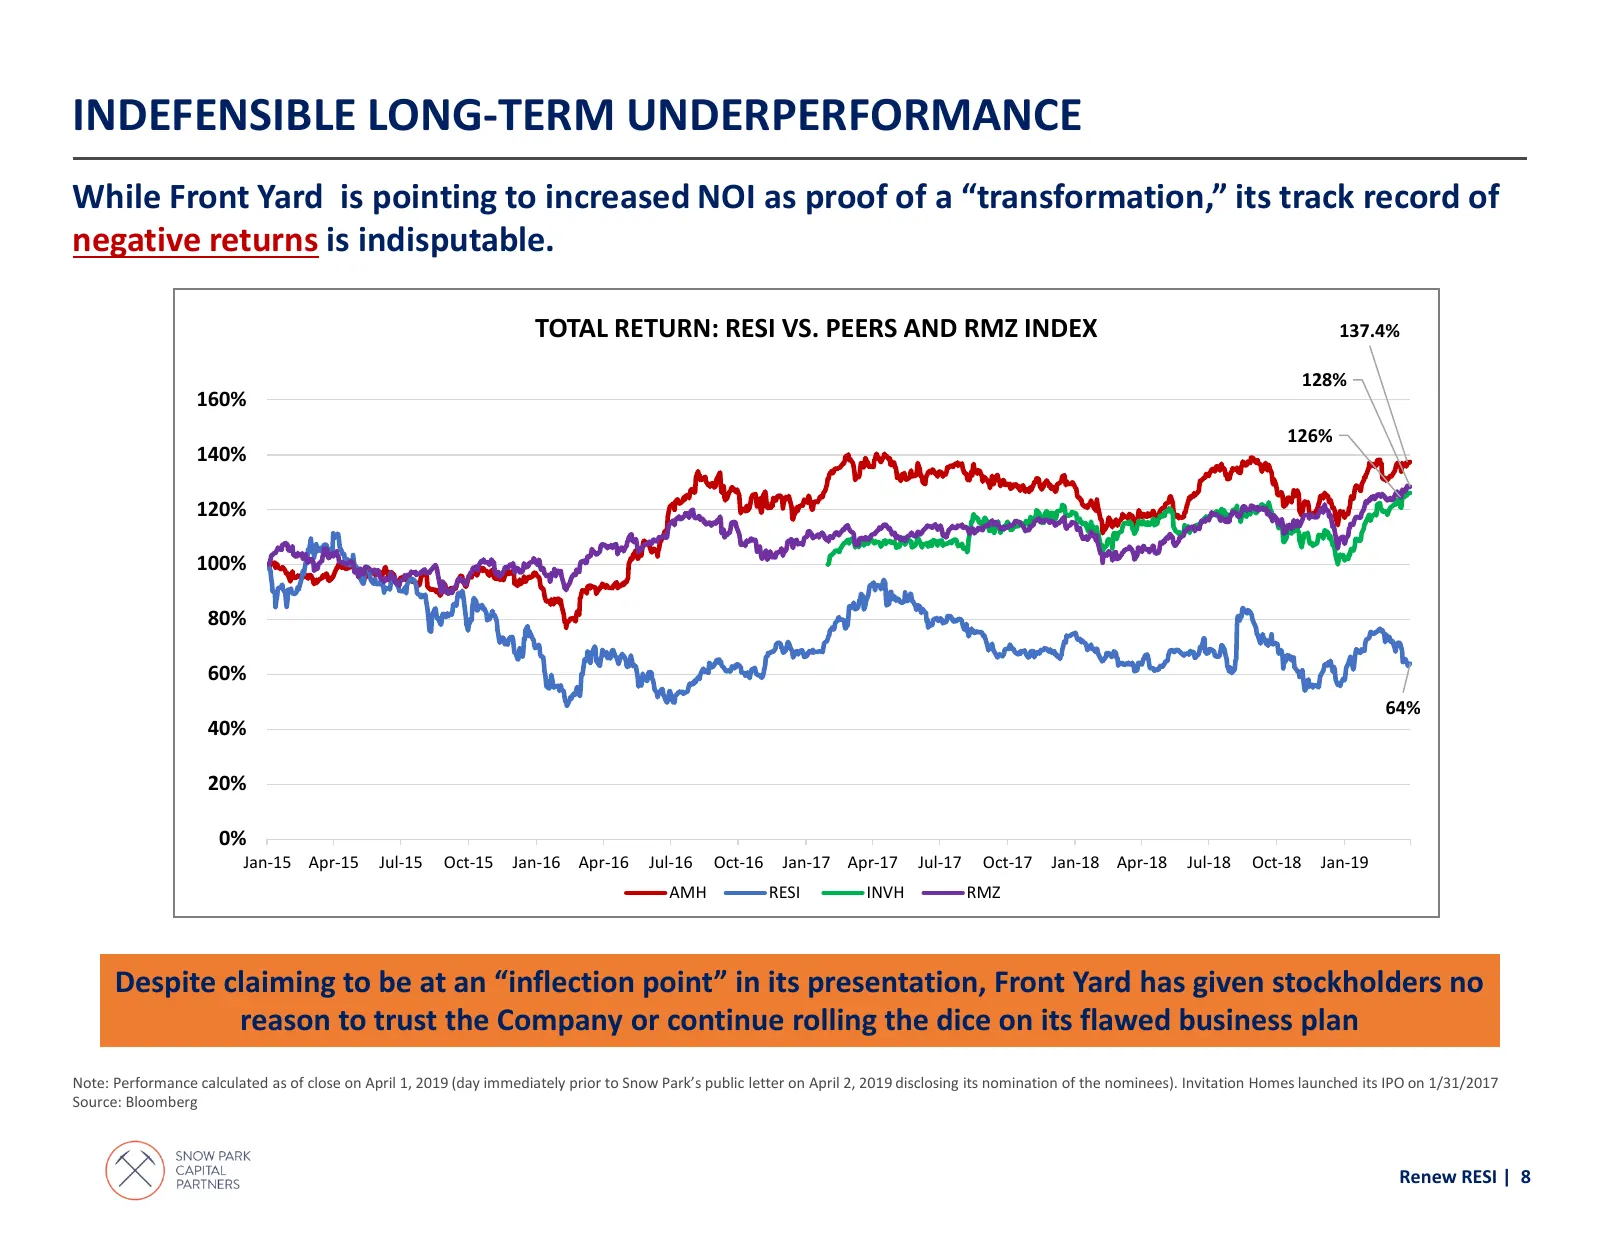
Slide 8: Indefensible Long-Term Underperformance
INDEFENSIBLE LONG-TERM UNDERPERFORMANCE While Front Yard is pointing to increased NOI as proof of a “transformation,” its track record of negative returns is indisputable. TOTAL RETURN: RESI VS. PEERS AND RMZ INDEX 137.4% 128% 160% 126% 140% 120% 100% 80% 60% 64% 40% 20% 0% Jan-15 Apr-15 Jul-15 Oct-
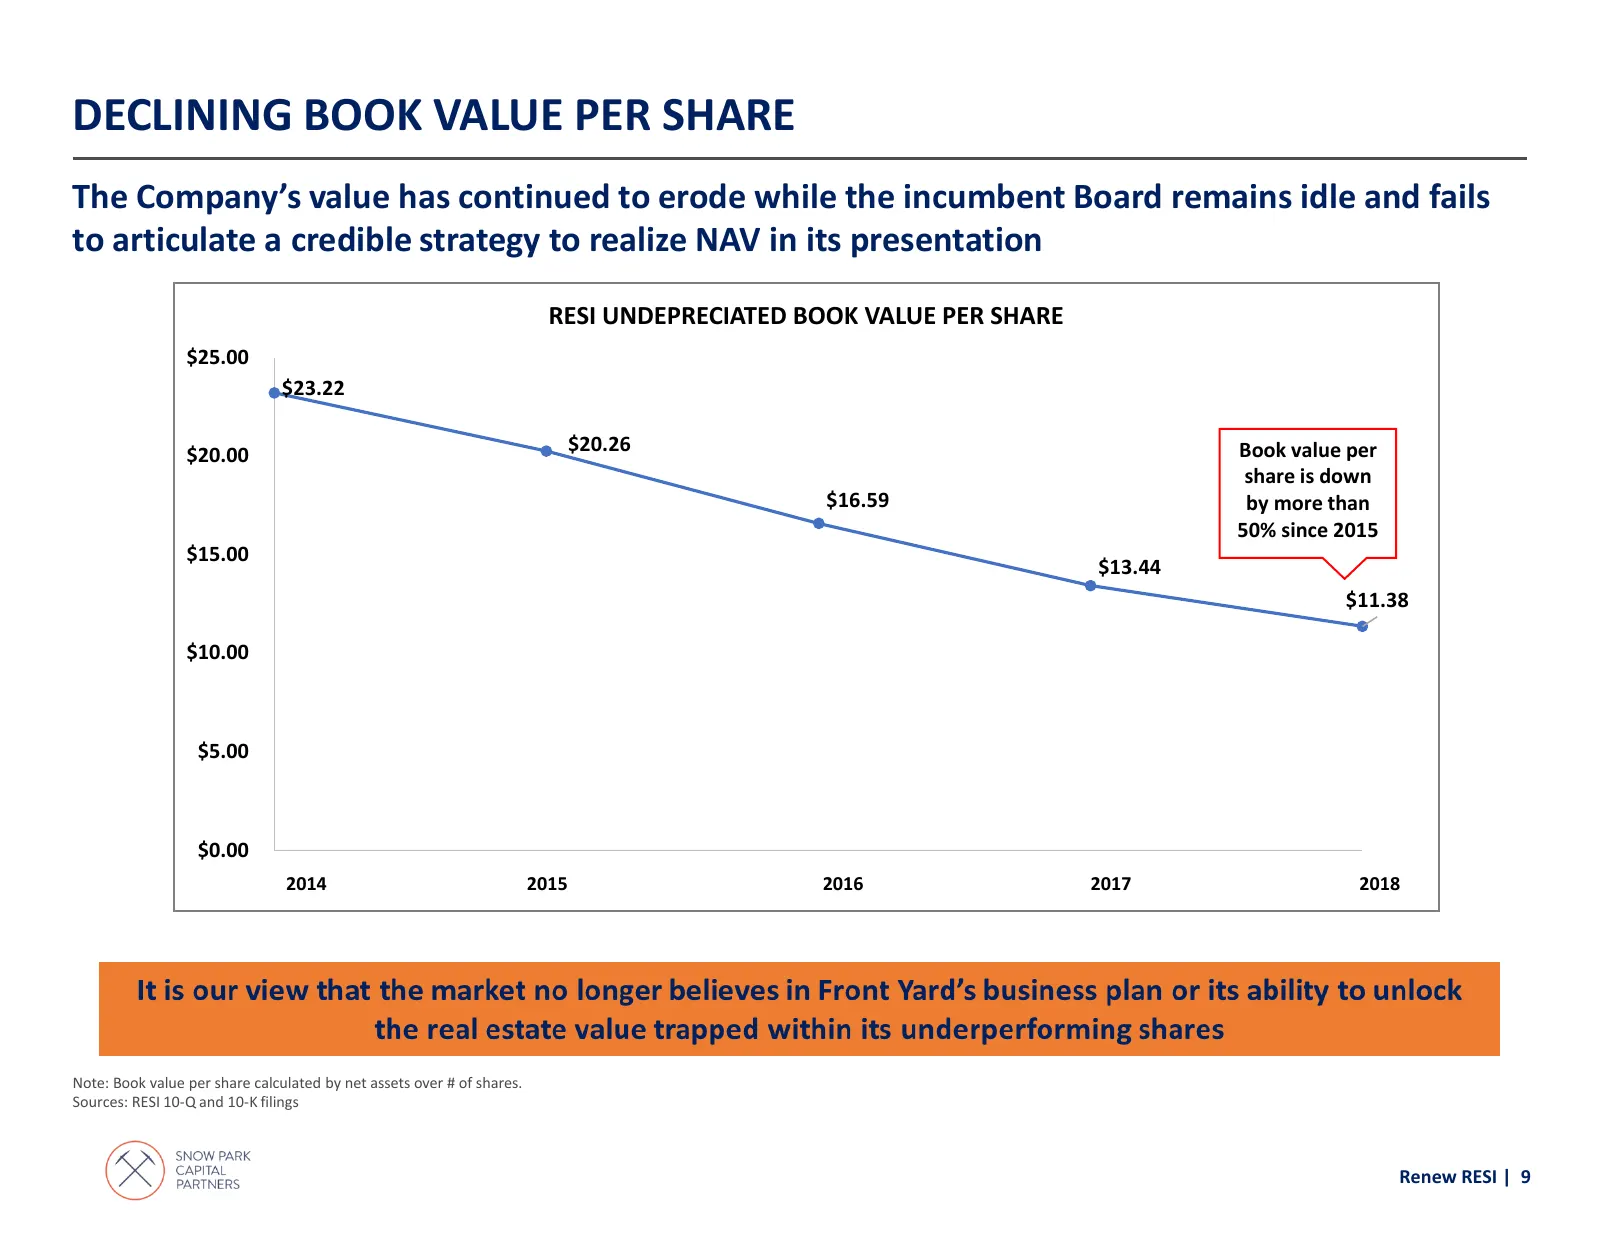
Slide 9: Declining Book Value Per Share
DECLINING BOOK VALUE PER SHARE The Company’s value has continued to erode while the incumbent Board remains idle and fails to articulate a credible strategy to realize NAV in its presentation RESI UNDEPRECIATED BOOK VALUE PER SHARE $25.00 $23.22 $20.00 $20.26 Book value per share is down $16.59 by m
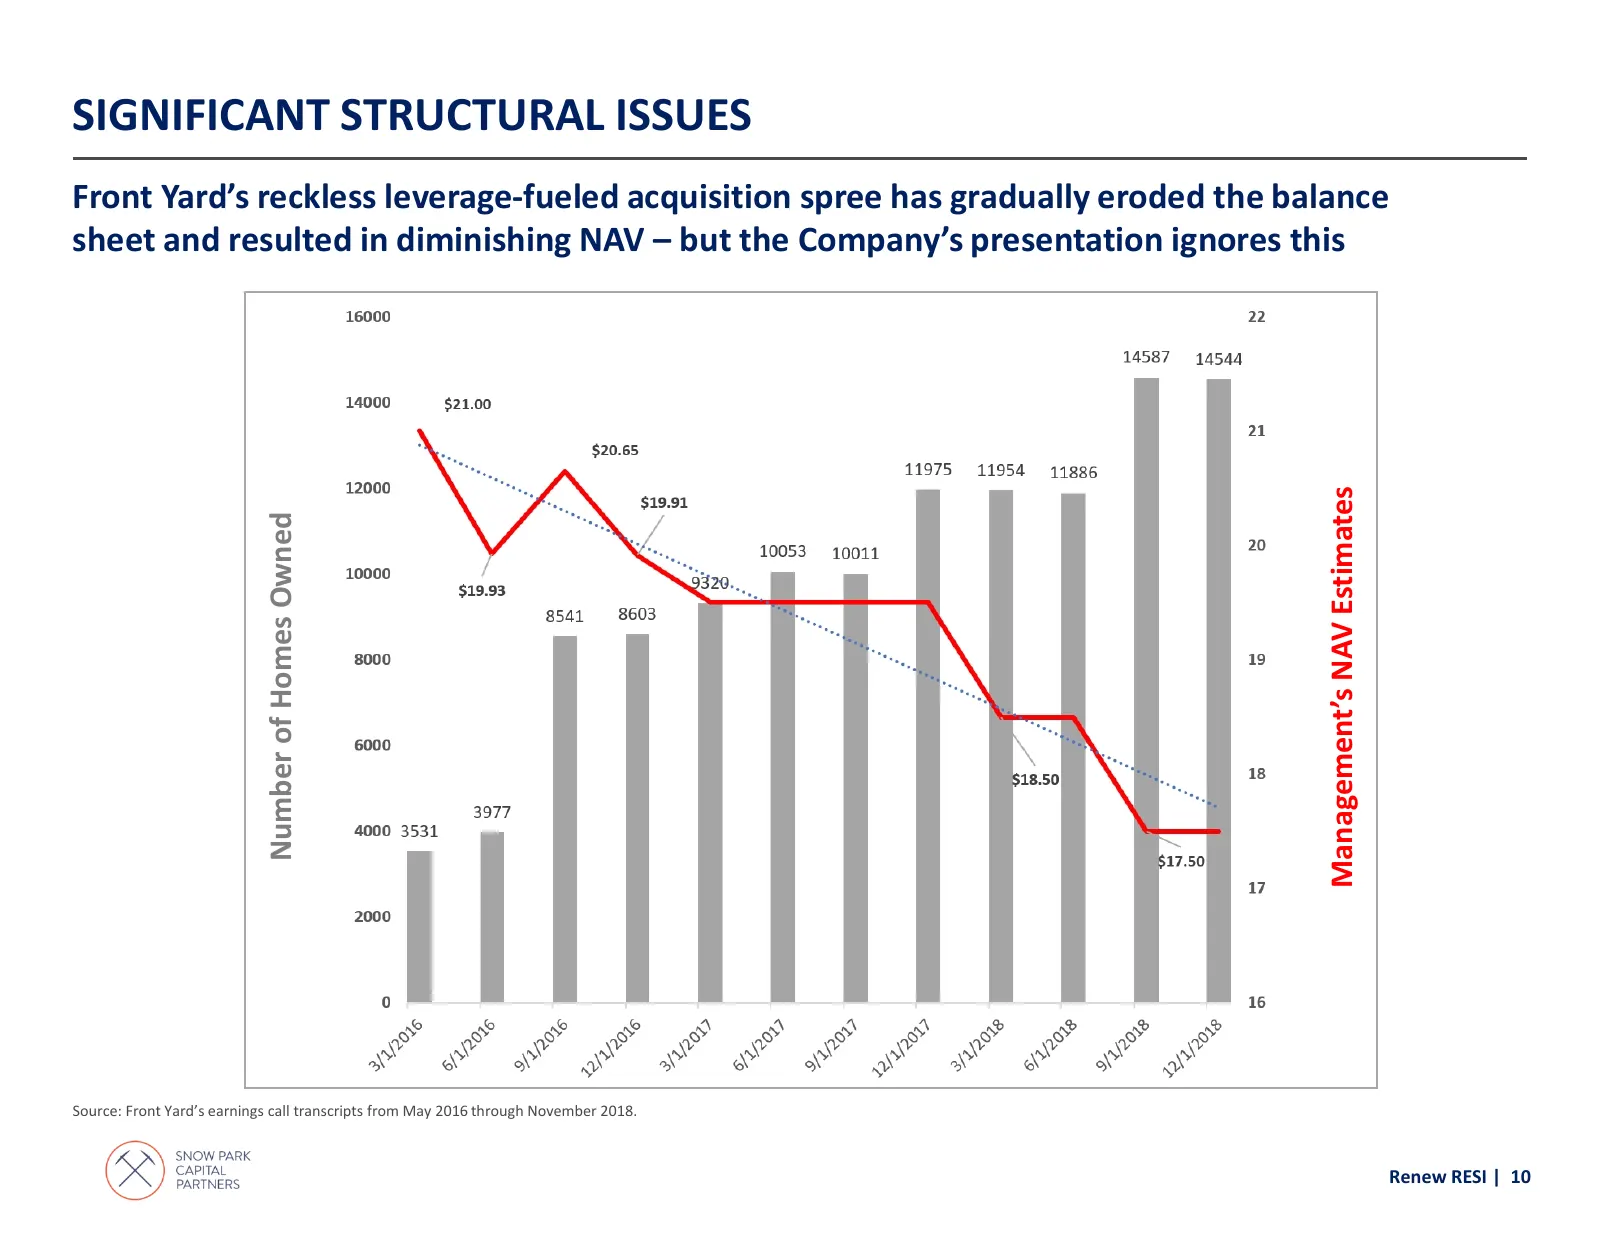
Slide 10: Significant Structural Issues: Management's NAV Estimates
SIGNIFICANT STRUCTURAL ISSUES Front Yard’s reckless leverage-fueled acquisition spree has gradually eroded the balance sheet and resulted in diminishing NAV – but the Company’s presentation ignores this Management’s NAV Estimates Number of Homes Owned Source: Front Yard’s earnings call transcripts f
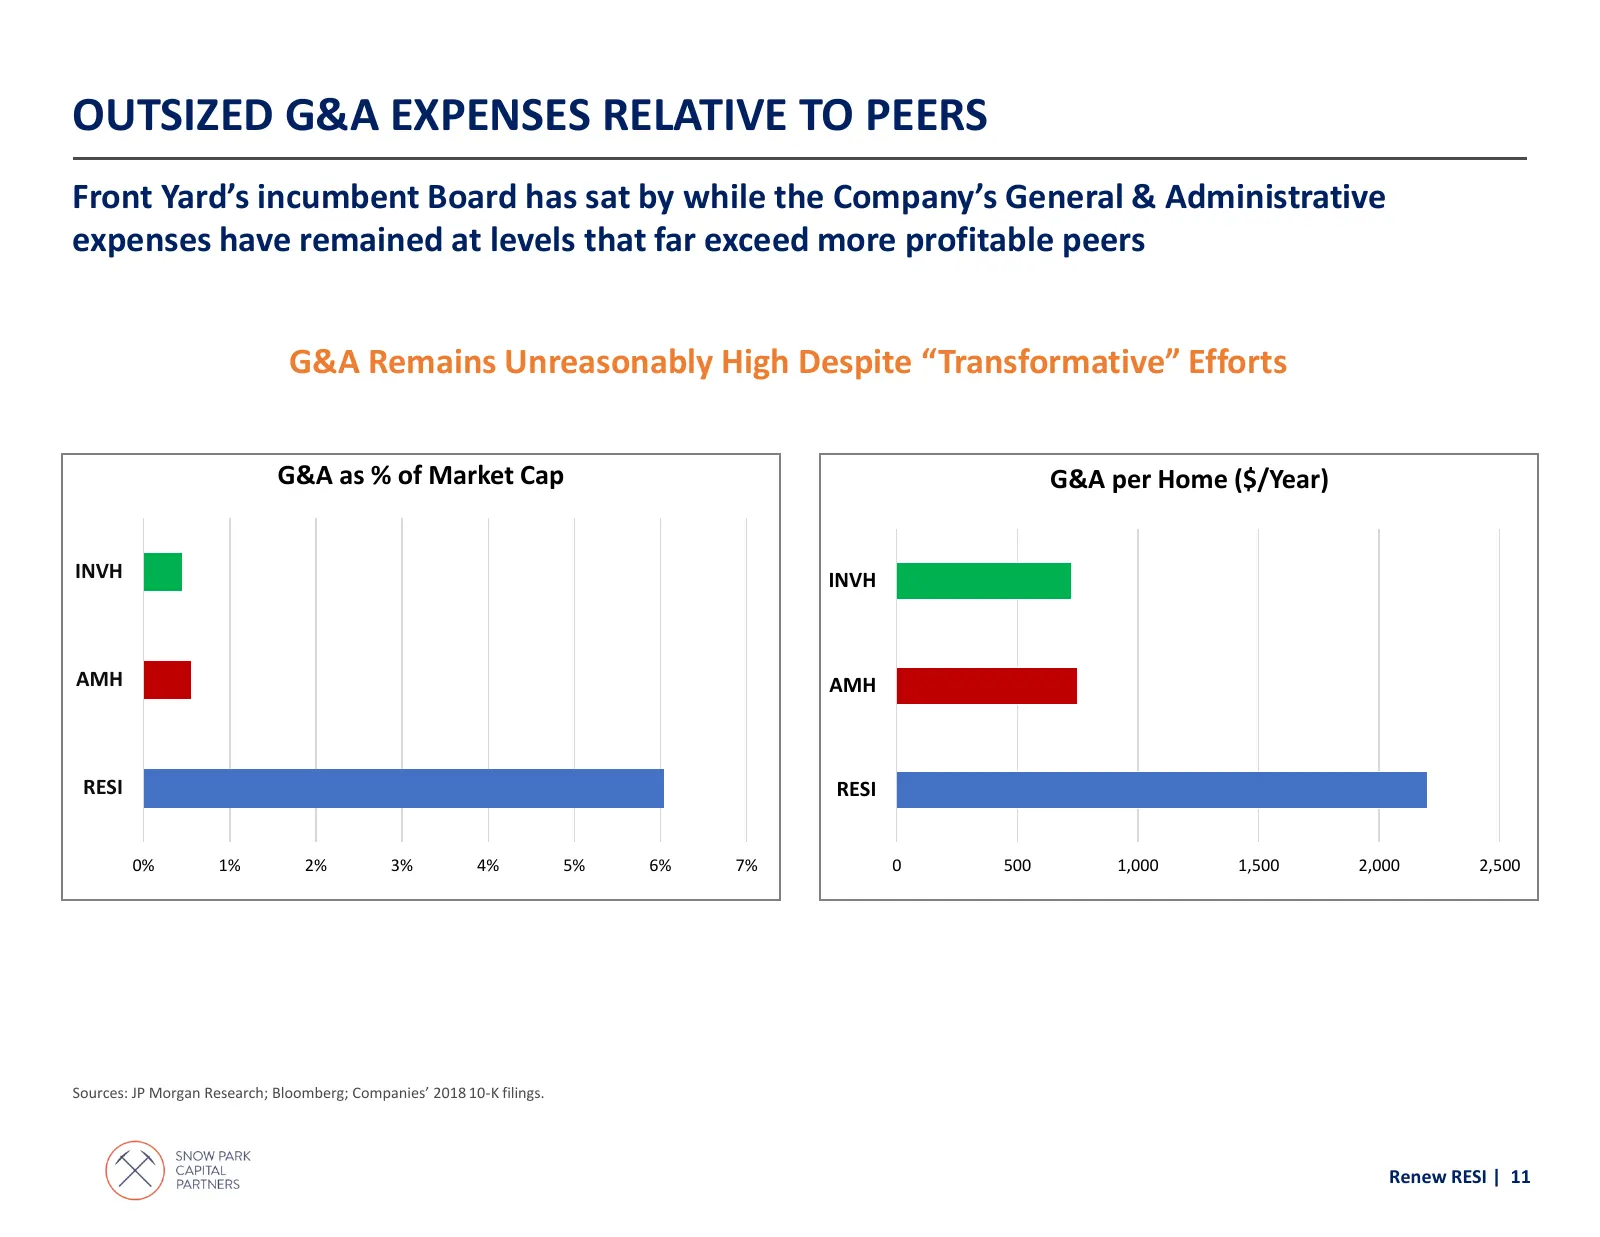
Slide 11: Outsized G&A Expenses Relative to Peers
OUTSIZED G&A EXPENSES RELATIVE TO PEERS Front Yard’s incumbent Board has sat by while the Company’s General & Administrative expenses have remained at levels that far exceed more profitable peers G&A Remains Unreasonably High Despite “Transformative” Efforts G&A as % of Market Cap G&A per Home ($/Ye
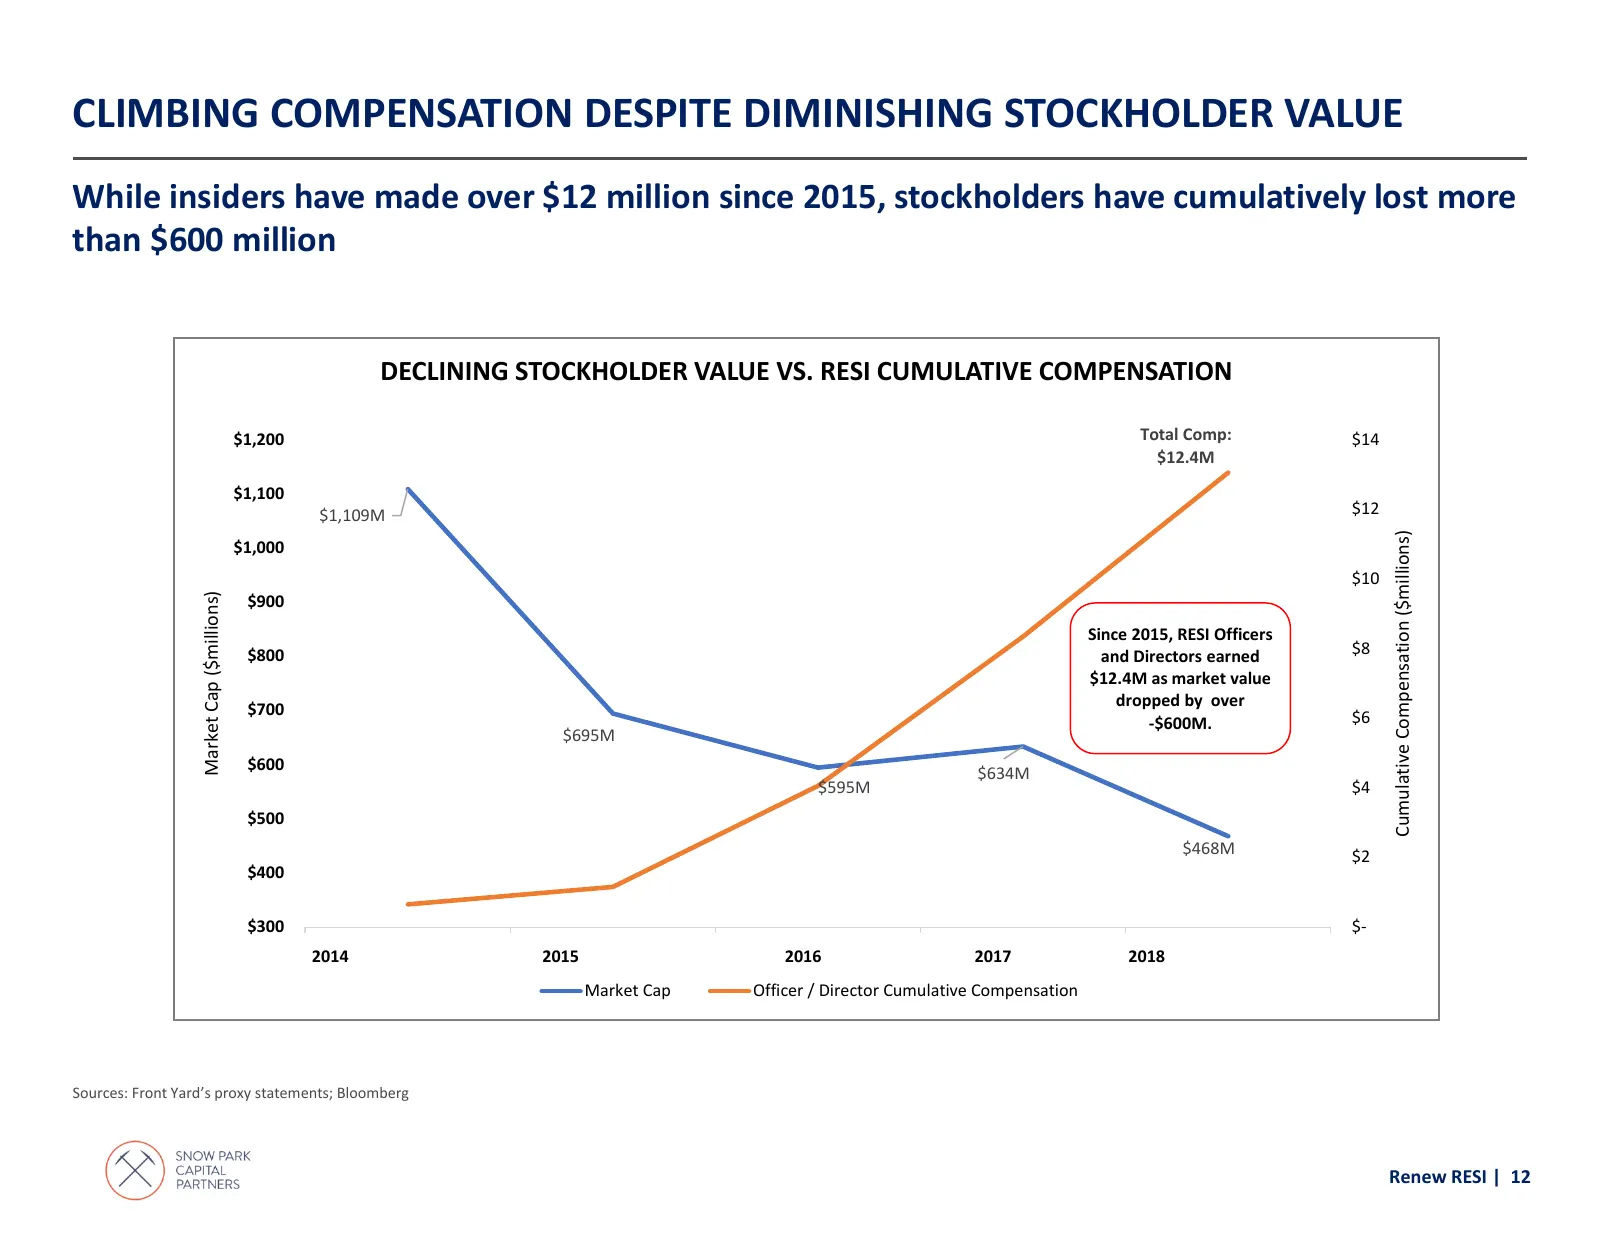
Slide 12: Climbing Compensation Despite Diminishing Stockholder Value
CLIMBING COMPENSATION DESPITE DIMINISHING STOCKHOLDER VALUE While insiders have made over $12 million since 2015, stockholders have cumulatively lost more than $600 million DECLINING STOCKHOLDER VALUE VS. RESI CUMULATIVE COMPENSATION $1,200 Total Comp: $14 $12.4M $1,100 $1,109M $12 Cumulative Compen
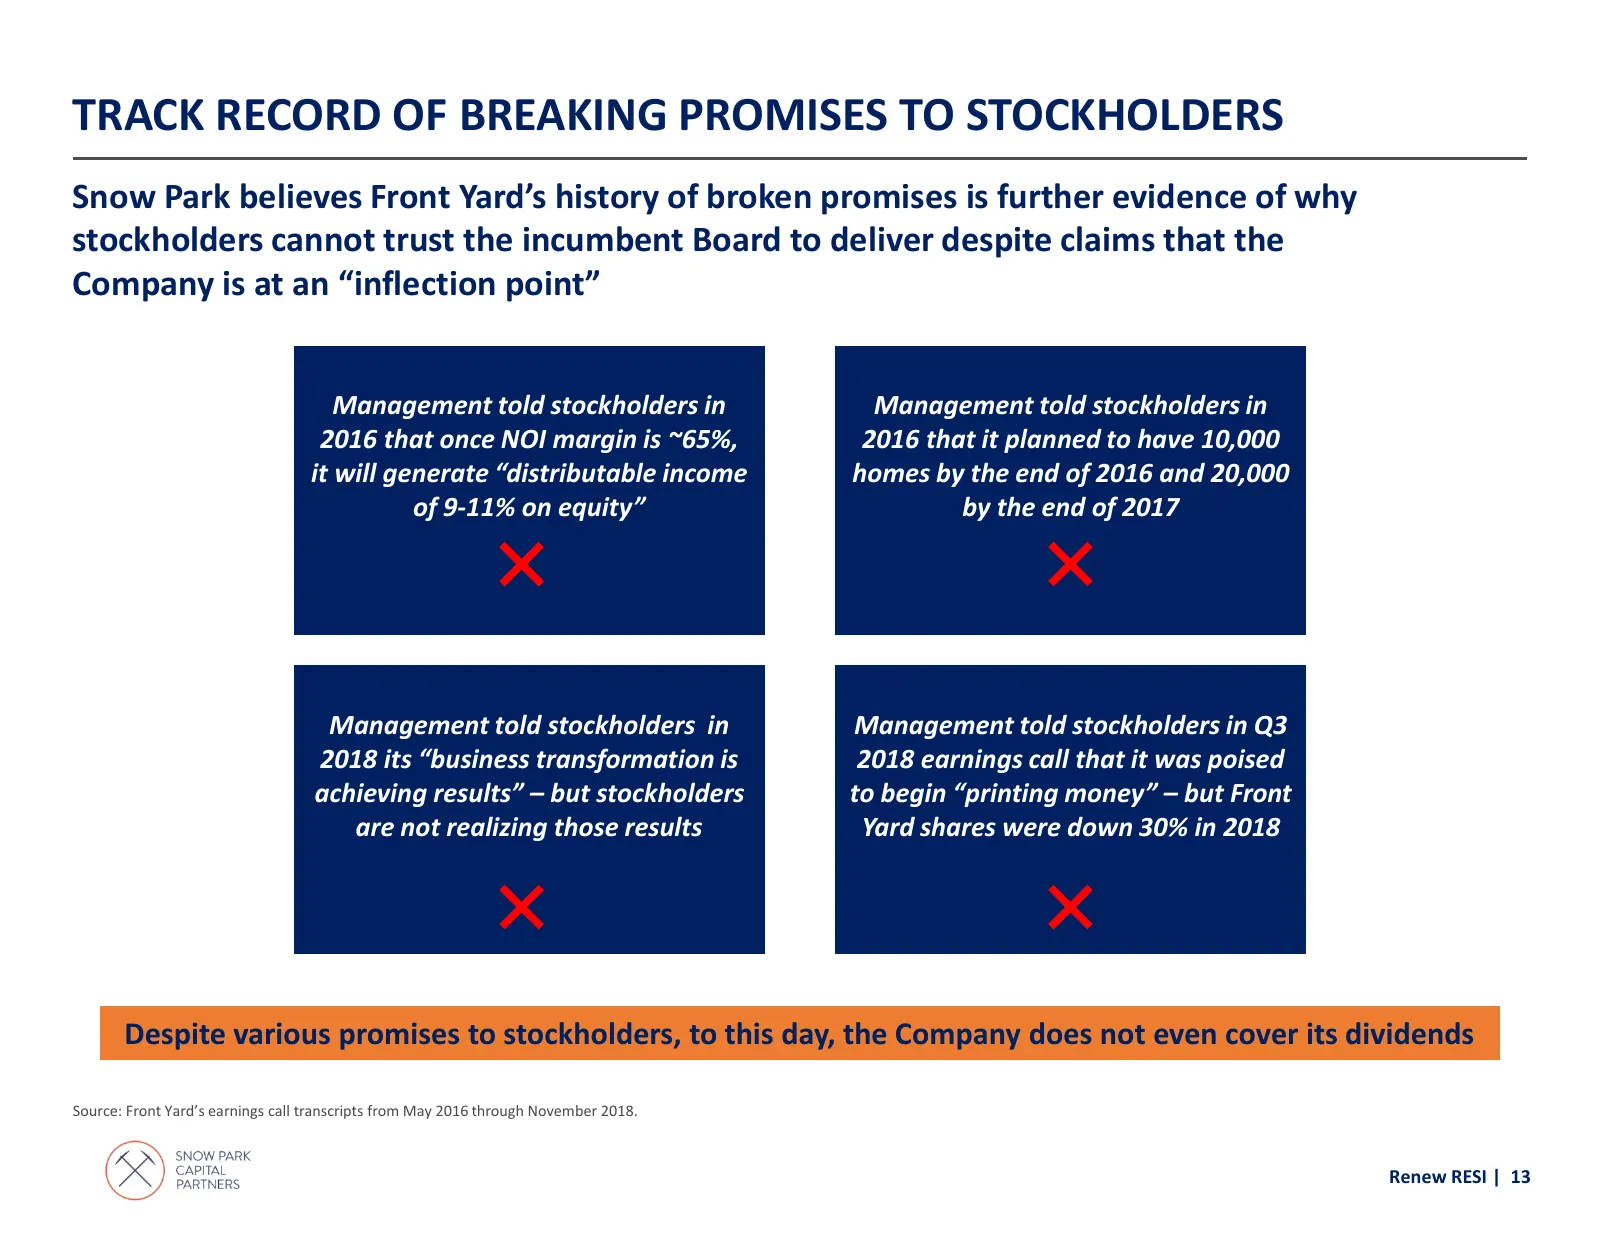
Slide 13: Track Record of Breaking Promises to Stockholders
TRACK RECORD OF BREAKING PROMISES TO STOCKHOLDERS Snow Park believes Front Yard’s history of broken promises is further evidence of why stockholders cannot trust the incumbent Board to deliver despite claims that the Company is at an “inflection point” Management told stockholders in Management told
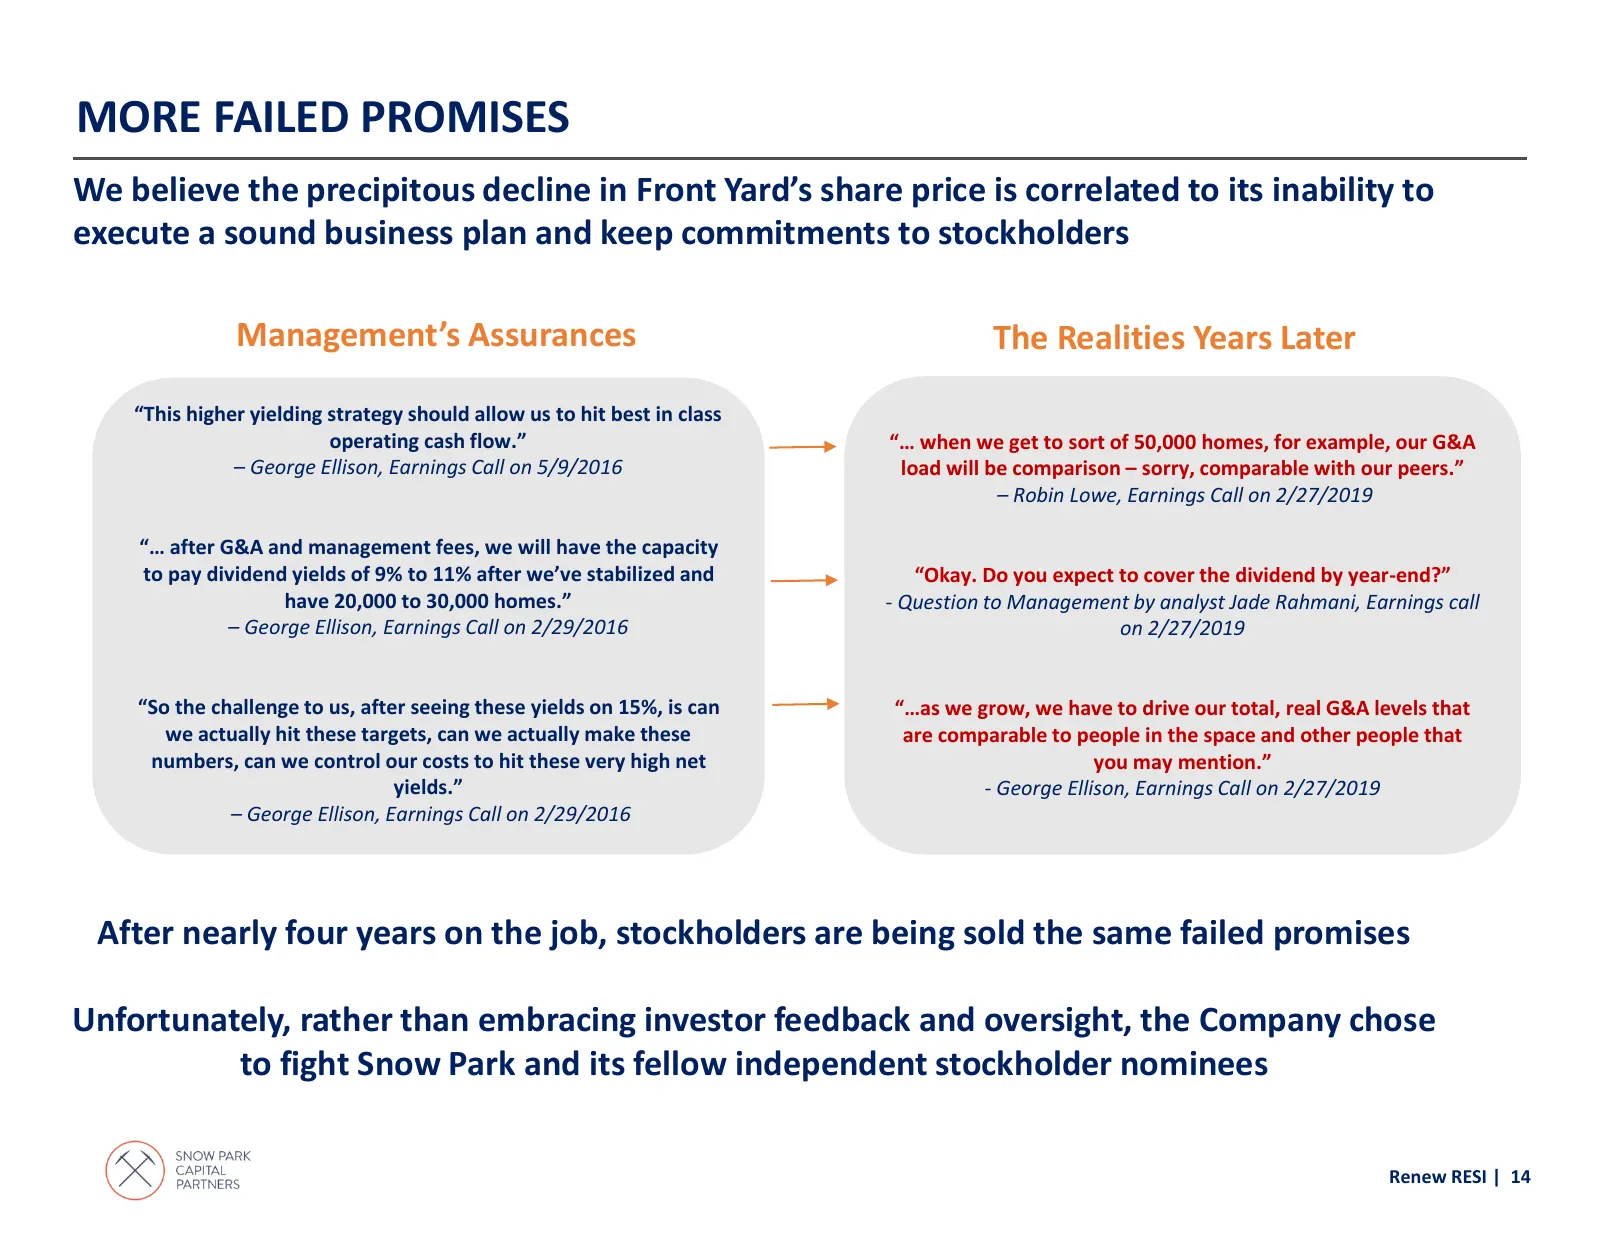
Slide 14: More Failed Promises
MORE FAILED PROMISES We believe the precipitous decline in Front Yard’s share price is correlated to its inability to execute a sound business plan and keep commitments to stockholders Management’s Assurances The Realities Years Later “This higher yielding strategy should allow us to hit best in cla
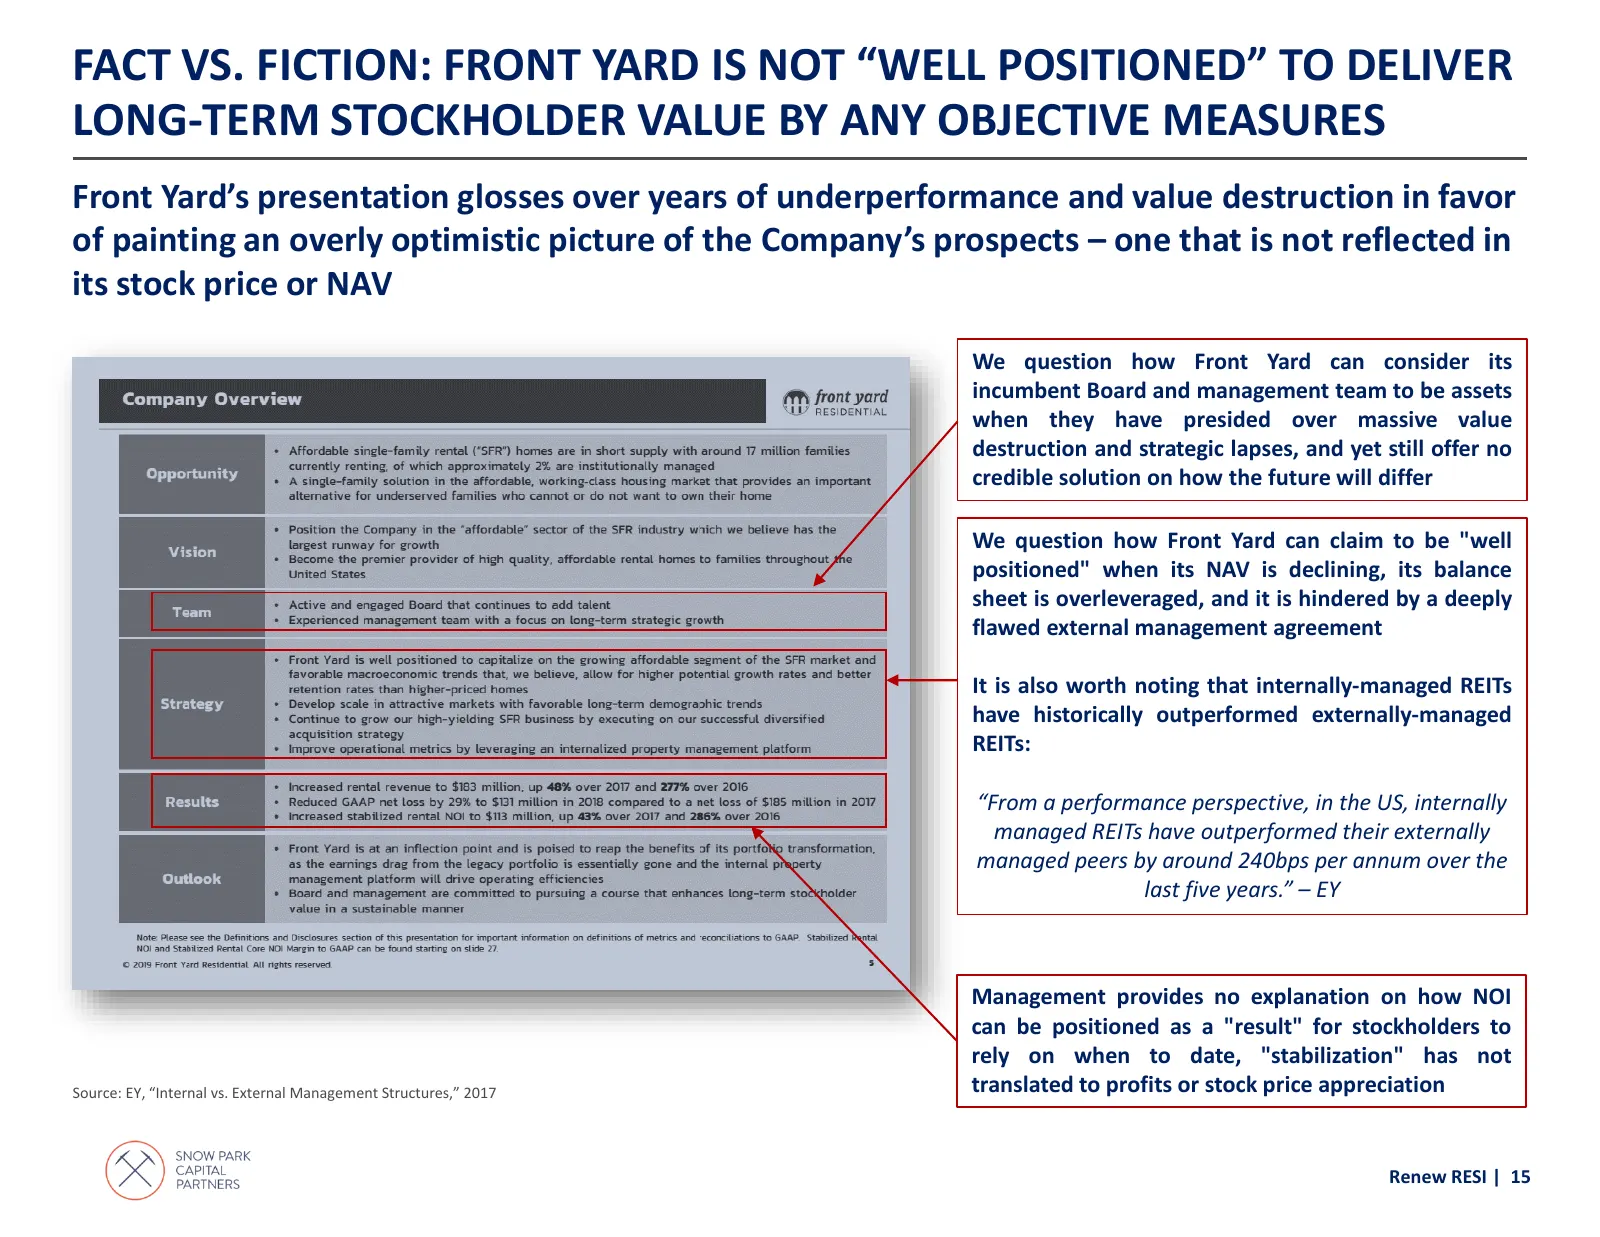
Slide 15: Fact vs. Fiction: Front Yard Is Not Well Positioned
FACT VS. FICTION: FRONT YARD IS NOT “WELL POSITIONED” TO DELIVER LONG-TERM STOCKHOLDER VALUE BY ANY OBJECTIVE MEASURES Front Yard’s presentation glosses over years of underperformance and value destruction in favor of painting an overly optimistic picture of the Company’s prospects – one that is not
Slide 16: Fact vs. Fiction: Increased NOI Is Meaningless Without Cashflows
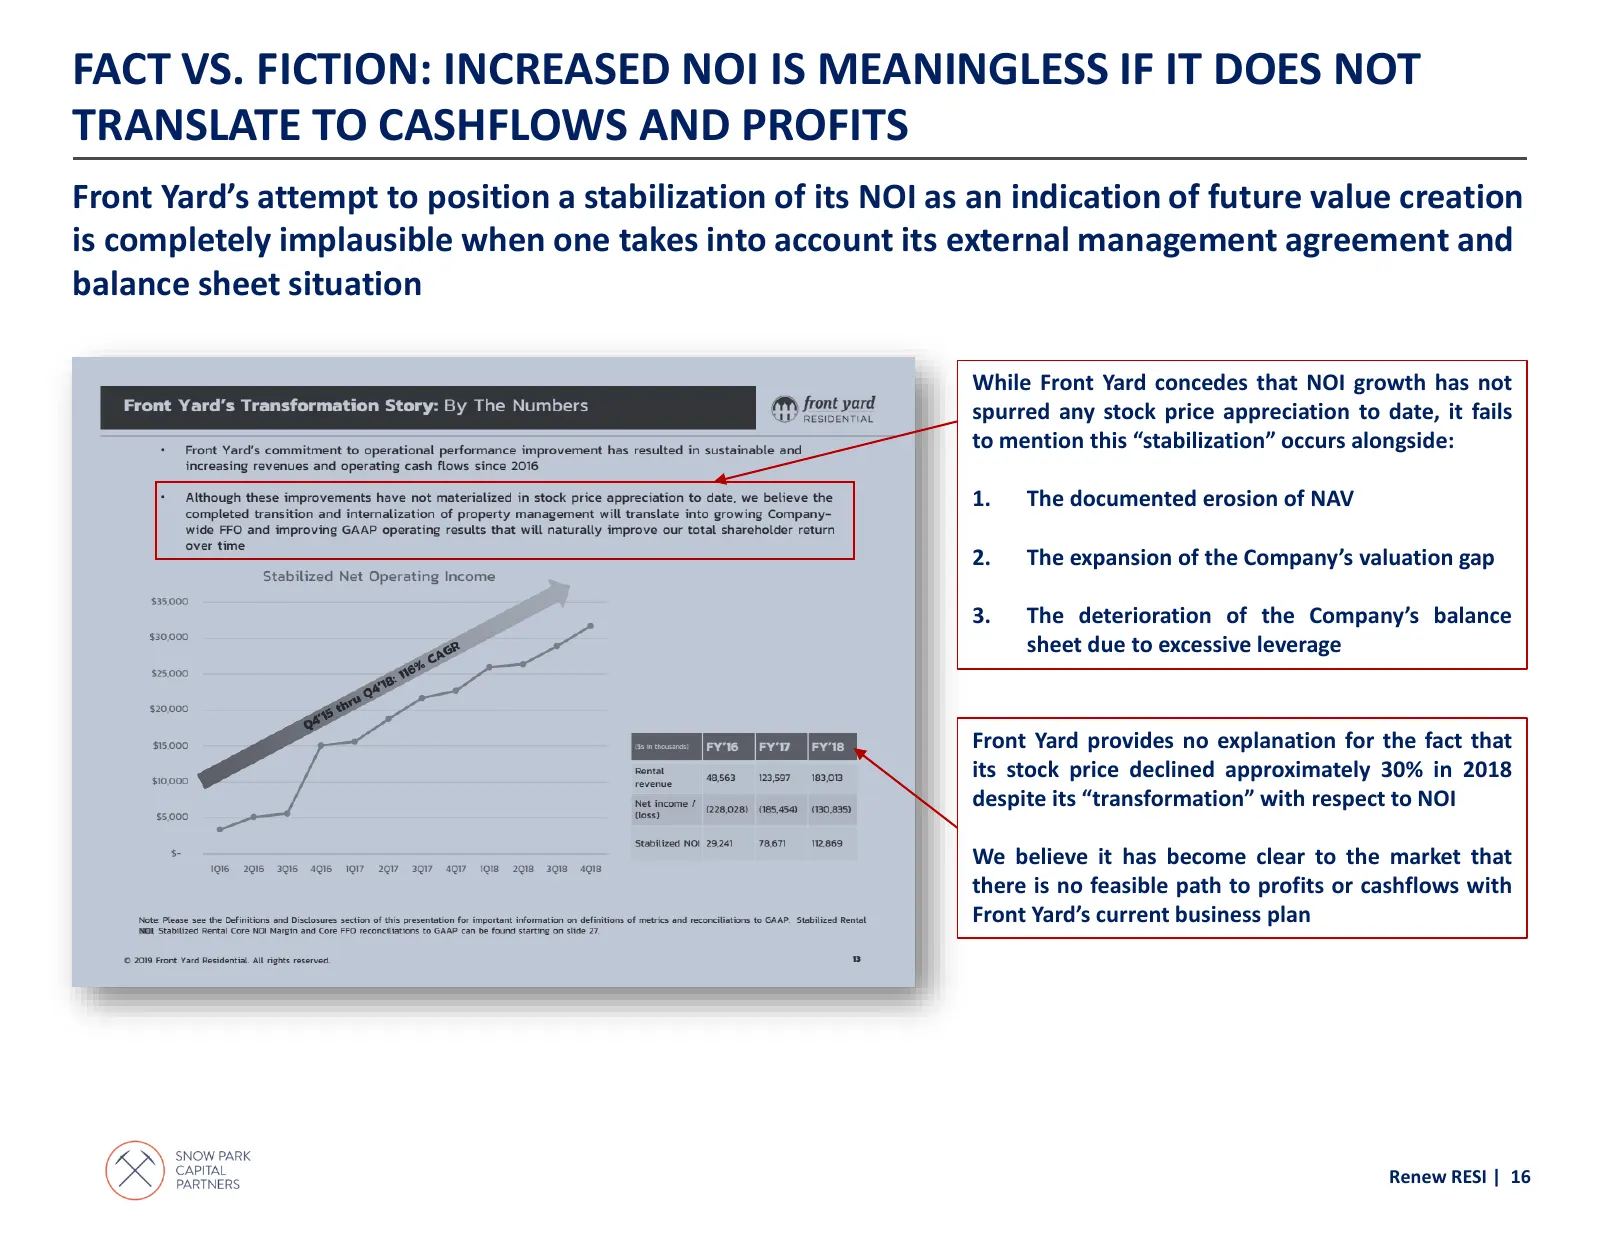
FACT VS. FICTION: INCREASED NOI IS MEANINGLESS IF IT DOES NOT TRANSLATE TO CASHFLOWS AND PROFITS Front Yard’s attempt to position a stabilization of its NOI as an indication of future value creation is completely implausible when one takes into account its external management agreement and balance s
Slide 17: Fact vs. Fiction: Analysts Do Not Have a Strong Outlook
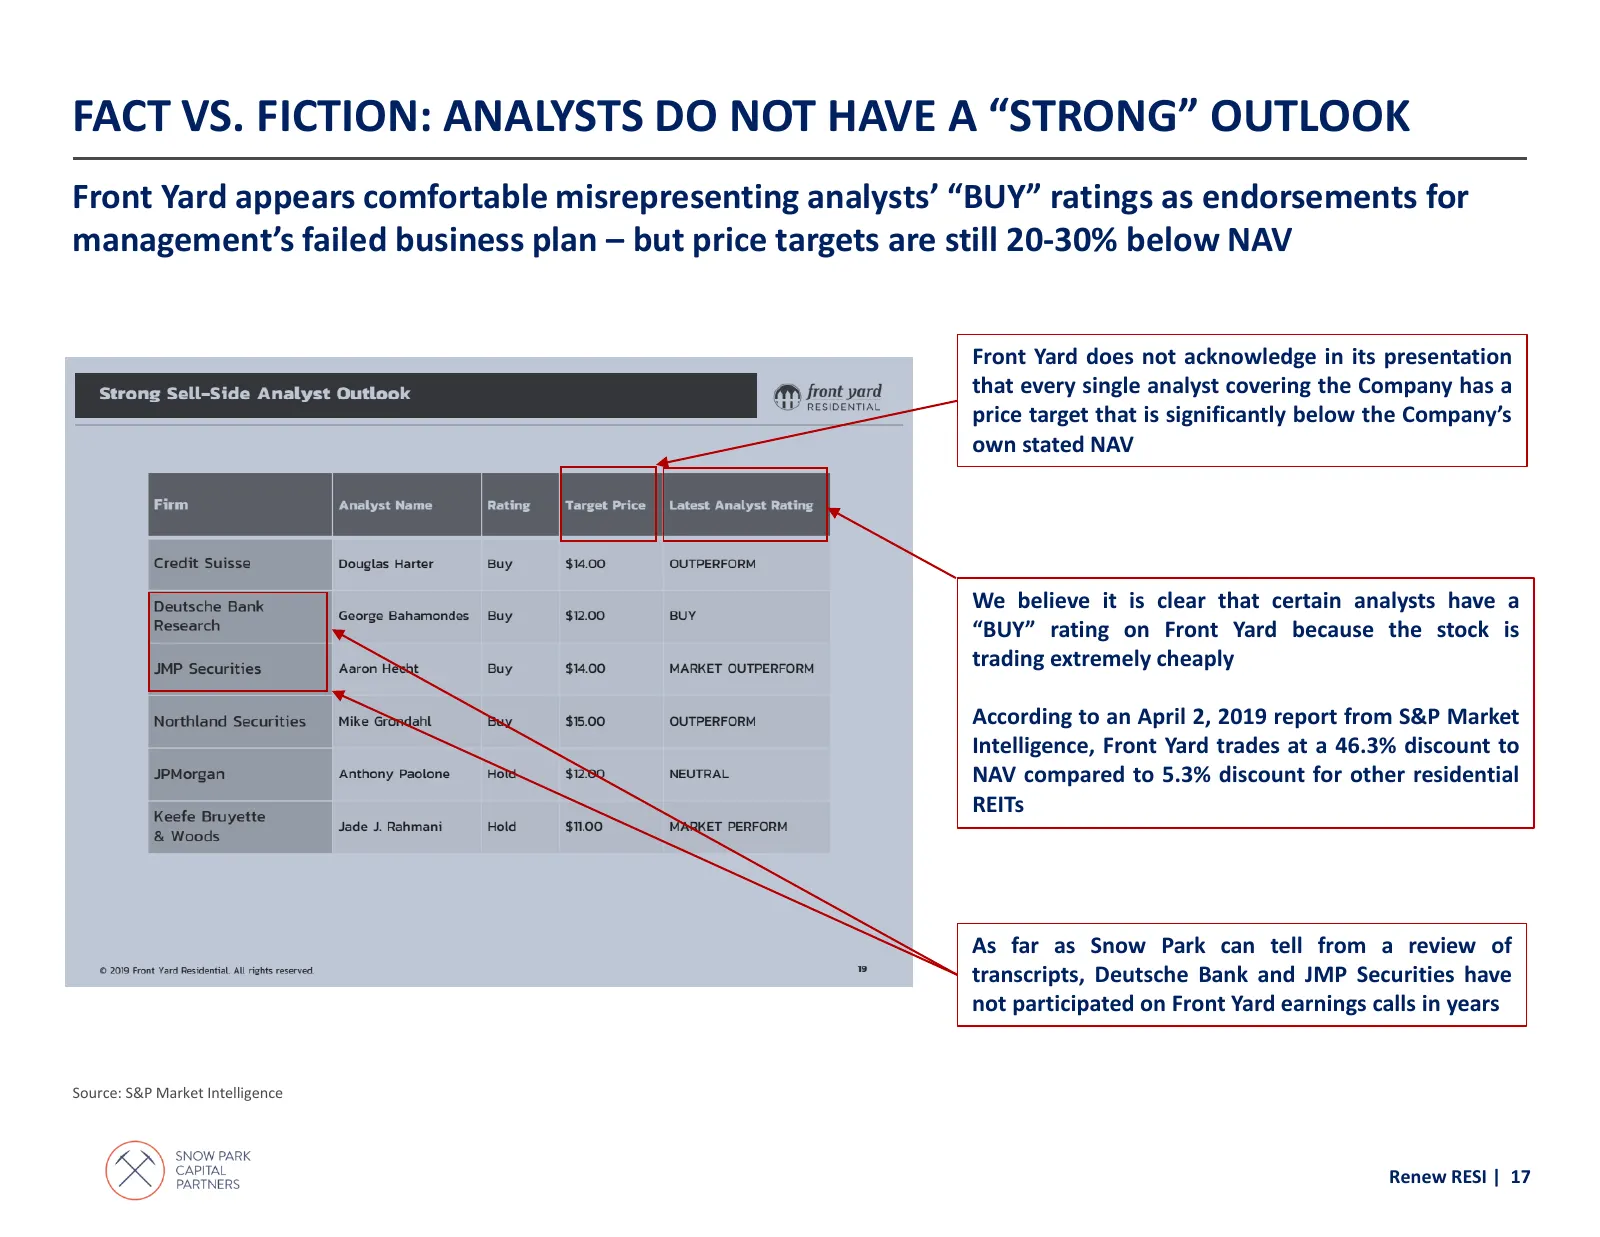
FACT VS. FICTION: ANALYSTS DO NOT HAVE A “STRONG” OUTLOOK Front Yard appears comfortable misrepresenting analysts’ “BUY” ratings as endorsements for management’s failed business plan – but price targets are still 20-30% below NAV Front Yard does not acknowledge in its presentation that every single
Slide 18: Fact vs. Fiction: HavenBrook Deal Has Further Eroded Value
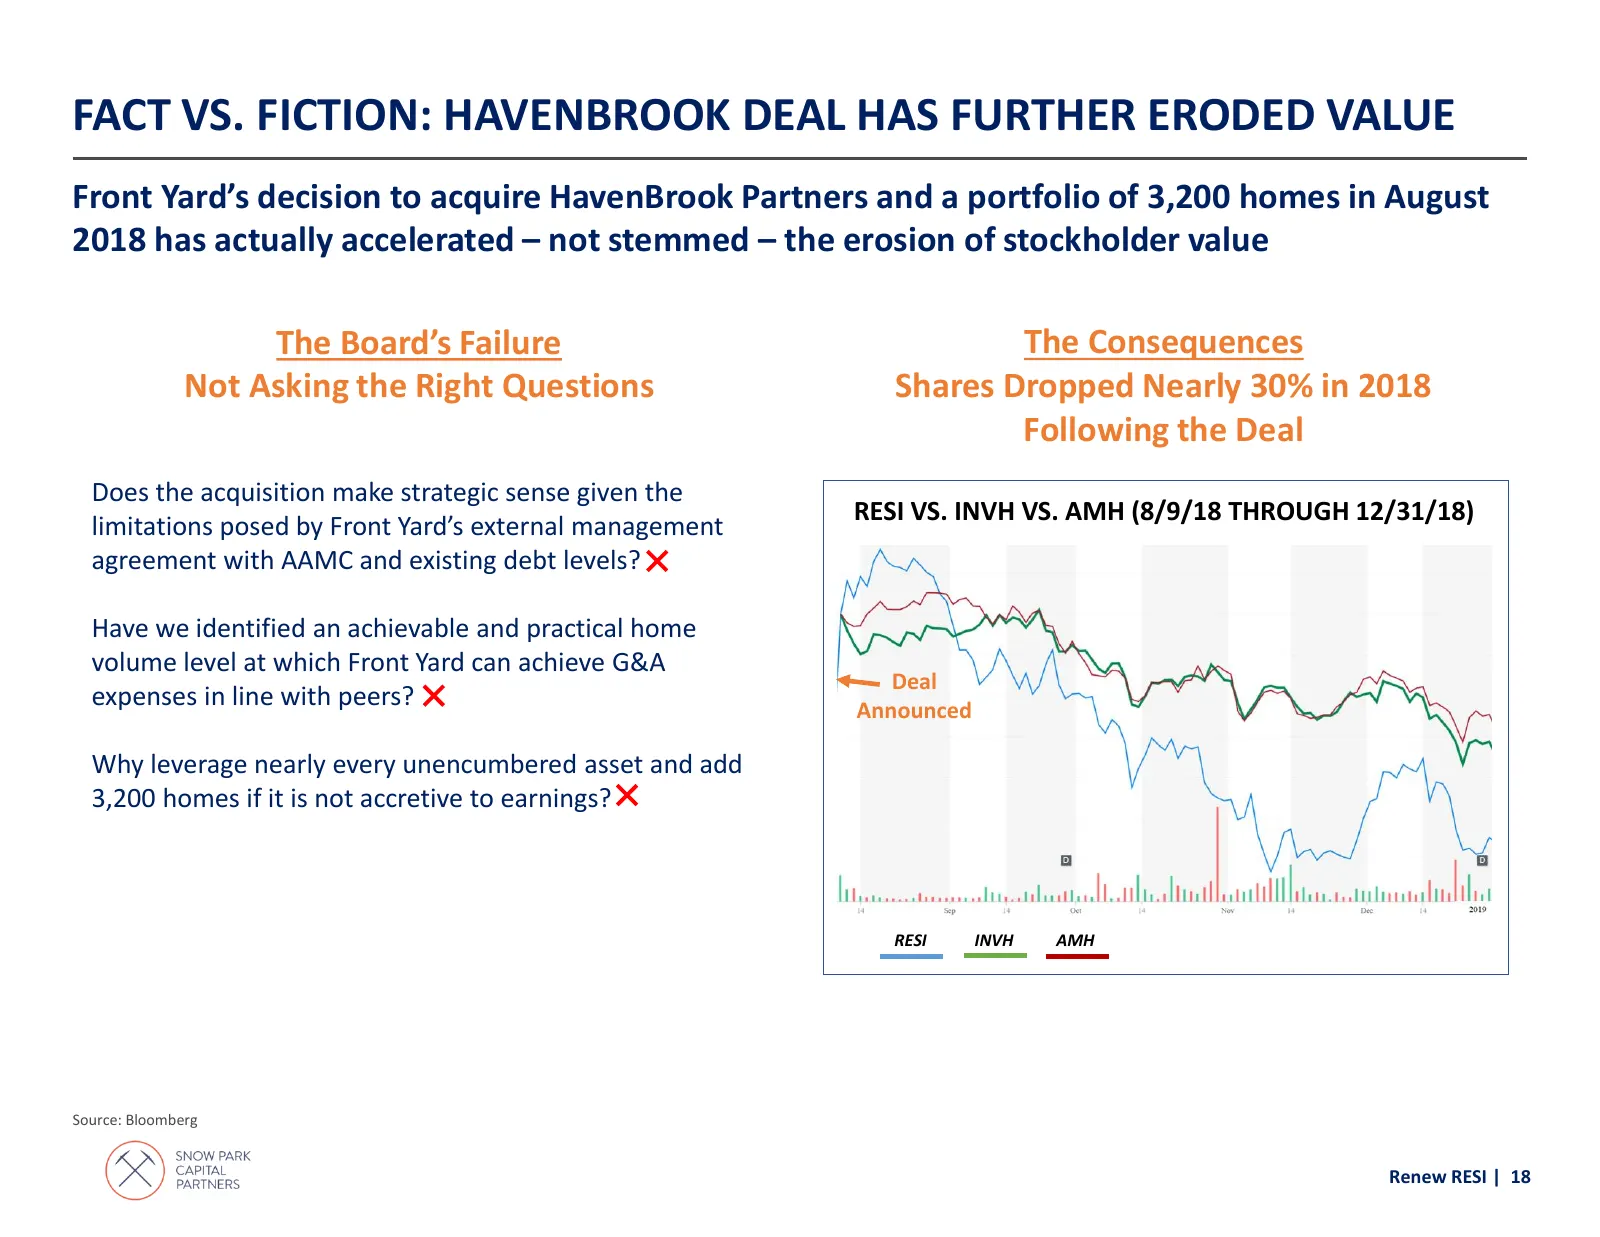
FACT VS. FICTION: HAVENBROOK DEAL HAS FURTHER ERODED VALUE Front Yard’s decision to acquire HavenBrook Partners and a portfolio of 3,200 homes in August 2018 has actually accelerated – not stemmed – the erosion of stockholder value The Board’s Failure The Consequences Not Asking the Right Questions
Slide 19: The Real Conflicts Exist in the Boardroom
THE REAL CONFLICTS EXIST IN THE BOARDROOM Despite the fact that Front Yard is seemingly comfortable attacking and disparaging Snow Park, the true conflicts impacting stockholders exist among management and the Board CEO George Ellison supported the George Ellison is CEO of both George Ellison held l
Slide 20: The Snow Park Slate's Qualifications and Vision
The Snow Park Slate’s Qualifications and Vision
Slide 21: Leland Abrams
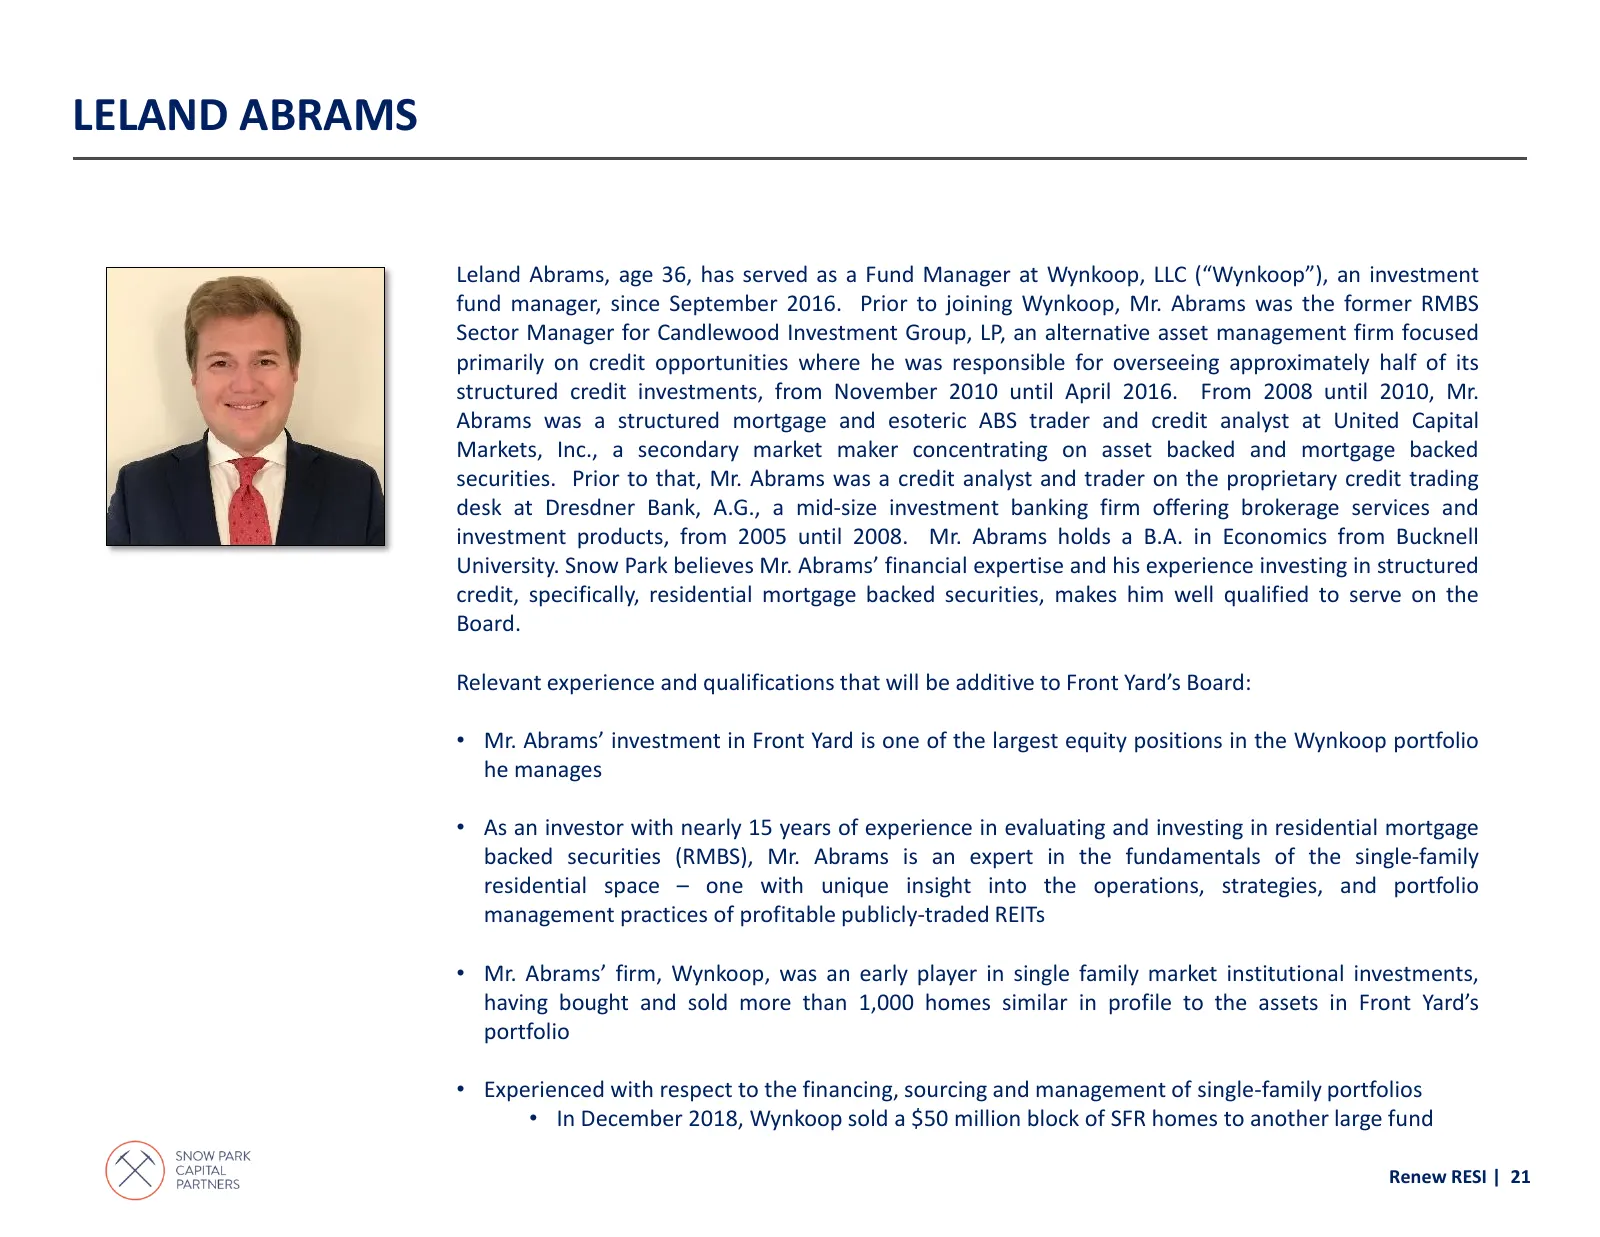
LELAND ABRAMS Leland Abrams, age 36, has served as a Fund Manager at Wynkoop, LLC (“Wynkoop”), an investment fund manager, since September 2016. Prior to joining Wynkoop, Mr. Abrams was the former RMBS Sector Manager for Candlewood Investment Group, LP, an alternative asset management firm focused p
Slide 22: Lazar Nikolic
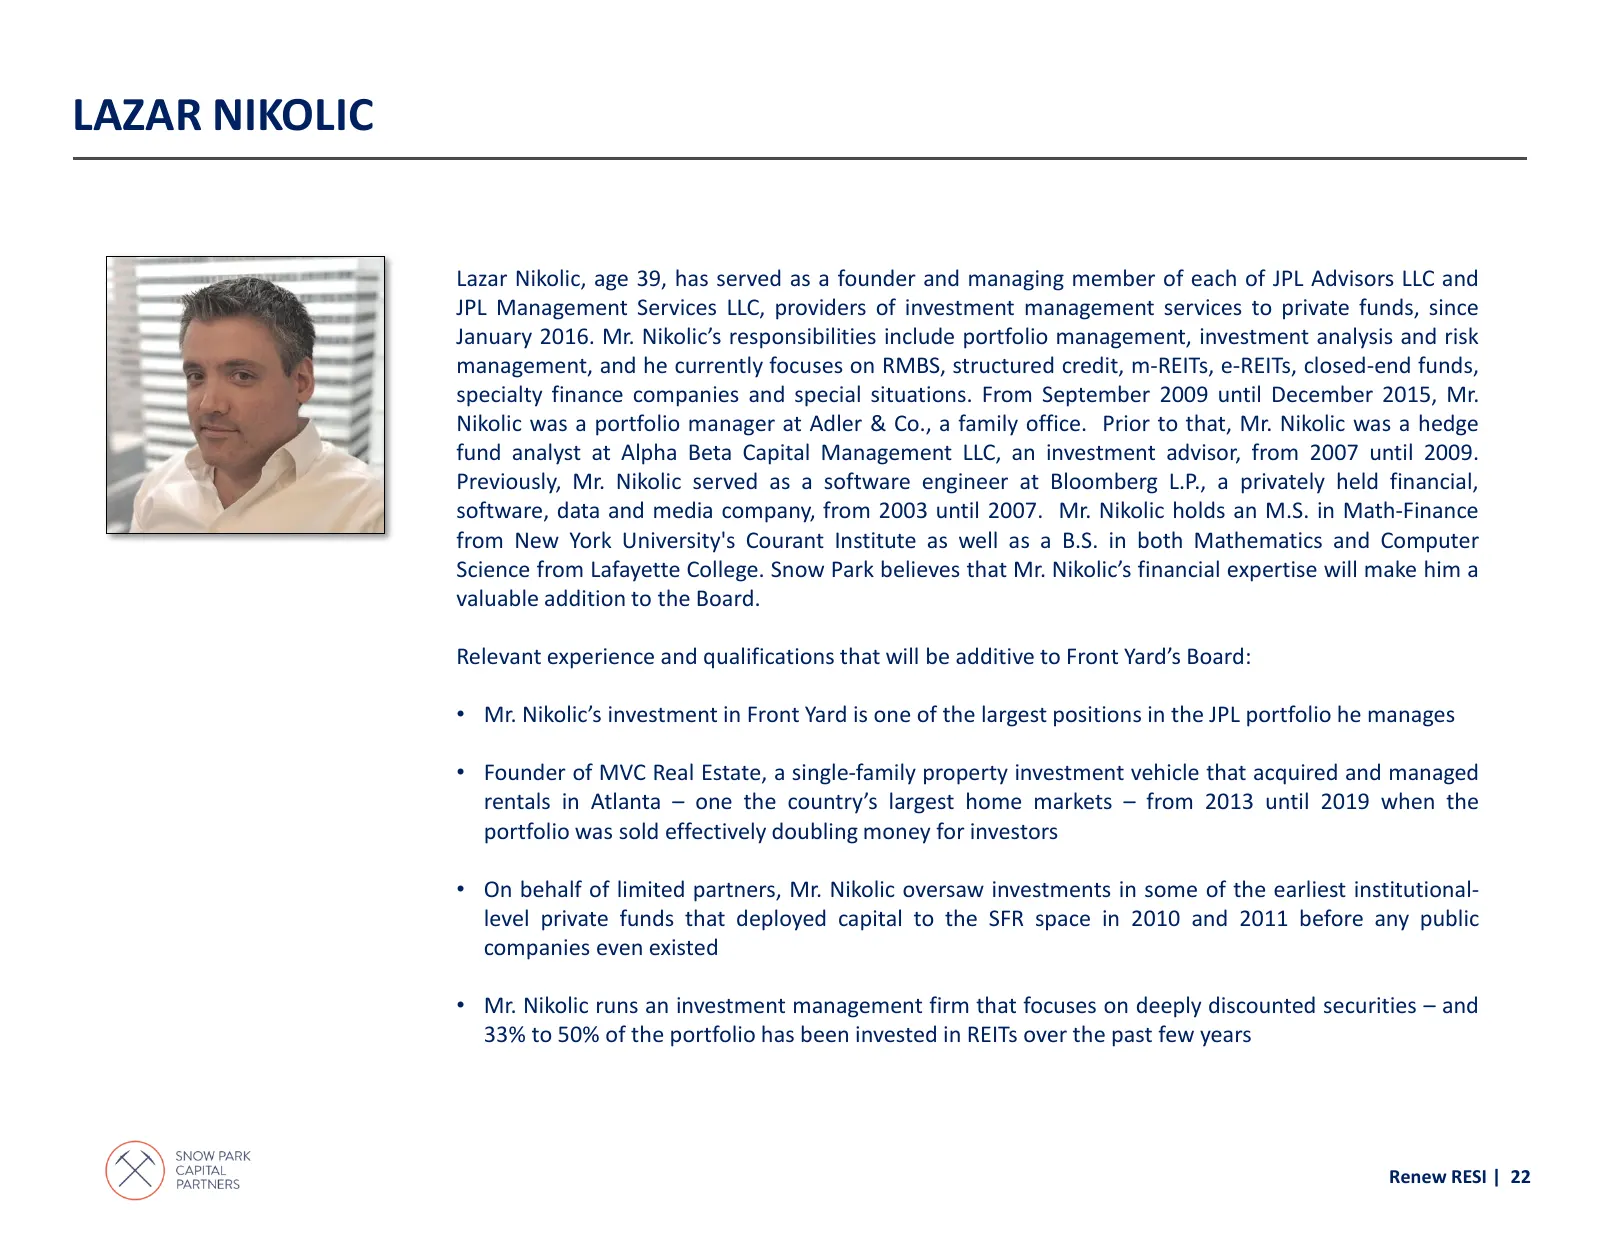
LAZAR NIKOLIC Lazar Nikolic, age 39, has served as a founder and managing member of each of JPL Advisors LLC and JPL Management Services LLC, providers of investment management services to private funds, since January 2016. Mr. Nikolic’s responsibilities include portfolio management, investment anal
Slide 23: Jeffrey Pierce
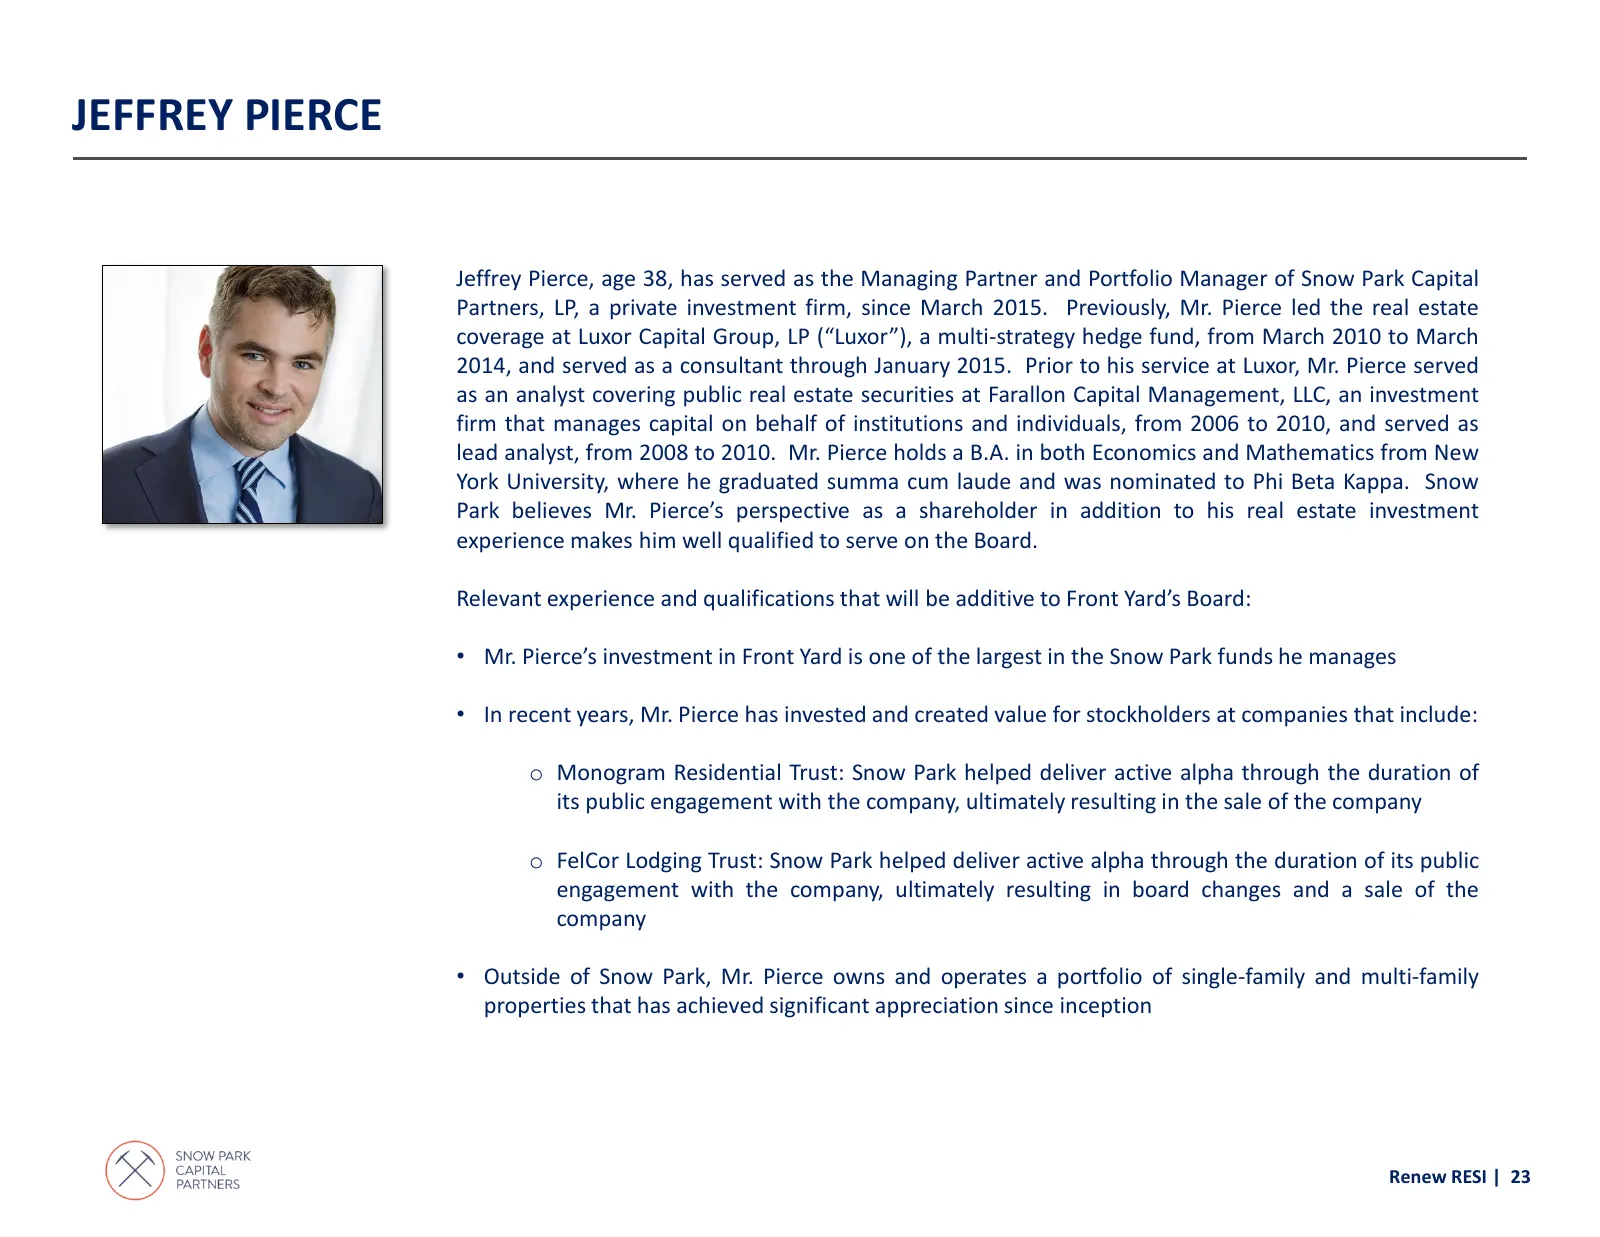
JEFFREY PIERCE Jeffrey Pierce, age 38, has served as the Managing Partner and Portfolio Manager of Snow Park Capital Partners, LP, a private investment firm, since March 2015. Previously, Mr. Pierce led the real estate coverage at Luxor Capital Group, LP (“Luxor”), a multi-strategy hedge fund, from
Slide 24: Our Slate Stands for a Full and Fair Strategic Review
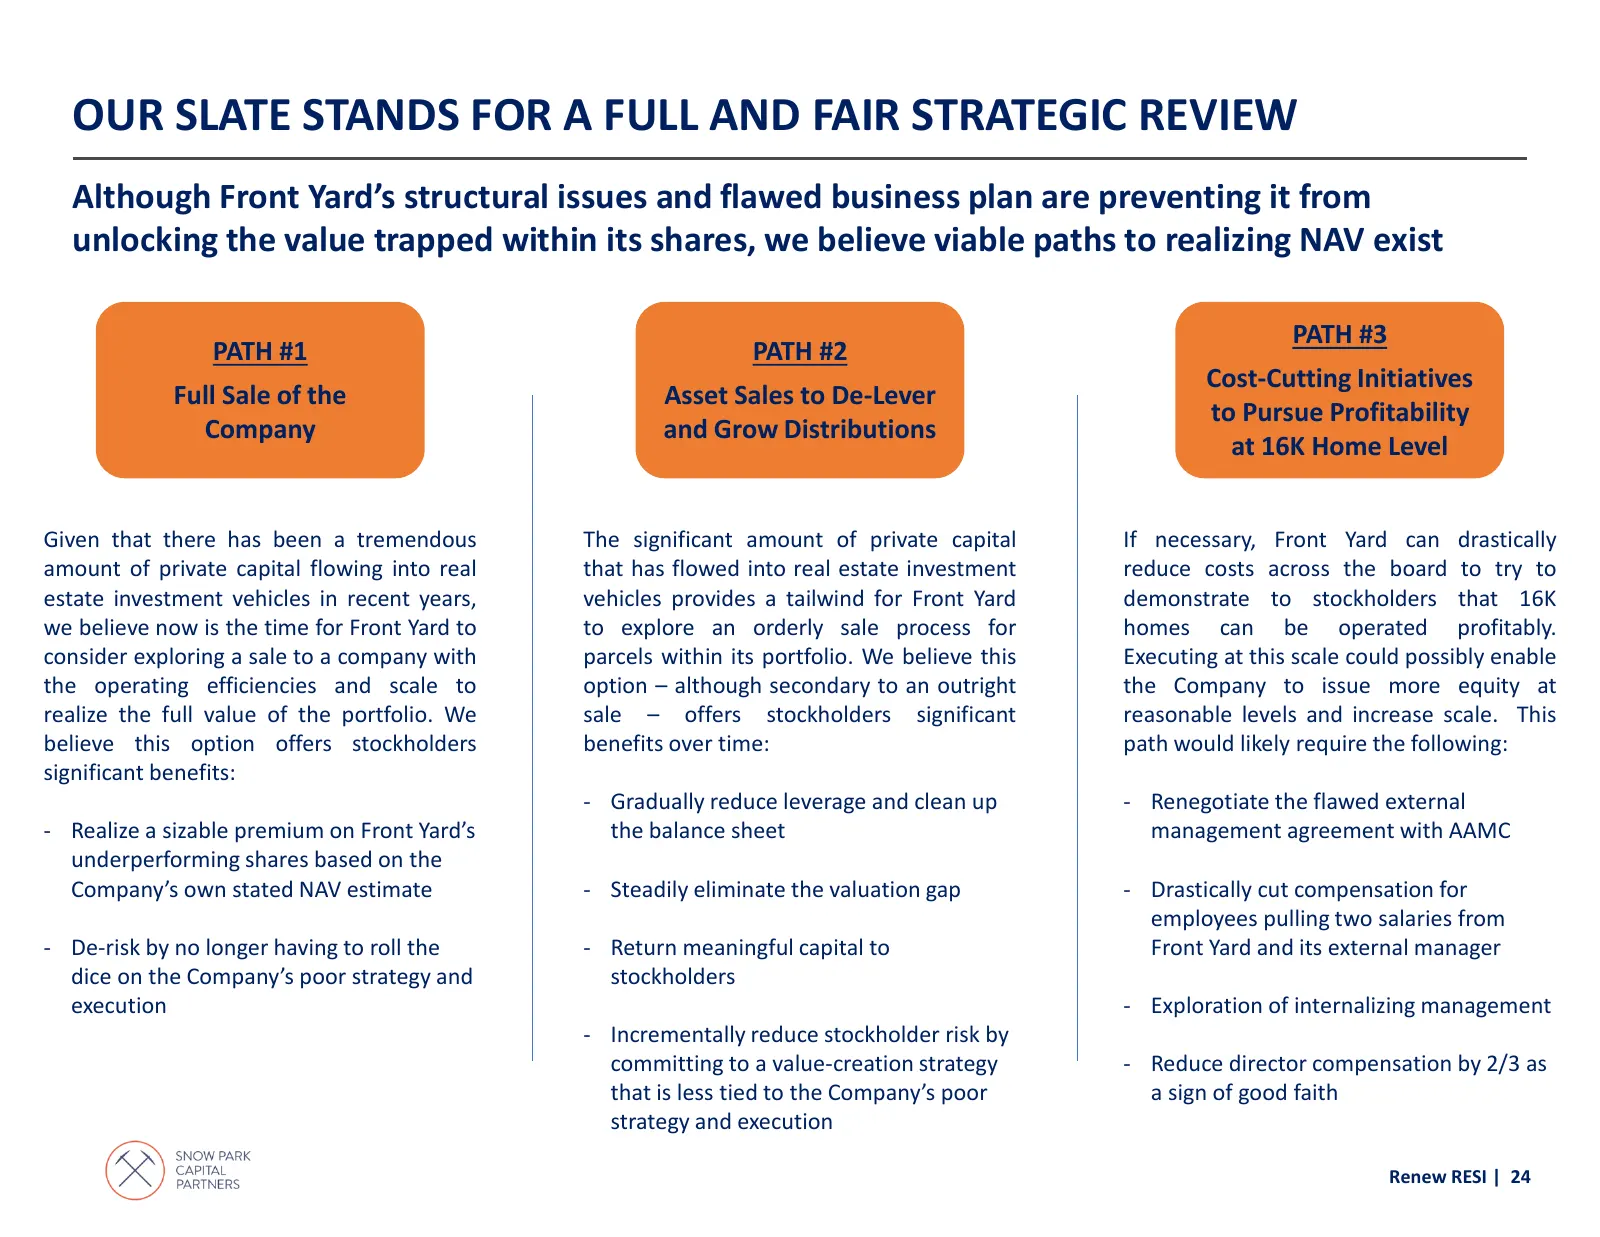
OUR SLATE STANDS FOR A FULL AND FAIR STRATEGIC REVIEW Although Front Yard’s structural issues and flawed business plan are preventing it from unlocking the value trapped within its shares, we believe viable paths to realizing NAV exist PATH #3 PATH #1 PATH #2 Cost-Cutting Initiatives Full Sale of th
Slide 25: Alignment of Interests: Our Nominees vs. Management and the Board
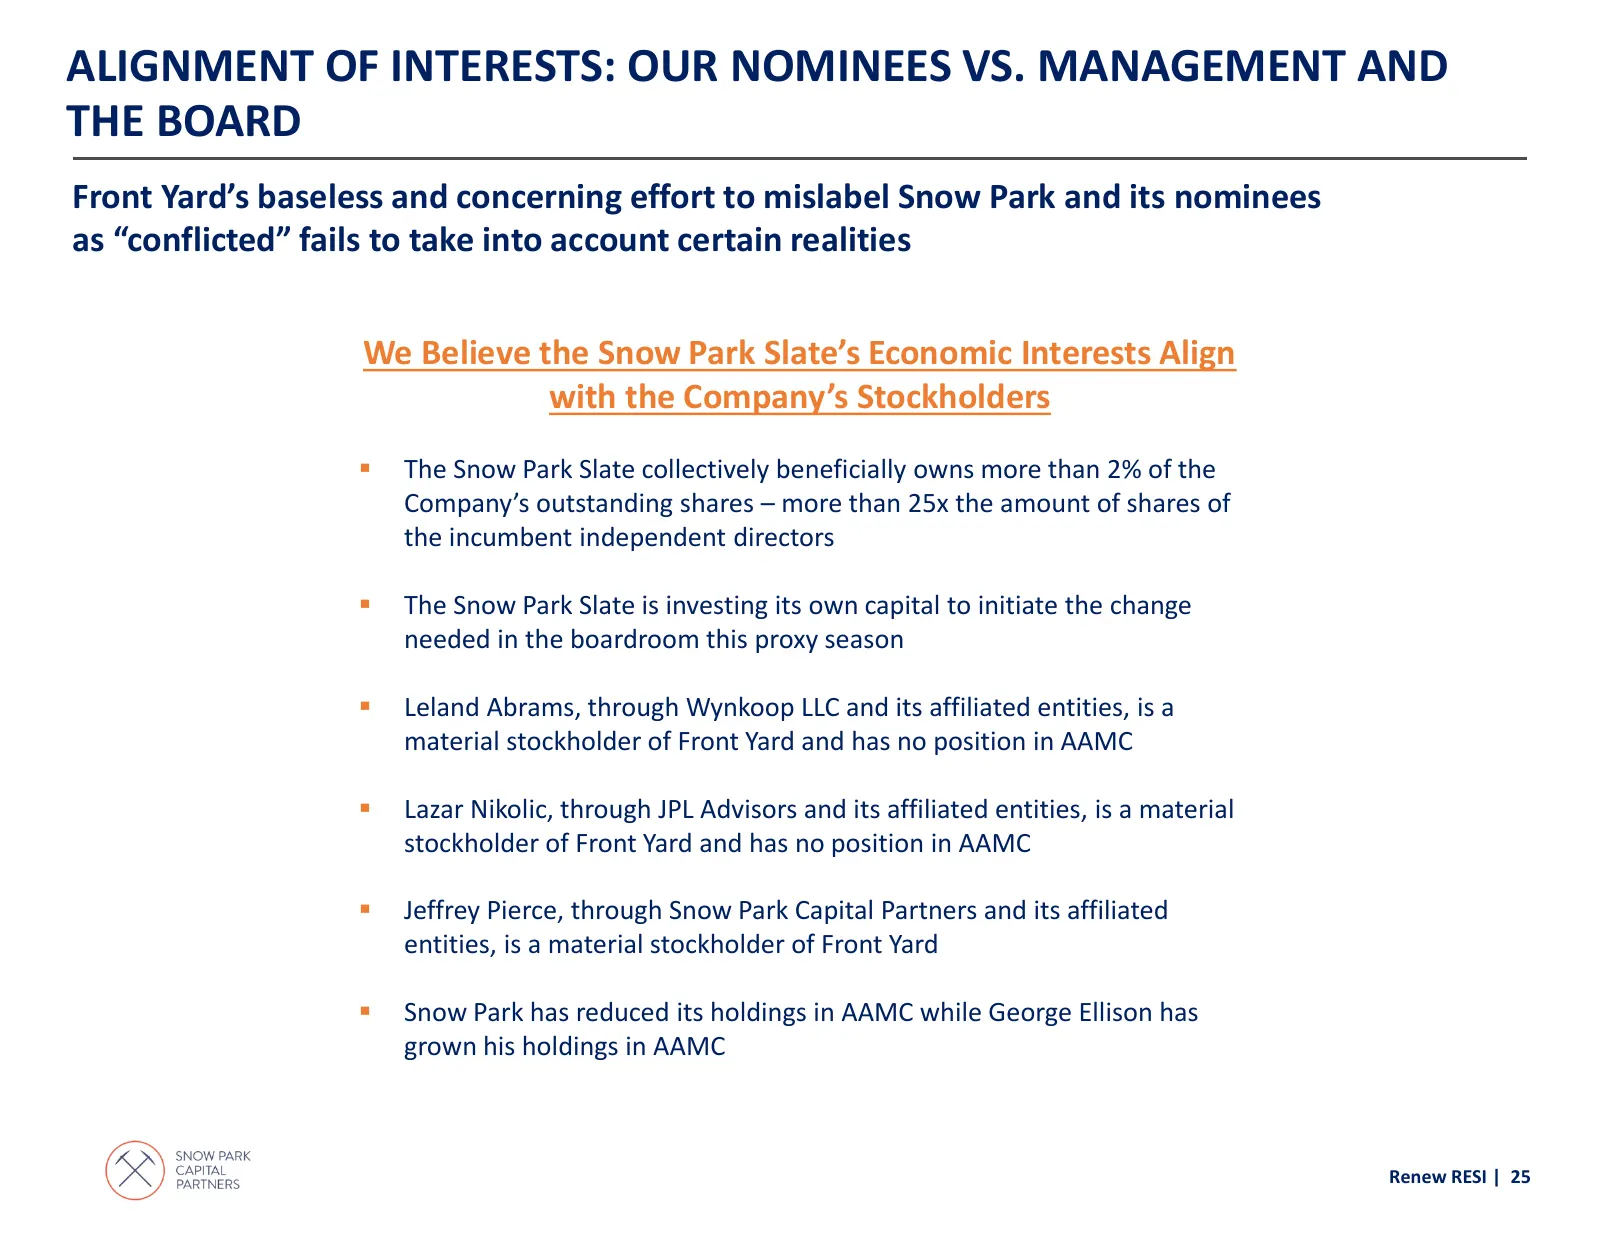
ALIGNMENT OF INTERESTS: OUR NOMINEES VS. MANAGEMENT AND THE BOARD Front Yard’s baseless and concerning effort to mislabel Snow Park and its nominees as “conflicted” fails to take into account certain realities We Believe the Snow Park Slate’s Economic Interests Align with the Company’s Stockholders
Slide 26: Board Quality Is a Critical Issue: Nominee Comparison
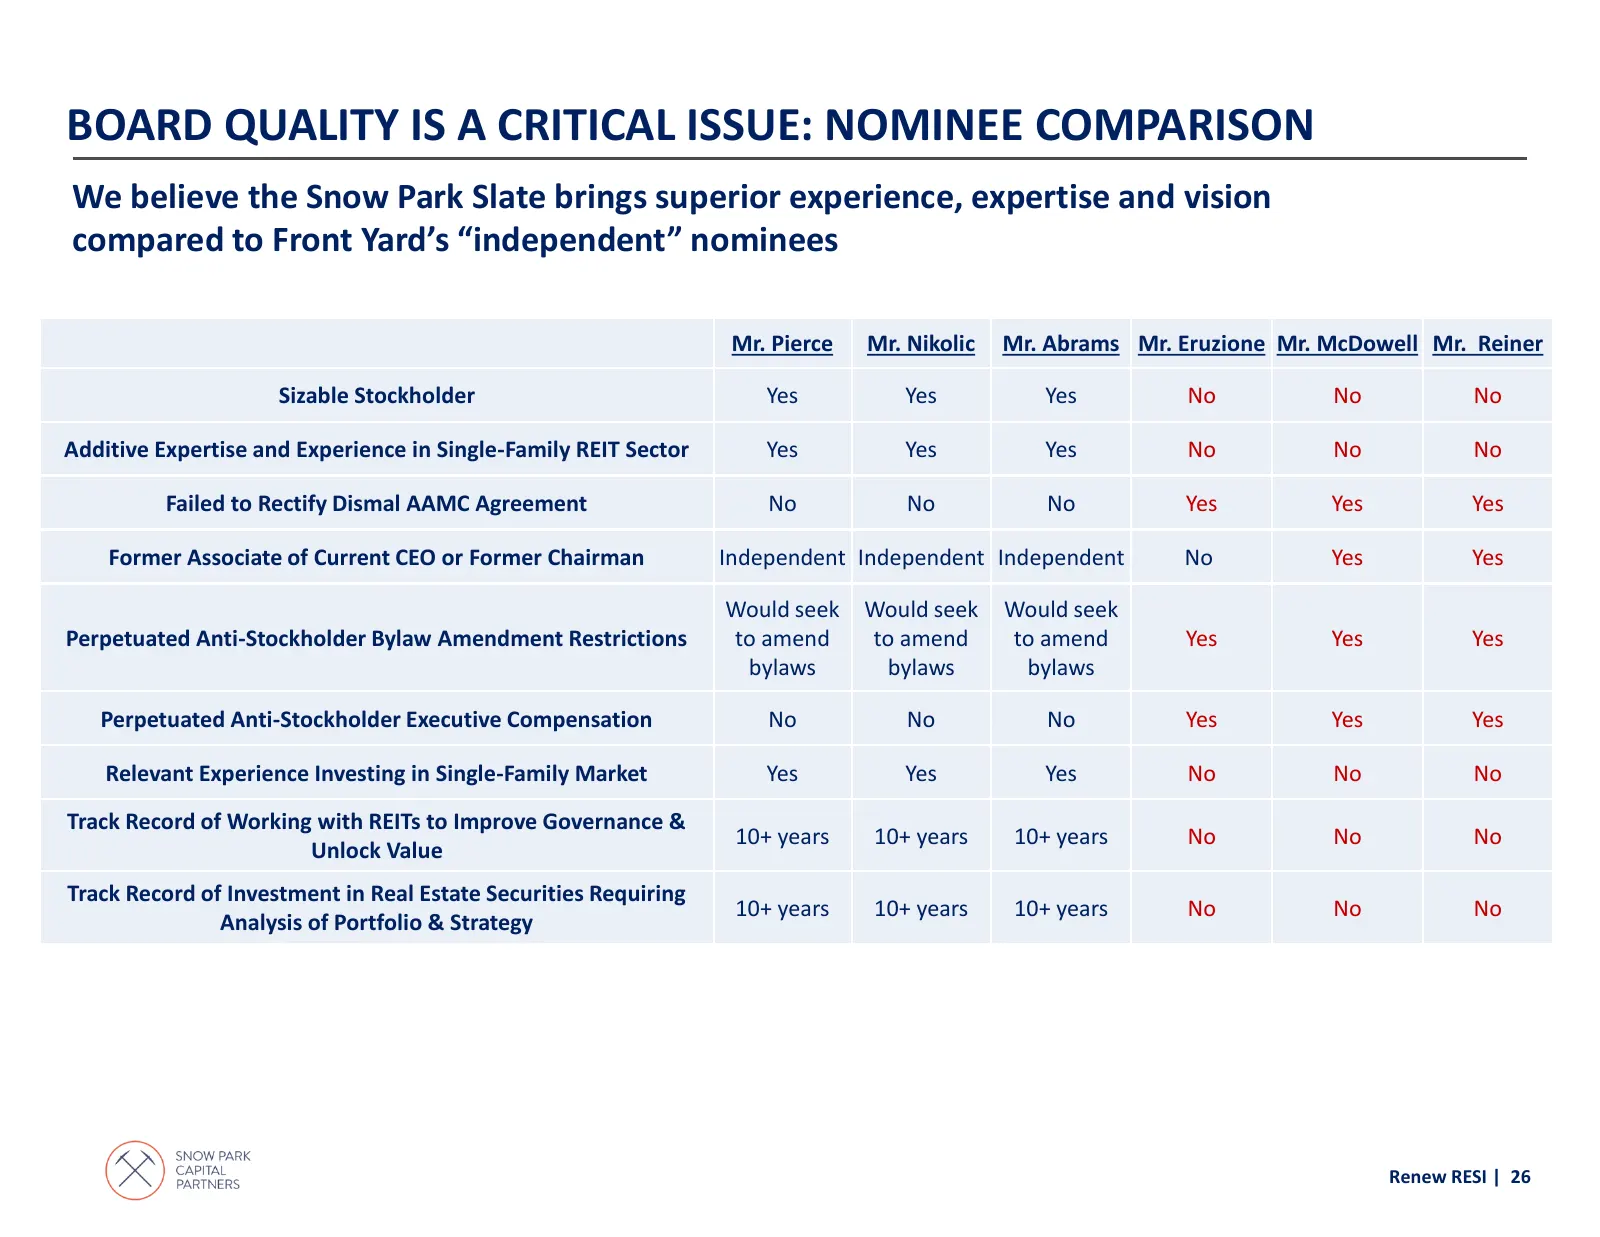
BOARD QUALITY IS A CRITICAL ISSUE: NOMINEE COMPARISON We believe the Snow Park Slate brings superior experience, expertise and vision compared to Front Yard’s “independent” nominees Mr. Pierce Mr. Nikolic Mr. Abrams Mr. Eruzione Mr. McDowell Mr. Reiner Sizable Stockholder Yes Yes Yes No No No Additi
Slide 27: Vote the Blue Proxy Card to Disrupt the Unacceptable Status Quo
VOTE THE BLUE PROXY CARD TO DISRUPT THE UNACCEPTABLE STATUS QUO AT FRONT YARD
Source: SEC EDGAR · DFAN14A filed May 7, 2019