Scpie — Proxy Contest (March 2008)
23 slides from Scpie's proxy contest presentation, Mar 12, 2008
Slide 1: Schedule 14A Proxy Statement Information
SCHEDULE 14A (RULE 14A-101) INFORMATION REQUIRED IN PROXY STATEMENT SCHEDULE 14A INFORMATION PROXY STATEMENT PURSUANT TO SECTION 14(a) OF THE SECURITIES EXCHANGE ACT OF 1934 (Amendment No. __) Filed by the registrant o Filed by a party other than the registrant x Check the appropriate box: o Prelimi
Slide 2: Schedule 14A filing fee information
(4) Proposed maximum aggregate value of transaction: (5) Total fee paid: o Fee paid previously with preliminary materials. o Check box if any part of the fee is offset as provided by Exchange Act Rule 0-11(a)(2) and identify the filing for which the offsetting fee was paid previously. Identify the p
Slide 3: The Stilwell Group's Presentation to Institutional Shareholder Services
The Stilwell Group’s Presentation to Institutional Shareholder Services RiskMetrics Group March 12, 2008 Opposing Bid From The Doctors Company For SCPIE Holdings Inc.
Slide 4: Overview
Overview I. The $28 Cash Offer Was An Inadequate Offer M&A Edge Note, March 5, 2008 SKP’s stock price was depressed when TDC deal accepted Net present value calculation Price/tangible book value comparison Normalized earnings Earnings accretion available II. The “Auction And Bidding” Process Was Fla
Slide 5: I. Inadequate Offer: M&A Edge Note, March 5, 2008
I. Inadequate Offer M&A Edge Note, March 5, 2008 “Unlike the ‘bumpitrage’ theme that prevailed in 2007, this year institutional shareholders are reaching out to the M&A Edge team to discuss the allegedly opportunistic low-ball bids made at a time when target shares are trading at a temporary market
Slide 6: I. Inadequate Offer
I. Inadequate Offer Article mentions proposed SKP-TDC deal as a “Selected Alleged ‘Opportunistic’ Offer” Proposed deal assigns no value to franchise and leaves shareholders no upside 4
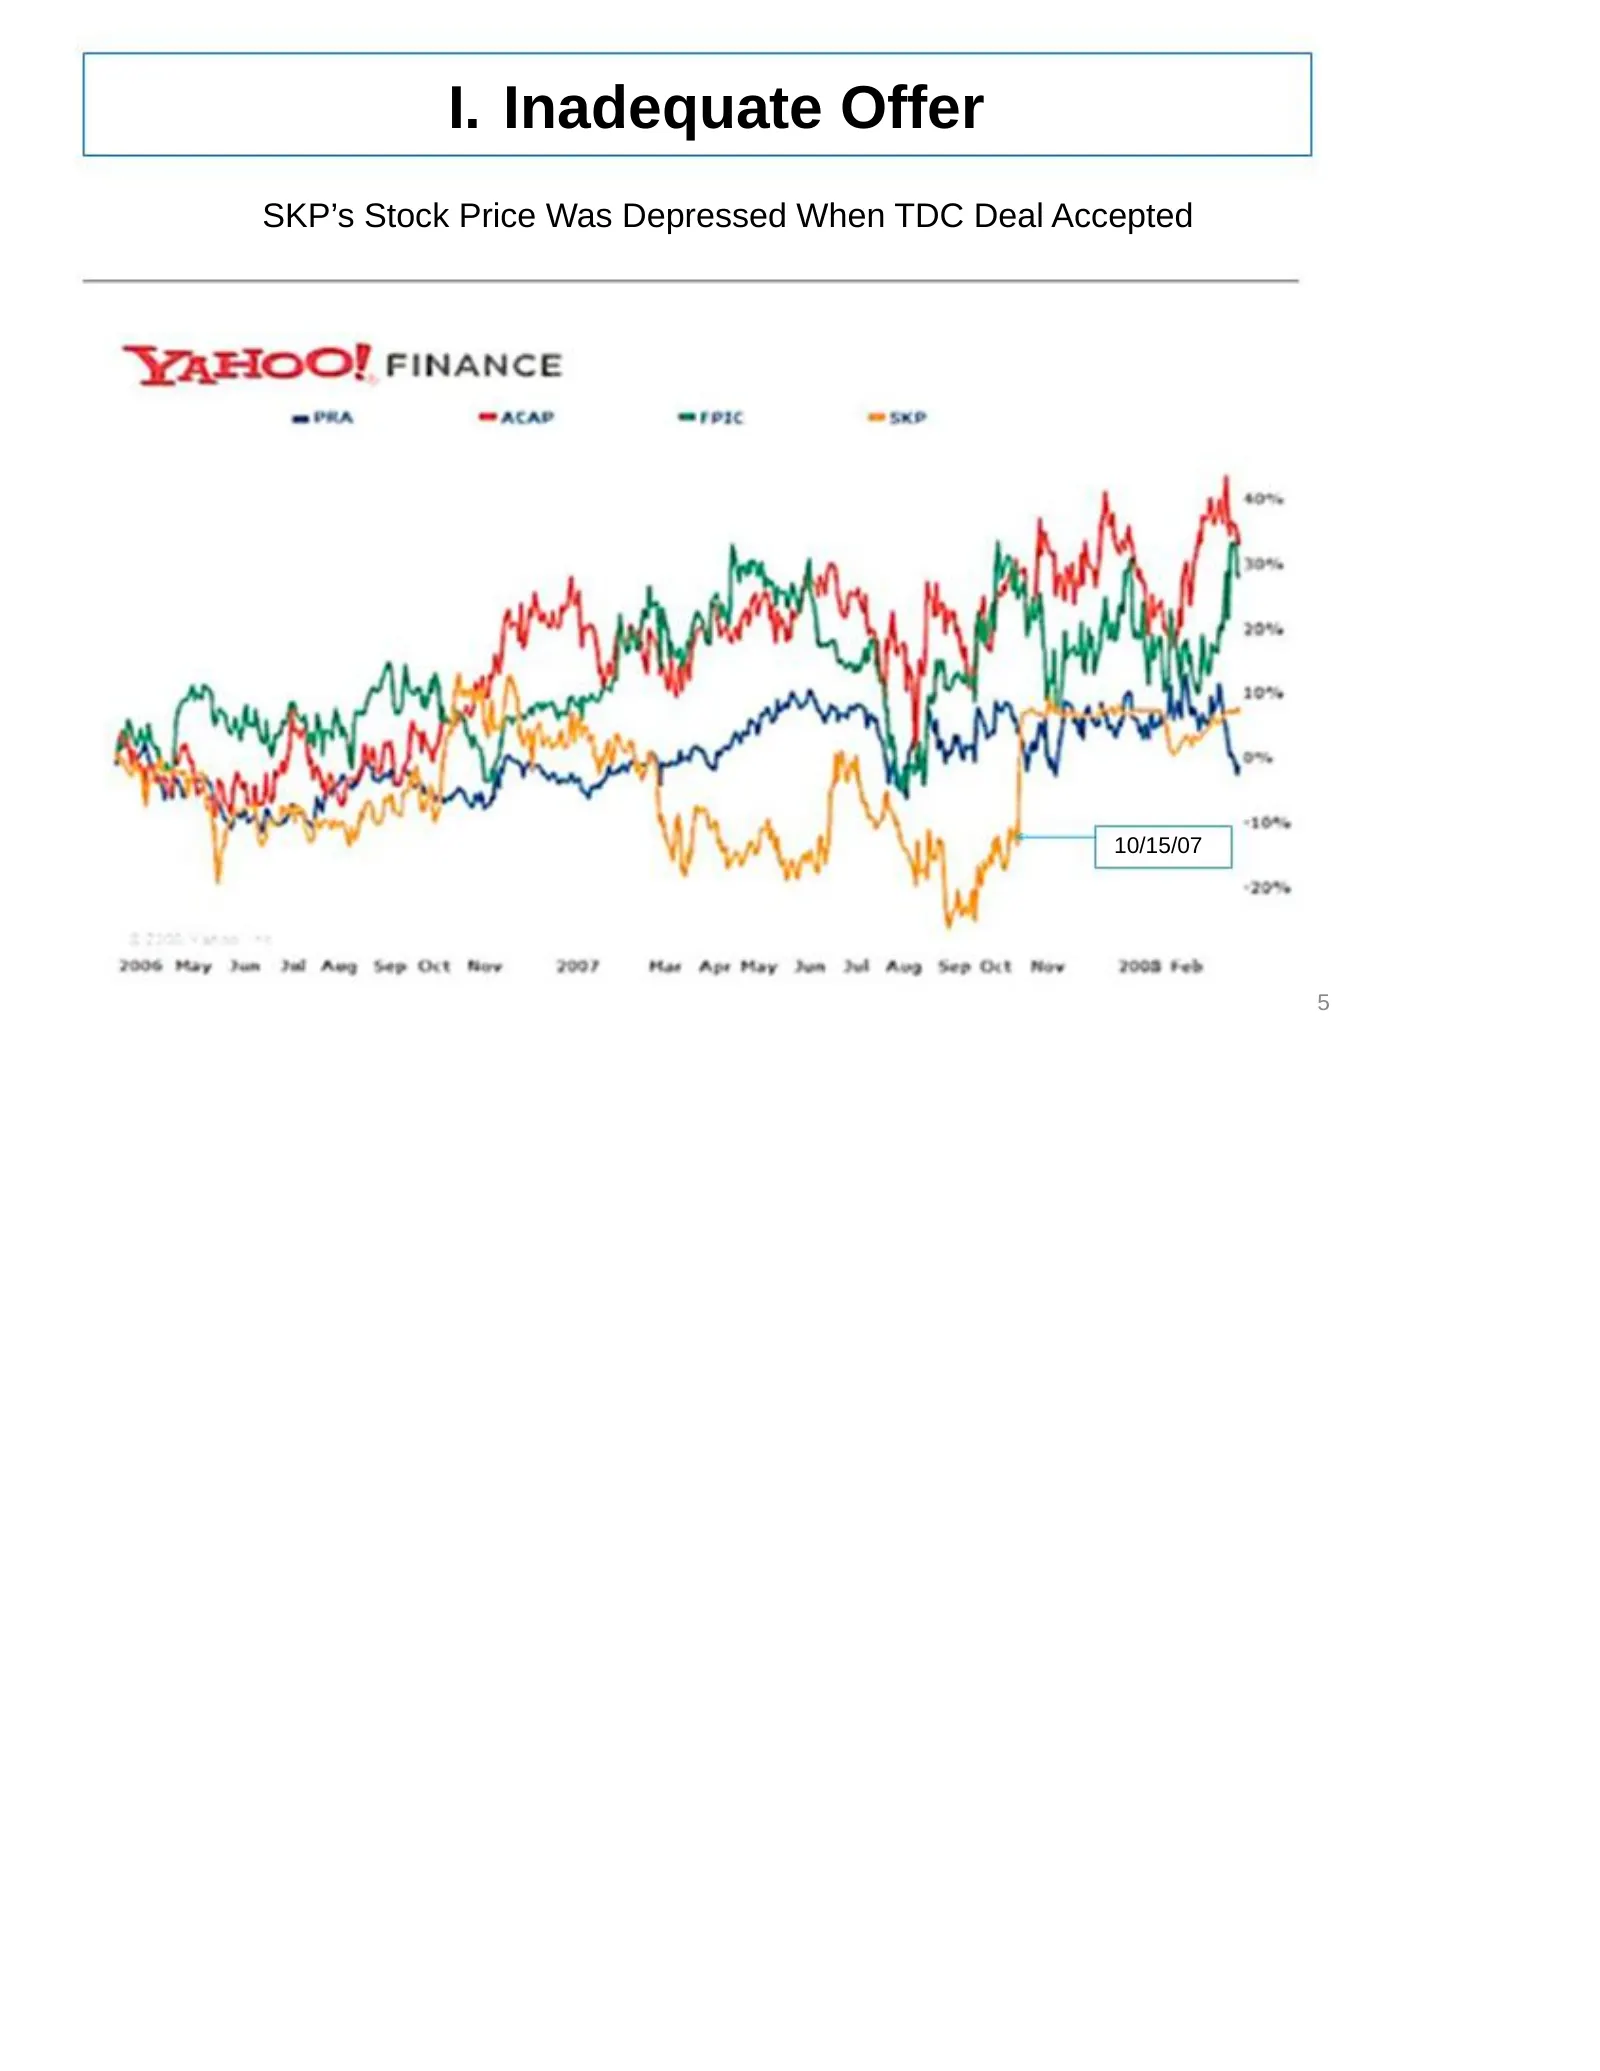
Slide 7: SKP's Stock Price Was Depressed When TDC Deal Accepted
I. Inadequate Offer SKP’s Stock Price Was Depressed When TDC Deal Accepted 10/15/07 5
Slide 8: Net present value calculation
I. Inadequate Offer Net present value calculation The net present value of company assets as of December 31, 2007 was $28.17 per share TDC bid therefore assigns $(0.17) per share value to SKP franchise as of December 31, 2007. We believe this is too low. “Gem” of a franchise undervalued: despite thr
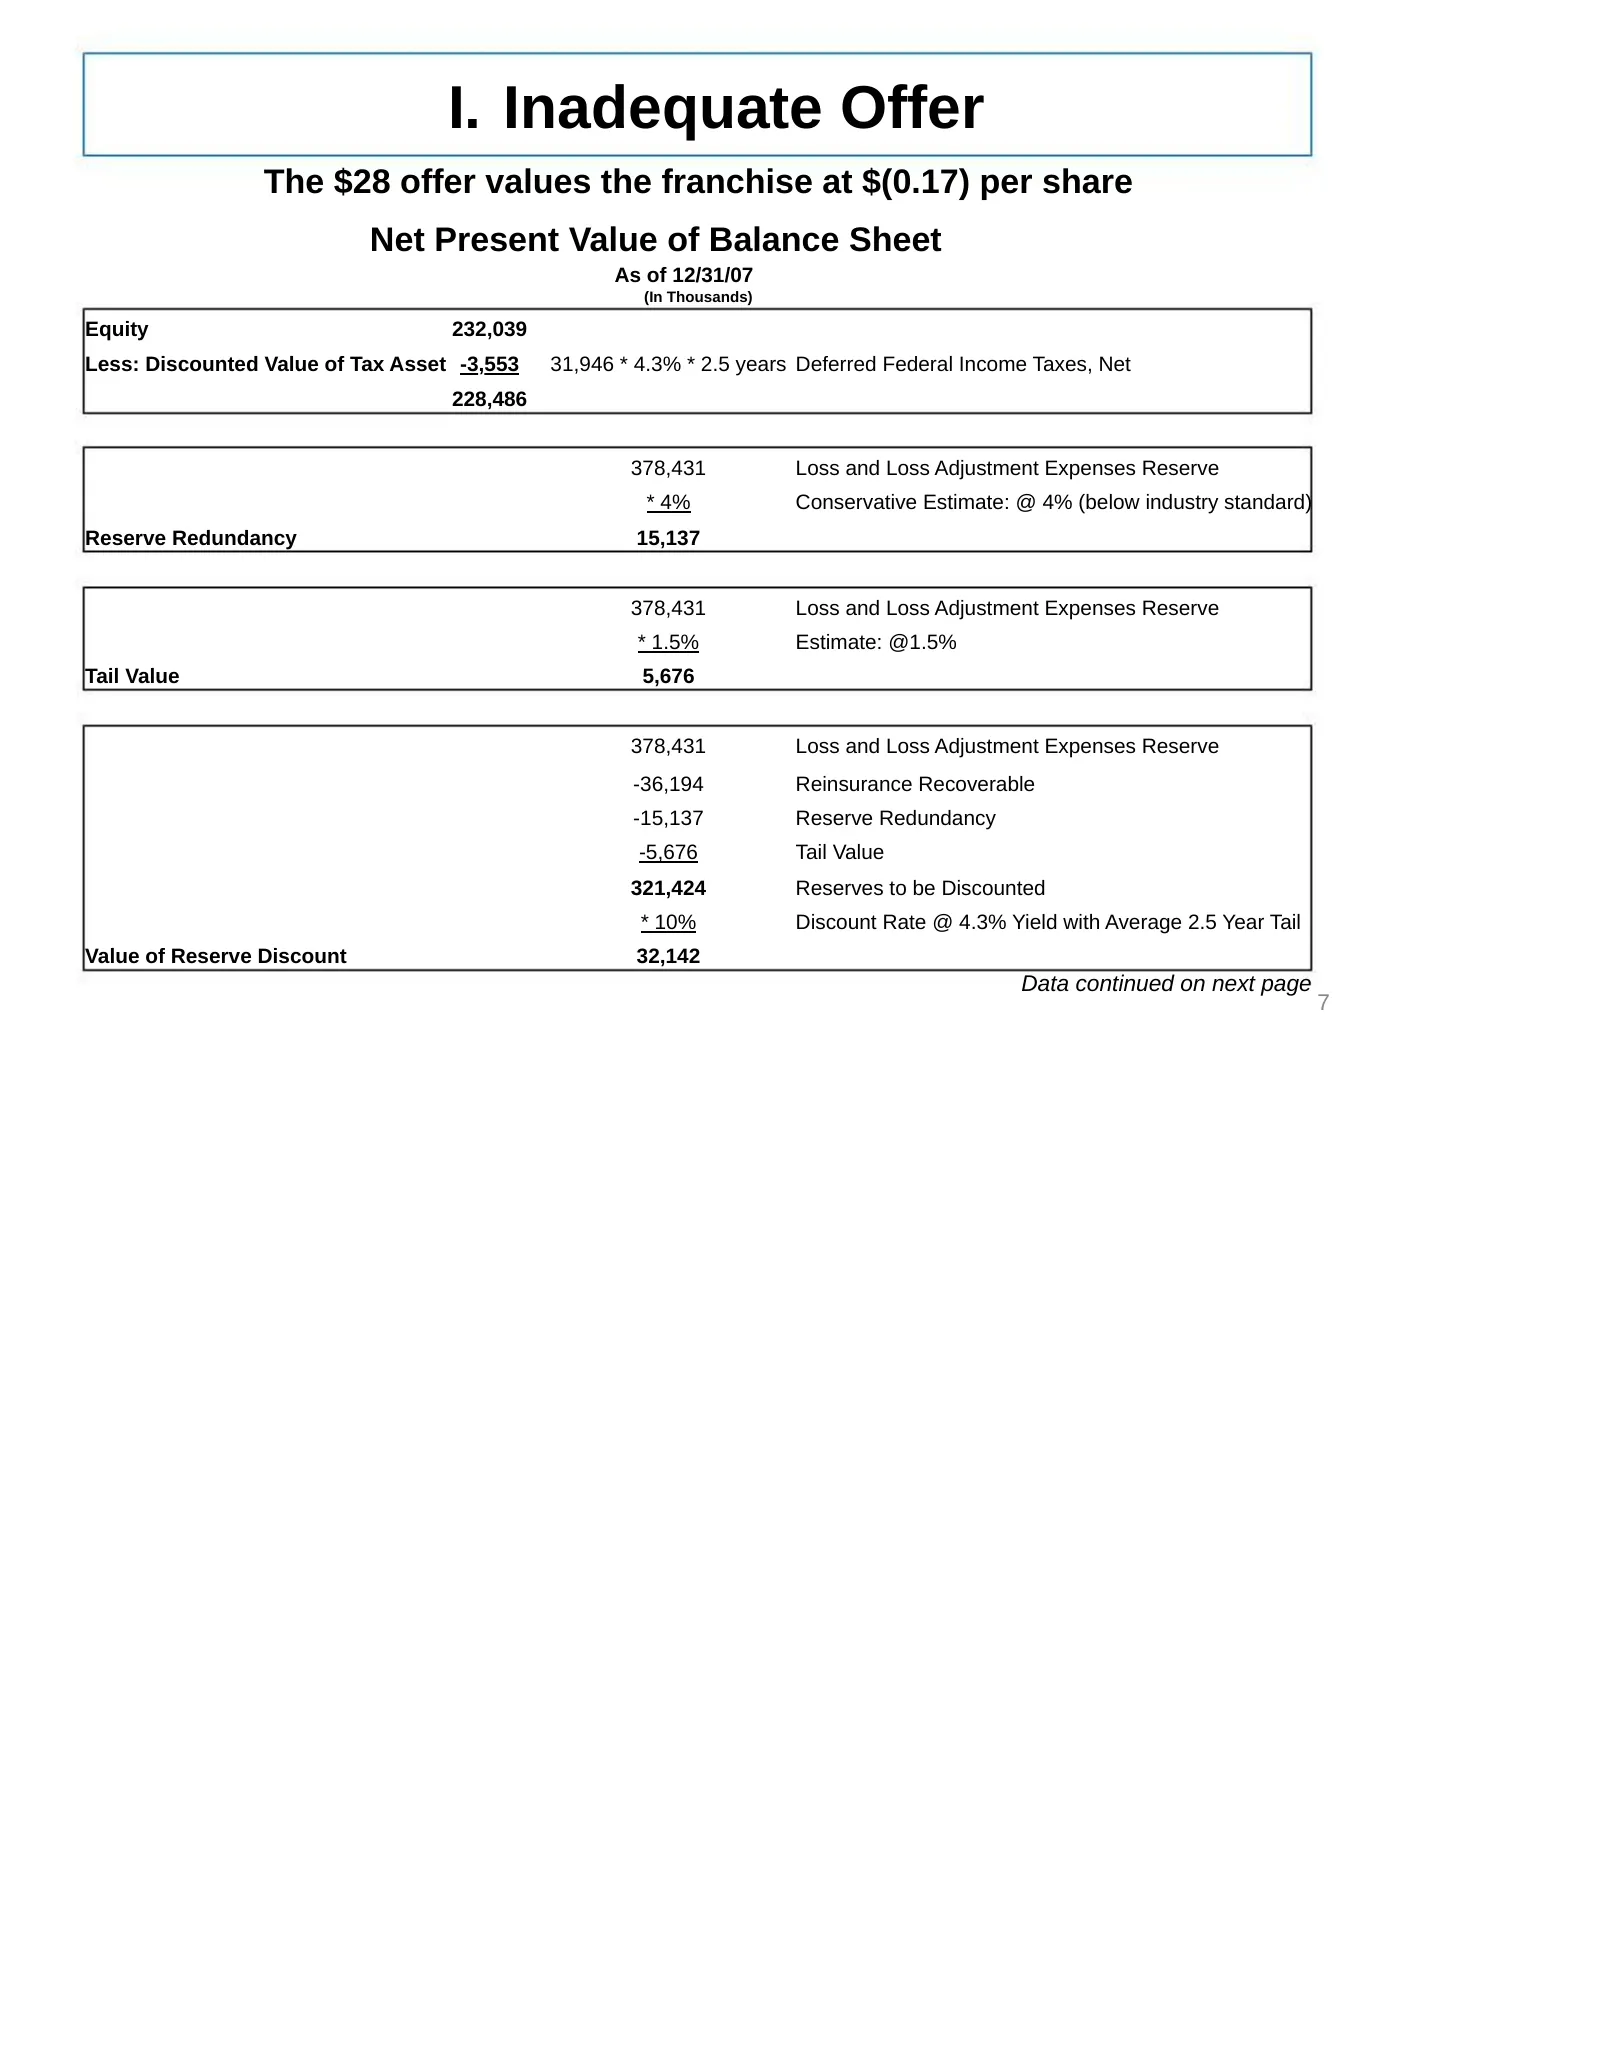
Slide 9: The $28 offer values the franchise at $(0.17) per share
I. Inadequate Offer The $28 offer values the franchise at $(0.17) per share Net Present Value of Balance Sheet As of 12/31/07 (In Thousands) Equity 232,039 Less: Discounted Value of Tax Asset -3,553 31,946 * 4.3% * 2.5 years Deferred Federal Income Taxes, Net 228,486 378,431 Loss and Loss Adjustment
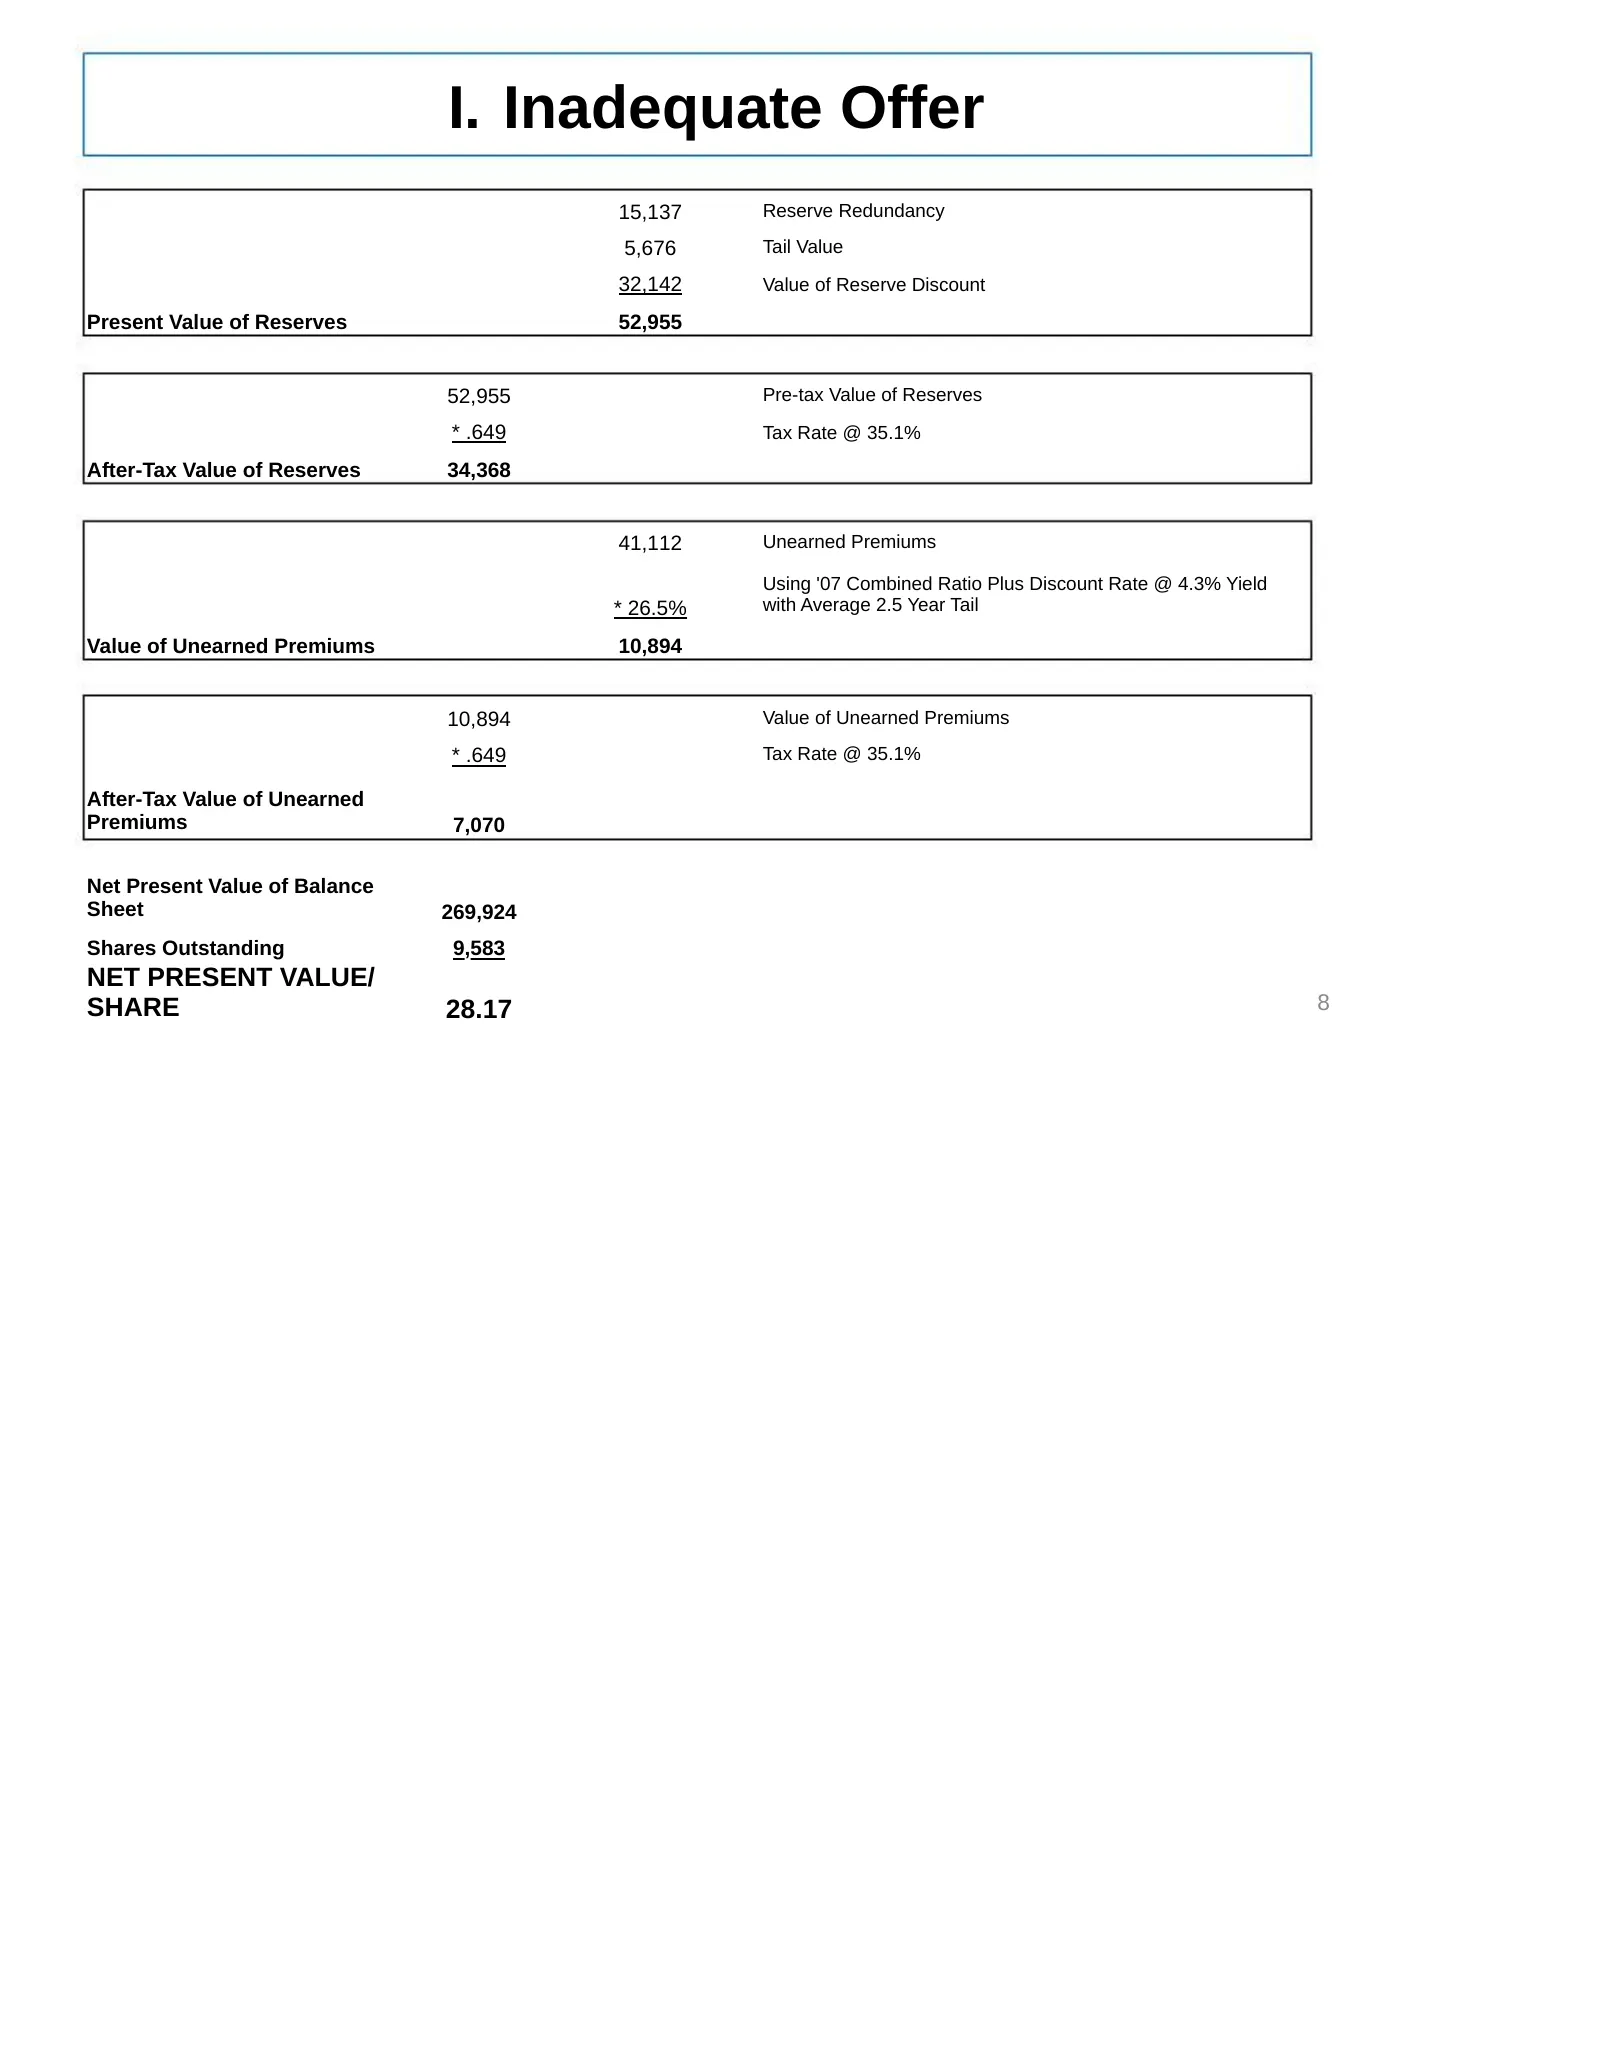
Slide 10: Net present value per share calculation
I. Inadequate Offer 15,137 Reserve Redundancy 5,676 Tail Value 32,142 Value of Reserve Discount Present Value of Reserves 52,955 52,955 Pre-tax Value of Reserves * .649 Tax Rate @ 35.1% After-Tax Value of Reserves 34,368 41,112 Unearned Premiums Using '07 Combined Ratio Plus Discount Rate @ 4.3% Yie
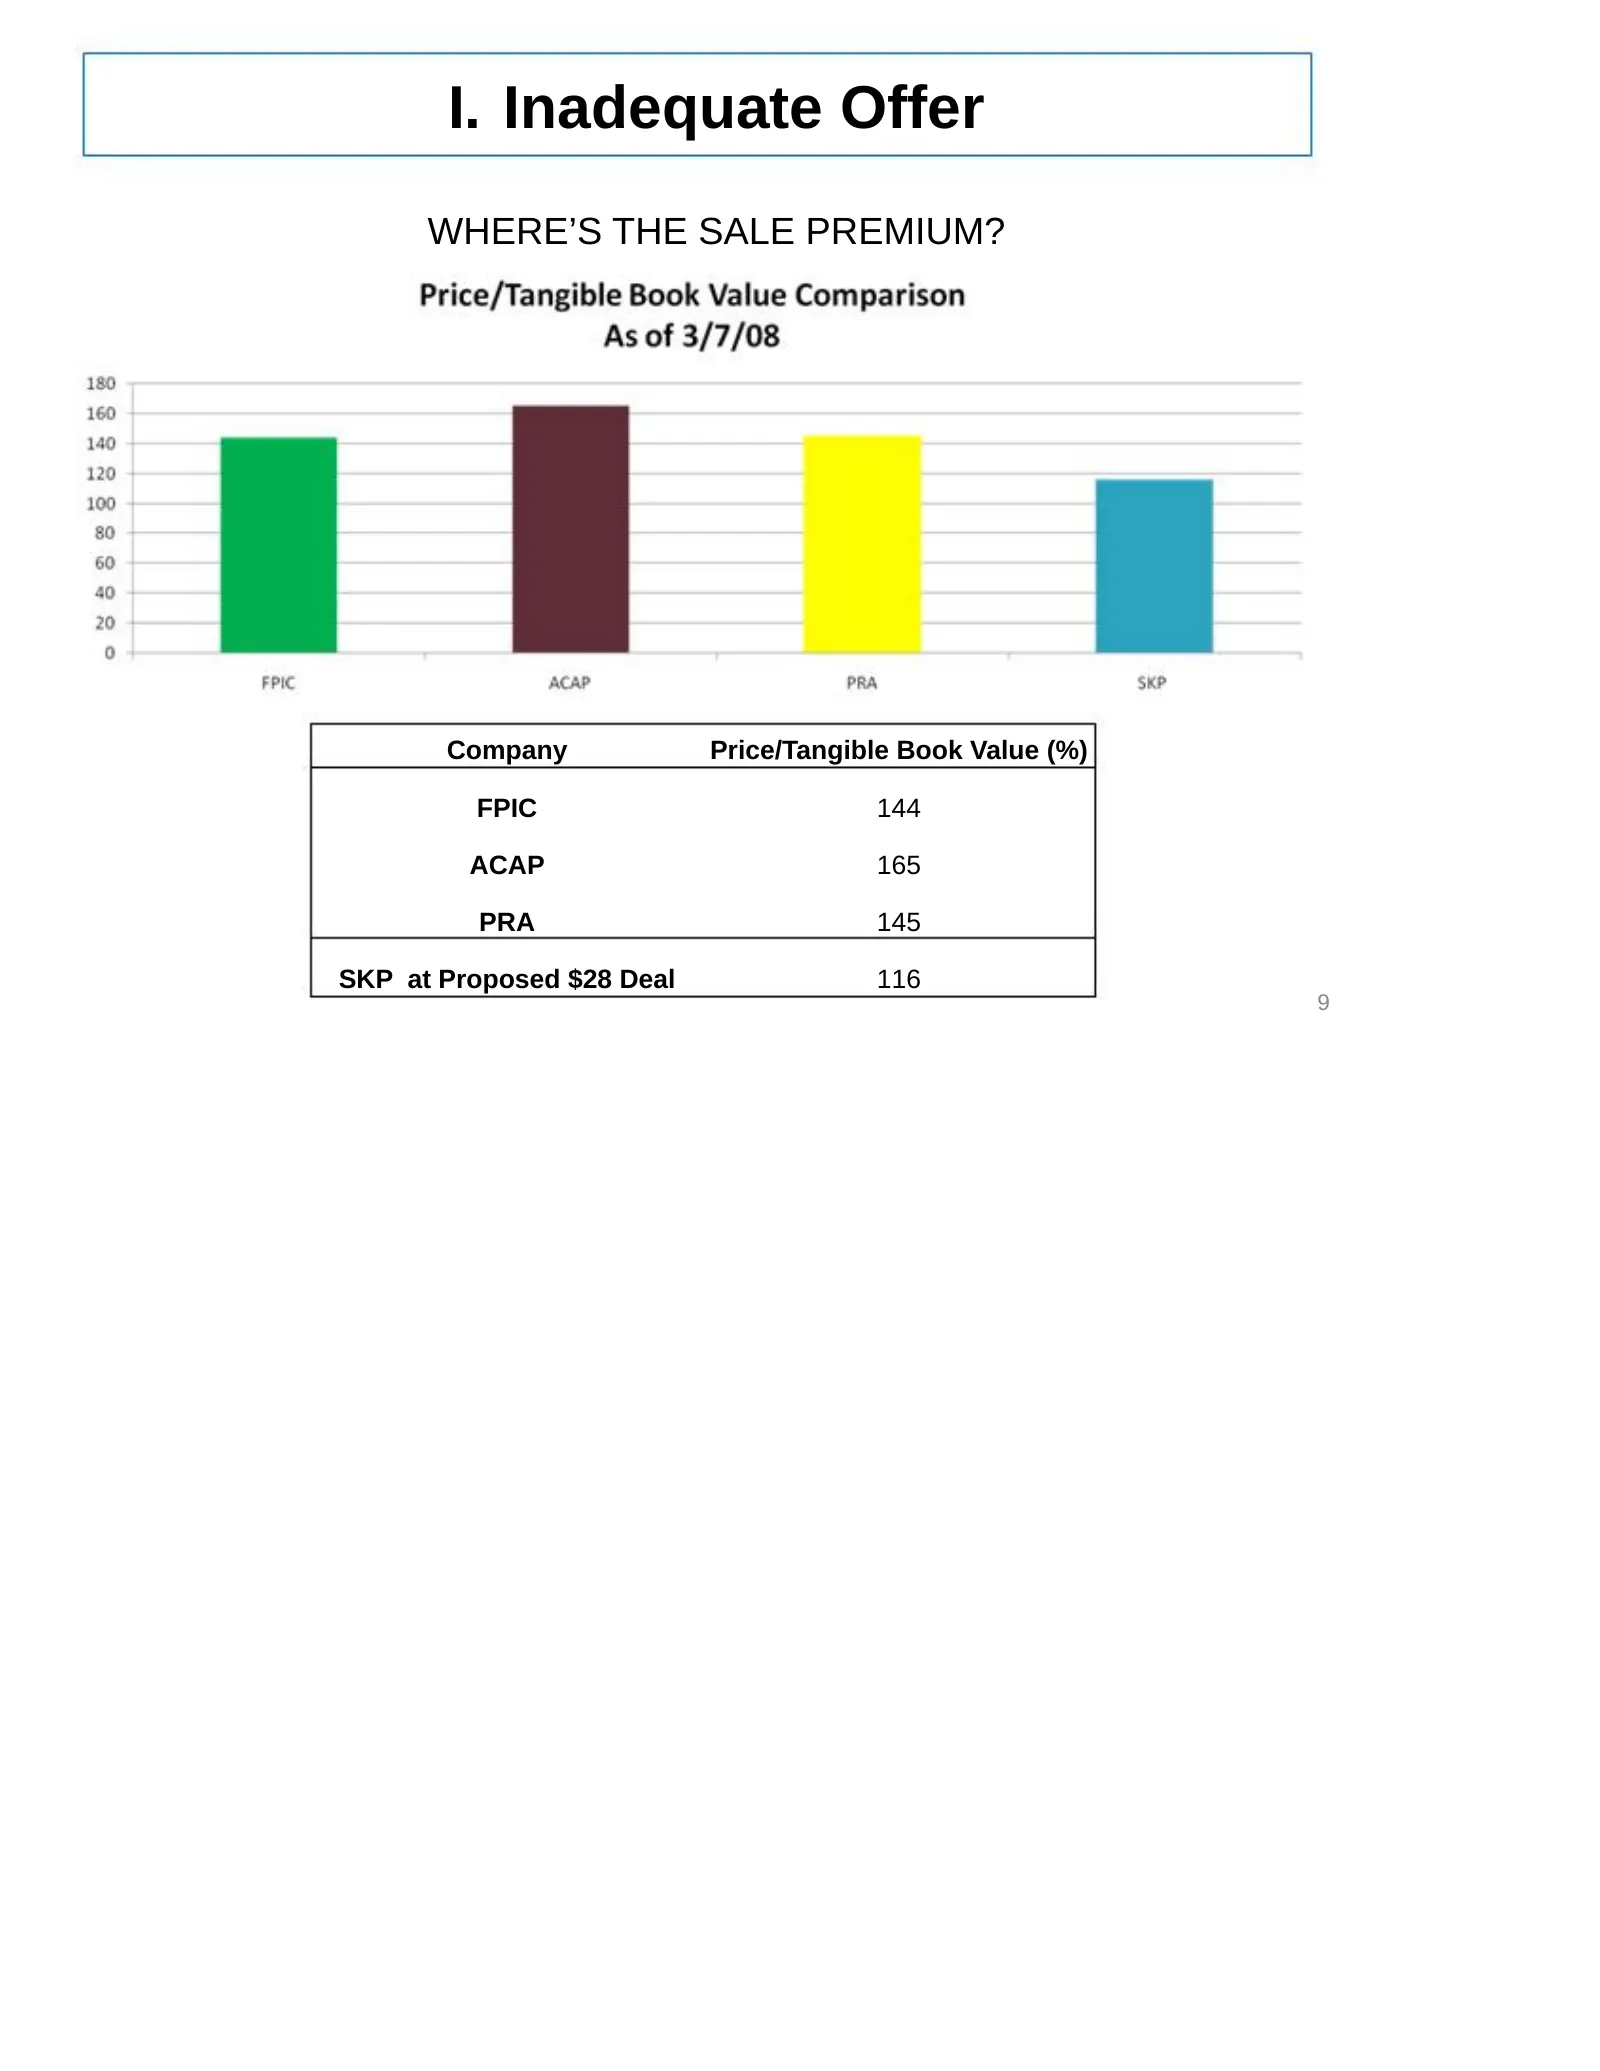
Slide 11: Where's the Sale Premium? Price/Tangible Book Value
I. Inadequate Offer WHERE’S THE SALE PREMIUM? Company Price/Tangible Book Value (%) FPIC 144 ACAP 165 PRA 145 SKP at Proposed $28 Deal 116 9
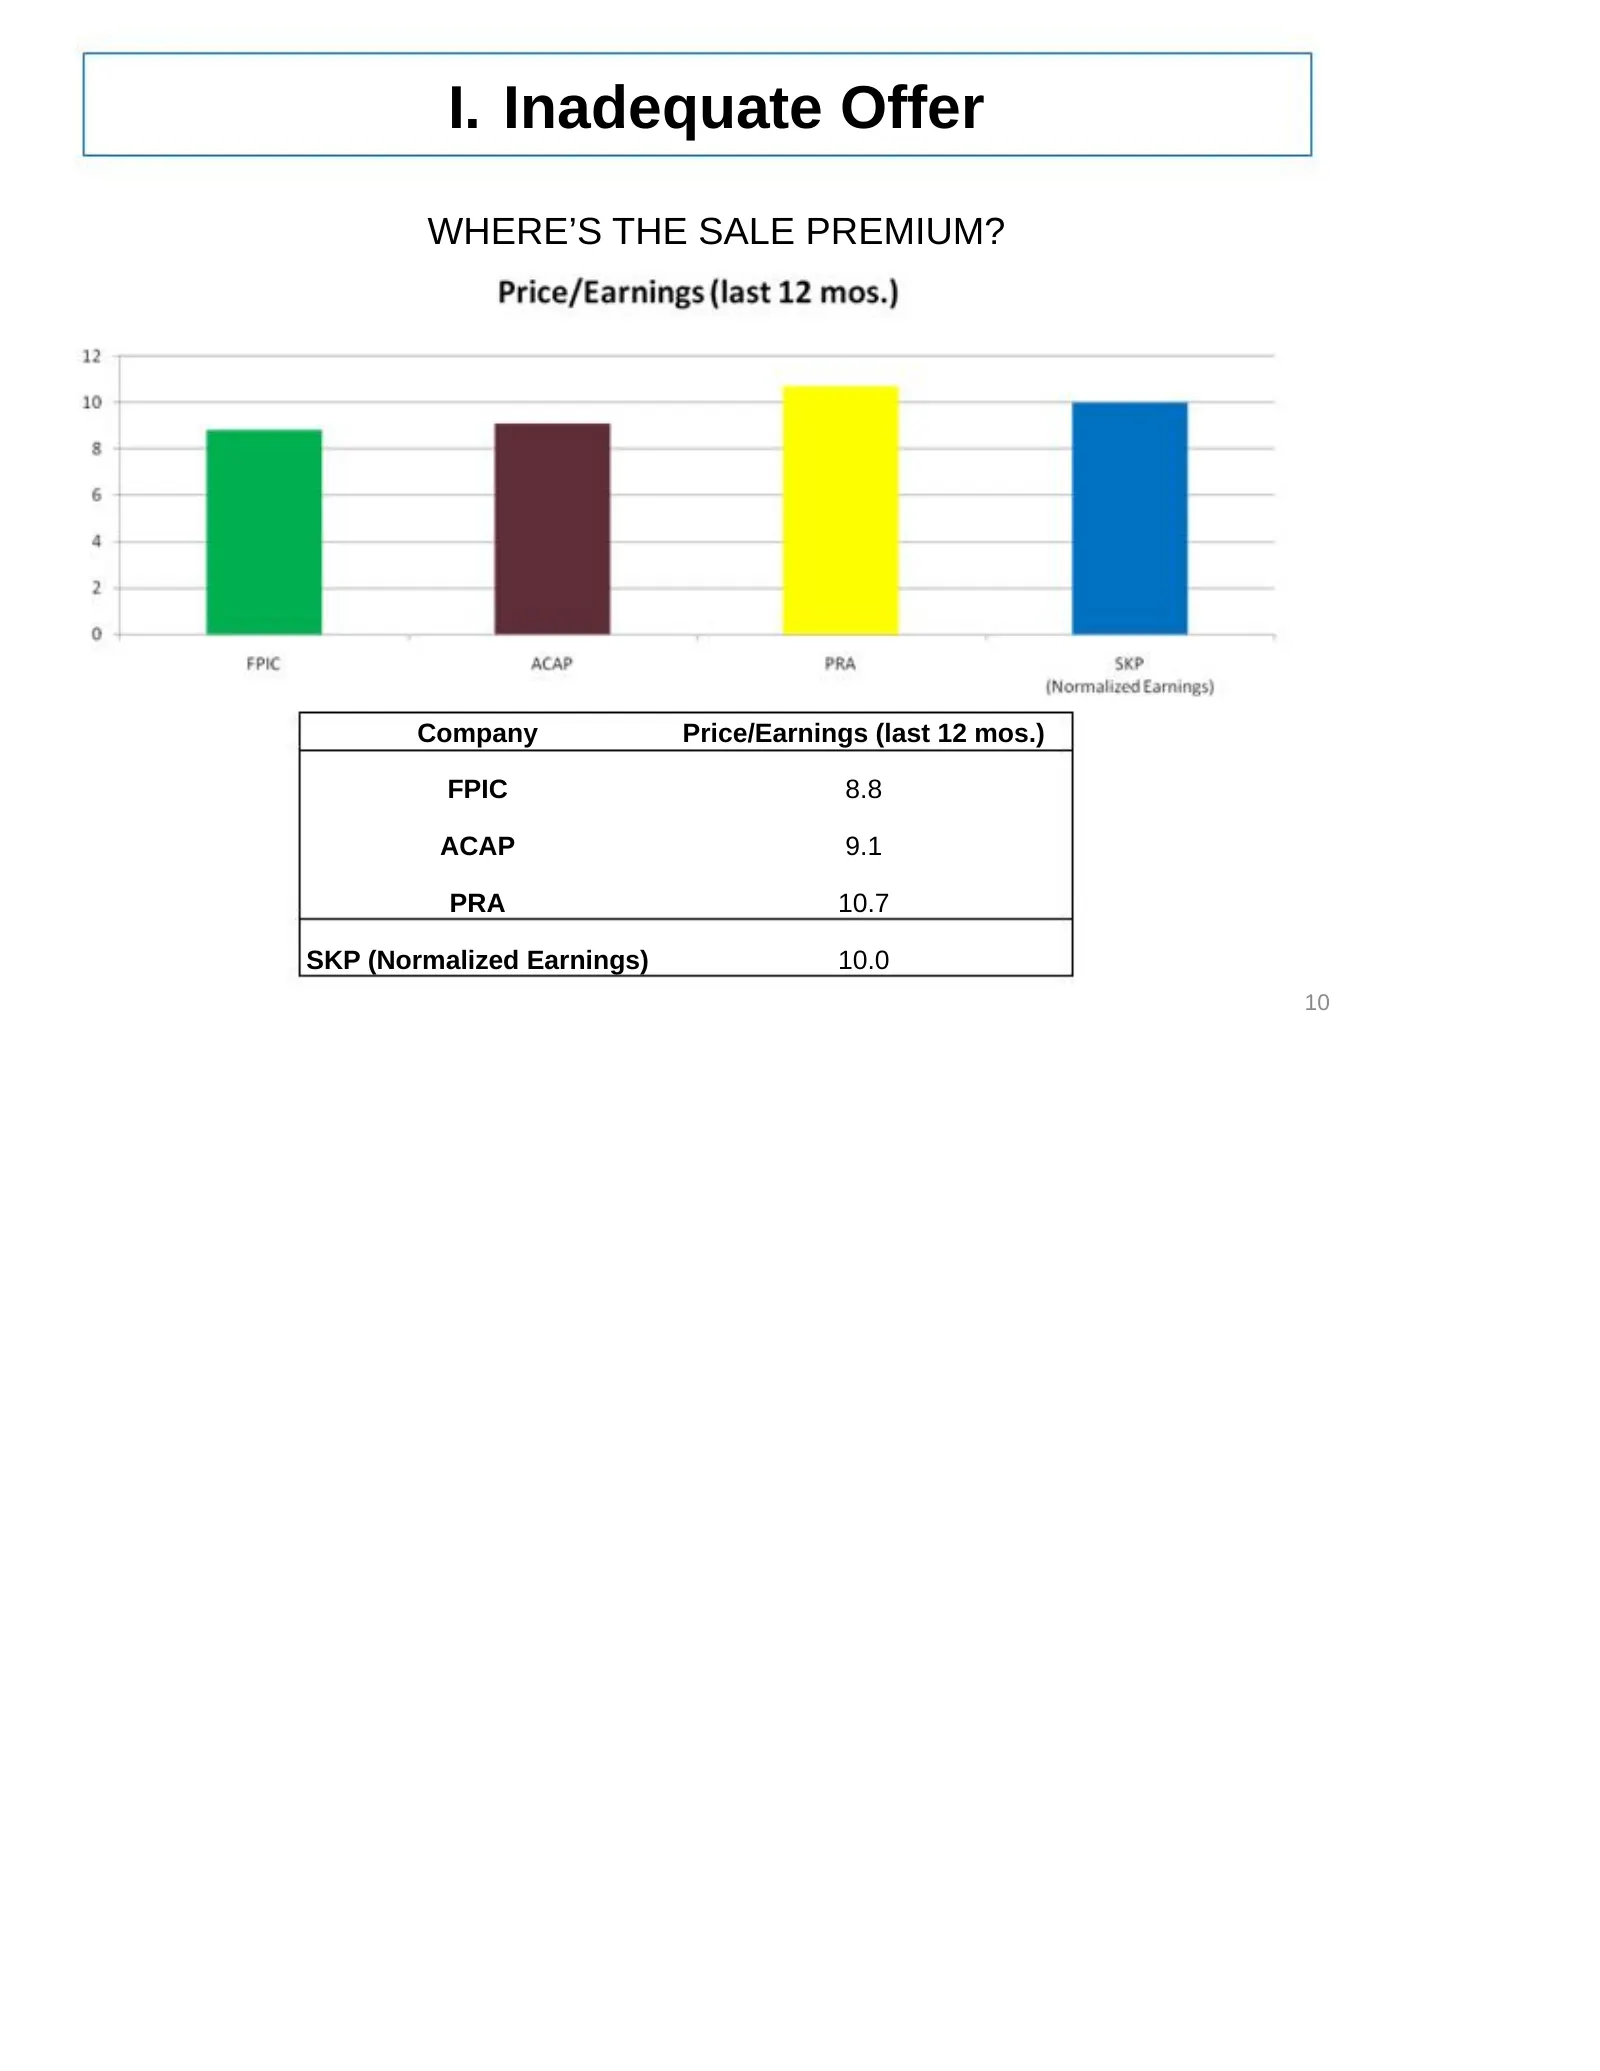
Slide 12: Where's the Sale Premium? Price/Earnings
I. Inadequate Offer WHERE’S THE SALE PREMIUM? Company Price/Earnings (last 12 mos.) FPIC 8.8 ACAP 9.1 PRA 10.7 SKP (Normalized Earnings) 10.0 10
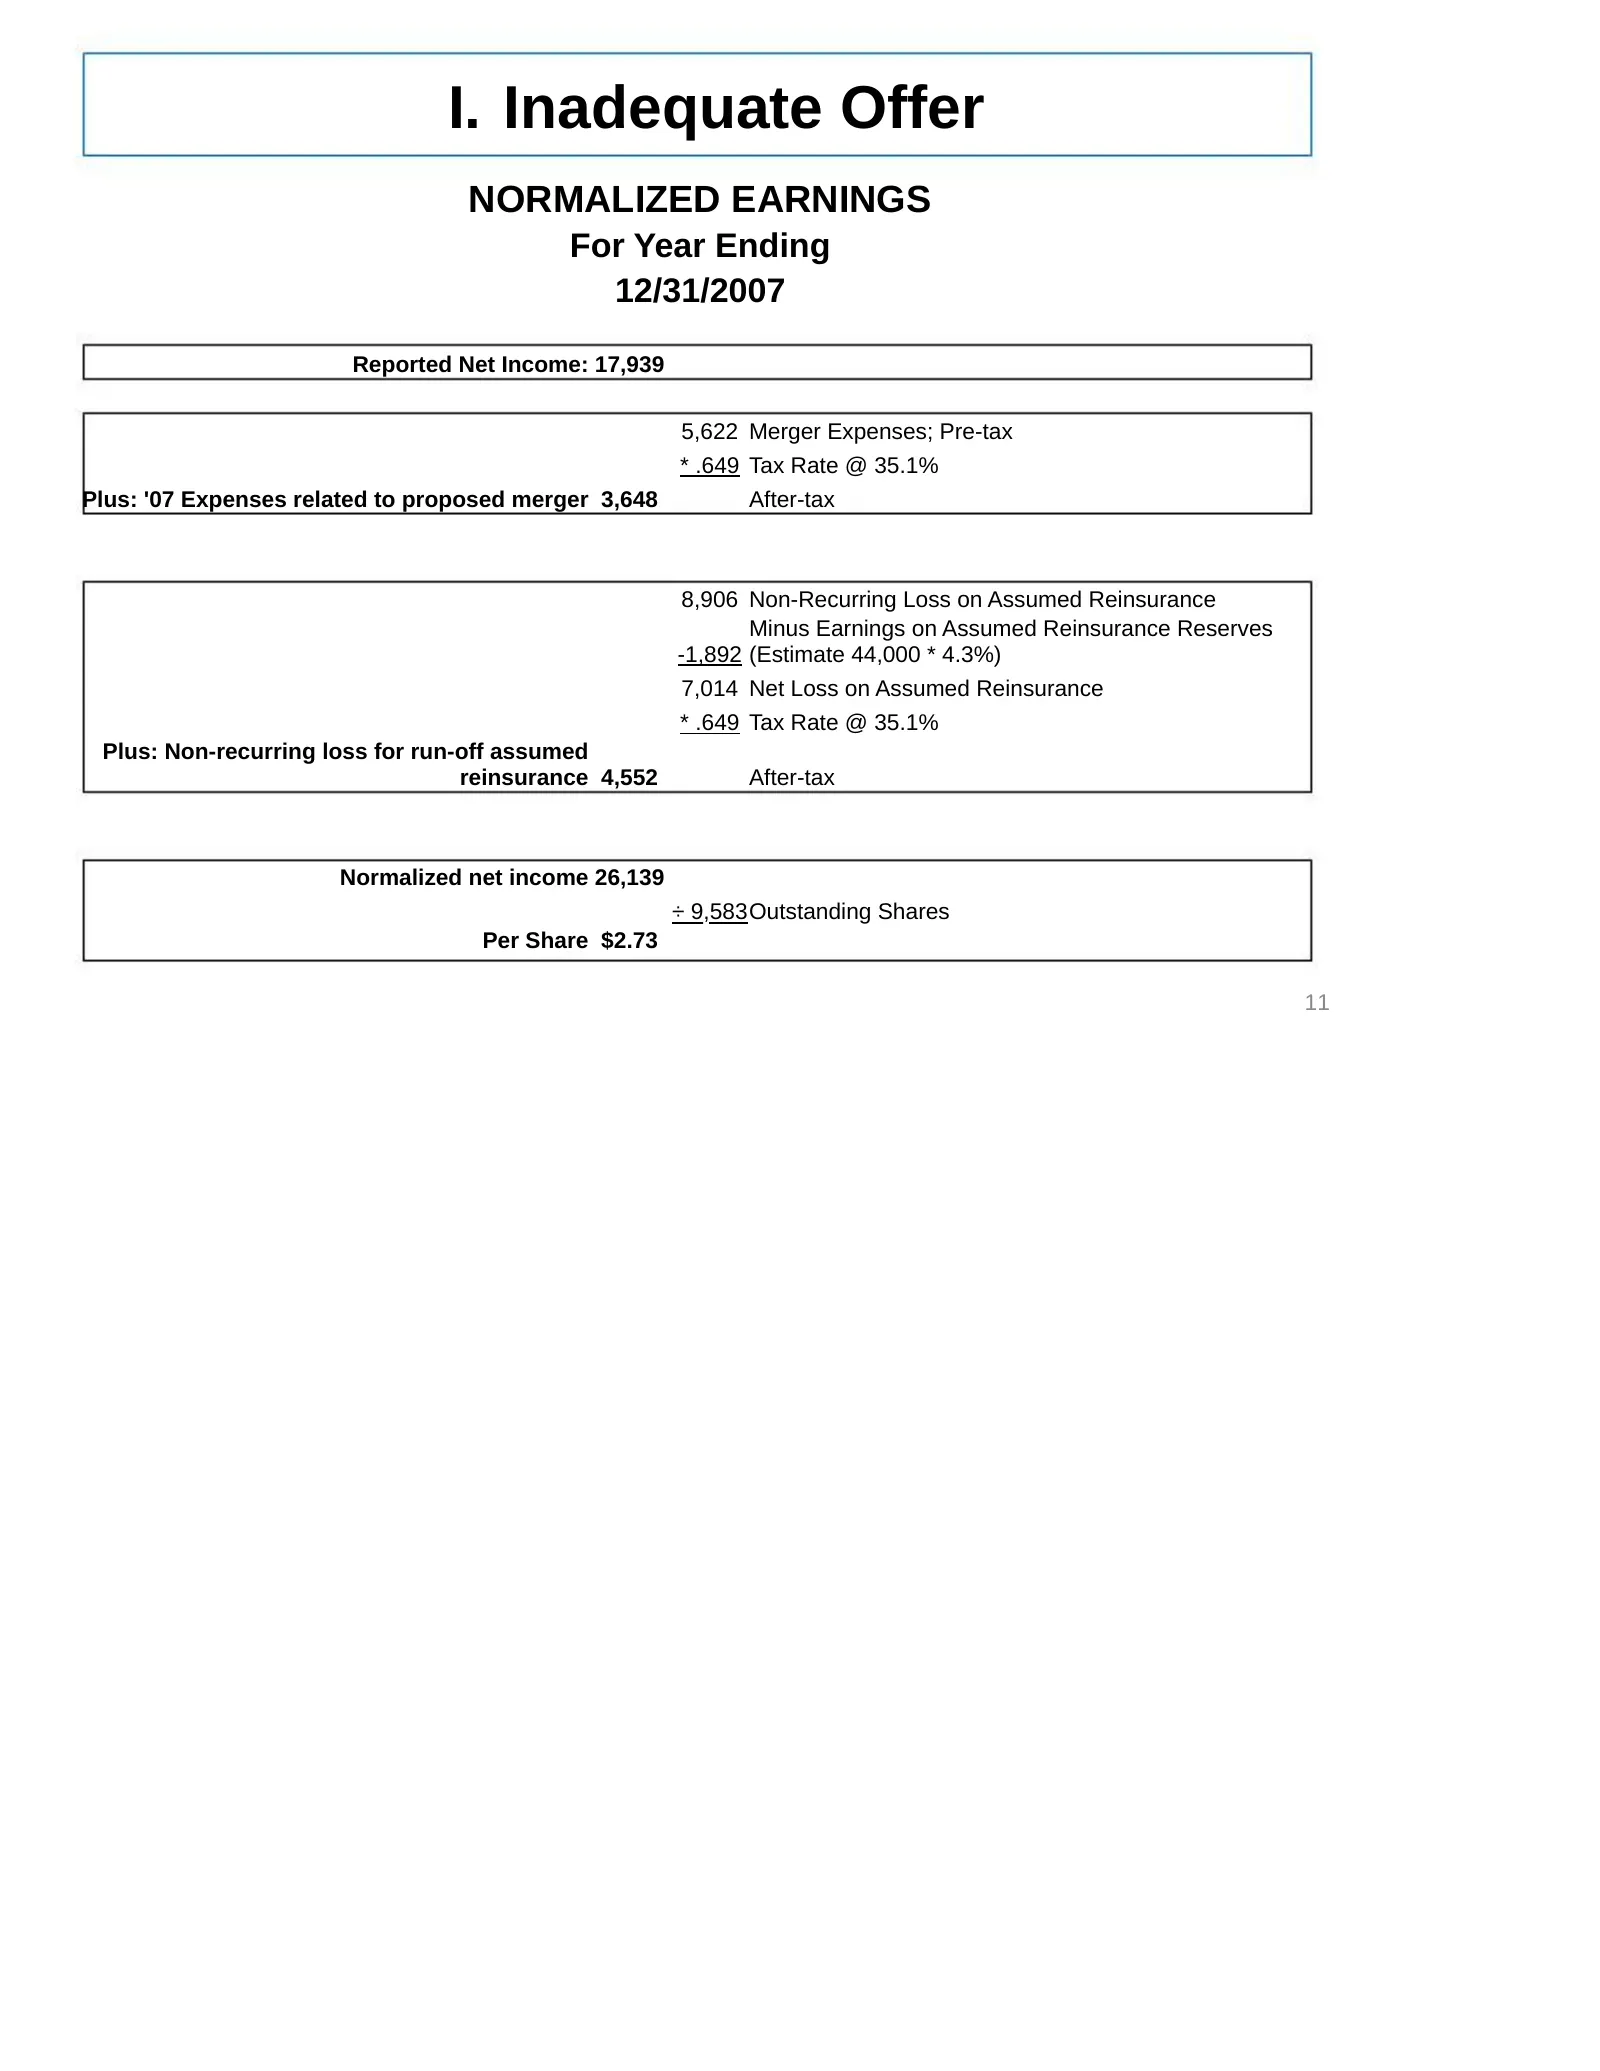
Slide 13: Normalized Earnings
I. Inadequate Offer NORMALIZED EARNINGS For Year Ending 12/31/2007 Reported Net Income: 17,939 5,622 Merger Expenses; Pre-tax * .649 Tax Rate @ 35.1% Plus: '07 Expenses related to proposed merger 3,648 After-tax 8,906 Non-Recurring Loss on Assumed Reinsurance Minus Earnings on Assumed Reinsurance Re
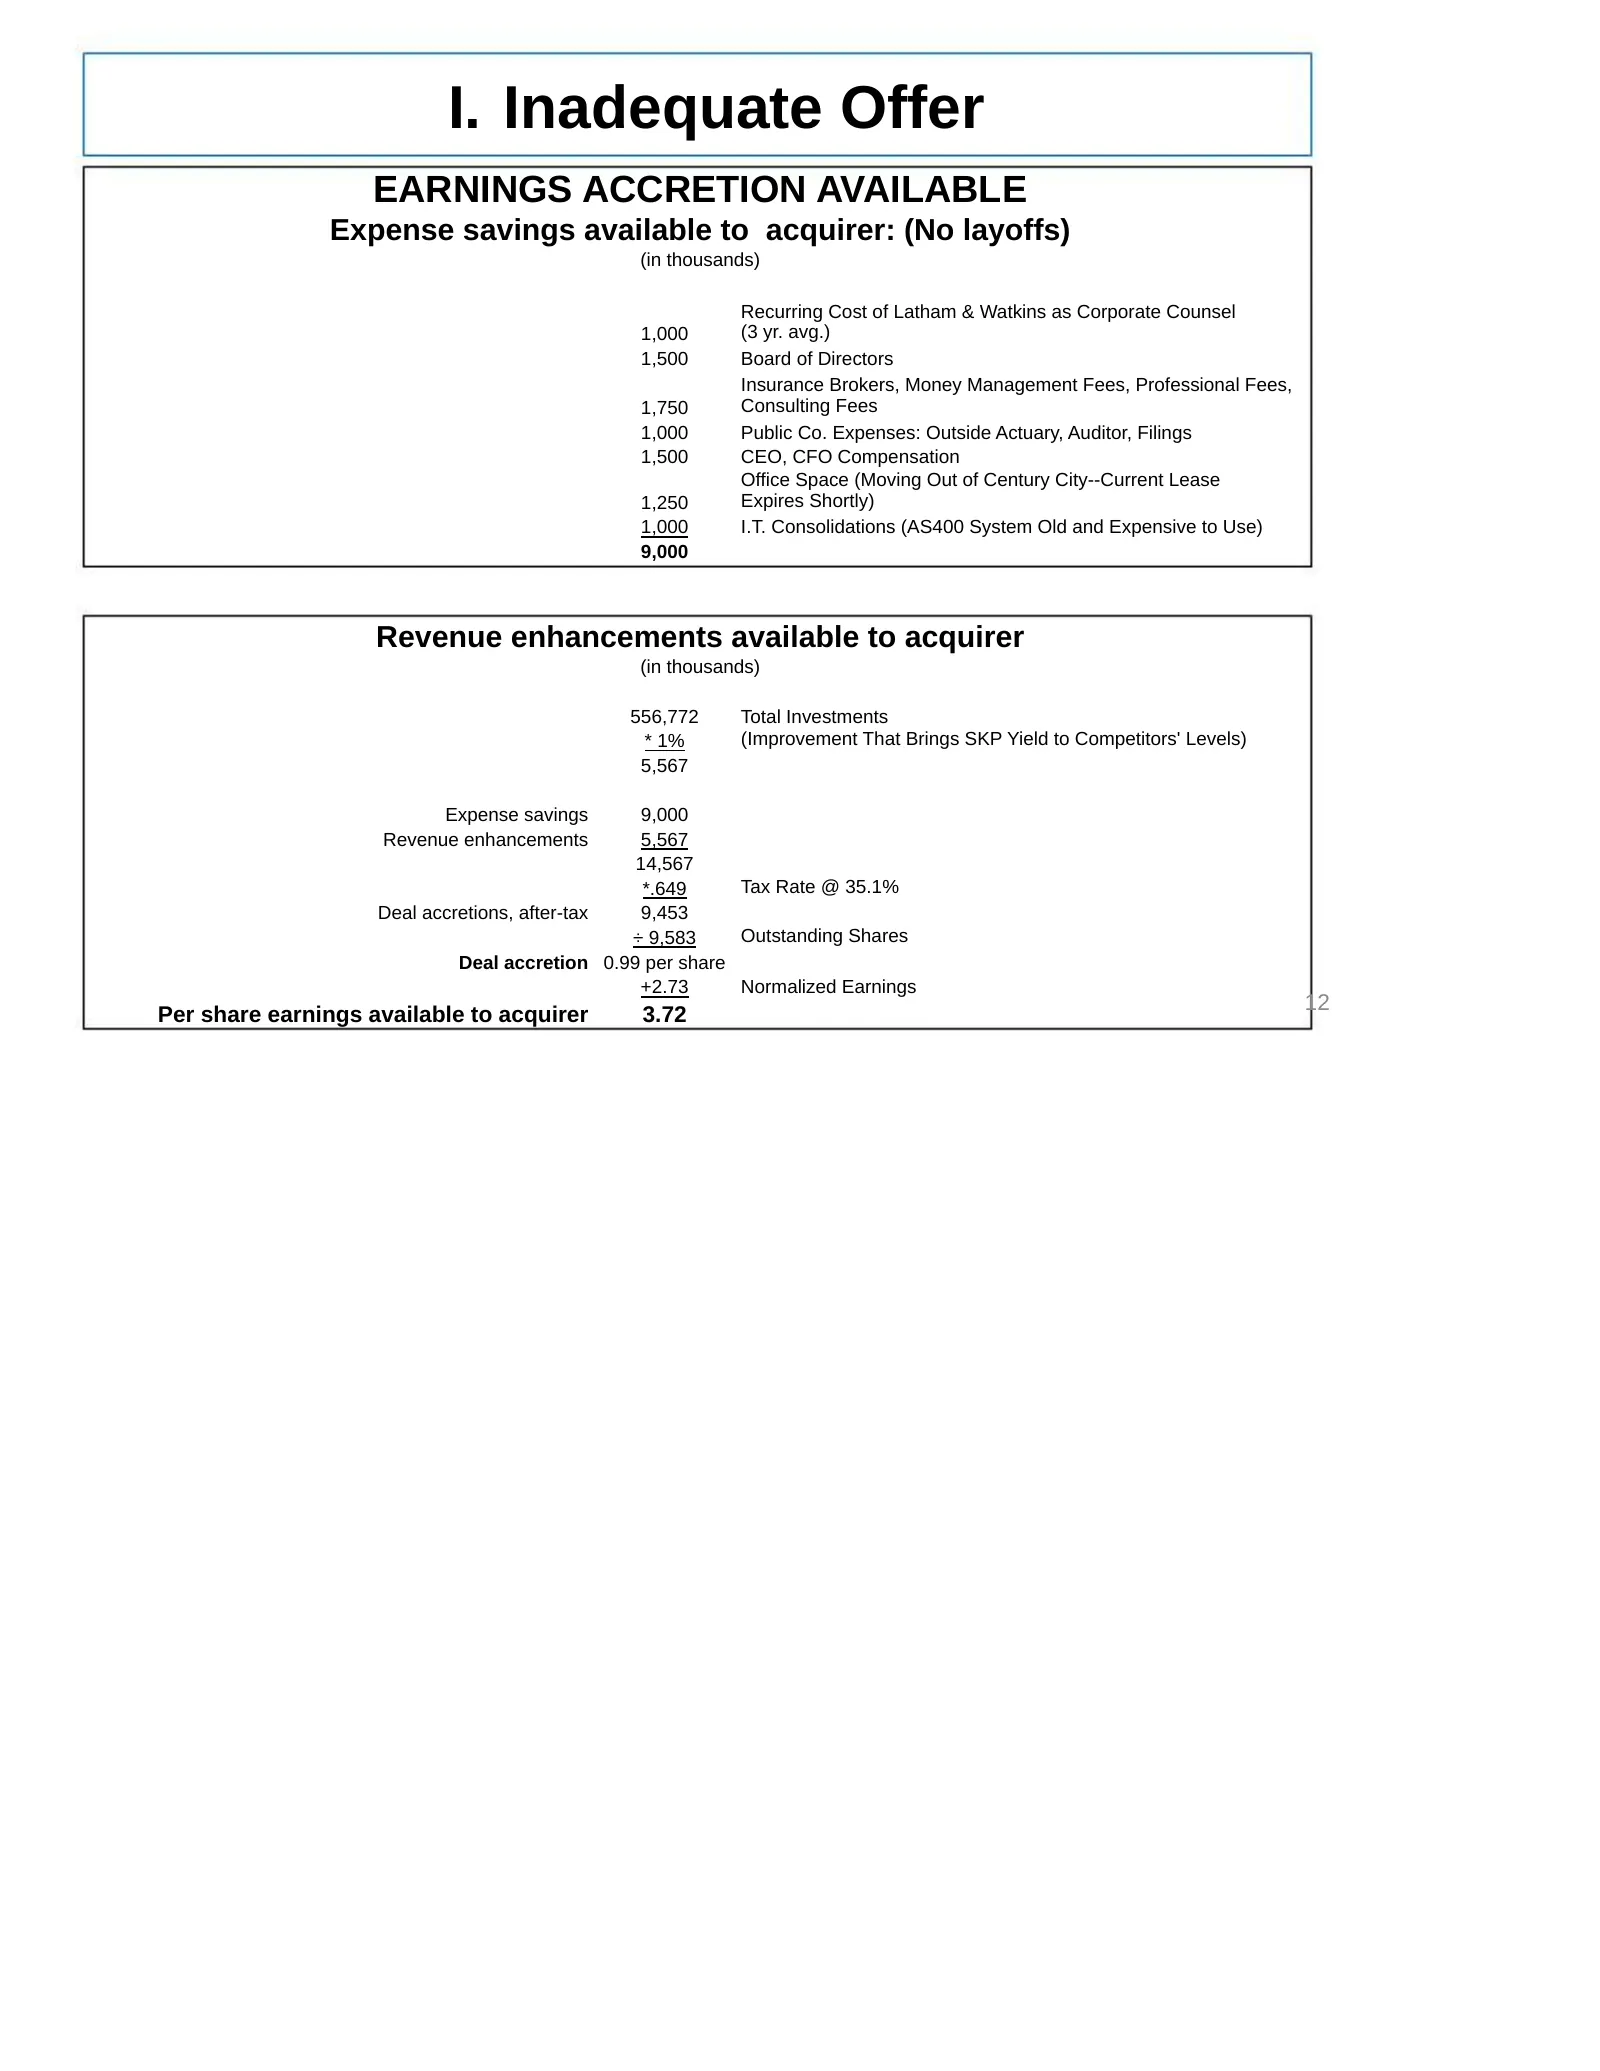
Slide 14: Earnings Accretion Available
I. Inadequate Offer EARNINGS ACCRETION AVAILABLE Expense savings available to acquirer: (No layoffs) (in thousands) Recurring Cost of Latham & Watkins as Corporate Counsel 1,000 (3 yr. avg.) 1,500 Board of Directors Insurance Brokers, Money Management Fees, Professional Fees, 1,750 Consulting Fees 1
Slide 15: Management Bias Towards a Cash Deal Spoiled the Process
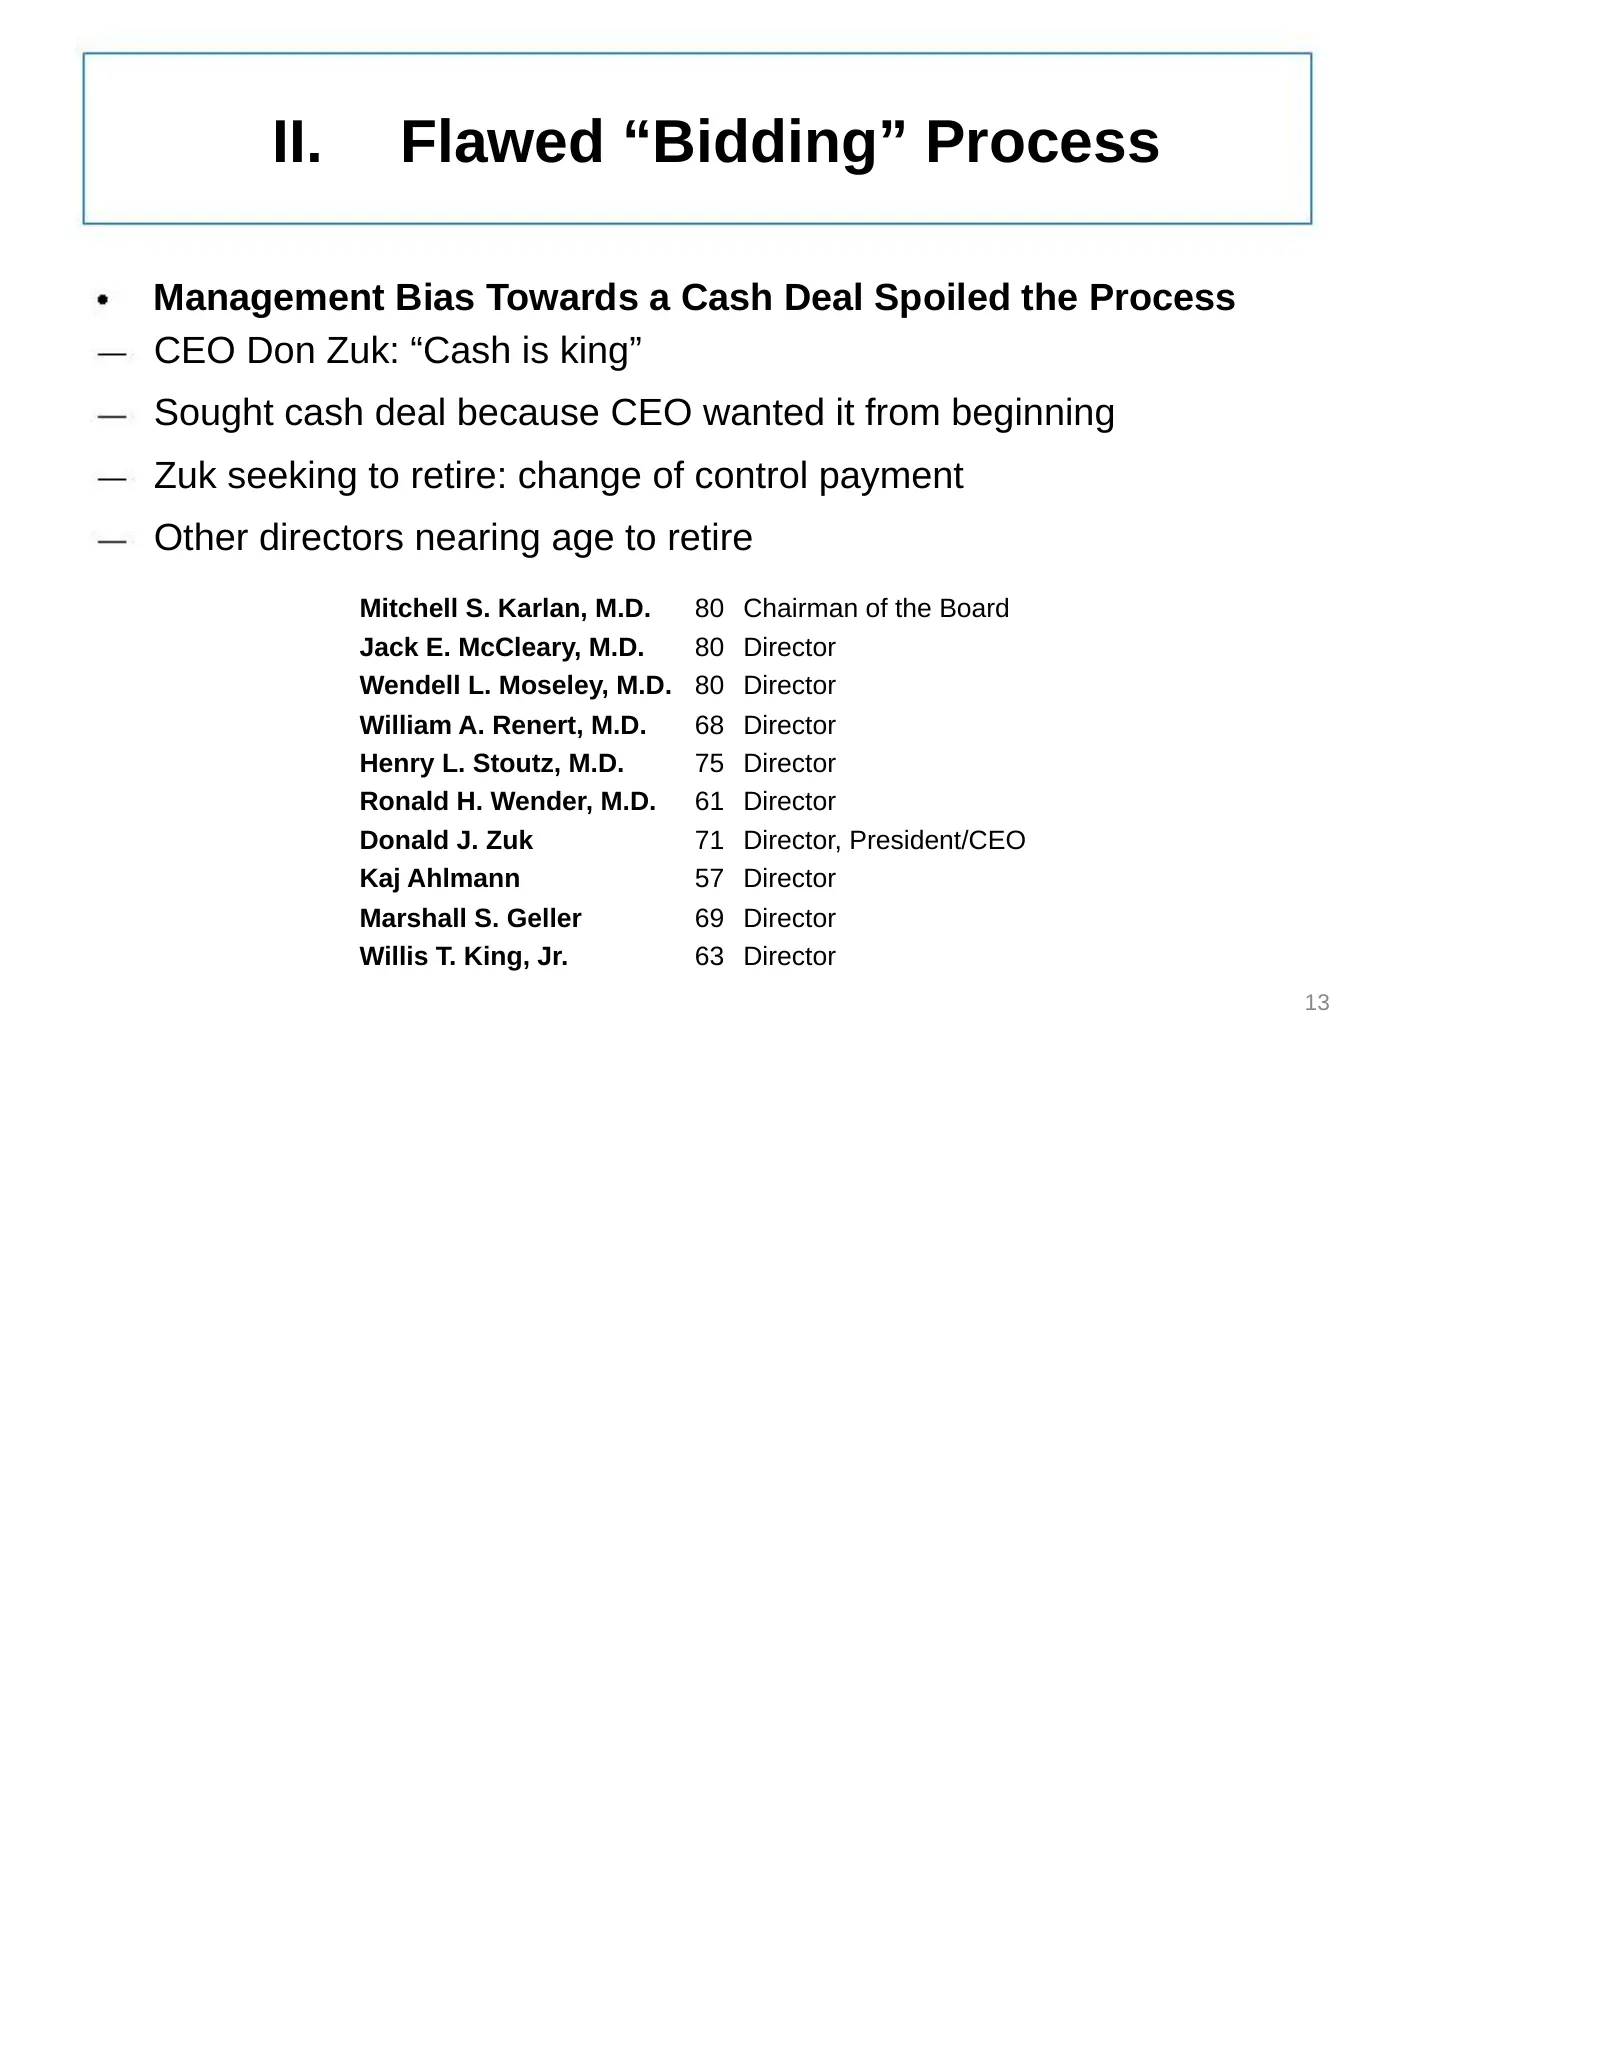
II. Flawed “Bidding” Process Management Bias Towards a Cash Deal Spoiled the Process CEO Don Zuk: “Cash is king” Sought cash deal because CEO wanted it from beginning Zuk seeking to retire: change of control payment Other directors nearing age to retire Mitchell S. Karlan, M.D. 80 Chairman of the Bo
Slide 16: Management, Not Board, Drove the Process
II. Flawed “Bidding” Process Management, Not Board, Drove the Process Board’s strategic planning committee, consisting of independent directors, removed from process early on and banker reported to Management for the duration “Whose bread I eat, his song I sing” 14
Slide 17: Only Three Types of Likely Purchasers
II. Flawed “Bidding” Process Only Three Types of Likely Purchasers Management Favored the Type Least Able to Pay Highest Price Three publicly-traded PL companies: ability to pay premium price using stock PL subsidiary of large AAA insurance company: ability to pay premium price using cash and stock
Slide 18: Ignored Procedures to Enhance Best Possible Bid
II. Flawed “Bidding” Process Ignored Procedures to Enhance Best Possible Bid ACAP was ‘sandbagged’ and not called back after being told by investment bankers it had highest offer Professional liability subsidiary of AAA insurer repeatedly urged to enter the auction process despite telling SKP its co
Slide 19: Other Fatal Flaws
II. Flawed “Bidding” Process Other Fatal Flaws Process ignored Company’s improved performance and decreased risk Management obsessed with expanding despite a balkanized professional liability market in California Ignored potential to increase shareholder value through capital allocation until the ma
Slide 20: Risk of Market Volatility
III. SKP Greatly Exaggerated Risks Risk of Market Volatility SKP did not give the same consideration to a stock offer with upside 18
Slide 21: Risk of Loss of Business
III. SKP Greatly Exaggerated Risks Risk of Loss of Business Two stock bidders agreed to maintain SCPIE Insurance Co., sans Zuk and Tschudy, with the same personnel servicing clients. All bidders’ A.M. Best ratings were higher than SKP’s. Any buyer would have been legally obligated to honor all terms
Slide 22: Deal Protection Terms Prohibit ACAP From Making Best And Highest Offer
III. SKP Greatly Exaggerated Risks Deal Protection Terms Prohibit ACAP From Making Best And Highest Offer Argument that ACAP couldn’t bring floor above $28 false; foolish not to have heard offer 20
Slide 23: SKP Directors' Fiduciary Duties
IV. SKP Directors’ Fiduciary Duties It will be incumbent upon SKP’s board of directors to consider a better offer if the TDC $28 cash offer is voted down by shareholders. Should have considered return of capital as all three other publicly traded companies are doing $60 million return consistent wit
Source: SEC EDGAR · DFAN14A filed Mar 12, 2008